
 Tablet Market | 2026-2036
Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Market Intelligence
The European Union's Digital Markets Act (DMA) is restructuring the competitive landscape by mandating interoperability and alternative app store access on major operating systems. Apple sustains its premium market position through a tightly integrated ecosystem of hardware and its proprietary iOS. Samsung Electronics competes across multiple price points with its diverse Android-based Galaxy Tab series. Microsoft positions its Surface line as a productivity-focused hybrid, blurring the line between tablet and laptop.
A tablet is a portable computing device characterized by a touchscreen interface, typically ranging from 7 to 13 inches, and a mobile operating system. These devices integrate processors, memory, and battery into a single slim chassis, designed for content consumption, light productivity, and web browsing. While iOS tablets command the premium segment, Android tablets dominate in terms of volume and price diversity. Demand from the education and business segments is expanding rapidly, shifting the market's center of gravity from entertainment towards productivity.
Device manufacturers must navigate a complex web of certifications, including FCC standards for radio frequency emissions in the United States and CE marking for safety in the European Union. In countries like India, Bureau of Indian Standards (BIS) certification is mandatory for market access, impacting supply chain timelines. Stakeholder success will hinge on adapting product strategies to divergent regional regulations and the growing demand for repairability and device longevity.
Market Dynamics
The tablet market's trajectory is defined by its pivot from consumer media consumption to a specialized tool for education and enterprise. This shift is driven by government-led digital learning initiatives and corporate demand for mobile productivity solutions in field operations.
Growth Catalysts
- Government Education Programs:Digital education mandates in countries like India, which include large-scale tablet procurement for students and teachers, are creating significant, concentrated demand and standardizing device specifications for the education sector.
- Enterprise Mobility:Adoption in logistics, field services, and healthcare for tasks like inventory management, service dispatch, and electronic health records is expanding the market beyond office-based productivity into specialized vertical applications.
- 5G Connectivity:The rollout of 5G networks enhances the utility of cellular-enabled tablets, enabling high-speed, low-latency connectivity for applications such as cloud gaming, augmented reality, and real-time data synchronization for mobile workforces.
Market Restraints
- Product Cannibalization:Large-screen smartphones and increasingly powerful, lightweight convertible laptops directly compete with tablets, narrowing the unique value proposition and use cases for a standalone tablet in many consumer segments.
- Component Supply Concentration:The supply of critical components like high-resolution OLED display panels and advanced application processors is concentrated among a few global suppliers, creating vulnerability to price volatility and supply disruptions.
- Elongated Replacement Cycles:Unlike smartphones, tablets experience slower hardware degradation and software obsolescence, leading to longer ownership periods and slower replacement cycles, which dampens new unit sales volume in mature markets.
Strategic Opportunities
- Right-to-Repair Mandates:European Union directives promoting device repairability create an opportunity for manufacturers to design modular tablets with easily replaceable batteries, screens, and ports, marketing longevity and lower total cost of ownership.
- Industrial and Ruggedized Devices:There is significant white space for specialized, ruggedized tablets designed for harsh environments in manufacturing, construction, and public safety, featuring enhanced durability, glove-touch capability, and specialized I/O ports.
- Telehealth Expansion:Growing telehealth infrastructure in regions like North America and Europe offers an opportunity for tablets optimized for remote patient monitoring, secure video consultations, and integration with medical peripherals.
Industry Challenges
- Divergent Certification Requirements:Manufacturers face operational friction from needing to secure distinct certifications for market access, such as FCC clearance in the US, CE marking in the EU, and BIS approval in India, complicating global product launches.
- Software Ecosystem Fragmentation:Developing applications that work seamlessly across different operating systems and device form factors remains a persistent challenge, particularly for enterprise customers requiring integration with legacy backend systems.
- E-Waste and Circular Economy Compliance:Increasing regulatory pressure regarding electronic waste requires manufacturers to establish complex reverse logistics and refurbishment programs, adding operational cost and complexity to lifecycle management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Market |
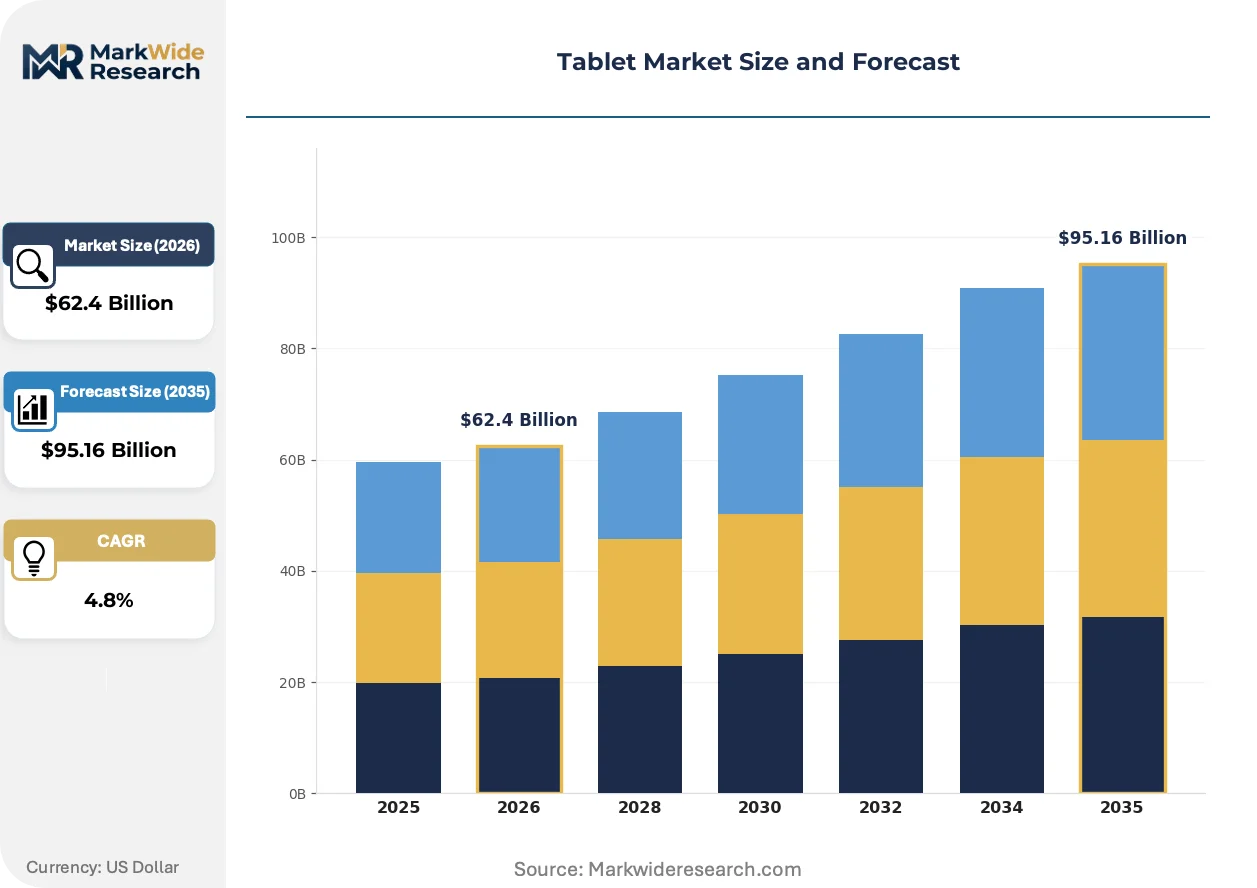
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $95.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Android Tablets, iOS Tablets, Windows Tablets, Chrome OS Tablets, Fire OS Tablets Technology: LCD Display, OLED Display, Retina Display, IPS Display, TFT Display Application: Education, Gaming, Business, Graphic Design, Entertainment, Field Work Customer Type: Students, Freelancers, Corporate Professionals, Graphic Artists, Educators |
| Companies Covered | Huawei, Lenovo Group, Apple, Google, Microsoft, Samsung Electronics, Xiaomi, Acer, Amazon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Market Strategic Shifts & Innovations
The tablet's evolution from a passive content viewer to an active productivity instrument is the market's defining narrative. This transformation is driven by the convergence of more powerful hardware with increasingly specialized software ecosystems, tailored for professional and educational use.
Neural Processing Units (NPUs) are dedicated hardware accelerators within a system-on-a-chip (SoC) for machine learning tasks. Creative professionals and enterprise clients are rapidly adopting NPU-equipped tablets for on-device AI functions. This development is unifying separate AI hardware and software into a single, efficient component, enabling complex applications without cloud reliance.
The European Union's Digital Markets Act (DMA) imposes new interoperability and access requirements on major operating system gatekeepers. This regulation directly compels platform owners to permit alternative app stores and third-party payment systems on their devices. Tablet ecosystems built on proprietary operating systems are most affected, particularly in Europe, forcing a strategic rethink of app distribution and service monetization.
Enterprises and educational institutions are shifting from capital expenditures on devices to subscription-based Device-as-a-Service (DaaS) models. This disrupts traditional retail channels by bundling hardware, software, and lifecycle management into a recurring operational cost. This procurement pattern is most visible in corporate deployments across North America and Europe.
Tablet Market Segmentation
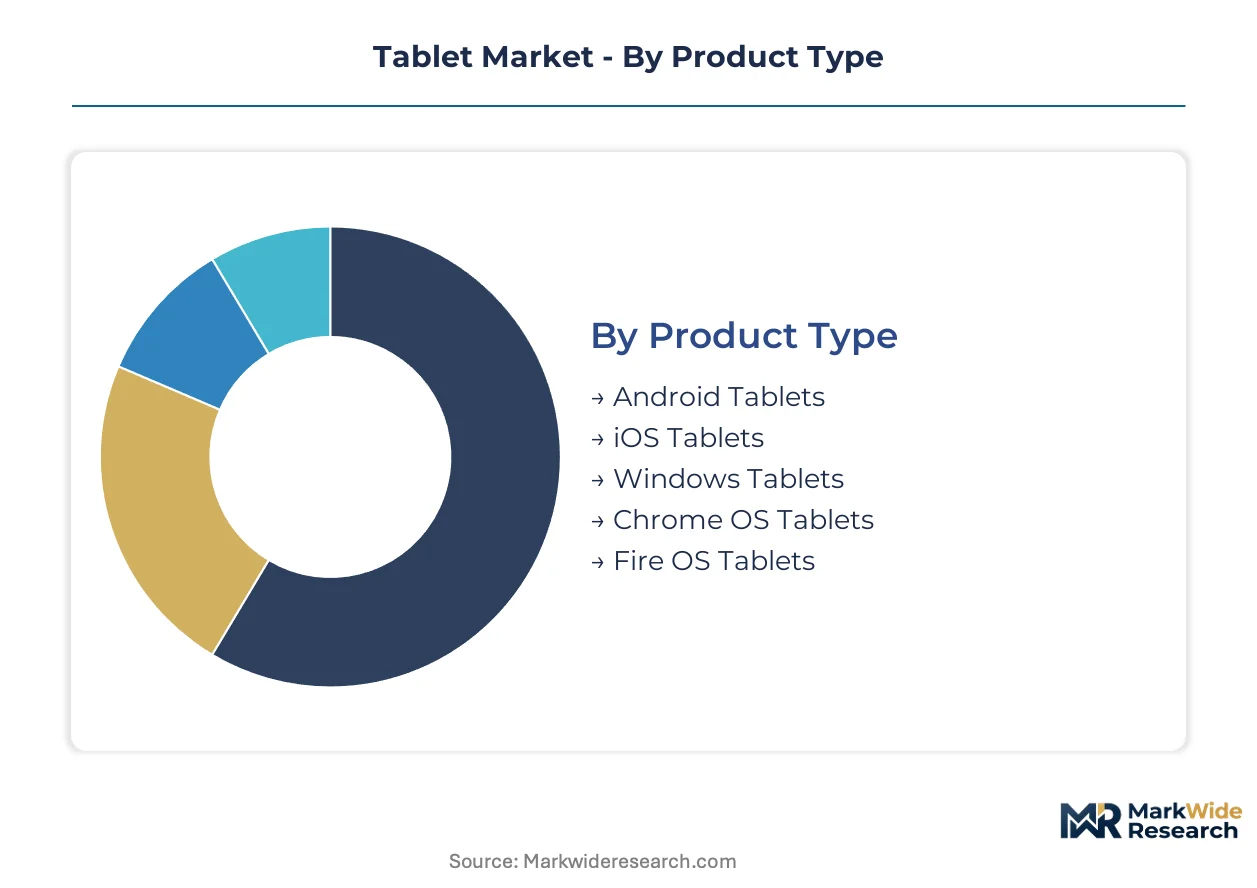
The Tablet Market exhibits diverse characteristics driven by evolving user needs and technological advancements. Understanding these segments helps manufacturers tailor product development and marketing strategies effectively. This analysis breaks down the market across key dimensions, highlighting the varied demands influencing device design and software ecosystems.
Product Type:
Buyer decisions for tablets frequently center on the operating system, which dictates app availability, ecosystem integration, and user experience.
- Android Tablets:These devices utilize Google's open-source Android operating system, offering extensive customization and a wide range of hardware configurations. Demand concentrates in emerging markets like India, driven by affordability and diverse applications in education.
- iOS Tablets:Apple's proprietary iPad line runs on iOS, known for its tightly integrated hardware-software ecosystem and strong app optimization. Premium segment demand comes from creative professionals and enterprise users in North America and Europe, valuing performance and security.
- Windows Tablets:These tablets run Microsoft's Windows OS, often blurring the line with laptops, and target productivity-focused business users.
- Chrome OS Tablets:Google's Chrome OS powers these devices, primarily aimed at the education sector and users seeking cloud-centric computing.
- Fire OS Tablets:Amazon's Fire OS, a fork of Android, primarily serves content consumption and smart home control within Amazon's ecosystem.
Volume sits with Android Tablets; growth tilts toward Windows Tablets.
Technology:
Display technology choices are often driven by desired visual fidelity and power efficiency, impacting both cost and user experience.
- OLED Display:Organic Light Emitting Diode displays deliver superior contrast, true blacks, and vibrant colors with lower power consumption compared to LCDs. Demand concentrates in premium consumer devices and high-end graphic design tablets in Europe, driven by visual quality requirements.
- Retina Display:Apple's Retina displays feature pixel densities where individual pixels are indistinguishable to the human eye at a typical viewing distance. These are prominent in Apple's iOS tablets, catering to users requiring sharp text and detailed imagery for professional tasks.
- LCD Display:Liquid Crystal Displays remain a cost-effective and widely adopted technology, offering good brightness and color reproduction across various tablet models.
- IPS Display:In-Plane Switching technology provides wide viewing angles and accurate color reproduction, common in mid-range to high-end tablets for a better visual experience.
- TFT Display:Thin-Film Transistor displays are a foundational LCD technology, found in more budget-friendly tablets due to their lower manufacturing cost.
OLED Display technology is expanding most quickly, while LCD Display technology still accounts for significant unit volumes.
Application:
Tablet application segmentation reflects the evolving utility of these devices, moving beyond mere entertainment to specialized professional and educational functions.
- Education:Tablets are integral to digital learning curricula, providing interactive content delivery, e-textbooks, and collaborative tools for students. Demand is concentrated in India and other developing nations, propelled by government-led digital education initiatives.
- Business:Enterprise use spans various sectors including logistics, healthcare, and field services, enabling mobile productivity, data collection, and specialized operational tasks. Adoption is significant in North America and Europe, driven by corporate demand for mobile workforce solutions.
- Entertainment:This segment encompasses content consumption like streaming, e-reading, and casual gaming, representing a traditional and still substantial tablet use case.
- Gaming:Tablets optimized for gaming feature powerful processors and high-refresh-rate displays, catering to mobile gamers seeking immersive experiences.
- Graphic Design:High-performance tablets with stylus support and advanced displays serve graphic artists and designers for digital illustration and photo editing.
- Field Work:Ruggedized tablets with enhanced durability and specialized connectivity are deployed in construction, public safety, and other harsh environments.
The Education segment is gaining share fastest, while Entertainment applications maintain a broad user base.
Customer Type:
Customer type segmentation highlights the diverse demographic and professional groups for whom tablets fulfill specific daily requirements.
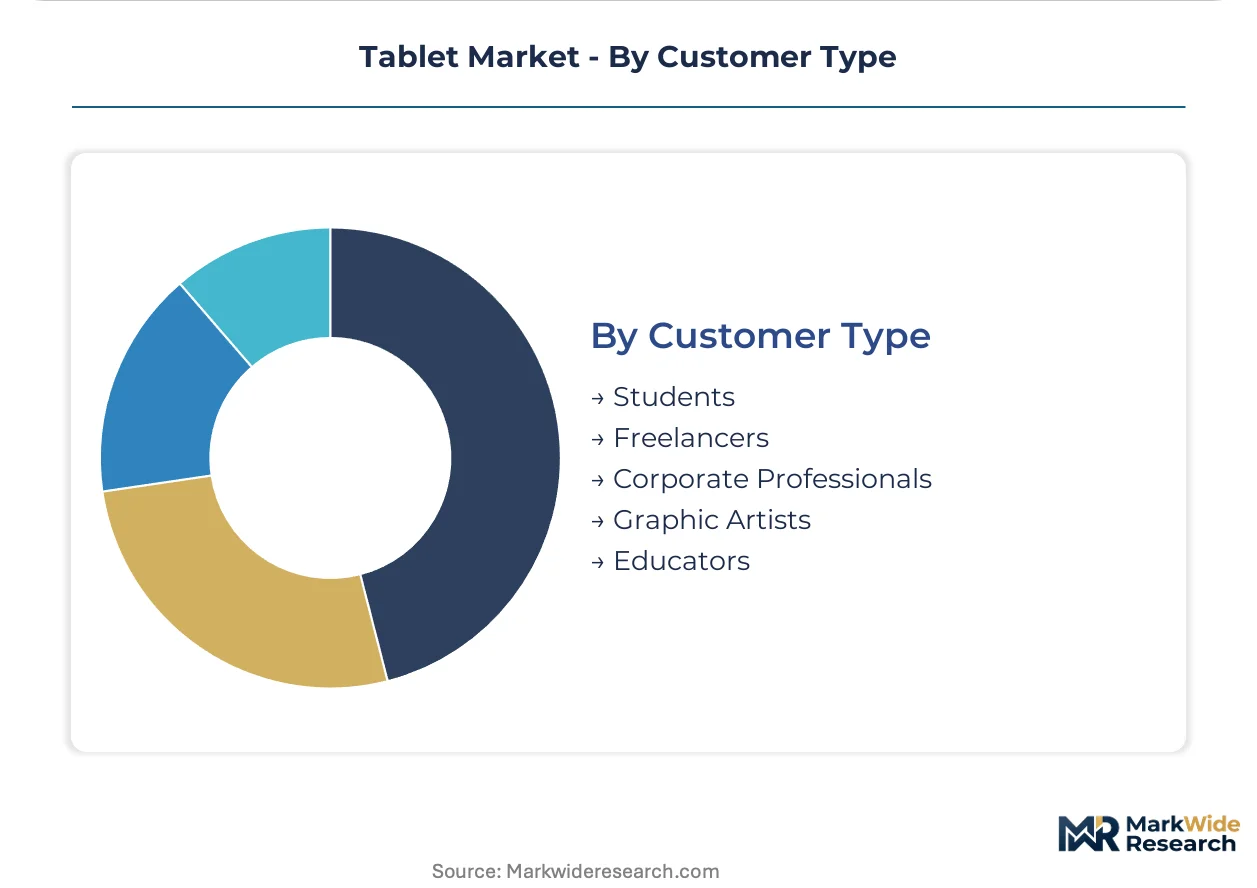
- Students:Students utilize tablets for digital textbooks, note-taking, online research, and interactive learning platforms within educational institutions. This customer type is a primary driver of large-scale procurement in countries implementing digital education mandates.
- Corporate Professionals:Professionals leverage tablets for presentations, document editing, remote collaboration, and specialized business applications in various enterprise settings. This segment values security features, device management capabilities, and integration with existing IT infrastructure.
- Freelancers:Freelancers often seek versatile tablets that balance productivity with portability for tasks ranging from content creation to client communication.
- Educators:Teachers and instructors use tablets for lesson planning, classroom management, digital grading, and delivering interactive educational content.
- Graphic Artists:Graphic artists require tablets with high-resolution screens, precise stylus input, and powerful processing for digital art and design work.
Students represent the fastest-growing customer base, with Corporate Professionals also showing strong expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for tablets is pronounced in key global markets, driven by government initiatives and corporate adoption. This regional disparity influences product specifications and market entry strategies. Manufacturers adapt to diverse regulatory landscapes and consumer preferences across these geographies.
India
Government education programs, including large-scale tablet procurements, are creating significant demand. The Bureau of Indian Standards (BIS) certification is mandatory for market access, impacting supply chain timelines. Educational technology hubs in cities like Bengaluru and Hyderabad are driving innovation in digital learning content for tablet platforms.
United States
Corporate demand for mobile productivity solutions and expanding telehealth services drives tablet adoption. Federal Communications Commission (FCC) standards for radio frequency emissions are a critical compliance requirement. Technology clusters in Silicon Valley and Boston are developing specialized software and hardware for enterprise and healthcare tablet applications.
Germany
Enterprise mobility and premium segment demand for high-performance tablets characterize the German market. CE marking for safety is essential for market entry within the European Union. Munich and Berlin are centers for industrial design and engineering, influencing modular tablet development for repairability and longevity.
France
Digital learning initiatives and corporate deployments of Device-as-a-Service (DaaS) models are expanding tablet usage. Compliance with EU directives, including the common charger mandate, shapes product design. Paris and Lyon are emerging as hubs for educational technology and enterprise software integration with tablet ecosystems.
Japan
Advanced 5G connectivity and a strong focus on productivity tools are driving tablet adoption in Japan. Manufacturers must adhere to Ministry of Economy, Trade and Industry (METI) guidelines for electronic devices. Tokyo's tech industry is pioneering new applications for NPU-equipped tablets in creative and professional fields.
Tablet Market Key Industry Players
Asian producers anchor one tier of the tablet market, offering diverse Android-based devices across multiple price points. North American specialists hold a significant share in the premium and productivity-focused segments. The competitive structure is tiered, with significant differentiation in operating systems and target applications. Companies engage in portfolio diversification and strategic partnerships to expand their market reach.
Within the premium segment, Apple exemplifies a tightly integrated hardware-software ecosystem with its iOS tablets. Samsung Electronics, a South Korean company, occupies a position across multiple price points, offering diverse Android-based devices globally. Microsoft, an American corporation, with its Surface line, anchors the productivity-focused hybrid device category, blurring the line between tablet and laptop functionalities.
| Leading Market Players |
|---|
| Huawei |
| Lenovo Group |
| Apple |
| Microsoft |
| Samsung Electronics |
| Xiaomi |
| Acer |
| Amazon |
| Others |
Cost & Logistics Intelligence
OLED display technology's increasing integration into tablets reshapes cost economics due to higher manufacturing expenses and concentrates supply among specialized panel producers. This shift impacts overall device pricing and introduces new dependencies within the supply chain.
Pricing Analysis
Volume-driven Android tablets face significant price competition, while iOS tablets command premium margins. Pricing stratifies across premium, standard, and economy tiers, driven by ecosystem integration and specialized features like NPU-enabled processors. Pricing pressure stems from product cannibalization by larger smartphones and convertible laptops. The education segment exhibits high price sensitivity, contrasting with corporate professionals who prioritize security and integration.
Supply Chain Analysis
Bureau of Indian Standards (BIS) certification in India and CE marking in Europe gate market access, influencing supply chain timelines. Component supply concentrates in China, South Korea, and Taiwan for critical inputs like high-resolution OLED display panels and advanced application processors. Single-source vulnerability for these components presents a significant structural risk. Distribution runs through both traditional retail channels and direct procurement models for enterprise and education DaaS solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tablet market is supply-constrained, primarily due to limited global manufacturing capacity for advanced display panels. This bottleneck props up pricing for premium devices, influencing market entry strategies.
For Market Incumbents: Anticipate continued product cannibalization from large-screen smartphones and lightweight laptops by focusing on specialized use cases. Diversify component sourcing to mitigate risks from concentrated suppliers in South Korea and Taiwan, investing in modular design for repairability to meet EU directives. Emphasize R&D into NPU-enabled applications for creative and enterprise segments, reinforcing ecosystem lock-in.
For New Entrants and Emerging Players: The EU's right-to-repair directives in Europe open a window for modular tablet designs emphasizing longevity and lower total cost of ownership. Target the underpenetrated ruggedized device segment for field work in construction and public safety, along with telehealth applications in North America. A go-to-market strategy centered on Device-as-a-Service models can secure recurring revenue from educational institutions and enterprises.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized B2B tablet manufacturers given expanding enterprise mobility demand and government-led education initiatives. Long-term viability hinges on deep integration into critical workflows across education, healthcare, and industrial sectors. Focus on mid-cap firms with strong intellectual property in secure operating systems or rugged hardware solutions. Watch for increasing government procurement tenders for educational tablets as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification into Rugged Devices | Targets underserved industrial and public safety segments with enhanced durability. |
| Investment in NPU-enabled Processors | Enables on-device AI capabilities for creative professionals and enterprise clients. |
| Expansion of Device-as-a-Service Models | Captures recurring revenue streams from corporate and educational institutions. |
| Modular Design for Repairability | Addresses EU right-to-repair mandates, extending device longevity and reducing e-waste. |
| Strategic Partnerships for 5G Integration | Enhances connectivity for mobile workforces and cloud-based applications. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. We engaged product managers, procurement officers, IT directors, and education technology specialists. Secondary sources included SEC 10-K filings, technology research reports, and government education policy documents. This approach ensured robust data triangulation, combining bottom-up market sizing with top-down validation.
An analytical framework reconciled diverse data streams to project market evolution across the analysis window. The model segmented the market by product type, application, customer type, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected demand elasticity. Key inputs included device refresh cycles, government education spending, and 5G network rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for foldable display technology would alter the outlook. Forecasts reflect assumptions regarding macroeconomic stability and regulatory enforcement. A model refresh is warranted upon material change in global semiconductor supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Earbuds Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Phone Headsets Market