
 Social Media Engagement Applications Market | 2026-2036
Social Media Engagement Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Social Media Engagement Applications Market Analytics
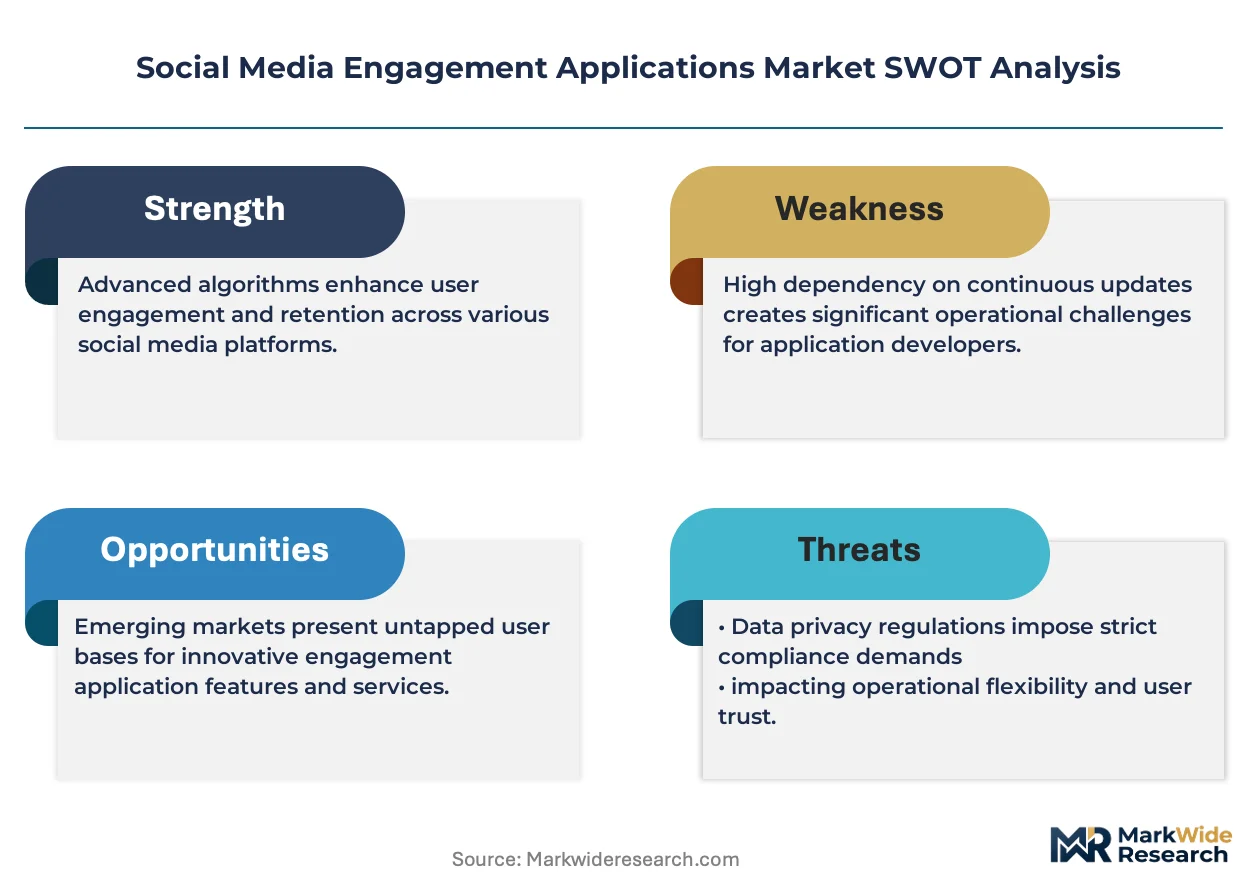
Platform licensing revenue is narrowing relative to direct commerce and creator monetization tools as social networks pivot from ad dependency. Meta Platforms leverages its Reels infrastructure and messaging commerce stack to sustain engagement-to-transaction pipelines. ByteDance anchors short-form video monetization through TikTok Shop integrations and algorithmic content distribution. Zapier competes by extending automation bridges between engagement platforms and CRM systems, occupying a connective layer that larger platforms underinvest in.
Social media engagement applications comprise software systems that orchestrate audience interaction, content distribution, and performance measurement across networked communication platforms, typically processing real-time behavioral signals through API-connected architectures to optimize reach and conversion outcomes. Their primary commercial purpose centers on converting attention metrics into attributable business outcomes for brand and agency operators. Cloud-based deployment models lead structural adoption due to elastic scaling requirements during campaign spikes and live event windows, while SaaS delivery concentrates margin pools through recurring subscription structures. Social listening functions represent the fastest-expanding feature category as brands demand real-time sentiment extraction and competitive intelligence across fragmented platform ecosystems.
The EU AI Act imposes algorithmic transparency obligations on engagement optimization systems deployed in Europe, forcing platforms to document content-ranking logic and risk classification protocols. The Federal Trade Commission in the United States scrutinizes dark pattern design and undisclosed influencer amplification, shaping product standards for disclosure automation and audience targeting controls. Stakeholders must monitor evolving interoperability mandates and data portability requirements that could unlock multi-platform workflow unification and erode single-vendor lock-in advantages.
Market Dynamics
Algorithmic transparency mandates from the EU AI Act are forcing engagement platforms to reengineer content-ranking architectures and document recommendation logic, compressing competitive advantages previously derived from opaque optimization systems.
Growth Catalysts
- Creator Monetization Infrastructure:Direct commerce integrations and native checkout tools transform engagement metrics into attributable revenue streams, pulling enterprise marketing spend toward platforms with closed-loop transaction capabilities.
- GDPR-Driven Data Governance:First-party data activation tools gain priority as brands rebuild audience intelligence around consented signal collection rather than third-party tracking deprecation.
- Short-Form Video Proliferation:TikTok Shop and Reels commerce stacks normalize impulse purchasing within entertainment feeds, expanding addressable transaction volume for engagement application vendors.
Market Restraints
- API Rate Limit Volatility:Platform policy shifts at Meta and ByteDance unpredictably constrain data access volumes, destabilizing multi-platform orchestration workflows and forcing redundant infrastructure investment.
- Talent Concentration in San Francisco and London:Machine learning engineers with social graph expertise cluster in two metropolitan hubs, inflating compensation costs and constraining vendor scaling velocity.
- Algorithmic Audit Compliance Burden:EU AI Act documentation requirements impose fixed operational overhead regardless of deployment scale, disproportionately compressing margins for mid-tier SaaS providers.
Strategic Opportunities
- India's Vernacular Creator Economy:Regional language content monetization remains underpenetrated as local payment infrastructure and brand-direct partnerships mature, opening first-mover positioning for engagement tools with native Indic language NLP.
- Convergence of Generative AI and Real-Time Personalization:Large language model integration with dynamic creative optimization enables individualized content generation at segment-of-one scale, collapsing production timelines for campaign asset deployment.
- CSRD-Aligned ESG Reporting Automation:Social listening data repurposed for sustainability narrative verification and stakeholder sentiment tracking creates incremental revenue attachment to compliance mandates.
Industry Challenges
- Cross-Platform Identity Resolution:Fragmented user graphs across TikTok, Instagram, and emerging networks complicate attribution modeling, requiring probabilistic matching investments that degrade measurement precision.
- Dark Pattern Design Scrutiny:FTC enforcement actions against undisclosed influencer amplification and manipulative interface elements force product roadmap pivots that sacrifice engagement optimization for legal defensibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Media Engagement Applications Market |
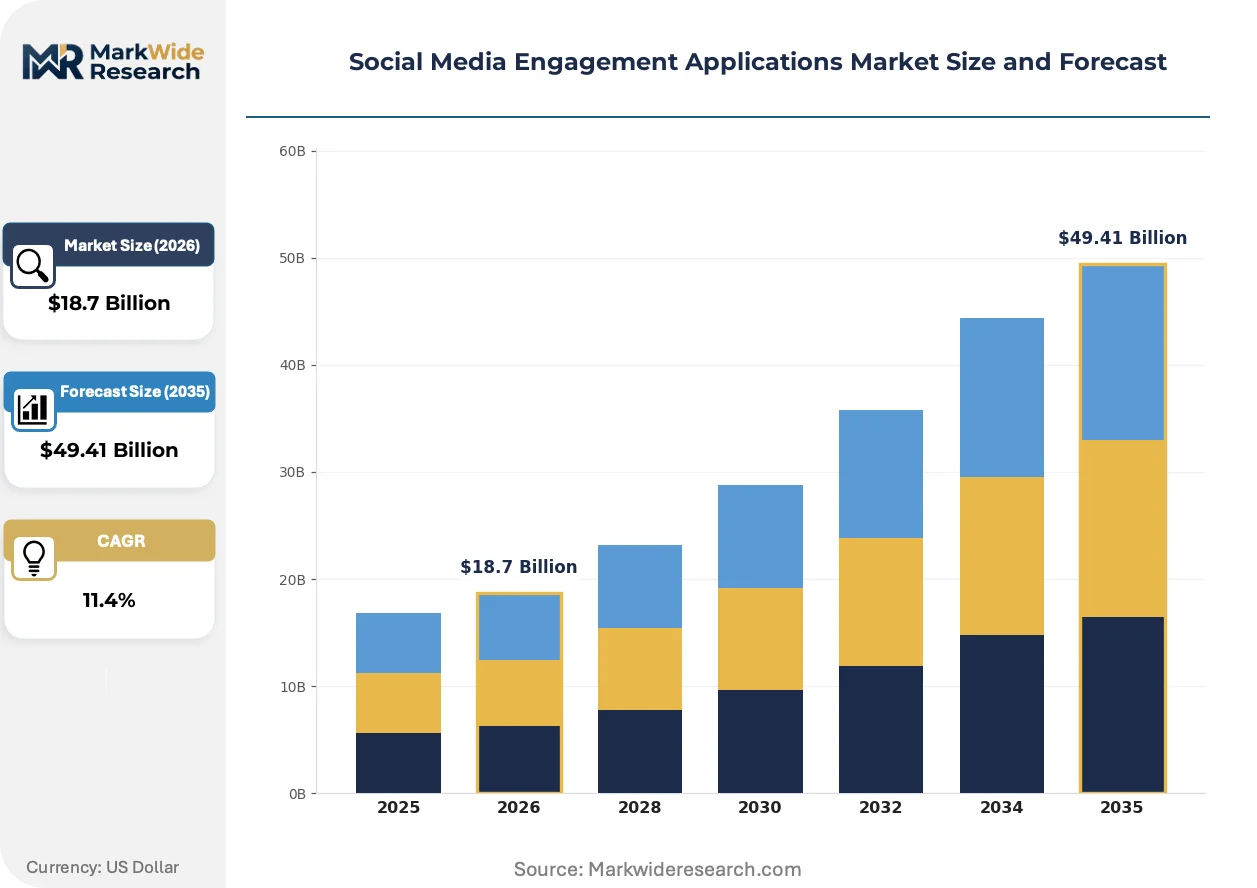
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Content Creation, Analytics, Social Listening, Engagement Tools Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS End User: Brands, Agencies, Influencers, Small Businesses Features: Automated Posting, Performance Metrics, Audience Insights, Chatbot Integration |
| Companies Covered | Meta Platforms, Alphabet Inc., ByteDance, Tencent, Telegram, Microsoft, Snap Inc., Reddit, Zapier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Media Engagement Applications Market Evolving Landscape
Real-time behavioral signal processing and automated creative generation are compressing campaign iteration cycles from weeks to hours, redefining competitive advantage around velocity rather than scale.
Generative adversarial networks for synthetic media production are digitizing influencer content creation workflows. Mid-market brands now deploy AI-generated avatars for localized campaign variants without human talent coordination. This capability is digitizing cost structures that previously required six-figure production budgets and multi-week timelines.
The EU AI Act's risk classification framework imposes documentation burdens on engagement optimization systems deployed in Europe. Platforms must maintain technical files detailing content-ranking parameters and human oversight protocols. Social listening vendors with European enterprise clients are restructuring product architectures to isolate algorithmic decision paths for audit trail generation.
Enterprise procurement of engagement tools is consolidating around outcome-based contracts tied to attributable revenue rather than seat-based subscriptions. Marketing teams at direct-to-consumer brands now negotiate performance guarantees with SaaS vendors, transferring optimization risk to technology suppliers. This shift is most visible in the United States where commerce-platform integrations enable closed-loop measurement infrastructure.
Social Media Engagement Applications Market Segmentation
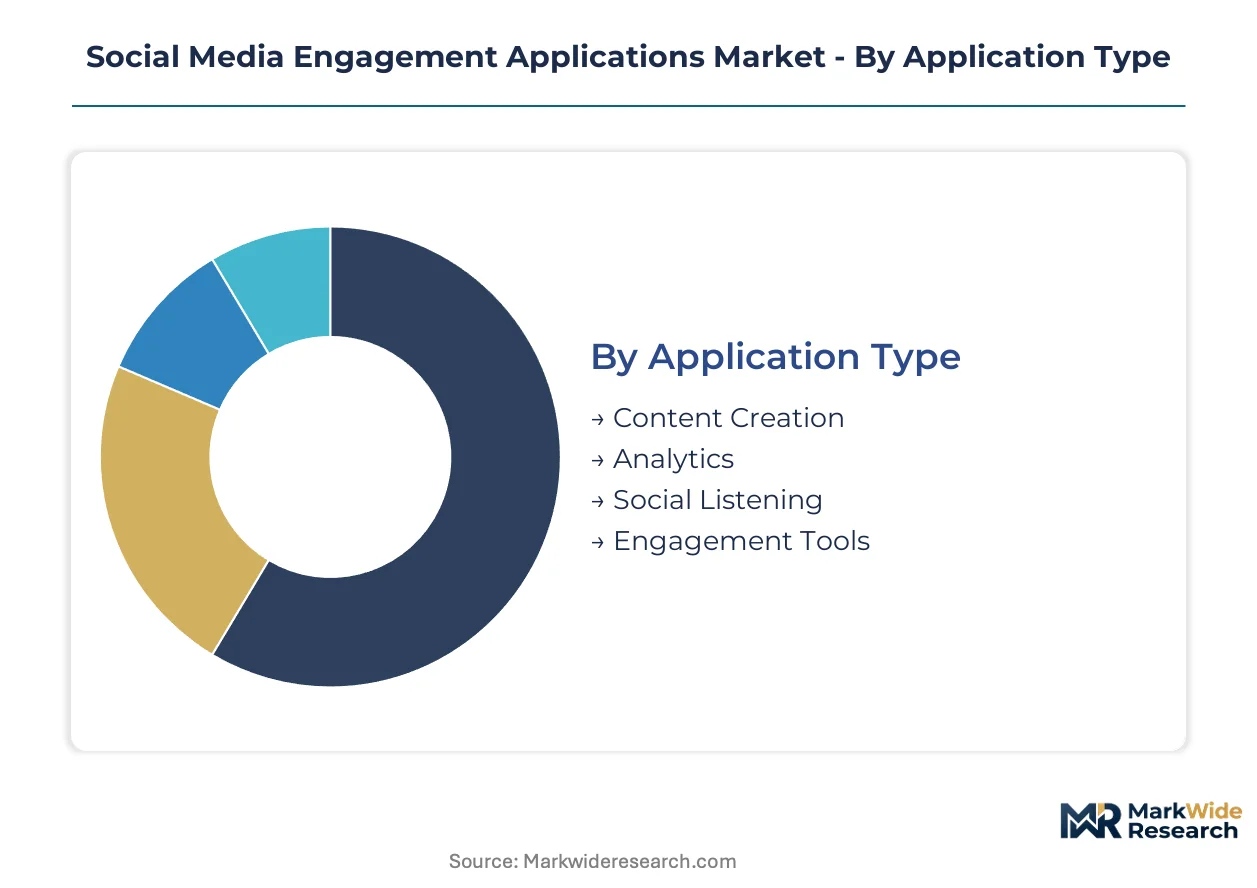
Segmentation in social media engagement applications reveals divergent procurement cycles and margin structures. Cloud-native solutions refresh every 18-24 months while on-premise deployments extend to 5-7 year horizons. Feature-level purchasing decisions increasingly decouple from platform licensing as brands assemble modular tech stacks.
Application Type:
Content creation tools turn over fastest as generative AI compresses production timelines, while social listening platforms embed deepest into enterprise workflows with slower replacement cycles.
- Content Creation:Generative AI-powered asset generation systems now produce campaign variants in hours rather than weeks. Demand concentrates among direct-to-consumer brands in the United States seeking localized creative at scale without talent coordination overhead.
- Social Listening:Real-time sentiment extraction engines process behavioral signals across fragmented platform ecosystems. European enterprise procurement prioritizes these tools for EU AI Act compliance documentation and competitive intelligence synthesis.
- Analytics:Attribution modeling platforms unify cross-platform performance data for closed-loop measurement.
- Engagement Tools:Community management and response automation systems orchestrate direct audience interaction at scale.
Content Creation anchors the volume base while Social Listening gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates elastic consumption models from capital-intensive infrastructure commitments, with hybrid architectures capturing mid-market procurement seeking compliance flexibility.
- Cloud-Based:Elastic scaling architectures accommodate traffic spikes during live events and campaign launches without provisioning overhead. United States-based enterprise marketing teams drive adoption for distributed workforce coordination and rapid deployment.
- SaaS:Recurring subscription structures concentrate margin pools through seat-based or outcome-based pricing. European procurement increasingly mandates SaaS delivery to satisfy GDPR data residency requirements and audit trail obligations.
- Hybrid:Split architectures isolate sensitive data processing on-premise while leveraging cloud elasticity for public-facing functions.
- On-Premise:Self-managed infrastructure persists in regulated industries requiring air-gapped environments for competitive intelligence operations.
SaaS delivery commands the revenue base while Cloud-Based deployments expand most quickly among mid-market entrants.
End User:
Customer type segmentation maps to divergent buying authority structures, with enterprise brands consolidating vendor relationships while influencer segments drive feature innovation through direct platform feedback.
- Brands:Enterprise marketing organizations with dedicated platform budgets negotiate outcome-based contracts tied to attributable revenue. Procurement concentrates in the United States where commerce-platform integrations enable closed-loop measurement.
- Agencies:Multi-client service providers demand white-label capabilities and cross-account workflow unification to manage portfolio complexity.
- Influencers:Individual creator monetization needs spur demand for lightweight tools with native commerce integration and simplified analytics.
- Small Businesses:Resource-constrained operators prioritize all-in-one solutions with minimal configuration overhead and template-driven content production.
Brands anchor the spending base while Influencers climb the fastest as creator economy infrastructure matures.
Features:
Functional module purchasing follows workflow integration depth, with automation layers attaching to existing systems while insight tools require standalone adoption decisions.
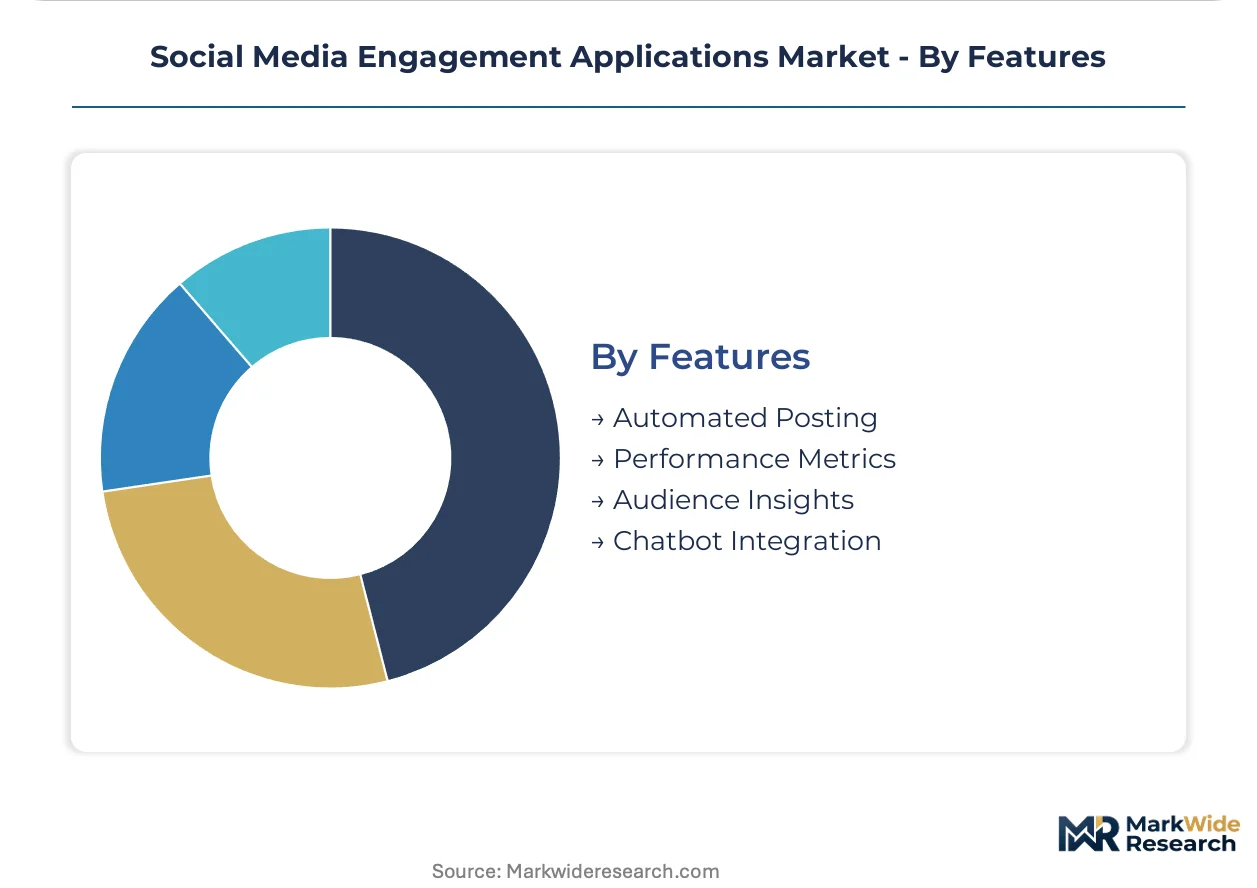
- Automated Posting:Schedule optimization engines determine optimal publish windows through engagement pattern analysis. Demand clusters among agency users managing multi-brand publishing calendars across time zones.
- Audience Insights:Demographic and behavioral segmentation tools rebuild first-party intelligence as third-party signal deprecation accelerates. European brands prioritize these capabilities for GDPR-compliant consented data activation.
- Performance Metrics:Cross-platform dashboarding unifies reach, engagement, and conversion indicators for executive reporting.
- Chatbot Integration:Conversational automation layers embed commerce transactions within messaging interfaces.
Automated Posting anchors the feature adoption base while Audience Insights gains share fastest as first-party data strategies intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States demonstrate the lowest price elasticity for engagement tools, while small businesses across emerging markets prioritize freemium tiers and localized payment methods that compress vendor margins.
United States
Creator economy infrastructure and closed-loop commerce integrations drive premium platform adoption. The FTC scrutinizes dark pattern design and undisclosed influencer amplification, forcing disclosure automation into product roadmaps. San Francisco and New York City concentrate machine learning engineering talent for social graph optimization, inflating compensation costs for vendors seeking scale.
Germany
Industrial brands and automotive marketing teams demand GDPR-compliant first-party data activation tools. The EU AI Act imposes algorithmic transparency obligations on engagement optimization systems, requiring technical documentation of content-ranking parameters. Berlin anchors startup development for privacy-preserving analytics, while Munich hosts enterprise procurement decisions for DAX-listed manufacturers.
India
Vernacular creator monetization and regional language content distribution expand addressable user bases. The Digital Personal Data Protection Act reshapes consent frameworks for audience intelligence collection. Bengaluru and Mumbai concentrate engineering talent for Indic language NLP development, supporting localization at scale for engagement application vendors.
United Kingdom
Agency holding companies and direct-to-consumer brands consolidate vendor relationships around outcome-based contracts. The Online Safety Bill introduces duty-of-care obligations for platform design standards affecting engagement optimization. London's Soho and Shoreditch districts cluster influencer marketing agencies that drive feature feedback loops for lightweight analytics tools.
Brazil
Small business operators and individual creators dominate demand for simplified, template-driven content production. ANVISA and consumer protection agencies enforce disclosure requirements for commercial content amplification. São Paulo anchors Latin American headquarters decisions for global platforms, while Rio de Janeiro concentrates lifestyle brand marketing spend on short-form video integrations.
Social Media Engagement Applications Market Competitive Landscape
Platform-native giants and connective automation specialists split the market between closed-loop commerce ecosystems and interoperability middleware. Consolidation pressure intensifies as enterprise procurement favors vendors with attributable revenue measurement capabilities. Three archetypes dominate: vertically integrated social networks with native checkout infrastructure, API bridge providers occupying underinvested integration layers, and modular SaaS vendors assembling best-of-breed feature stacks. Competitive moves center on M&A for first-party data assets and strategic partnerships that embed transaction capabilities within messaging interfaces.
Within the platform-native tier, Meta Platforms and ByteDance exemplify commerce-integrated engagement architectures that convert attention metrics directly into attributable transactions. Zapier occupies a distinct position as a connective-layer specialist, extending automation bridges between fragmented engagement platforms and enterprise CRM systems where larger competitors underinvest.
| Leading Market Players |
|---|
| Meta Platforms |
| Alphabet Inc. |
| ByteDance |
| Tencent |
| Telegram |
| Microsoft |
| Snap Inc. |
| Zapier |
| Others |
Value Network & Pricing Analysis
San Francisco Bay Area engineering clusters concentrate machine learning talent for social graph optimization, inflating compensation costs that vendors pass downstream through premium SaaS tiers. This supply concentration reinforces pricing power for incumbents with established talent pipelines while compressing margins for mid-tier entrants competing on feature parity.
Pricing Analysis
Outcome-based contract tiers now drive lifetime value as enterprise procurement shifts from seat-based subscriptions to performance guarantees tied to attributable revenue. Three-tier pricing structure across premium, standard, and economy levels separates enterprise marketing teams with dedicated platform budgets from resource-constrained small businesses seeking template-driven solutions. Cost compression in mid-market SaaS is intensifying because API rate limit volatility forces redundant infrastructure investment. Small business operators across emerging markets demonstrate highest price sensitivity, while United States enterprise buyers show lowest elasticity for tools with closed-loop commerce measurement.
Supply Chain Analysis
Tariff exposure between United States and China dominates risk planning for hardware-dependent edge computing infrastructure supporting real-time behavioral signal processing. Cloud infrastructure provisioning concentrates in United States, Ireland, and Singapore data center clusters. Raw material dependencies span silicon wafers, specialized GPUs, and subsea cable capacity. Single-source vulnerability in NVIDIA GPU supply chains threatens scaling velocity for generative AI-powered creative tools. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with regional account executives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates constitute a regulatory inflection forcing product architecture reengineering across the entire competitive landscape. This disruption creates asymmetric opportunities for vendors with pre-built audit trail capabilities.
For Market Incumbents: Pre-empt margin erosion by consolidating first-party data assets through targeted acquisition of social listening specialists with European enterprise footprints. Invest in documentation infrastructure for EU AI Act technical files before compliance deadlines compress operational bandwidth. Channel control through exclusive messaging commerce partnerships with Meta Platforms and ByteDance defends against API bridge disintermediation.
For New Entrants and Emerging Players: Build out vernacular creator economy infrastructure in India before local payment rails and brand-direct partnerships mature. India's regional language content monetization remains the most penetrable geography for engagement tools with native Indic language NLP. A vertical go-to-market targeting Bengaluru-based creator collectives bypasses incumbent channel saturation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular SaaS vendors assembling best-of-breed feature stacks over vertically integrated platform giants facing regulatory headwinds. Long-term viability across the next decade hinges on attributable revenue measurement capabilities that satisfy enterprise procurement consolidation. Watch for FTC enforcement actions against dark pattern design as signal for compliance-driven M&A premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding commerce transactions within Meta's messaging interfaces captures closed-loop attribution. |
| Acquisition of Specialist Firm | First-party data assets from social listening vendors satisfy EU AI Act documentation requirements. |
| Geographic Expansion | India's vernacular creator economy opens first-mover positioning before infrastructure maturation. |
| Strategic Partnership | API bridge agreements with Zapier extend workflow automation into underinvested integration layers. |
| Product Launch | Generative AI-powered avatar systems digitize influencer content production for mid-market brands. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with platform engineering directors, enterprise marketing executives, creator economy operators, and compliance officers at SaaS vendors; and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie engagement metrics, and EU regulatory documentation. Bottom-up triangulation across deployment model adoption curves and top-down validation against aggregate platform revenue disclosures anchored volume estimates.
Forecast inputs span deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs derive from segment-level growth rate blending weighted by procurement cycle timing. Industry-specific forecast inputs include API rate limit policy trajectories at major platforms and EU AI Act implementation timelines.
Stress conditions across platform policy volatility, talent compensation inflation, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about creator monetization infrastructure maturation and commerce-platform integration velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Road Safety Market
Others
Food Technology Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Solar Panel Testers Market
Others
Griffin Beaker Market
Others
Evidence Management Market
Others
Smart Home Solutions Market
Others
Security Envelopes Market
Others
Advanced Combat Helmet Market
Others
Astrology Market
Others
Asia Pacific Contract Packaging Market
Others
Hot Air System Market
Others
Europe Intercom Devices Market
Others
Global Contactless Biometrics Technology Market
Others
Africa 3D Printing Construction Market
Others
Asia-Pacific Programmatic Display Advertising Market