
 Japan Anti-Caking Market | 2026-2036
Japan Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Anti-Caking Market Foresight
The Japan anti-caking ingredient trade is restructuring around a sharp split between pharmaceutical-grade silicates commanding stringent purity premiums and commodity carbonates serving bulk fertilizer and road-salt blending. BASF SE leverages its global silicate technology base to sustain high-specification supply lines into Japanese pharmaceutical customers. Kao Corporation anchors domestic food-grade production through integrated fatty acid derivative channels. Evonik Industries AG competes on precipitated silica specialization for hygroscopic powder formulations.
Anti-caking agents are inorganic or organic additives, typically comprising silicates, carbonates, or fatty acid salts, manufactured through precipitation, calcination, or surface-modification processes to maintain particulate flowability by absorbing excess moisture or reducing interparticle friction. Their primary commercial purpose spans food processing, pharmaceutical tableting, and agricultural fertilizer conditioning where caking disrupts dosing accuracy and shelf stability. Sodium silicoaluminate occupies the mature volume core in seasoning and flour applications, while calcium silicate captures expanding share in pharmaceutical excipient blends where compression performance matters. Talc retains niche positioning in personal care powders where lubricity and skin-feel differentiate premium cosmetic formulations.
METI administers chemical substance safety assessments under the Chemical Substances Control Law, while the Ministry of Health, Labour and Welfare sets food additive specifications through the Food Sanitation Act, together elevating compliance costs for imported anti-caking materials. JIS standards for industrial silicate grades further segment qualification pathways between food-contact and non-contact applications. Stakeholders must monitor evolving MHLW purity revisions and Kanto-region logistics constraints as domestic pharmaceutical and precision food manufacturing tighten supplier qualification windows.
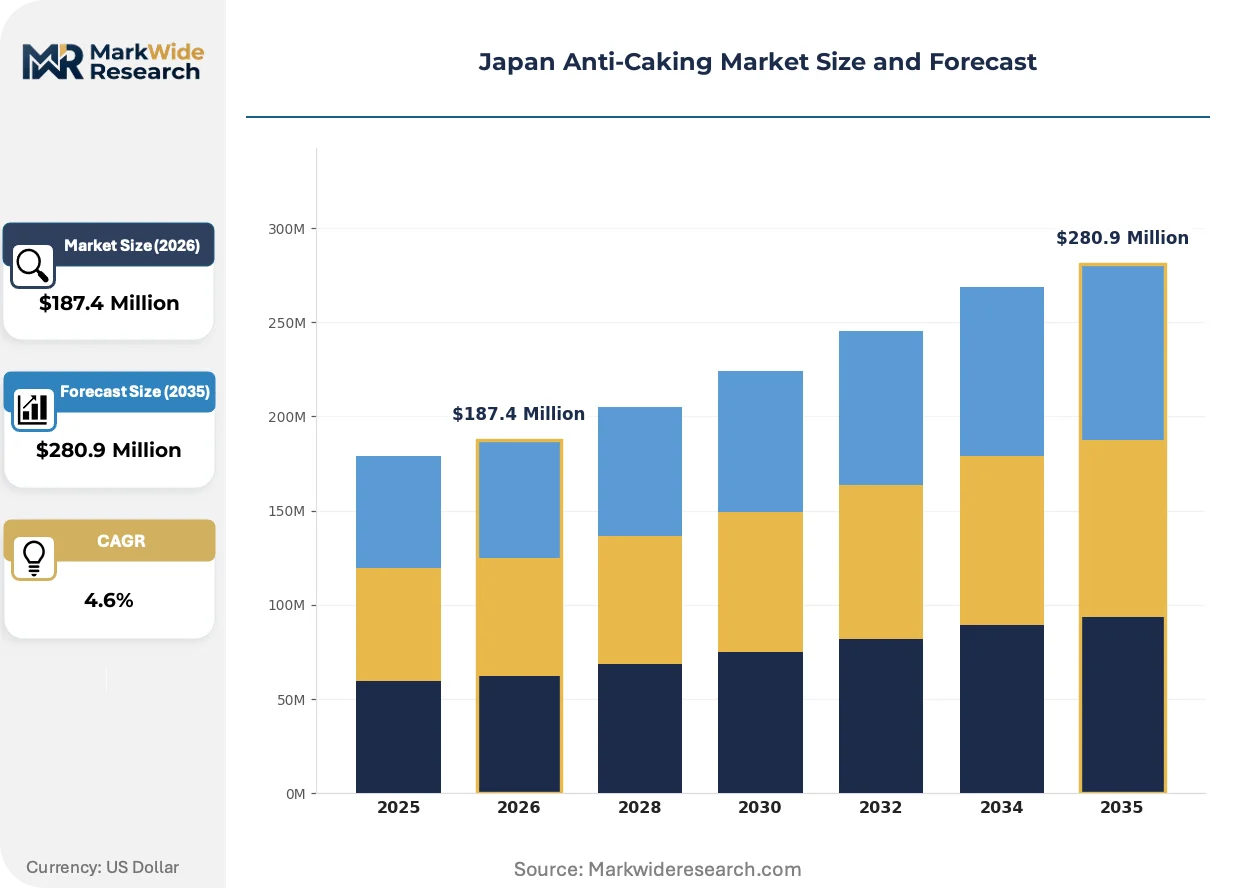
Market Dynamics
METI's tightening purity benchmarks under the Chemical Substances Control Law are forcing domestic anti-caking suppliers to restructure qualification protocols, splitting the market between pharmaceutical-grade silicates and commodity carbonates.
Growth Catalysts
- Instant noodle manufacturing scale-up:Seasoning packet producers in Saitama prefecture are expanding sodium silicoaluminate offtake to maintain powder flowability during high-speed filling operations.
- METI chemical substance management frameworks:Stricter impurity thresholds are accelerating replacement of legacy anti-caking stocks with certified pharmaceutical-grade alternatives in excipient applications.
- Kanto industrial corridor concentration:Proximity between Tokyo pharmaceutical formulators and Saitama food processors enables just-in-time silicate delivery networks with reduced inventory carrying costs.
Market Restraints
- High-purity silica feedstock volatility:Precipitated silica producers face input cost swings from energy-intensive calcination processes tied to regional electricity pricing.
- Import dependency for pharmaceutical-grade silicates:Domestic capacity constraints force Japanese tablet manufacturers to qualify overseas suppliers through extended PMDA notification pathways.
- Calcium carbonate substitution pressure:Fertilizer blenders in northern prefectures are shifting toward unconditioned bulk salts to reduce additive expenditure amid compressed agricultural margins.
Strategic Opportunities
- Hyogo prefecture pharmaceutical cluster expansion:Osaka-Kobe corridor tablet manufacturers are diversifying excipient sourcing beyond Kanto-based suppliers.
- Surface-modified fatty acid salt formulations:Kao Corporation's integrated fatty acid channels enable custom anti-caking blends for moisture-sensitive nutraceutical powders.
- MHLW food additive specification revisions:Upcoming purity standard updates will disqualify marginal imports, opening share for domestic producers with pre-qualified JIS certification.
Industry Challenges
- PMDA pharmaceutical excipient master file preparation:New market entrants face 18-24 month documentation timelines to support tablet compression performance claims.
- Legacy seasoning plant equipment retrofitting:Sodium silicoaluminate dosing systems require pneumatic conveying upgrades incompatible with existing flour handling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Anti-Caking Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicoaluminate, Calcium Silicate, Magnesium Carbonate, Talc Application: Food Processing, Pharmaceutical, Agriculture, Personal Care Form: Powder, Granule, Liquid, Crystal End User: Food Producers, Cosmetic Manufacturers, Agricultural Suppliers, Chemical Companies |
| Companies Covered | Merck KGaA, BASF SE, Kao Corporation, Roquette Frères, Evonik Industries AG, AGC Chemicals, Huber Engineered Materials, PPG Industries, Solvay SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Anti-Caking Market Shifts & Advancements
Japanese anti-caking formulation is pivoting toward engineered particle architectures that combine moisture absorption with compression performance, displacing single-function legacy additives.
Precipitated silica with controlled pore distribution is expanding into pharmaceutical tableting applications where simultaneous glidant and disintegrant functions reduce excipient count. Osaka-based contract manufacturers are qualifying these grades ahead of generic drug portfolio expansions. The technology is compressing traditional multi-additive blending steps into single-silicate solutions.
MHLW's pending revisions to food additive specifications under the Food Sanitation Act are elevating heavy metal testing protocols for imported silicates. Domestic blenders are responding by localizing supplier qualification to reduce border inspection delays. Seasoning producers in Saitama prefecture face the steepest compliance recertification burden.
Direct procurement from silicate precipitators is replacing layered distribution networks among mid-sized pharmaceutical formulators. Buyers in the Kanto corridor are negotiating volume commitments in exchange for batch-specific particle size certificates. This pattern is most pronounced among generic tablet manufacturers seeking to compress raw material qualification cycles.
Japan Anti-Caking Market Segmentation
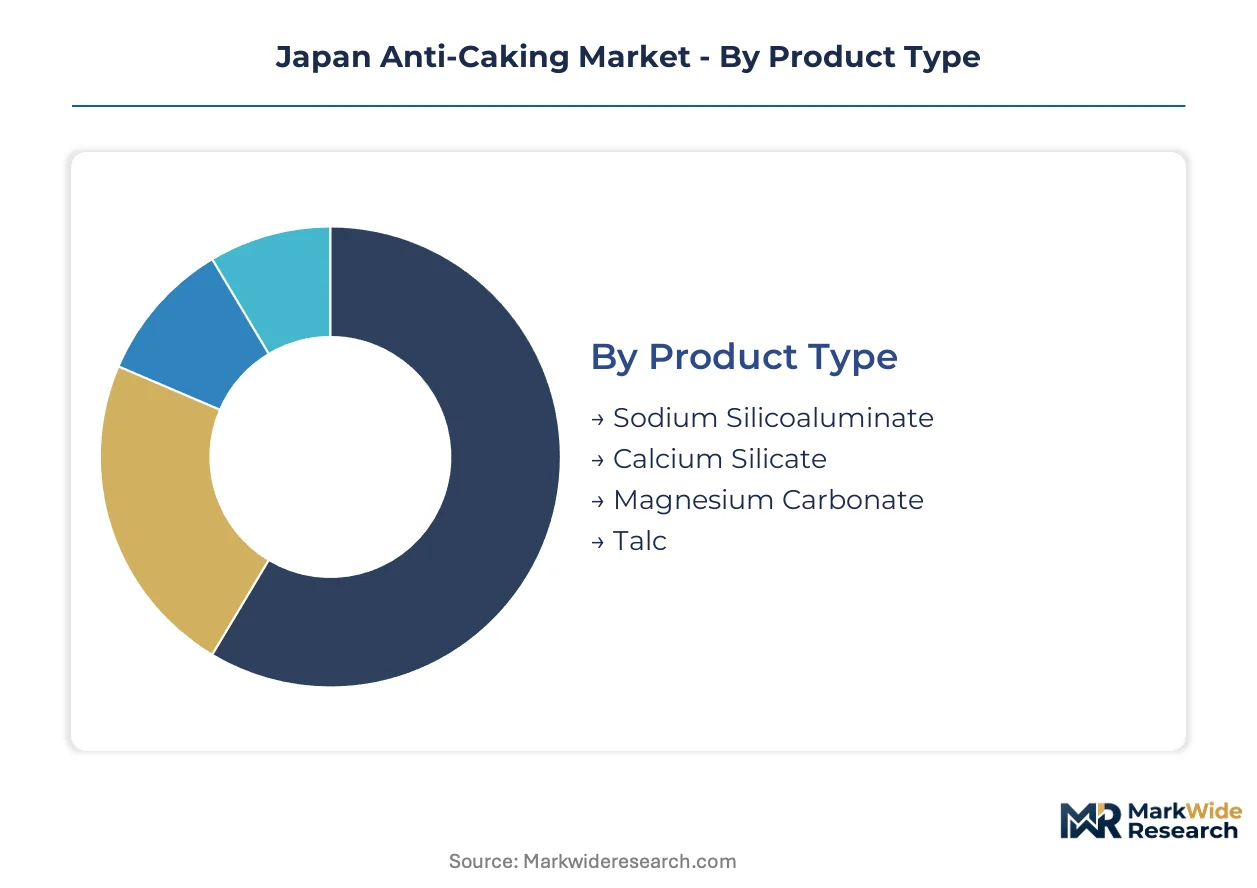
Japanese anti-caking procurement splits sharply between pharmaceutical-grade silicates requiring PMDA master files and commodity carbonates serving bulk fertilizer blending. Formulators in Tokyo and Saitama prefectures prioritize flowability specifications over price in seasoning applications, while tablet manufacturers demand compression-grade precipitated silica with documented particle size distributions.
Product Type:
Cost tier separates buyers seeking certified pharmaceutical excipients from bulk fertilizer conditioners accepting industrial-grade carbonates.
- Sodium Silicoaluminate:Synthetic amorphous aluminosilicate manufactured through sodium silicate and aluminum sulfate precipitation. Demand concentrates in Saitama prefecture seasoning plants where hygroscopic powder flowability determines high-speed filling line throughput; METI impurity thresholds are accelerating replacement of legacy stocks with certified food-grade alternatives.
- Calcium Silicate:Porous precipitated silicate with high specific surface area and oil absorption capacity. Pharmaceutical tablet formulators in the Kanto corridor specify this grade for simultaneous glidant and disintegrant functionality; PMDA notification pathways favor domestic producers with pre-qualified JIS certification.
- Magnesium Carbonate:Light or heavy carbonate grades produced through magnesite calcination or seawater precipitation. Fertilizer blenders in northern prefectures specify this for hygroscopic ammonium salt conditioning amid compressed agricultural margins.
- Talc:Hydrated magnesium silicate with lamellar particle morphology and low abrasiveness. Cosmetic powder manufacturers leverage its lubricity and skin-feel properties in premium formulations.
Volume sits with sodium silicoaluminate; growth tilts toward calcium silicate.
Application:
Customer type dictates specification intensity, with pharmaceutical formulators running 18-24 month qualification cycles versus agricultural buyers purchasing on spot price.
- Food Processing:Anti-caking functionality in seasoning packets, flour blends, and powdered drink mixes. Instant noodle manufacturers in Saitama prefecture expand sodium silicoaluminate offtake to maintain powder flowability during automated filling operations.
- Pharmaceutical:Excipient applications demanding documented compression performance and disintegration profiles. Osaka-Kobe corridor tablet manufacturers diversify sourcing beyond Kanto-based suppliers to compress raw material qualification cycles.
- Agriculture:Fertilizer conditioning and road-salt anti-caking. Northern prefecture blenders shift toward unconditioned bulk salts to reduce additive expenditure.
- Personal Care:Talc and modified silicates in cosmetic powders and dry shampoo formulations. Premium positioning depends on particle morphology and dermatological testing documentation.
Revenue concentrates in pharmaceutical applications; food processing delivers the steepest volume expansion trajectory.
Form:
Supply concentration in precipitated silica manufacturing favors powder and granule outputs, while liquid formulations remain marginal.
- Powder:Standard milled precipitates and surface-modified silicates for direct blending. Dominates seasoning and pharmaceutical excipient applications.
- Granule:Agglomerated grades with controlled particle size distribution for reduced dusting. Agricultural fertilizer conditioners prefer this form for pneumatic conveying compatibility.
- Liquid:Colloidal silica suspensions and fatty acid salt solutions. Limited uptake in specialized coating applications.
- Crystal:Purified carbonate and silicate crystalline forms. Niche positioning in high-purity pharmaceutical and laboratory reagent segments.
Granule forms are expanding most quickly in agricultural conditioning; powder retains pharmaceutical and food processing dominance.
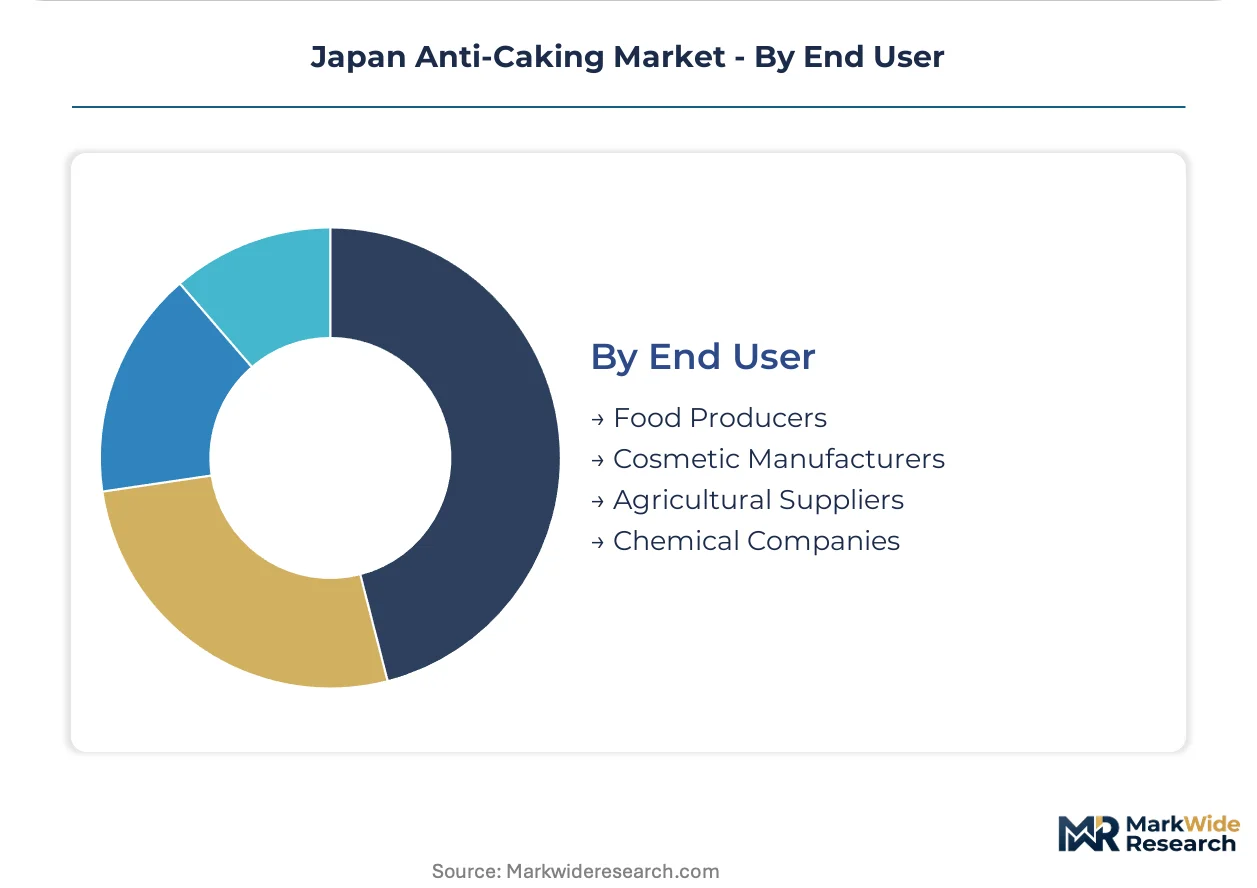
End User:
Geography within Japan determines logistics configuration, with Kanto corridor concentration enabling just-in-time delivery networks.
- Food Producers:Seasoning manufacturers and flour millers in Saitama and Tokyo prefectures. MHLW food additive specification revisions drive supplier requalification toward domestic JIS-certified sources.
- Cosmetic Manufacturers:Personal care formulators in Osaka and Kobe seeking premium talc and modified silicates. Product differentiation depends on particle size certificates and dermatological safety documentation.
- Agricultural Suppliers:Fertilizer blenders and road-salt distributors in northern Honshu. Price pressure from compressed agricultural margins favors commodity carbonate grades.
- Chemical Companies:Industrial silicate distributors and specialty chemical blenders serving multi-sector demand. Direct procurement from precipitators is replacing layered distribution networks.
Food producers command the largest volume share; cosmetic manufacturers deliver the highest margin per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kanto industrial corridor around Tokyo and Saitama prefectures concentrates Japanese anti-caking demand through seasoning manufacturers and pharmaceutical formulators. METI's chemical substance management frameworks and MHLW food additive specifications shape supplier qualification across sub-regional markets.
Kanto Region
Tokyo pharmaceutical tablet manufacturers and Saitama instant noodle seasoning plants drive sodium silicoaluminate offtake. METI's Chemical Substances Control Law enforces impurity thresholds that accelerate replacement of legacy stocks. The Tokyo-Saitama logistics corridor enables just-in-time silicate delivery networks with reduced inventory carrying costs.
Kansai Region
Osaka-Kobe corridor tablet manufacturers diversify excipient sourcing beyond Kanto-based suppliers to compress raw material qualification cycles. PMDA notification pathways favor domestic producers with pre-qualified JIS certification. Contract manufacturers in Osaka are qualifying precipitated silica grades ahead of generic drug portfolio expansions.
Chubu Region
Nagoya-based chemical distributors serve industrial silicate demand across central Japan. MHLW food additive specification revisions drive supplier requalification toward domestic JIS-certified sources. The region's automotive and machinery supply chains generate secondary demand for precision powder handling additives.
Northern Honshu
Fertilizer blenders in northern prefectures face compressed agricultural margins shifting toward unconditioned bulk salts. METI's industrial silicate standards segment qualification pathways between food-contact and non-contact applications. Road-salt distributors in the region specify magnesium carbonate for hygroscopic ammonium salt conditioning.
Kyushu
Chemical processing facilities in Fukuoka and Kitakyushu import pharmaceutical-grade silicates through extended PMDA notification pathways. Domestic capacity constraints force tablet manufacturers to qualify overseas suppliers. The region's port infrastructure supports bulk carbonate imports for agricultural conditioning applications.
Japan Anti-Caking Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity certification and application specificity. The Japanese anti-caking market structures around three tiers: multinational chemical conglomerates with global silicate technology bases, integrated domestic producers with fatty acid derivative channels, and specialized precipitated silica manufacturers. Market consolidation is accelerating through PMDA master file preparation barriers that extend qualification timelines for new entrants. Direct procurement from silicate precipitators is replacing layered distribution networks among mid-sized pharmaceutical formulators.
Within the multinational chemical tier, BASF SE and Evonik Industries AG occupy positions anchored by precipitated silica specialization and pharmaceutical-grade supply capabilities. Kao Corporation exemplifies the integrated domestic producer archetype through its fatty acid derivative channels. Merck KGaA represents the pharmaceutical-grade excipient specialist segment serving tablet compression applications. These three companies collectively span the premium-mid-economy pricing differentiation across seasoning, pharmaceutical, and industrial end-uses.
| Leading Market Players |
|---|
| Merck KGaA |
| BASF SE |
| Kao Corporation |
| Roquette Frères |
| Evonik Industries AG |
| AGC Chemicals |
| Huber Engineered Materials |
| PPG Industries |
| Solvay SA |
| Others |
Supply & Pricing Matrix
PMDA pharmaceutical excipient master file preparation timelines are compressing procurement windows for Japanese tablet manufacturers, forcing supply chains to absorb extended qualification costs while pricing stratifies across certification tiers.
Pricing Analysis
Throughput guarantees in high-speed seasoning packet filling anchor value-based pricing for sodium silicoaluminate grades, with pharmaceutical excipient premiums scaling against documented compression performance and disintegration profiles. Price differentiation separates PMDA-notified domestic producers from marginal imports facing MHLW border inspection delays. Cost compression in agricultural-grade magnesium carbonate intensifies because northern prefecture fertilizer blenders shift toward unconditioned bulk salts. Pharmaceutical formulators in the Kanto corridor exhibit lowest price sensitivity; agricultural suppliers in northern Honshu demonstrate highest.
Supply Chain Analysis
Single-source vulnerability sits with precipitated silica feedstock drawn from energy-intensive calcination facilities in China and South Korea, where regional electricity pricing volatility transmits directly into input cost swings. Domestic Japanese pharmaceutical-grade capacity constraints force tablet manufacturers to qualify German and US suppliers through extended PMDA notification pathways. Tariff exposure runs through imported pharmaceutical-grade silicates subject to evolving chemical substance management frameworks. Distribution runs through direct procurement from silicate precipitators replacing layered distribution networks among mid-sized pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where METI's Chemical Substances Control Law creates a barrier-to-entry moat favoring domestic producers with pre-qualified JIS certification and established PMDA master files.
For Market Incumbents: Deploy PMDA master file leverage to extend qualification timelines for overseas competitors seeking pharmaceutical excipient entry. BASF SE and Evonik Industries AG should deepen backward integration into precipitated silica manufacturing to offset energy cost volatility from East Asian calcination facilities. Kao Corporation must defend its fatty acid derivative channels against surface-modified silicate substitution in nutraceutical applications. For New Entrants and Emerging Players: Hyogo prefecture pharmaceutical cluster expansion represents the most penetrable geography, with Osaka-Kobe corridor tablet manufacturers actively diversifying excipient sourcing beyond Kanto-based suppliers. Surface-modified fatty acid salt formulations for moisture-sensitive nutraceutical powders offer white-space entry through custom blending capabilities. A go-to-market angle anchored to batch-specific particle size certificates with compressed qualification cycles addresses the 18-24 month PMDA documentation barrier. For Investors and Strategic Acquirers: Re-rating potential sits with domestic JIS-certified producers given upcoming MHLW food additive specification revisions that will disqualify marginal imports. Long-term viability favors acquisition targets with established PMDA pharmaceutical excipient master files and integrated fatty acid derivative production channels. The signal to watch is MHLW purity standard update timing, which will determine share capture windows for pre-qualified domestic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Master File Preparation | 18-24 month documentation timelines protect incumbent market positions against import competition. |
| Backward Integration into Precipitated Silica | Captive supply of pharmaceutical-grade feedstock insulates against East Asian energy cost volatility. |
| Hyogo Prefecture Capacity Expansion | Osaka-Kobe corridor diversification demand creates geographic arbitrage against Kanto supply concentration. |
| Surface-Modified Fatty Acid Salt Development | Kao Corporation's integrated channels enable custom nutraceutical formulations with moisture absorption functionality. |
| JIS Certification Pre-Qualification | Upcoming MHLW specification revisions will open share for domestic producers with certified food-grade status. |
Research Methodology
Independent corroboration across pharmaceutical formulator procurement leads, seasoning plant operations managers, and chemical distributor account executives underwrites the qualitative findings. Primary interviews with PMDA regulatory consultants, METI chemical substance management officers, and JIS certification auditors combined with secondary validation from customs trade data, MHLW food additive specification filings, and pharmaceutical excipient import records. Bottom-up demand modeling from individual prefecture consumption patterns and top-down supply verification from precipitated silica production capacity triangulate volume estimates.
Comparable-period anchoring to historical seasoning packet production volumes and pharmaceutical tablet compression throughput established the forecast baseline across the analysis window. Segmentation dimensions modeled include product grade tier, end-use application, and regional production hub concentration. CAGRs were derived from trend extrapolation of PMDA notification pathway durations and MHLW specification revision implementation timelines. Industry-specific forecast inputs incorporated instant noodle manufacturing scale-up trajectories in Saitama prefecture and generic drug portfolio expansion patterns in the Osaka-Kobe corridor.
Revisions become necessary when METI impurity threshold adjustments, MHLW food additive specification updates, or East Asian energy pricing shocks materialize outside modeled parameters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market