
 High Shear Mixer Market | 2026-2036
High Shear Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
High Shear Mixer Market Foresight
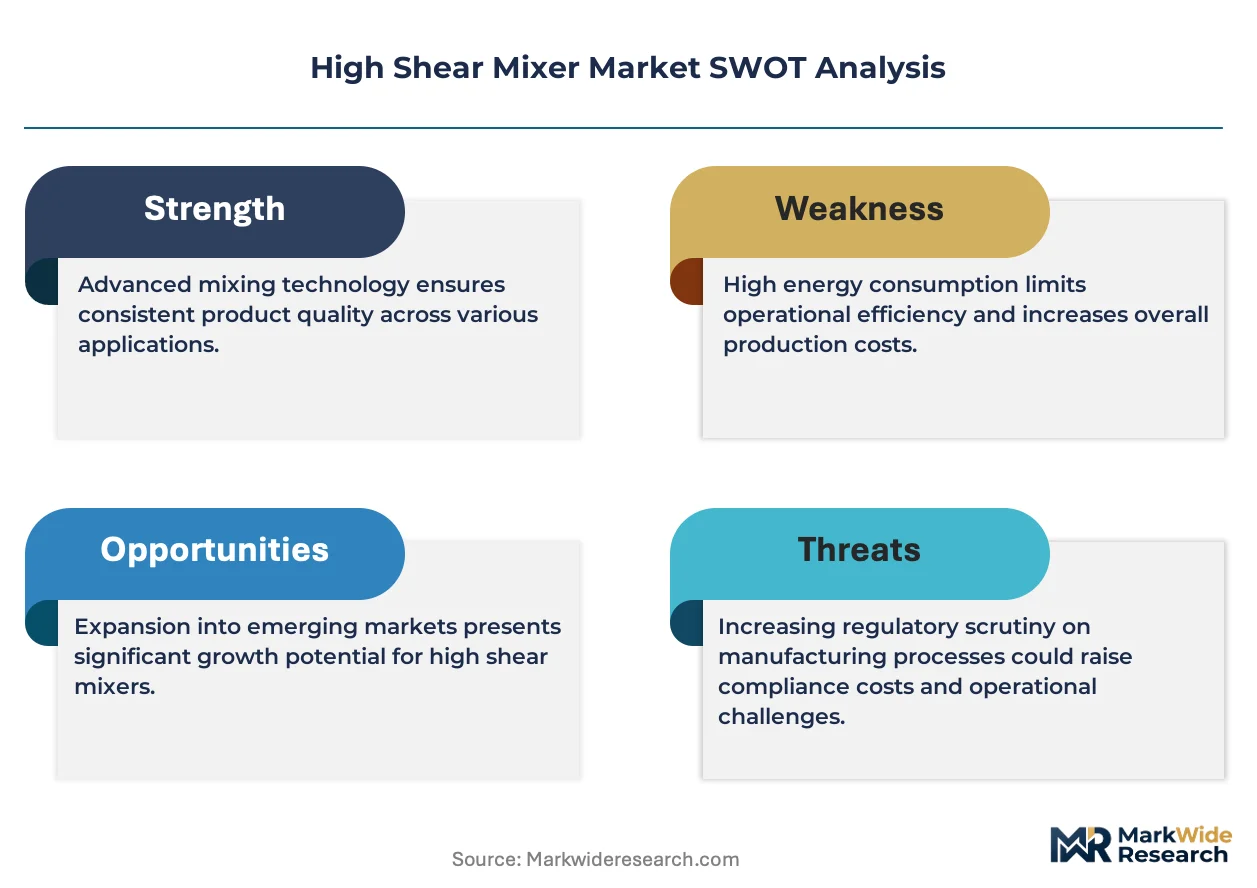
Multi-source procurement for high-shear rotor-stator assemblies is expanding as end-users diversify supplier risk across pharmaceutical and food processing capital budgets. ROSS Mixers leverages in-house foundry capacity to control delivery timelines for custom alloy components. Silverson Machines Ltd. anchors its position through dedicated cleanroom manufacturing lines serving aseptic pharma applications. GEA Group extends engineering reach by integrating high shear modules into larger process skids for dairy and beverage clients.
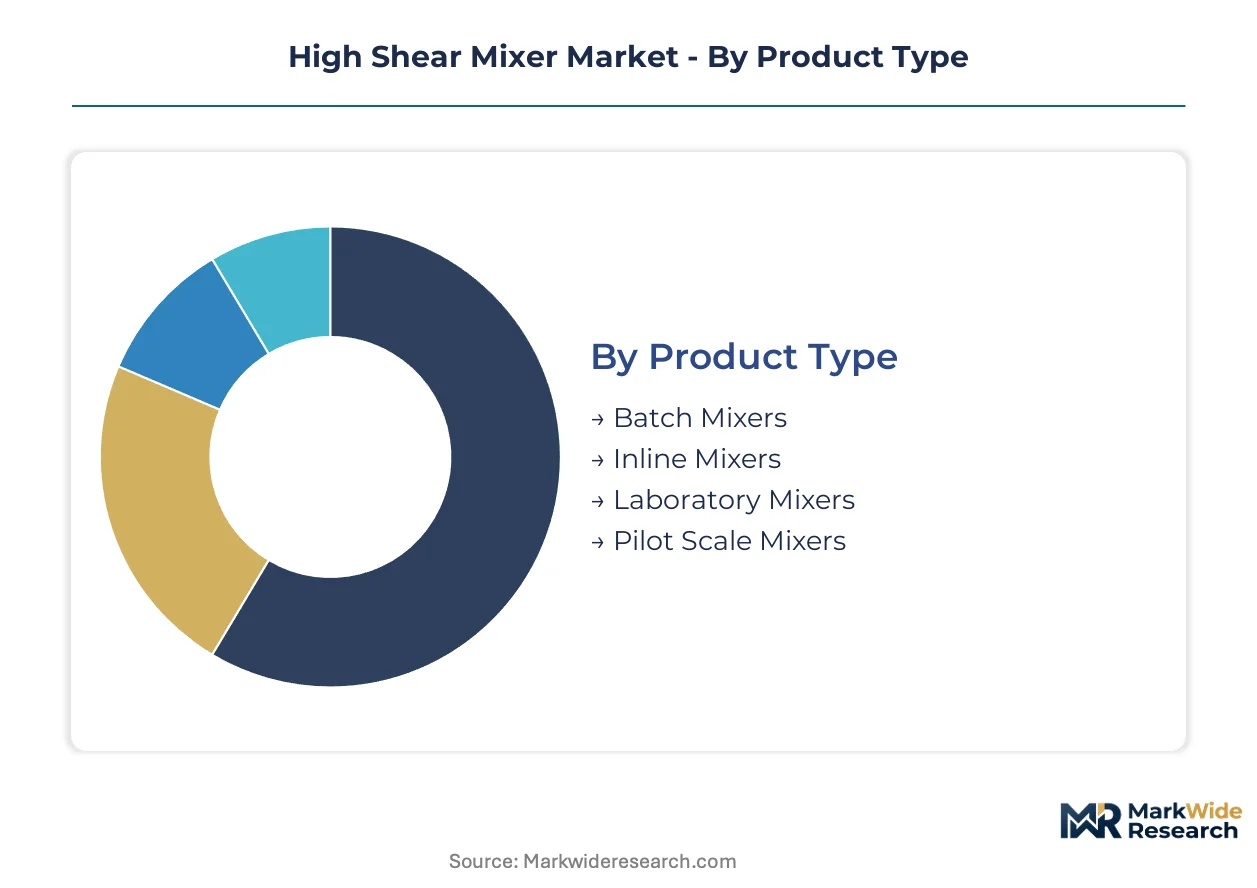
High shear mixers employ intermeshing rotor-stator geometries operating at tip speeds from 10 to 50 m/s to generate intense mechanical energy for particle size reduction and uniform dispersion. Batch configurations dominate installed base volumes across food and cosmetics processing, while inline mixers represent the fastest-growing technology segment as continuous manufacturing replaces vessel-based production in pharmaceutical active ingredient processing. Electromagnetic drive systems command premium positioning due to reduced seal maintenance and improved energy recovery, though mechanical technology retains cost advantages in mid-scale chemical applications.
FDA process validation guidance and EMA Annex 15 requirements on qualification of equipment shape capital allocation toward documented cleanability and material traceability. ISO 9001 and ASME BPE standards further constrain vendor qualification for biopharmaceutical supply chains. Stakeholders must weigh total cost of ownership against throughput flexibility when selecting between batch and continuous high shear architectures.
Market Dynamics
Continuous manufacturing mandates from FDA and EMA are compressing batch processing timelines, forcing pharmaceutical producers to requalify entire mixing trains for inline operation. Equipment vendors must now validate integrated skid systems rather than standalone units, fundamentally altering procurement specifications and service contracts.
Growth Catalysts
- Inline continuous processing:Pharmaceutical active ingredient manufacturers are replacing vessel-based production with rotor-stator inline systems to meet FDA process analytical technology guidance.
- REACH compliance:ECHA substance restrictions on industrial chemicals are accelerating equipment replacement cycles across European coatings and specialty chemical plants.
- Precision engineering clusters:Concentrated supplier networks around Cologne and Düsseldorf are reducing lead times for custom alloy rotor-stator assemblies serving global pharma clients.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel and Hastelloy feedstock for corrosion-resistant rotors concentrates among German and Swedish specialty metal processors.
- Validation cost escalation:ASME BPE and ISO 9001 qualification documentation requirements extend capital deployment cycles for biopharmaceutical installations.
- Mechanical seal maintenance burden:Traditional drive systems require quarterly seal replacement in abrasive slurry applications, elevating total cost of ownership versus electromagnetic alternatives.
Strategic Opportunities
- ASEAN pharmaceutical manufacturing:CDSCO-aligned regulatory harmonization across India, Thailand, and Vietnam is opening contract manufacturing demand for aseptic mixing skids.
- Cell culture media preparation:Biopharma downstream processing requires gentle high-shear cell lysis systems distinct from traditional chemical dispersion applications.
- Electromagnetic drive convergence:Integration of magnetic bearing technology with variable frequency drives eliminates seal maintenance and enables energy recovery.
Industry Challenges
- Cross-functional commissioning expertise:Inline system deployment requires simultaneous mastery of mechanical, electrical, and process automation disciplines that rarely coexist in single engineering teams.
- Legacy batch infrastructure retrofit:Existing vessel-based facilities face structural floor loading and utility capacity constraints when converting to continuous high-shear architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Shear Mixer Market |
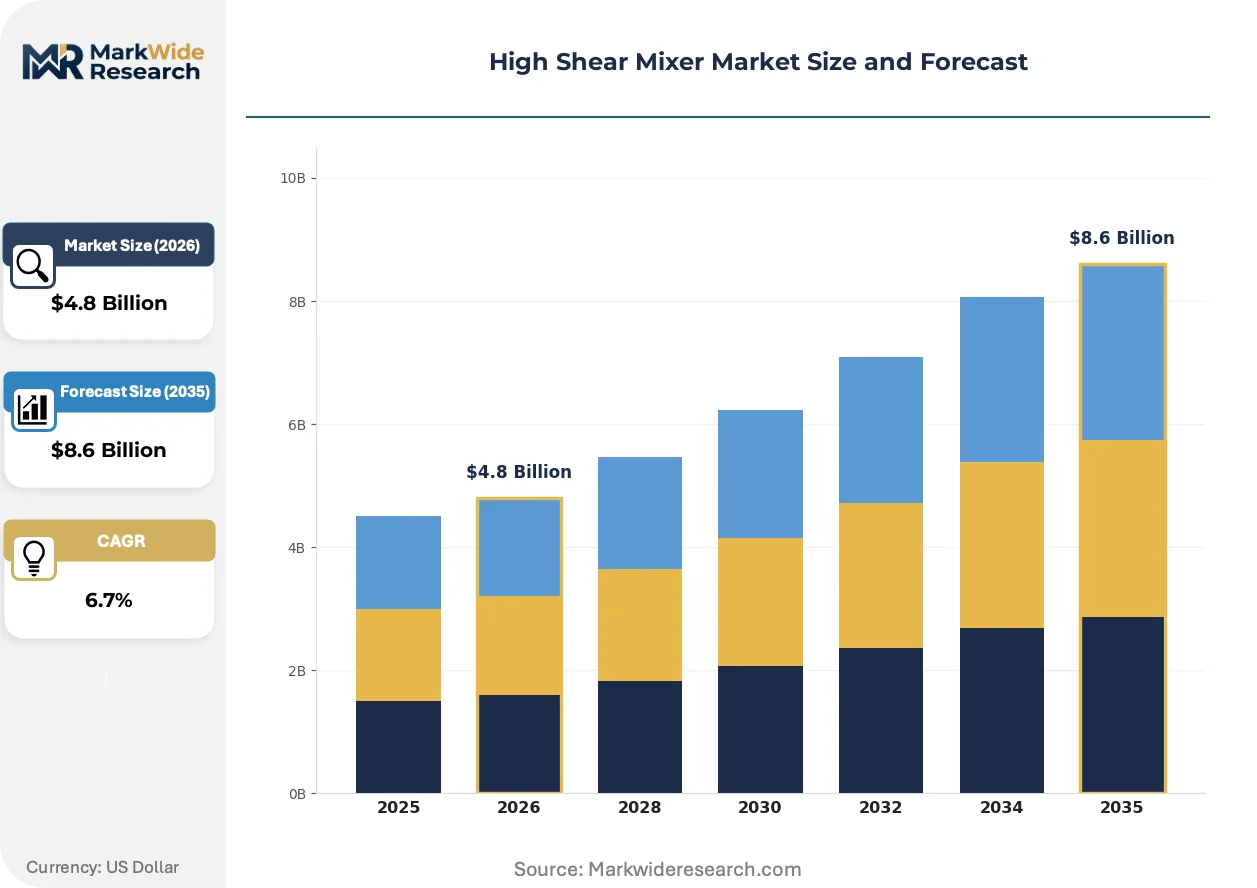
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Mixers, Inline Mixers, Laboratory Mixers, Pilot Scale Mixers Technology: Mechanical, Ultrasonic, Electromagnetic, Combination End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Application: Emulsification, Homogenization, Dispersing, Powder Mixing |
| Companies Covered | IKA, Brawn Mixer, ROSS Mixers, INOXPA, Admix, Silverson Machines Ltd., Lee Industries, Jinhu Ginhong Machinery Co., Ltd, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Shear Mixer Market Shifts & Advancements
Equipment architecture is fragmenting into configurable subsystems as end-users demand application-specific rotor-stator geometries without full platform replacement. Vendors are responding with standardized mounting interfaces and interchangeable workheads.
Modular skid-mounted high shear systems is modularizing pharmaceutical capital deployment by enabling phased qualification of individual unit operations rather than entire process trains. Contract manufacturers in North America and Europe are adopting this approach to preserve capital flexibility for multi-product facilities. The shift compresses project timelines from 18-month validation cycles to 6-month modular increments.
EMA Annex 15 equipment qualification requirements are tightening documentation standards for cleanability and material traceability across European biopharmaceutical supply chains. Manufacturers must now demonstrate validated cleaning protocols for all product-contact surfaces. This regulatory pressure favors vendors with dedicated cleanroom manufacturing lines and batch-level material certification.
Service contract unbundling is disrupting traditional bundled maintenance arrangements as pharmaceutical procurement teams separate spare parts, field service, and remote monitoring into distinct vendor relationships. Large-scale chemical processors in Germany and the United States are driving this disintermediation to optimize total cost of ownership. The trend elevates component suppliers with direct digital distribution channels.
High Shear Mixer Market Segmentation
High shear mixer procurement decisions hinge on process architecture, regulatory environment, and scale requirements. Buyers must reconcile batch flexibility against continuous throughput, mechanical reliability against electromagnetic efficiency, and vessel-based validation against inline qualification protocols.
Product Type:
Equipment selection pivots on production volume thresholds and changeover frequency demands across multi-product facilities.
- Batch Mixers:Vessel-mounted rotor-stator systems dominate installed base volumes in food processing and cosmetics manufacturing. German precision engineering clusters around Cologne supply integrated mixing-skid systems to global producers requiring validated cleaning protocols between product runs.
- Inline Mixers:Continuous rotor-stator architectures are gaining share fastest in pharmaceutical active ingredient processing as FDA process analytical technology guidance compresses batch timelines. These systems eliminate vessel cleaning validation cycles but require simultaneous mastery of mechanical, electrical, and process automation disciplines during commissioning.
- Laboratory Mixers:Bench-scale units enable formulation development and process parameter mapping prior to scale-up.
- Pilot Scale Mixers:Intermediate capacity systems bridge R&D and commercial manufacturing for technology transfer validation.
Batch Mixers lead on scale; Inline Mixers lead on momentum.
Technology:
Drive system selection determines seal maintenance burden, energy recovery potential, and capital deployment cycles.
- Mechanical:Traditional shaft-seal configurations retain cost advantages in mid-scale chemical applications. Quarterly seal replacement requirements in abrasive slurry processing elevate total cost of ownership versus electromagnetic alternatives.
- Electromagnetic:Magnetic bearing integration with variable frequency drives eliminates seal maintenance and enables energy recovery. Premium positioning reflects reduced downtime in aseptic pharmaceutical environments where ASME BPE qualification documentation extends capital deployment cycles.
- Ultrasonic:High-frequency cavitation systems serve niche cell lysis applications in biopharma downstream processing.
- Combination:Hybrid architectures merge rotor-stator mechanical energy with auxiliary energy inputs for specialized dispersion challenges.
Mechanical technology commands volume leadership; Electromagnetic systems are expanding most quickly in regulated pharmaceutical environments.
End User:
Industry-specific validation requirements and material traceability standards fragment procurement specifications across verticals.
- Pharmaceuticals:Aseptic processing demands dominate specification development. EMA Annex 15 equipment qualification requirements and FDA process validation guidance tighten documentation standards for cleanability and material traceability. Dedicated cleanroom manufacturing lines and batch-level material certification favor specialized vendors.
- Food & Beverage:Sanitary design standards and rapid changeover capabilities drive equipment selection. Dairy and beverage producers integrate high shear modules into larger process skids for continuous production lines.
- Cosmetics:Emulsion stability and particle size distribution requirements shape rotor-stator geometry preferences.
- Chemicals:Corrosion-resistant alloy specifications concentrate procurement among processors with aggressive media handling requirements.
Food & Beverage anchors volume demand; Pharmaceuticals sets the steepest expansion trajectory through continuous manufacturing mandates.
Application:
Process mechanism determines rotor-stator geometry, tip speed range, and energy input requirements.
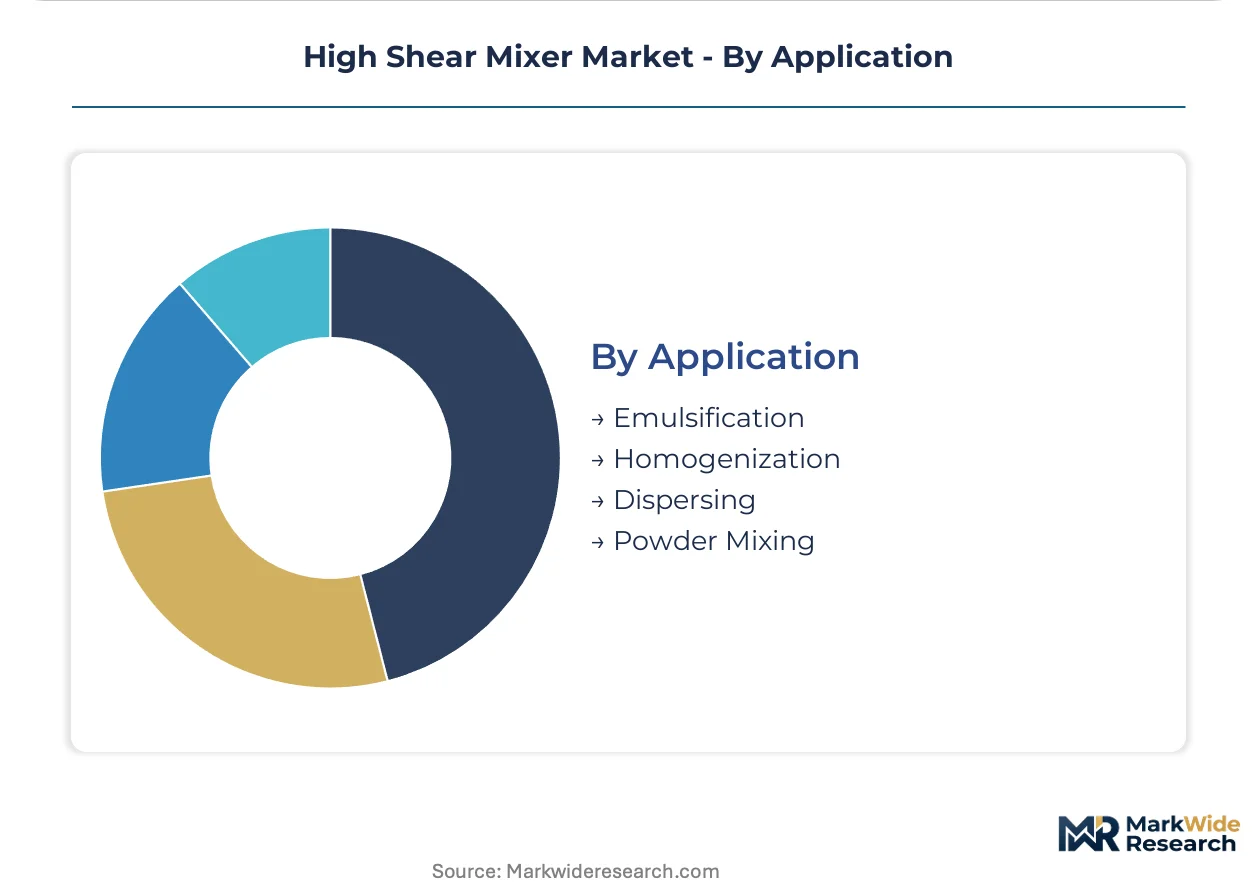
- Emulsification:Immiscible liquid phase reduction demands controlled shear intensity to achieve droplet size targets without over-processing. Cosmetics and food producers prioritize narrow particle distribution for product stability.
- Homogenization:Pressure-driven size reduction competes with mechanical shear in dairy and beverage processing. Inline systems displace valve homogenizers where energy efficiency and cleaning validation converge.
- Dispersing:Solid-liquid incorporation requires specific workhead configurations to prevent agglomeration and ensure complete wetting.
- Powder Mixing:Dry phase blending applications utilize modified rotor-stator geometries distinct from liquid processing systems.
Emulsification commands the broadest cross-industry deployment; Homogenization is climbing the fastest through continuous dairy and beverage line upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cologne-Düsseldorf precision engineering clusters anchor European supply capacity for custom alloy rotor-stator assemblies. FDA process analytical technology guidance and EMA Annex 15 equipment qualification requirements are compressing procurement timelines across pharmaceutical manufacturing hubs. Regional demand concentrates where biopharma downstream processing and continuous manufacturing mandates converge.
Germany
Pharmaceutical active ingredient producers in North Rhine-Westphalia are replacing vessel-based systems with inline rotor-stator architectures. REACH compliance through ECHA substance restrictions accelerates equipment replacement cycles in coatings and specialty chemical plants. Precision engineering clusters around Cologne and Düsseldorf supply integrated mixing-skid systems with documented cleanability protocols.
United States
Contract manufacturers across Massachusetts and North Carolina are adopting modular skid-mounted systems for multi-product facility flexibility. FDA process validation guidance on continuous manufacturing tightens qualification documentation requirements for equipment vendors. Electromagnetic drive adoption concentrates in aseptic processing environments where reduced seal maintenance offsets premium capital deployment.
India
CDSCO-aligned regulatory harmonization across Maharashtra and Gujarat is opening contract manufacturing demand for aseptic mixing skids. The country's national pharmaceutical regulator is aligning inspection protocols with FDA and EMA standards for equipment qualification. Hyderabad and Mumbai pharmaceutical corridors are sourcing corrosion-resistant rotor assemblies from domestic fabricators.
China
NMPA process analytical technology guidance is pushing active ingredient manufacturers toward continuous processing architectures. GB standards for pharmaceutical equipment are tightening material traceability requirements for product-contact surfaces. Yangtze River Delta chemical processing hubs are retrofitting legacy batch infrastructure with inline high-shear modules.
Switzerland
Swissmedic equipment qualification requirements are elevating documentation standards for cleanability validation in biopharma supply chains. Batch-level material certification is becoming mandatory for all product-contact components in precision manufacturing. Basel pharmaceutical engineering clusters are integrating high shear modules into downstream processing skids for cell culture media preparation.
High Shear Mixer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electromagnetic drive specialization and modular skid integration. The vendor base stratifies between precision engineering specialists with in-house foundry capacity and systems integrators bundling third-party components into process skids. Two strategic archetypes dominate: alloy fabrication specialists controlling rotor-stator supply chains, and automation-forward integrators validating complete mixing trains. Competitive moves center on service contract unbundling and backward integration into specialty metal feedstock.
Among German precision engineering specialists, GEA Group and IKA exemplify the systems integration archetype, anchoring positions through validated skid architectures. ROSS Mixers represents the in-house fabrication tier, with Silverson Machines Ltd. occupying the cleanroom manufacturing specialization. Jinhu Ginhong Machinery Co., Ltd. sits within the Asia-Pacific fabrication cluster serving cost-sensitive chemical processing demand.
| Leading Market Players |
|---|
| IKA |
| Brawn Mixer |
| ROSS Mixers |
| INOXPA |
| Admix |
| Silverson Machines Ltd. |
| Lee Industries |
| Jinhu Ginhong Machinery Co., Ltd |
| GEA Group |
| Others |
Supply & Pricing Matrix
FDA process analytical technology mandates for continuous manufacturing are compressing procurement timelines and forcing pharmaceutical buyers toward pre-validated skid systems with documented material traceability, which concentrates supplier pricing power among German precision engineering clusters and electromagnetic drive specialists while squeezing mid-tier mechanical vendors.
Pricing Analysis
Specialty alloy feedstock pass-through dominates cost structures, with duplex stainless steel and Hastelloy price volatility transmitting directly to rotor-stator assembly quotations. Three-tier pricing structure across premium electromagnetic, standard mechanical, and economy batch configurations reflects ASME BPE certification tiers and cleanroom manufacturing lineage. Pricing pressure stems from service contract unbundling as pharmaceutical procurement teams disaggregate spare parts, field service, and remote monitoring into discrete vendor relationships. Contract manufacturers exhibit highest price sensitivity due to capital flexibility requirements, while aseptic biopharma facilities prioritize total cost of ownership over upfront capital deployment.
Supply Chain Analysis
Regional distribution centers in Cologne, Düsseldorf, and Stuttgart anchor European hub-and-spoke patterns for custom alloy rotor-stator assemblies serving global pharmaceutical clients. Manufacturing concentration centers on Germany, Sweden, and Switzerland for corrosion-resistant specialty metals, with downstream fabrication clustering in North Rhine-Westphalia and Bavaria. Feedstock dependencies encompass duplex stainless steel from Outokumpu, nickel-based superalloys from VDM Metals, and precision bearings from SKF and Schaeffler. Single-source vulnerability concentrates in German specialty metal processors for pharmaceutical-grade material certification. Distribution runs through validated cold-chain logistics for aseptic components and standard freight for industrial chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High shear mixer procurement has shifted toward late-cycle quality specifications as continuous manufacturing mandates elevate validation documentation and material traceability above unit cost considerations, concentrating margin capture with vendors possessing captive foundry capacity and cleanroom manufacturing infrastructure.
For Market Incumbents: Anchor market position through backward integration into specialty alloy feedstock and dedicated cleanroom manufacturing lines serving EMA Annex 15 qualification requirements. Electromagnetic drive specialists threaten mechanical incumbents in aseptic pharmaceutical applications; defend through modular skid architectures that compress customer validation cycles from eighteen-month timelines to six-month phased qualifications. Capacity expansion in North Rhine-Westphalia precision engineering clusters preserves proximity advantages for custom rotor-stator geometries. For New Entrants and Emerging Players: Enter via ASEAN pharmaceutical contract manufacturing corridors where CDSCO-aligned regulatory harmonization across India, Thailand, and Vietnam has opened demand for aseptic mixing skids with FDA-equivalent qualification documentation. Cell culture media preparation for biopharma downstream processing represents the most penetrable white-space segment, requiring gentle high-shear cell lysis systems distinct from traditional chemical dispersion. Pursue electromagnetic drive convergence partnerships with magnetic bearing technology suppliers to bypass mechanical seal maintenance burdens. For Investors and Strategic Acquirers: Asymmetric upside sits with precision engineering specialists controlling in-house foundry capacity for custom alloy components, as supply concentration in German and Swedish specialty metal processors creates scarcity value for vertically integrated fabrication assets. Five-to-ten year viability favors vendors with validated skid architectures rather than standalone unit suppliers. Monitor FDA draft guidance on continuous manufacturing as the critical inflection signal for inline system adoption velocity across North American pharmaceutical manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Feedstock | Captive supply of duplex stainless steel and Hastelloy insulates margin from raw material volatility and ECHA supply restrictions. |
| Modular Skid-Mounted System Architecture | Phased qualification protocols align with pharmaceutical procurement teams seeking capital flexibility for multi-product facilities. |
| Electromagnetic Drive Technology Convergence | Magnetic bearing integration eliminates seal maintenance burdens that elevate total cost of ownership in aseptic environments. |
| Cleanroom Manufacturing Line Certification | Batch-level material traceability satisfies EMA Annex 15 equipment qualification requirements for European biopharma supply chains. |
| ASEAN Distribution Partnership Network | CDSCO-aligned regulatory harmonization across India, Thailand, and Vietnam opens contract manufacturing demand for validated mixing skids. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory affairs leads at pharmaceutical manufacturers with secondary validation from FDA guidance documents, EMA submissions, ASME BPE standards, SEC filings from listed equipment vendors, and customs trade data for rotor-stator assembly imports. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from installed base analysis and replacement cycle assumptions.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning batch versus inline architectures, mechanical versus electromagnetic drive technologies, pharmaceutical versus food versus chemical end-use industries, and regional regulatory clusters encompassing FDA, EMA, and CDSCO jurisdictions. CAGRs derived from regression analysis of capital expenditure patterns and equipment replacement cycles, incorporating process analytical technology adoption curves and REACH compliance-driven replacement demand as industry-specific forecast inputs.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time pharmaceutical capital expenditure disclosure introduce uncertainty bands around near-term demand projections. Forecasts reflect documented assumptions regarding continuous manufacturing adoption velocity and specialty alloy supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Battery Separator Materials Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Argon Knife Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Steel Processing Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Shock Mat Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Industrial Pails and Drums Market