
 Industrial Silica Sand Market | 2026-2036
Industrial Silica Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Silica Sand Market Outlook
The EPA's revised crystalline silica exposure standards is recalibrating procurement priorities across foundry and construction supply chains. U.S. Silica Holdings Inc. anchors North American production capacity through vertically integrated mine-to-terminal operations. Badger Mining Corporation leverages Wisconsin geological deposits to sustain premium Northern White sand output. Covia Holdings LLC controls extensive logistics networks that differentiate delivery reliability across basins.
Industrial silica sand consists of high-purity quartz grains with minimum SiO₂ content of 95%, processed through washing, hydraulic classification, and attrition scrubbing to achieve specific grain angularity and sphericity for industrial applications. Glass Sand dominates value generation due to stringent iron oxide tolerances below 0.02% for optical and solar-grade specifications, while Fracturing Sand captures volume leadership through mesh-size standardization for proppant permeability. Foundry Sand maintains mature demand patterns tied to automotive casting cycles, with margin pools concentrating in chemically bonded resin-coated variants.
The EPA enforces workplace exposure limits under OSHA's Respirable Crystalline Silica standard, while the EU REACH framework governs chemical safety classifications for silica imports into European manufacturing. China's GB standards and NMPA oversight shape export qualification requirements for pharmaceutical-grade silica derivatives. Stakeholders must monitor evolving silica classification thresholds under emerging occupational health frameworks to anticipate product reformulation mandates and regional supply reconfigurations.
Market Dynamics
Frac sand demand from the Permian Basin is concentrating supply chain investments around rail-to-wellhead logistics infrastructure, while OSHA's tightened crystalline silica exposure limits force processing facility retrofits that reshape regional production economics.
Growth Catalysts
- Solar glass manufacturing expansion:Photovoltaic module producers in China and India are scaling float-glass capacity that requires ultra-low iron silica feedstock, pulling premium Glass Sand volumes from Australian and Egyptian deposits.
- REACH chemical safety classifications:The EU framework's evolving silica hazard designations are accelerating substitution toward processed synthetic alternatives, creating premium pricing tiers for certified low-crystalline natural sands.
- Hydraulic fracturing intensity:Extended lateral lengths in West Texas shale formations consume 50% more proppant per well than 2018 baselines, sustaining Northern White sand demand despite regional competition from in-basin Texas mines.
Market Restraints
- Natural gas price volatility:Wet sand drying operations depend on natural gas-fired thermal processing; Henry Hub price spikes above $4/MMBtu compress margins for Wisconsin and Minnesota mine operators.
- Permian supply concentration:Three counties in West Texas control 60% of domestic frac sand rail unload capacity, creating bottlenecks when simultaneous completion crews strain last-mile trucking networks.
- Resin-coated sand substitution:Ceramic proppants from Chinese manufacturers achieve comparable crush resistance at 20% lower delivered cost for deep-basin unconventional wells exceeding 12,000 feet true vertical depth.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Production-linked incentives for domestic photovoltaic cell and module assembly are attracting glass furnace investments in Gujarat and Tamil Nadu that require imported high-purity silica.
- MEA pharmaceutical-grade silica derivatives:Saudi Arabia's SFDA and UAE's MOHAP are harmonizing excipient purity standards that favor precipitated silica from controlled-impurity natural feedstocks over synthetic alternatives.
- Digital freight matching platforms:Load-board technologies are disintermediating traditional sand broker networks, enabling direct mine-to-wellhead contracting that captures 15-20% logistics cost savings for Permian operators.
Industry Challenges
- Attrition scrubbing technician scarcity:Specialized knowledge of hydraulic classification and density separation equipment maintenance is concentrated among aging workforces in Wisconsin's Chippewa Valley mining corridor.
- ISO 9001:2015 certification timelines:Glass Sand suppliers to automotive and solar sectors face 18-24 month quality management system audits that delay market entry against incumbent certified producers.
- Legacy pneumatic conveying integration:Wet plant expansions must interface with decades-old dry silo infrastructure, creating dust control compliance gaps during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Silica Sand Market |
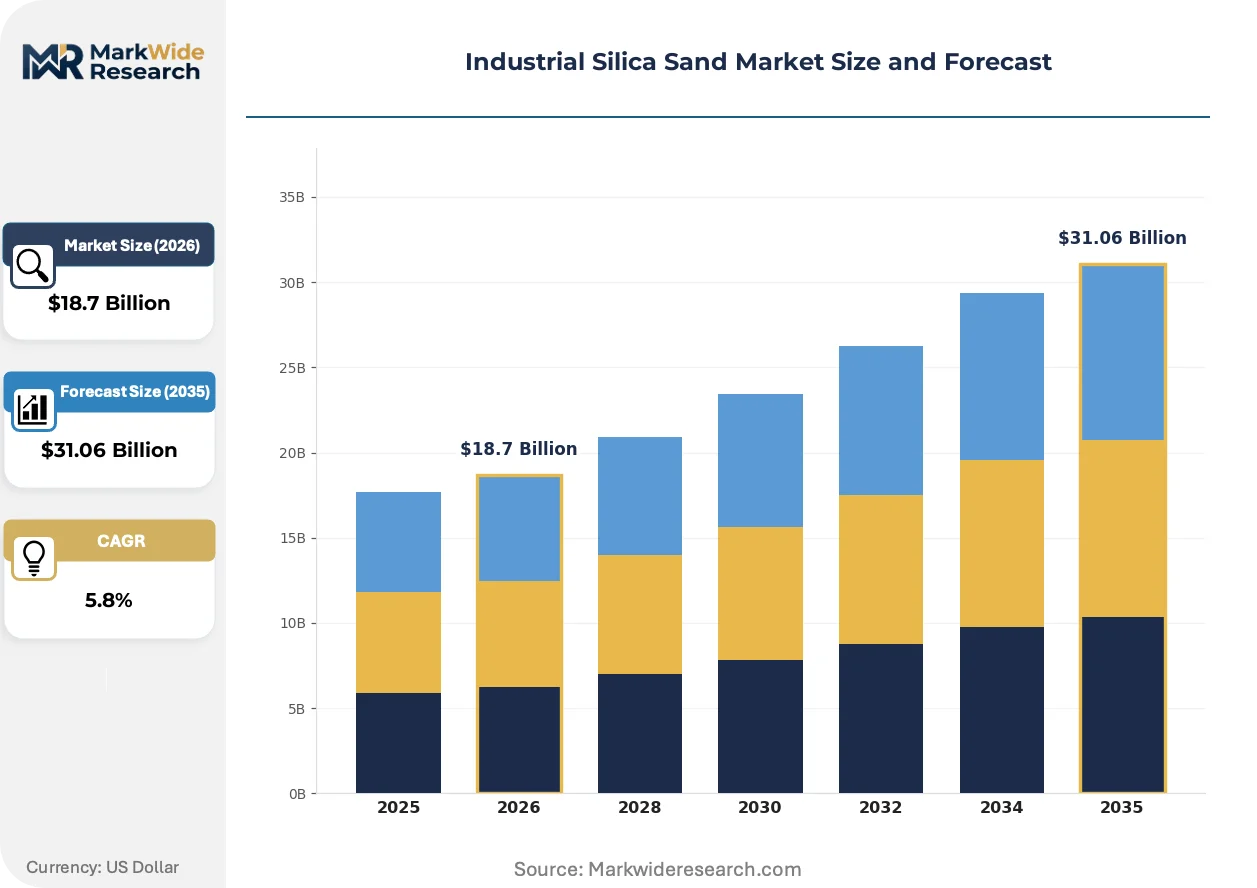
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fracturing Sand, Glass Sand, Foundry Sand, Mortar Sand Application: Construction, Oil & Gas, Foundry, Chemical Manufacturing End User: Construction Companies, Oil Producers, Foundries, Chemical Plants Distribution Channel: Direct Sales, Distributors, Retailers, E-commerce |
| Companies Covered | Hi-Crush Inc., Badger Mining Corporation, Covia Holdings LLC, Source Energy Services, Sil Industrial Minerals, U.S. Silica Holdings Inc., Mitsubishi Corporation, Quarzwerke GmbH, Sibelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Silica Sand Market Strategic Shifts
Processing technology and logistics digitization are compressing the traditional mine-to-wellhead value chain, while regulatory hazard reclassifications force product differentiation strategies that separate commodity and specialty silica tiers.
Dry screening with multi-deck high-frequency vibratory units is overtaking traditional wet washing for coarse frac sand sizing. Permian Basin operators adopting this technology reduce water consumption by 70% and achieve faster mesh-size transitions between 40/70 and 100-mesh proppant specifications. The shift is compressing capital recovery periods for mine operators from seven years to four years in water-scarce West Texas counties.
OSHA's Respirable Crystalline Silica standard is mandating engineering controls across foundry and construction supply chains that exceed previous permissible exposure limits by 50%. Processing facilities must install enclosed cabs, local exhaust ventilation, and continuous air monitoring systems that add $2-4 million per plant retrofit. Foundry sand suppliers in Ohio and Pennsylvania are responding by marketing pre-coated chemically bonded resins that minimize downstream worker exposure during mold preparation.
Direct contracting between mine operators and exploration-and-production companies is displacing traditional sand broker intermediaries that historically managed price volatility and logistics coordination. Large independents in the Delaware Basin now negotiate three-year offtake agreements with fixed rail tariffs and volume flex provisions. The disintermediation is most visible in Reeves and Loving counties, where dedicated unit-train spurs eliminate transload costs and reduce delivered sand prices by 12-18% versus broker-mediated spot purchases.
Industrial Silica Sand Market Segmentation
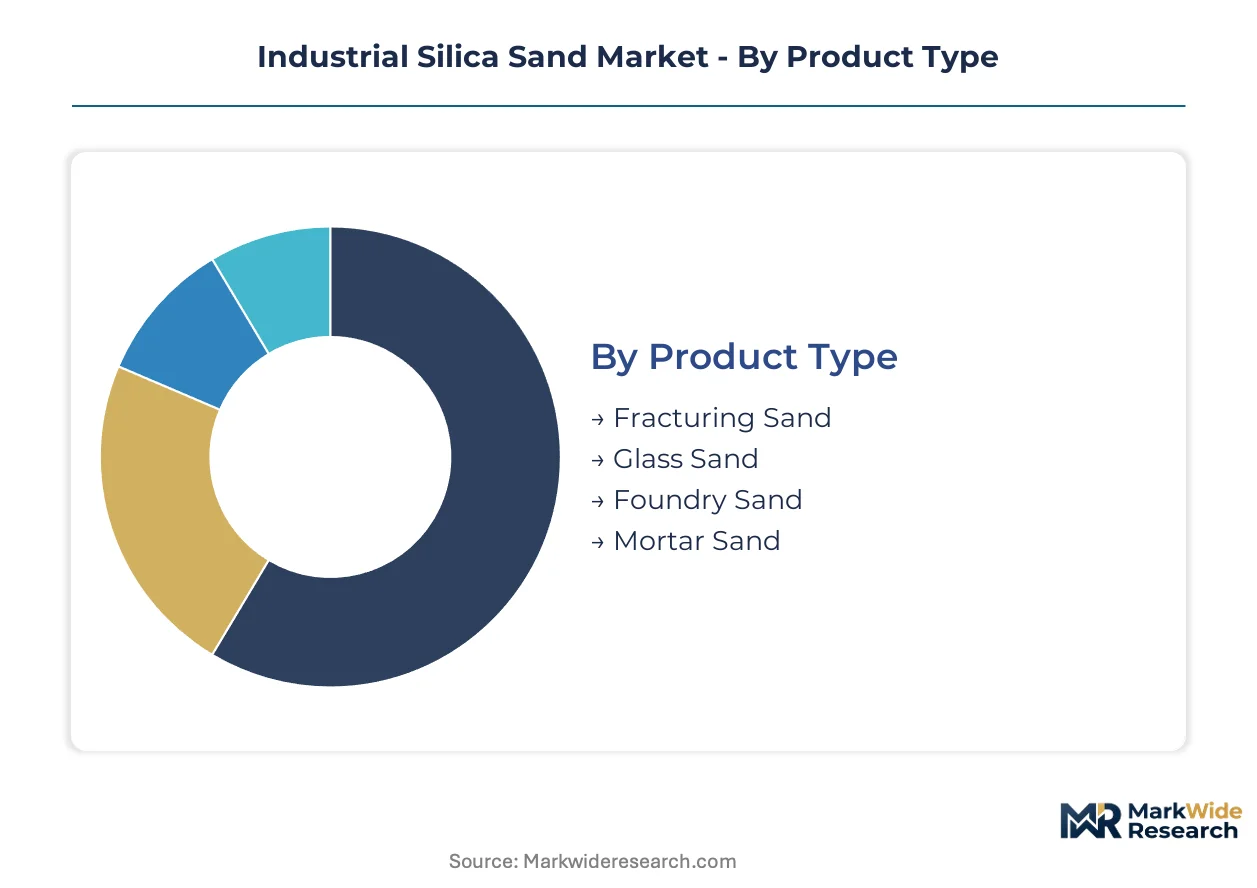
Segmentation in industrial silica sand tracks how purity thresholds, logistics intensity, and regulatory exposure fragment procurement behavior across end-use verticals. Buyers prioritize distinct performance vectors: crush resistance dominates oilfield decisions, while iron oxide tolerance governs glass furnace feedstock selection.
Product Type:
Purchase specifications diverge sharply based on whether the application demands mechanical integrity under pressure or chemical purity for optical transmission.
- Fracturing Sand:High-purity quartz grains sized to precise mesh distributions, engineered for crush resistance above 8,000 psi closure stress. Demand concentrates in the Permian Basin of West Texas, where extended lateral drilling consumes 50% more proppant per well than historical baselines.
- Glass Sand:Ultra-low iron silica with Fe₂O₃ content below 0.02%, processed through attrition scrubbing and acid leaching to achieve optical clarity. Solar panel manufacturers in China and India are scaling float-glass capacity that pulls premium volumes from Egyptian and Australian deposits.
- Foundry Sand:Chemically bonded resin-coated variants dominate automotive casting cycles, with margin pools concentrating in mold preparation applications that minimize worker silica exposure.
- Mortar Sand:Construction-grade material with moderate SiO₂ thresholds, sourced regionally to minimize transport costs for masonry and stucco applications.
Fracturing Sand leads on scale; Glass Sand leads on momentum.
Application:
Volume allocation follows energy sector drilling intensity and renewable manufacturing buildouts rather than traditional construction cycles.
- Oil & Gas:Hydraulic fracturing operations consume standardized proppant mesh sizes for permeability optimization. West Texas shale formations sustain Northern White sand demand despite regional competition from in-basin Texas mines.
- Construction:Mortar and concrete applications require locally sourced deposits with consistent grain distribution. EPA crystalline silica exposure limits are tightening workplace standards across extraction and batching operations.
- Foundry:Automotive casting demand maintains mature patterns tied to vehicle production cycles, with OSHA's Respirable Crystalline Silica standard forcing mold preparation facility retrofits.
- Chemical Manufacturing:Precipitated silica derivatives for pharmaceutical excipients require controlled-impurity natural feedstocks that meet harmonized purity standards in Saudi Arabia and the UAE.
Oil & Gas commands volume share; Chemical Manufacturing exhibits the steepest expansion trajectory.
End User:
Procurement sophistication varies from spot-market commodity purchasing to multi-year offtake agreements with embedded logistics commitments.
- Oil Producers:Large independents in the Delaware Basin negotiate three-year contracts with fixed rail tariffs and volume flex provisions, displacing traditional sand broker intermediaries.
- Construction Companies:Regional batching plants prioritize transport radius over purity specifications, sourcing within 150-mile haul distances to maintain margin.
- Foundries:Ohio and Pennsylvania operators respond to OSHA mandates by specifying pre-coated chemically bonded resins that minimize downstream worker exposure.
- Chemical Plants:Pharmaceutical-grade silica buyers in the Middle East favor precipitated material from controlled-impurity natural feedstocks over synthetic alternatives.
Oil Producers drive contract innovation; Chemical Plants concentrate premium pricing power.
Distribution Channel:
Logistics configuration determines whether intermediaries capture value or direct mine-to-wellhead contracting compresses delivered costs.
- Direct Sales:Unit-train spurs in Reeves and Loving counties eliminate transload costs and reduce delivered sand prices by 12-18% versus broker-mediated alternatives.
- Distributors:Traditional sand broker networks manage price volatility and railcar coordination, though digital freight matching platforms are disintermediating their role.
- Retailers:Bagged mortar sand for residential construction moves through building material yards with limited specification differentiation.
- E-commerce:Digital load-board technologies enable direct mine-to-wellhead contracting that captures 15-20% logistics cost savings for Permian operators.
Direct Sales anchors volume concentration; E-commerce channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial silica sand extraction originated in the Great Lakes region of North America during the early 20th century, where Wisconsin's St. Peter sandstone deposits established the benchmark for high-purity Northern White sand. Today, production geography tracks energy basins, solar manufacturing corridors, and foundry clusters across four continents.
United States
Permian Basin hydraulic fracturing consumes the majority of domestic frac sand output, with Reeves and Loving counties hosting dedicated unit-train rail spurs. OSHA enforces Respirable Crystalline Silica exposure limits that mandate $2-4 million processing plant retrofits. Wisconsin's Chippewa Valley mining corridor retains specialized attrition scrubbing expertise concentrated among aging workforces.
China
Photovoltaic glass manufacturers in Jiangsu and Anhui provinces scale float-glass capacity requiring ultra-low iron silica feedstock. NMPA oversight and GB standards govern pharmaceutical-grade silica derivative exports. The Yangtze River Delta clustering of solar panel assembly plants pulls premium Glass Sand volumes from Australian and Egyptian import sources.
India
Production-linked incentives under the PLI scheme attract glass furnace investments in Gujarat and Tamil Nadu for domestic photovoltaic cell manufacturing. BIS certification requirements shape import qualification protocols for high-purity silica. Mundra and Hazira port infrastructure supports bulk material handling for solar-grade feedstock arriving from Middle Eastern suppliers.
Germany
Automotive foundries in Baden-Württemberg and North Rhine-Westphalia specify chemically bonded resin-coated sand variants that minimize worker silica exposure. ECHA's REACH framework governs hazard classifications for silica imports into European manufacturing. The Ruhr industrial basin maintains mature demand patterns tied to vehicle production cycles.
Saudi Arabia
SFDA harmonization with UAE's MOHAP creates unified excipient purity standards favoring precipitated silica from controlled-impurity natural feedstocks. The Eastern Province industrial cities of Jubail and Yanbu host pharmaceutical manufacturing investments requiring certified low-crystalline sand inputs. Rail connectivity to Ras Al-Khair minerals processing zone supports downstream chemical derivatives production.
Industrial Silica Sand Market Competitive Environment
Capital-heavy mine operators compete with asset-light logistics coordinators across divergent margin structures. The vendor base organizes around three strategic archetypes: vertically integrated mine-to-terminal operators controlling rail and storage assets; regional deposit specialists leveraging localized geological advantages; and broker-mediated networks managing price volatility through inventory positioning. Competitive dynamics center on unit-train contracting and direct offtake negotiations that displace traditional intermediary relationships.
Within the integrated infrastructure tier, U.S. Silica Holdings Inc. exemplifies captive supply chain control spanning extraction through terminal operations. Badger Mining Corporation and Covia Holdings LLC occupy positions defined by Wisconsin geological access and logistics network scale respectively. These archetypes represent the prevailing competitive configurations as three-year fixed-tariff contracts with volume flex provisions replace spot-market intermediation.
| Leading Market Players |
|---|
| Hi-Crush Inc. |
| Badger Mining Corporation |
| Covia Holdings LLC |
| Source Energy Services |
| Sil Industrial Minerals |
| U.S. Silica Holdings Inc. |
| Mitsubishi Corporation |
| Quarzwerke GmbH |
| Sibelco |
| Others |
Value Chain & Pricing Dynamics
OSHA's Respirable Crystalline Silica standard gates both qualified supply and premium-tier pricing access, forcing processing facility retrofits that stratify operational compliance costs across mine operators. Buyers seeking certified low-exposure feedstock for foundry and glass applications must absorb elevated procurement premiums, while non-compliant suppliers face margin compression from forced capital deployment.
Pricing Analysis
Contract-based long-term offtake with embedded logistics commitments dominates frac sand transactions, displacing spot-market intermediation. Price differentiation separates Northern White sand with crush resistance certification above 8,000 psi from in-basin Texas alternatives with lower closure-stress ratings. Pricing pressure stems from ceramic proppant substitution achieving comparable mechanical performance at reduced delivered cost. Oil producers in the Delaware Basin exhibit lowest price sensitivity due to volume-flex provisions, while regional construction batching plants operate on thin transport-radius margins.
Supply Chain Analysis
India's PLI scheme and domestic-content preferences for solar manufacturing are reshaping sourcing patterns for high-purity glass sand feedstock. Geographic supply concentrates in the United States, Egypt, and Australia, with Wisconsin's St. Peter sandstone and Egyptian desert deposits anchoring premium Northern White and ultra-low iron grades respectively. Raw material processing draws from natural gas-fired thermal drying, water-intensive hydraulic classification, and specialized attrition scrubbing equipment. Single-source vulnerability runs through Permian rail-to-wellhead infrastructure concentrated in Reeves and Loving counties. Distribution runs through unit-train spurs and digital freight matching platforms that disintermediate traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial silica sand market reads as a late-cycle quality story, with solar glass manufacturing specifications tightening iron oxide tolerances below 0.02% and pulling premium volumes toward certified suppliers.
For Market Incumbents: Deploy attrition scrubbing expertise as a defensive moat against regional competition from in-basin Texas mines. U.S. Silica Holdings and Badger Mining should accelerate ISO 9001:2015 certification timelines for automotive and solar sector entry, while retrofitting enclosed cabs and local exhaust ventilation to preempt OSHA enforcement actions. Captive rail terminal assets differentiate delivery reliability against asset-light logistics coordinators. For New Entrants and Emerging Players: The 12-18% delivered cost gap between broker-mediated spot purchases and direct mine-to-wellhead contracting opens white-space for digital freight matching platforms. Target India's Mundra and Hazira port corridors for solar-grade silica import handling, where BIS certification requirements delay incumbent qualification. Pursue pharmaceutical-grade precipitated silica derivatives in Saudi Arabia's Eastern Province, where SFDA-MOHAP harmonization favors controlled-impurity natural feedstocks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional deposit specialists with Wisconsin geological access but limited downstream logistics integration. The five-to-ten year viability window favors asset-heavy mine-to-terminal operators over pure-play brokers facing disintermediation. Watch for inflection where extended lateral drilling intensity in West Texas shale formations sustains proppant consumption despite natural gas price volatility compressing wet sand drying margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rail Terminal Assets | U.S. Silica Holdings captures transload cost elimination through dedicated unit-train spurs in Permian counties. |
| Green Manufacturing Transition to Dry Screening | High-frequency vibratory units reduce water consumption 70% in water-scarce West Texas mining operations. |
| Long-term Supply Agreement with Volume Flex | Delaware Basin independents lock fixed rail tariffs against Henry Hub price spikes affecting drying economics. |
| Joint Venture for Solar Glass Feedstock Qualification | Egyptian and Australian deposit access meets India's PLI scheme domestic-content requirements for Gujarat furnaces. |
| Capacity Expansion in Resin-Coated Foundry Sand | Ohio and Pennsylvania mold preparation facilities specify pre-coated variants minimizing OSHA exposure liability. |
Study Parameters
Multiple input streams — executive interviews with frac sand procurement officers, technical discussions with attrition scrubbing equipment specialists, and regulatory consultations with OSHA compliance attorneys — were reconciled against secondary validation from EIA drilling productivity reports, SEC 10-K filings of listed mine operators, and BIS certification databases. Primary fieldwork captured logistics coordination practices at Permian rail terminals and Wisconsin wet plant operations. Bottom-up volume modeling across mesh-size specifications and top-down value aggregation through end-use verticals enabled triangulation.
Historical production capacity deployment patterns were cross-referenced against panel input from glass furnace engineers and foundry sand buyers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, application vertical, end-user procurement sophistication, and distribution channel configuration. CAGRs were derived from slope analysis of annual volume trajectories, with specific inputs from hydraulic fracturing intensity metrics and photovoltaic glass capacity buildouts in China and India.
Caveats apply where natural gas price volatility, ceramic proppant substitution rates, or REACH hazard reclassification could materially shift the outlook for premium sand tiers. Forecasts embed assumptions regarding OSHA enforcement timelines and solar manufacturing incentive durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Welding Consumables Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Argon Knife Market
Industrial Materials
Mineral Wool Market
Industrial Materials
Conveyor Belt Materials Market