
 Wedge Wire Screen Market | 2026-2036
Wedge Wire Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Wedge Wire Screen Market Outlook
Skilled welder availability in precision stainless fabrication is unwinding capacity expansion plans across the sector. Hendrick Screen leverages its deep vertical integration in profile wire drawing to sustain margin stability. GKD Group anchors European supply through captive German production. Multotec competes in African mining applications with localized assembly capabilities.
Wedge wire screen comprises a surface of V-shaped profile wires welded onto support rods at precise spacing, typically manufactured in slot openings from 25 microns upward for controlled particle retention. The structure delivers high open-area ratios with minimal pressure drop across filtration and separation duties. Tubular screen configurations dominate oil and gas downhole completions where collapse resistance determines field reliability. Flat screen formats lead mining tailings dewatering due to structural load capacity. Profile wire screen variants capture premium positioning in food-grade and pharmaceutical separation where surface finish and traceability matter.
EPA effluent limitation guidelines and ASME boiler and pressure vessel codes shape product certification requirements in the United States. ECHA REACH restrictions on nickel alloy compositions affect raw material sourcing for European manufacturers. China's GB standards for water treatment equipment and India's BIS certification for filtration products govern market access across Asia. Stakeholders must monitor evolving PFAS filtration mandates and alloy substitution timelines to align R&D priorities with regulatory trajectories.
Market Dynamics
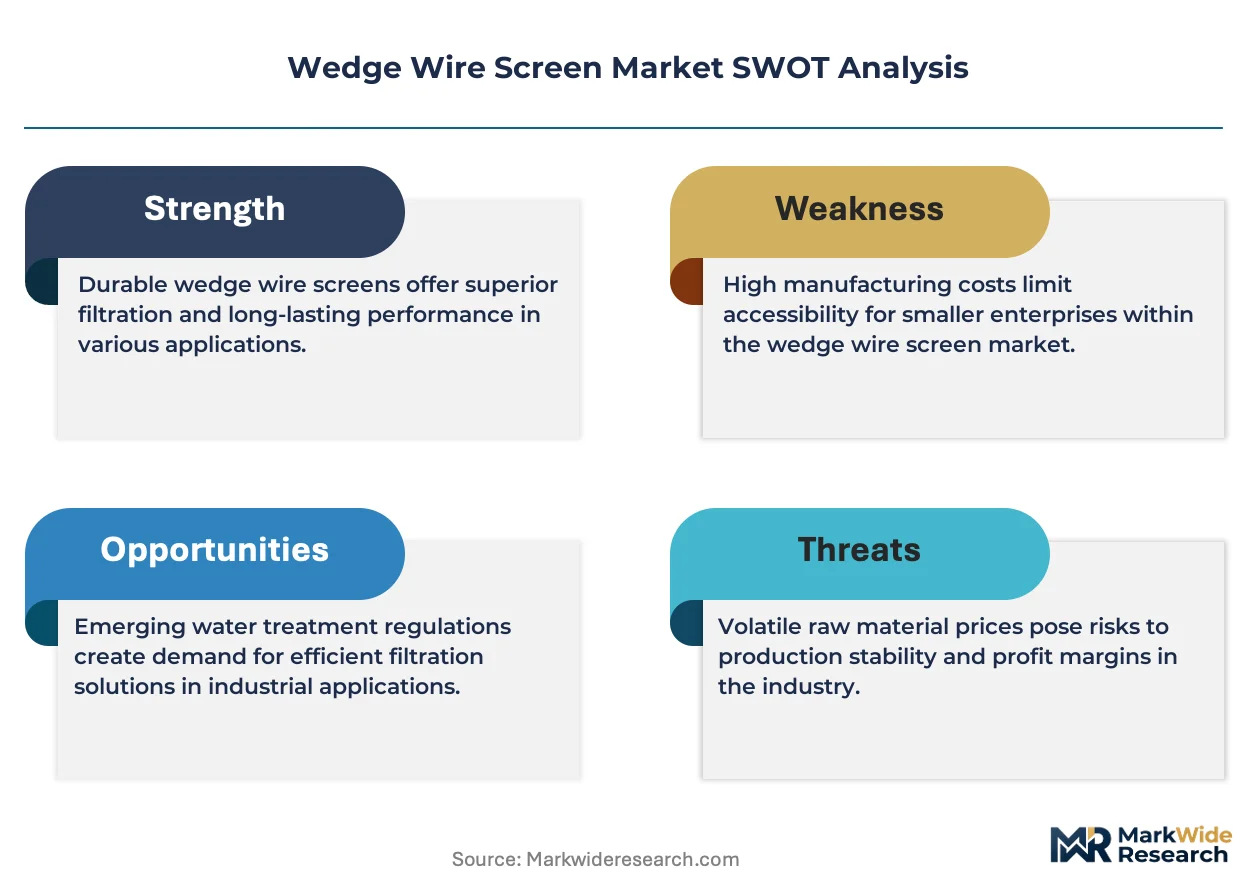
Skilled welder scarcity in precision stainless fabrication is compressing capacity expansion timelines across the sector, forcing manufacturers to prioritize automation or captive skill development over geographic diversification.
Growth Catalysts
- EPA effluent limitation guidelines:Municipal water treatment utilities in the United States are accelerating infrastructure replacement cycles to meet tightened discharge standards, directly lifting specification-grade screen orders.
- Industrial wastewater treatment:German chemical and pharmaceutical clusters sustain elevated capital expenditure on zero-liquid-discharge systems, anchoring European demand for high-slot-accuracy profiles.
- Downhole collapse resistance:Oil and gas completions in deepwater basins require tubular wedge wire configurations with enhanced structural integrity, pulling premium alloy specifications.
Market Restraints
- Nickel alloy cost volatility:ECHA REACH restrictions on nickel-containing compositions constrain raw material substitution options for European fabricators, amplifying margin pressure when London Metal Exchange prices spike.
- Profile wire supply concentration:Captive drawing capabilities cluster among a handful of vertically integrated specialists, limiting second-source availability for precision V-wire geometries.
- Slot tolerance limitations:Conventional welding automation struggles to hold sub-50-micron slot consistency at production scale, capping addressable market share in pharmaceutical sterile filtration.
Strategic Opportunities
- PFAS filtration mandates:Emerging state-level requirements for per- and polyfluoroalkyl substance removal in the United States are creating specification pull for specialized surface treatments and enhanced open-area designs.
- Food-grade traceability convergence:Integration of laser-etched serialization with profile wire manufacturing is enabling pharmaceutical and dairy processors to satisfy batch-record requirements without secondary handling.
- India BIS certification expansion:Water treatment equipment standards under India's Bureau of Indian Standards are tightening import compliance, creating localized assembly partnerships as a market entry mechanism.
Industry Challenges
- Precision TIG welding talent scarcity:The specialized skill set for orbital welding of profile wire to support rods is aging out of the workforce faster than training pipelines replenish capacity.
- Multi-jurisdictional certification timelines:Simultaneous pursuit of ASME pressure vessel codes, EPA filtration validation, and EU pressure equipment directives extends product qualification cycles by twelve to eighteen months.
- Legacy system integration friction:Retrofitting wedge wire screens into existing municipal headworks requires custom flange adaptations that erode standardization economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wedge Wire Screen Market |
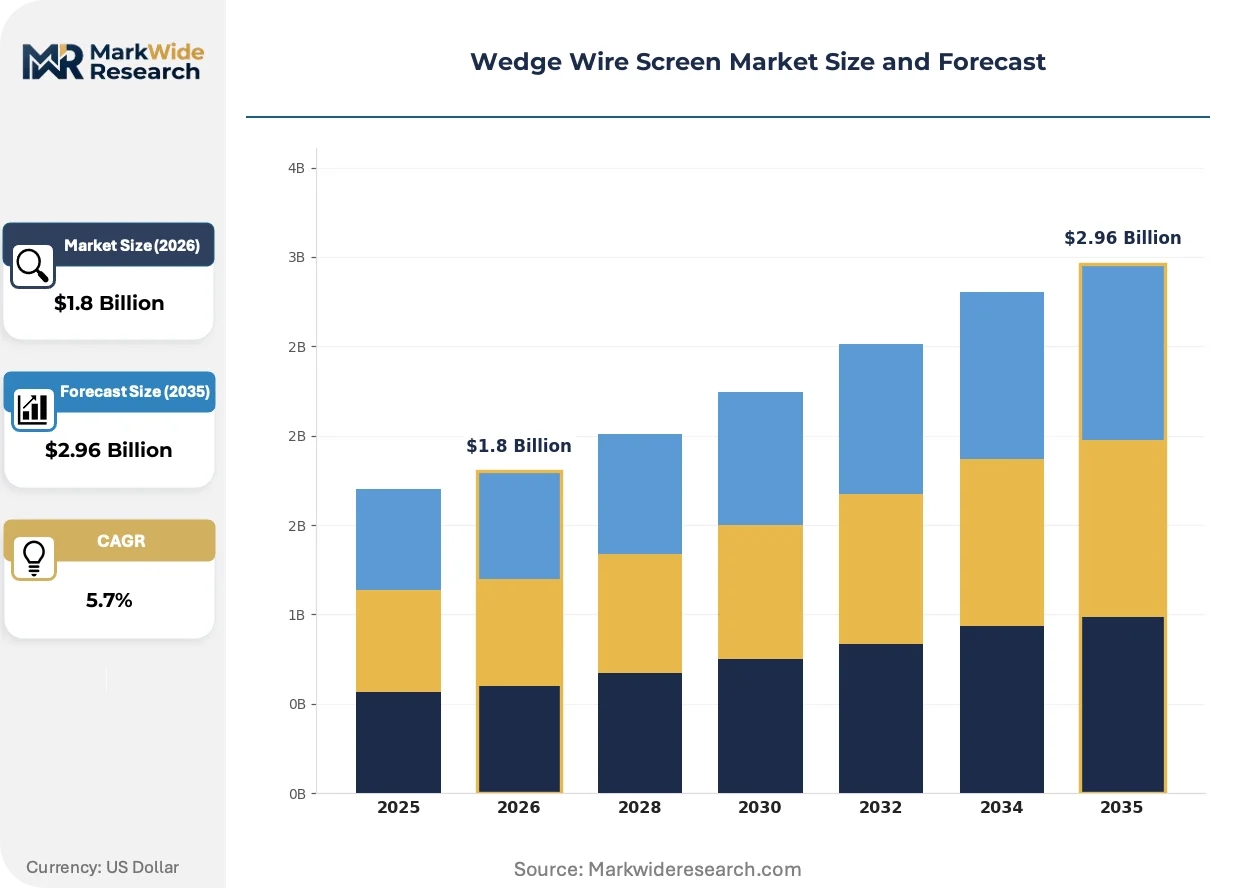
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Screen, Welded Screen, Profile Wire Screen, Tubular Screen End User: Water Treatment, Oil & Gas, Mining, Agricultural Application: Filtration, Separation, Reinforcement, Support Technology: Mechanical, Hydraulic, Pneumatic, Hybrid |
| Companies Covered | ANPING COUNTY ANSHENG WIRE MESHES PRODUCT CO.,LTD., Brilliant Metals, Hendrick Screen, MAJOR, Hightop, Multotec, Wedge Tech, GKD Group, Schenck Process Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wedge Wire Screen Market Strategic Shifts
Automation in precision welding and surface finishing is compressing the traditional trade-off between slot accuracy and production throughput, while regulatory chemistry restrictions are accelerating material science experimentation.
Laser-assisted welding of profile wire to support rods is bifurcating the manufacturing base between high-automation specialists and manual fabrication shops. Municipal water treatment authorities in the Netherlands and Singapore are specifying laser-welded screens for critical headworks installations. The technology is bifurcating competitive positioning: fabricators with capital access are capturing specification-grade contracts, while manual shops retreat to repair and aftermarket segments.
REACH restrictions on nickel alloy formulations are forcing stainless steel substitution toward duplex grades and titanium-clad alternatives. European pharmaceutical separators face reformulation of their material certificates to maintain ECHA compliance. German and Swiss equipment OEMs are responding with accelerated qualification programs for super-duplex profiles in high-chloride applications.
Buyers in mining tailings dewatering are consolidating vendor relationships around full-service maintenance contracts rather than transactional screen replacement. Channel intermediaries in Australian and Chilean mineral processing hubs are losing volume to direct manufacturer engagement. This concentration is most visible in copper and iron ore operations where unplanned downtime costs exceed screen replacement economics by an order of magnitude.
Wedge Wire Screen Market Segmentation
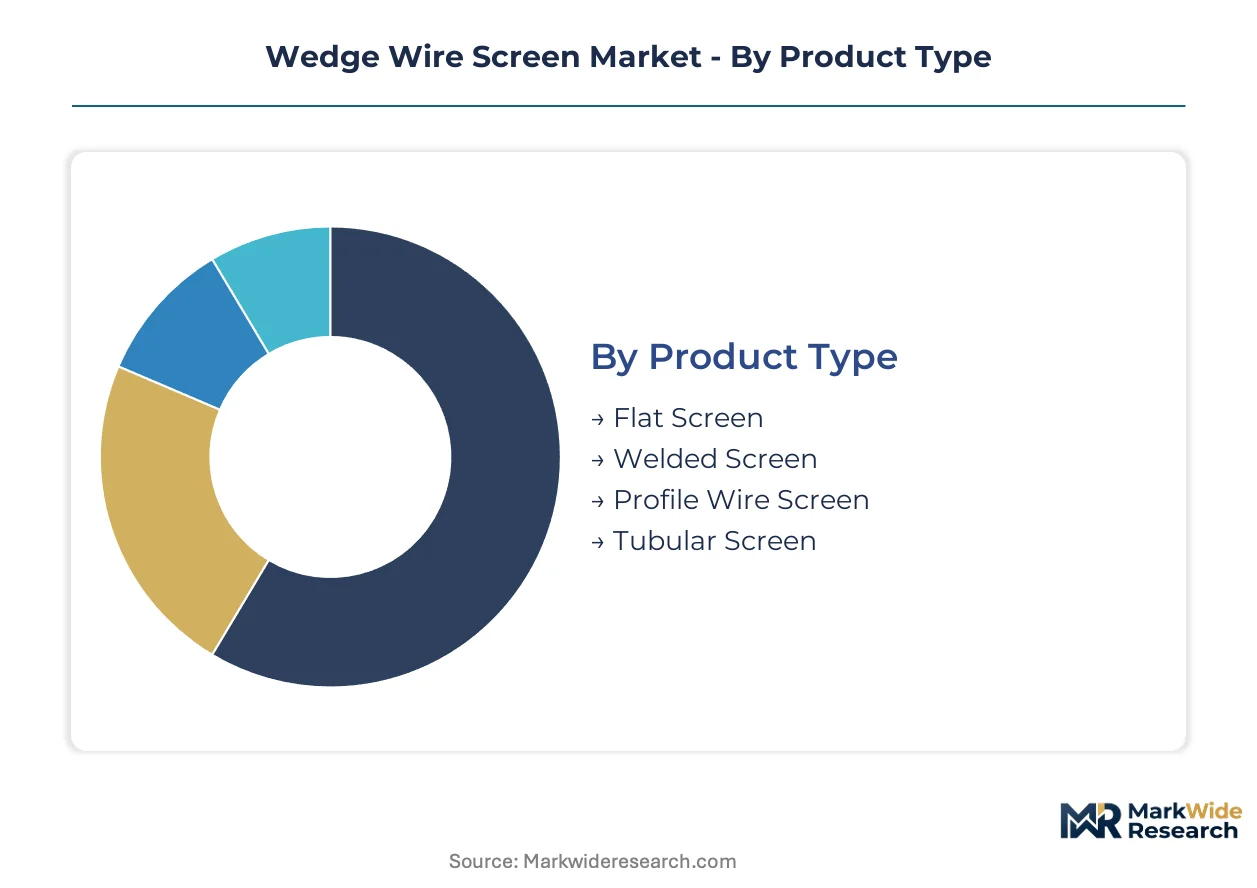
Wedge wire screen procurement channels diverge sharply by product geometry and end-use criticality. Municipal utilities favor specification-grade tubular formats through direct manufacturer engagement, while mining operators source flat screens via distributor networks with embedded maintenance contracts.
Product Type:
Channel economics split between stock-and-ship commodity formats and engineered-to-order configurations requiring application engineering support. Direct sales teams capture premium tubular contracts; flat and welded variants flow through industrial distribution.
- Tubular Screen:Cylindrical configurations with circumferential profile wire wrapping deliver collapse resistance ratings essential for downhole oil and gas completions. Deepwater basins off Brazil and West Africa specify these formats for pressure integrity at depth. Premium alloy grades and orbital welding certification requirements sustain manufacturer-direct procurement channels.
- Flat Screen:Planar wedge wire surfaces mounted on rigid frames dominate mining tailings dewatering and municipal headworks installations. Structural load capacity determines specification in Chilean copper concentrators and Australian iron ore processing hubs. Volume procurement through regional distributors competes with direct mill relationships for large fleet operators.
- Profile Wire Screen:Precision V-wire geometries with surface finish traceability serve pharmaceutical sterile filtration and dairy processing. FDA and EFSA compliance documentation sustains specialty fabricator premiums.
- Welded Screen:Field-repairable formats with manual weld accessibility capture aftermarket replacement demand across agricultural irrigation and legacy water treatment infrastructure.
Tubular configurations dominate installed base value. Flat screens are where volume expansion concentrates.
End User:
Customer sophistication tiers separate specification-driven engineering procurement from price-sensitive replacement purchasing. Capital project cycles in extractive industries contrast with operational budget constraints in municipal utilities.
- Water Treatment:Municipal utilities and industrial effluent processors drive specification-grade demand for EPA-compliant headworks and membrane bioreactor support. Dutch and Singaporean water authorities specify laser-welded formats for critical installations. Zero-liquid-discharge mandates in German chemical clusters sustain premium slot-accuracy requirements.
- Mining:Mineral processors prioritize total cost of ownership over unit screen pricing, consolidating vendor relationships around uptime guarantees. Copper and iron ore operations in Australia and Chile negotiate direct manufacturer contracts bypassing traditional distribution. Tailings dewatering duty cycles demand structural redundancy in flat screen formats.
- Oil & Gas:Downhole completion specifications require ASME pressure vessel certification and collapse resistance validation for deepwater deployment.
- Agricultural:Irrigation intake screening and livestock water systems represent price-elastic demand served through regional equipment dealers.
Water treatment commands specification premiums. Mining is expanding most quickly as fleet operators consolidate procurement.
Application:
Functional requirements determine slot tolerance, open-area ratio, and surface finish specifications. Process criticality separates pharmaceutical sterile filtration from structural support applications with redundant backup systems.
- Filtration:Particle retention applications from 25 microns upward require precise slot tolerance control and cleanability validation. PFAS removal mandates in US state regulations are pulling specialized surface treatment specifications for enhanced contaminant capture.
- Separation:Solid-liquid separation in mining tailings and food processing demands high open-area ratios with minimal pressure drop. Slot geometry optimization balances throughput against structural integrity.
- Reinforcement:Composite structure applications in civil engineering and architectural screening prioritize aesthetic finish and corrosion resistance over filtration precision.
- Support:Membrane bioreactor carrier and catalyst bed applications require uniform flow distribution with mechanical stability under cyclic loading.
Filtration dominates technical specification complexity. Separation is gaining share fastest as mining throughput requirements intensify.
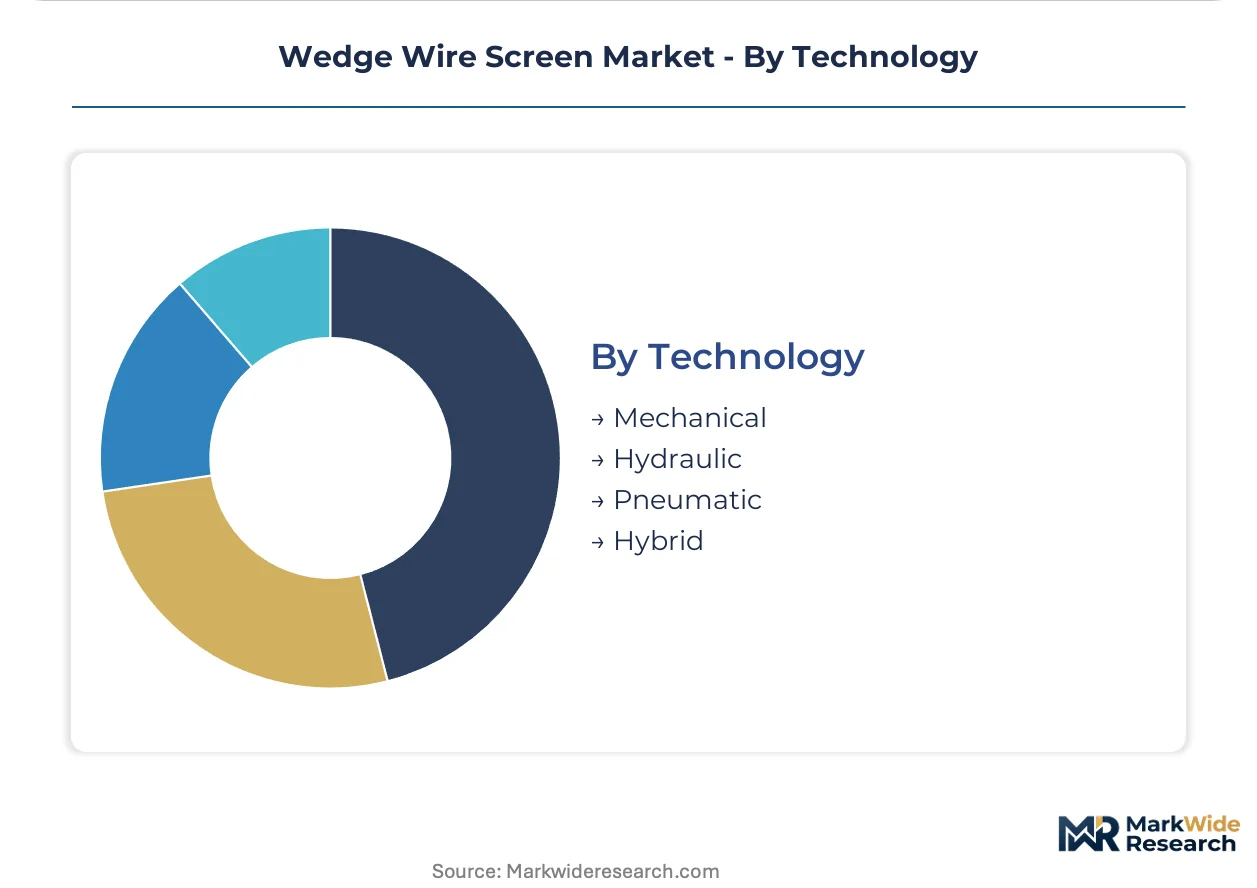
Technology:
Manufacturing process selection constrains slot tolerance capability and production scalability. Automation investment separates specification-grade producers from manual fabrication shops.
- Mechanical:Conventional resistance welding of profile wire to support rods remains volume-efficient for slot openings above 100 microns. Manual TIG welding sustains sub-50-micron capability in specialty pharmaceutical applications but faces skilled welder scarcity constraints.
- Hydraulic:Pressure-assisted forming processes enable complex curved geometries for architectural and custom industrial applications with moderate precision requirements.
- Pneumatic:Air-actuated clamping and positioning systems improve repeatability in high-volume flat screen production for mining and water treatment commodity demand.
- Hybrid:Laser-assisted welding combined with robotic handling is bifurcating competitive positioning between capital-intensive specialists and manual shops.
Mechanical welding retains installed base dominance. Hybrid processes are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany and the United States prioritize specification-grade tubular formats for industrial wastewater and downhole applications. China and India concentrate procurement in flat-screen mining and municipal water treatment segments where volume economics dominate.
United States
EPA effluent limitation guidelines are accelerating municipal infrastructure replacement cycles across Midwest and Southeast utilities. ASME boiler and pressure vessel codes govern certification requirements for oil and gas downhole completions. Houston-Gulf Coast petrochemical clusters specify premium alloy tubular screens for deepwater deployment.
Germany
Zero-liquid-discharge mandates in chemical and pharmaceutical clusters sustain elevated capital expenditure on precision slot-accuracy profiles. ECHA REACH restrictions on nickel alloy compositions constrain raw material sourcing options for fabricators. Rhine-Ruhr industrial corridor anchors European demand for high-specification wastewater treatment systems.
China
GB standards for water treatment equipment govern domestic procurement and import compliance for municipal utilities. Mining tailings dewatering operations in Inner Mongolia and Shanxi provinces drive flat-screen volume demand. Yangtze River Delta manufacturing hubs are localizing precision welding automation for specification-grade production.
India
Bureau of Indian Standards certification tightening is creating localized assembly partnerships as market entry mechanisms for international suppliers. Agricultural irrigation and municipal water treatment represent price-elastic demand growth vectors. Gujarat and Maharashtra industrial corridors concentrate pharmaceutical and chemical processing installations requiring traceable surface finishes.
Australia
Copper and iron ore operations in Western Australia and Queensland negotiate direct manufacturer contracts bypassing traditional distribution channels. Unplanned downtime costs exceeding screen replacement economics by an order of magnitude are consolidating vendor relationships around uptime guarantees. Perth and Brisbane mineral processing hubs anchor Asia-Pacific mining demand.
Wedge Wire Screen Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in wedge wire screen manufacturing. The upper tier commands premium positioning through captive profile wire drawing capabilities and orbital welding certification. Mid-scale fabricators compete on geographic proximity and aftermarket service density. The dominant competitive moves are backward integration into raw material supply and automation investment to offset skilled welder scarcity.
Among German fabricators, Schenck Process Holding GmbH and GKD Group occupy positions reflecting deep European industrial heritage. Hendrick Screen exemplifies North American vertical integration through its profile wire drawing operations. Multotec anchors African and Australian mining applications with localized assembly presence. These three represent distinct archetypes: European precision engineering, North American integrated manufacturing, and emerging-market regional adaptation.
| Leading Market Players |
|---|
| ANPING COUNTY ANSHENG WIRE MESHES PRODUCT CO.,LTD. |
| Brilliant Metals |
| Hendrick Screen |
| MAJOR |
| Hightop |
| Multotec |
| Wedge Tech |
| GKD Group |
| Schenck Process Holding GmbH |
| Others |
Value Chain & Pricing Dynamics
Scale economies in precision profile wire drawing cluster among vertically integrated specialists in Germany and the United States, compressing price floors for commodity formats while sustaining premium tiers for specification-grade tubular configurations. This concentration amplifies pricing power for ASME-certified producers while forcing mid-scale fabricators toward aftermarket service bundling to defend margin structures.
Pricing Analysis
Contract-based long-term offtake agreements dominate municipal water treatment procurement, with spot purchasing limited to emergency replacement inventory. Price differentiation rests on ASME pressure vessel certification tier and orbital welding traceability documentation, with EPA-compliant specification grades commanding substantial premiums over BIS-certified economy imports. Cost compression in standard flat-screen formats is intensifying as Chinese manufacturers expand GB-certified production capacity. Mining fleet operators exhibit lowest price sensitivity due to uptime guarantee requirements, while agricultural irrigation dealers remain most responsive to unit cost variations.
Supply Chain Analysis
Strategic stockpiling of nickel alloy feedstock prevails among European fabricators confronting ECHA REACH restriction timelines, while just-in-time raw material flows sustain North American operations with shorter regulatory lead times. Captive profile wire production concentrates in Germany, the United States, and China, with downstream fabrication drawing from stainless steel rod mills in India and Japan. Single-source vulnerability in precision V-wire geometries amplifies disruption risk when London Metal Exchange prices spike. Distribution runs through manufacturer-direct channels for oil and gas completions, with industrial distributors capturing mining and municipal replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wedge wire screen market constitutes a defensive-moat opportunity anchored in regulatory entrenchment: ASME and EPA certification timelines create eighteen-month qualification barriers that protect incumbent positioning against rapid competitive displacement.
For Market Incumbents: Shield specification-grade positioning through accelerated laser-welding automation investment to offset precision TIG welder scarcity, while deepening captive profile wire supply to reduce nickel alloy cost volatility exposure. Prioritize orbital welding certification maintenance as emerging Chinese competitors challenge mid-tier flat-screen segments. For New Entrants and Emerging Players: Differentiate on PFAS filtration surface treatment specialization to capture emerging state-level mandate pull in United States municipal markets, where incumbent R&D pipelines lag regulatory acceleration. Target India's BIS certification expansion through localized assembly partnerships in Gujarat pharmaceutical corridors, leveraging traceability documentation gaps among established suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mining full-service maintenance contract providers, where unplanned downtime economics sustain decade-long vendor relationships. Acquisition focus should center on German precision fabricators with ECHA-compliant material certificate libraries and established Rhine-Ruhr chemical cluster relationships. Watch for nickel alloy substitution timeline acceleration as the signal warranting portfolio rebalancing toward duplex-grade specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Welding Automation Investment | ASME-certified fabricators compress slot tolerance capability gaps against manual competitors. |
| Captive Profile Wire Drawing Expansion | Upstream control over V-wire geometry reduces raw material substitution risk under REACH restrictions. |
| PFAS Surface Treatment Qualification | EPA state mandate alignment creates specification pull in municipal headworks replacement cycles. |
| India BIS Localized Assembly Partnership | Import compliance tightening favors regional production presence in pharmaceutical processing hubs. |
| Mining Full-Service Maintenance Contract Consolidation | Uptime guarantee bundling displaces transactional distributor relationships in Australian copper operations. |
Study Parameters
Initial hypotheses were tested against primary input from municipal water treatment procurement managers, oil and gas completion engineers, mining maintenance directors, and precision fabrication plant managers, then refined through secondary validation against EPA effluent guideline filings, ASME boiler and pressure vessel code documentation, ECHA REACH restriction updates, and London Metal Exchange nickel price series. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the analysis window.
Variance decomposition across product geometry, end-use criticality, and regional regulatory clusters shaped the analytical framework for volume and value projections throughout the forecast period. CAGRs were derived from segment-level demand elasticity modeling calibrated to infrastructure replacement cycle timing and capital expenditure survey data. Industry-specific inputs incorporated skilled welder pipeline demographics and laser welding technology adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or nickel alloy price stability corridors would require recalibration. Forecasts reflect documented assumptions regarding municipal infrastructure funding continuity and deepwater exploration permit issuance velocity. Revision becomes warranted when PFAS filtration mandate adoption crosses threshold penetration in United States state legislatures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Mineral Wool Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Paint Knife Market
Industrial Materials
North America Activated Carbon Market