
 Asia-Pacific Wood Based Panel Market | 2026-2036
Asia-Pacific Wood Based Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wood Based Panel Market Outlook
The Asia-Pacific wood based panel trade is recalibrating around a widening split between premium certified products for export and commodity grades serving domestic construction. EGGER Group leverages its European technical standards to anchor premium MDF supply into Australian and Japanese markets. Dare Wood-Based Panels Group Co Ltd dominates mass-volume particleboard output for China's interior fit-out sector. West Fraser Timber Co Ltd extends its BC coastal softwood fiber advantage into specialty plywood for North American re-export.
Wood based panels are engineered sheet materials manufactured from wood fibers, particles, or veneers bonded under heat and pressure with resin adhesives, typically ranging from 2.5 mm to 60 mm in thickness depending on end-use structural or decorative requirements. Hot pressing remains the dominant manufacturing technology across Asia-Pacific, though cold pressing gains traction for veneered decorative surfaces where surface fidelity commands margin premiums. Plywood retains the largest revenue pool in coastal markets with established timber access, while MDF captures faster growth in India's furniture and cabinetry channels where uniform machinability reduces downstream fabrication waste.
China's MEE enforces formaldehyde emission limits under GB standards that reshape adhesive formulation across domestic mills. Japan's JIS standards and Australia's Building Code of Australia create dual compliance hurdles for regional exporters seeking premium positioning. India's BIS certification for structural plywood governs public infrastructure procurement and limits informal supplier participation. Stakeholders must monitor how carbon accounting rules in multiple jurisdictions reshape fiber sourcing economics and mill location decisions.
Market Dynamics
China's MEE emission standards are compressing formaldehyde limits under GB protocols, forcing adhesive reformulation across domestic mills while simultaneously accelerating biomass energy recovery investments. This regulatory compression is bifurcating output between export-grade certified panels and commodity construction supply.
Growth Catalysts
- Urban furniture manufacturing corridors:India's Pune and Ahmedabad clusters absorb rising MDF volumes for cabinetry and built-in storage systems. Domestic mill capacity expansion tracks this geographic concentration.
- Dual carbon goals:China's national targets push mills toward renewable thermal energy and carbon-accounted fiber sourcing, creating compliance-driven equipment upgrade cycles.
- MEE GB standards:Stricter formaldehyde emission protocols reshape adhesive chemistry, eliminating urea-formaldehyde formulations in premium product lines.
Market Restraints
- Formaldehyde input volatility:Petrochemical-derived resin costs fluctuate with crude pricing, compressing margins on commodity particleboard and plywood grades.
- Softwood fiber concentration:British Columbia and Russian Far East supply disruptions concentrate risk for specialty plywood producers dependent on coastal softwood log access.
- Technical substitution ceiling:Cross-laminated timber and mass timber systems displace structural panel demand in mid-rise commercial construction above six stories.
Strategic Opportunities
- Vietnam and Indonesia greenfield sites:Underpenetrated Southeast Asian markets offer tariff-advantaged export positioning to Japanese and Australian buyers seeking certified supply.
- Biomass co-generation integration:Waste heat recovery systems and wood-residue power generation align with Japan's METI decarbonization incentives for industrial facilities.
- E-commerce cabinetry channels:Direct-to-installer distribution bypasses traditional wholesale layers in India's tier-two urban markets.
Industry Challenges
- Adhesive chemistry talent scarcity:Low-formaldehyde and bio-based resin formulation expertise concentrates in European and Japanese technical centers, limiting domestic R&D velocity in emerging mills.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of Japan's JIS standards, Australia's BCA compliance, and China's GB marking extends product launch cycles by 18-24 months.
- Legacy press retrofit complexity:Hot pressing lines require substantial capital redeployment to accommodate cold-press decorative surface capabilities without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wood Based Panel Market |
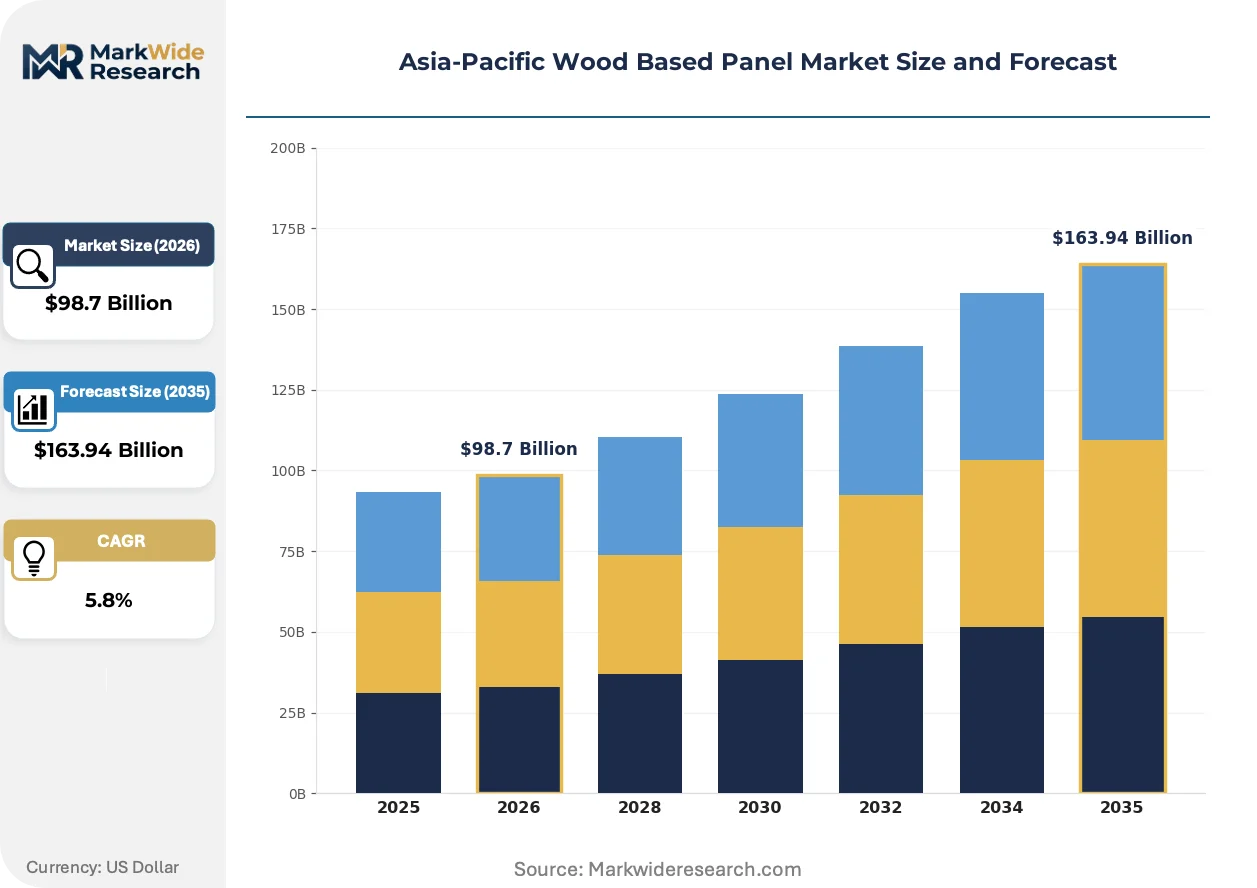
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Particleboard, MDF, Plywood, OSB End User: Furniture, Construction, Flooring, Packaging Technology: Hot Pressing, Cold Pressing, Veneering, Laminating Application: Interior Design, Automotive Interiors, Cabinetry, Soundproofing |
| Companies Covered | EGGER Group, West Fraser Timber Co Ltd, Dare Wood-Based Panels Group Co Ltd, ARAUCO, Georgia-Pacific, Daiken Corporation, Kastamonu Entegre, Nelson Pine Industries Ltd, Kronoplus Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wood Based Panel Market Strategic Shifts
Digital process control and adhesive chemistry advances are compressing the performance gap between commodity and specialty grades while regulatory stringency accelerates capital turnover in mature production bases.
Continuous press technology is consolidating market share among high-volume MDF and particleboard producers. Japanese and Australian import buyers specify continuous-pressed dimensional stability for automated furniture fabrication. This equipment shift is consolidating regional supply into fewer, larger-scale facilities capable of meeting multi-jurisdiction certification requirements simultaneously.
China's MEE enforcement of GB 18580-2017 formaldehyde limits is eliminating E2-grade panel circulation in domestic commerce. Mills face binary compliance outcomes: upgrade adhesive systems or exit premium segments. Interior fit-out contractors in Shanghai and Beijing now specify E0 or ENF-grade products exclusively, compressing allowable emission thresholds below 0.025 mg/m³.
Japanese commercial furniture buyers are consolidating procurement around certified sustainable supply chains. Trading houses and mill-direct relationships displace spot-market purchasing for large-scale hospitality and office fit-out projects. This concentration is most visible in Tokyo-Osaka corridor projects where FSC chain-of-custody documentation has become a mandatory bid qualifier.
Asia-Pacific Wood Based Panel Market Segmentation
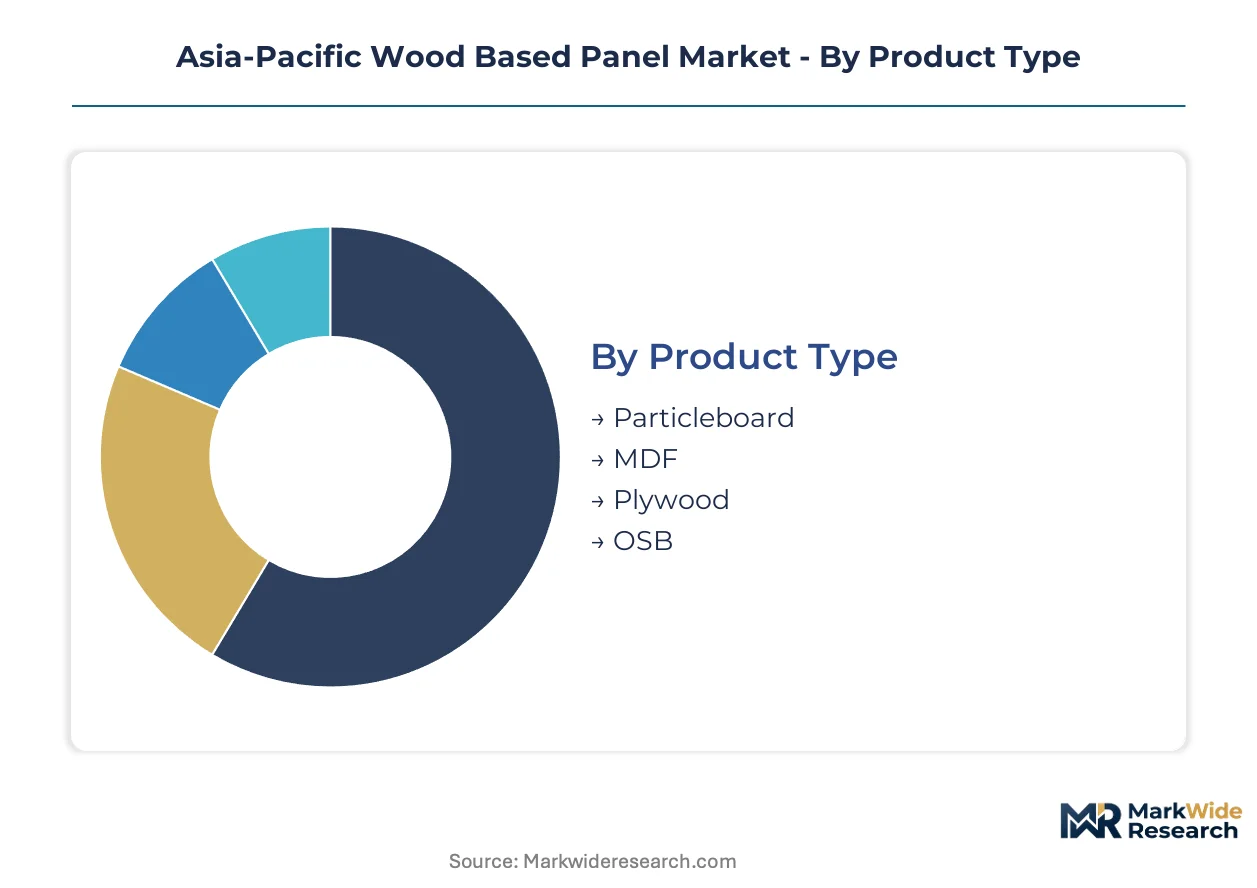
Segmentation in the Asia-Pacific wood based panel market reveals how capital deployment, regulatory compliance, and end-use specifications fragment manufacturing strategy across the region. Each dimension carries distinct margin profiles and certification burdens that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across product categories, with continuous press lines demanding the heaviest upfront investment while batch plywood operations retain lower barriers to entry.
- Particleboard:Manufactured from wood chips and resin under heat and pressure, typically 8-38 mm thickness for load-bearing applications. China's interior fit-out sector in Guangdong and Jiangsu provinces consumes mass volumes for commercial furniture and partition systems, with MEE emission standards forcing adhesive system upgrades on legacy mills.
- MDF:Fine wood fiber mat formation produces uniform density boards prized for CNC machining and edge profiling. India's Pune-Ahmedabad furniture manufacturing corridor absorbs rising volumes for modular cabinetry, driven by e-commerce distribution channels bypassing traditional wholesale layers.
- Plywood:Cross-laminated veneer construction delivers structural strength for construction and marine applications. British Columbia coastal fiber access supports specialty grades for Japanese and Australian export markets.
- OSB:Oriented strand mat technology aligns wood flakes for dimensional stability in structural sheathing. Limited adoption in Asia-Pacific outside Australian residential construction codes.
Plywood absorbs the bulk of installed capacity across coastal Southeast Asian mills; MDF is expanding most quickly in India's urban furniture corridors.
End User:
Customer concentration patterns split procurement between project-based construction contracts and recurring manufacturing orders with diverging certification requirements.
- Furniture:Automated fabrication lines in Japan and South Korea specify continuous-pressed dimensional stability for high-volume cabinetry production. JIS standards and FSC chain-of-custody documentation function as mandatory bid qualifiers for Tokyo-Osaka hospitality projects.
- Construction:Structural panel demand concentrates in mid-rise commercial and residential developments across Vietnam and Indonesia. Building Code of Australia compliance creates dual certification hurdles for regional exporters seeking premium positioning.
- Flooring:Laminate and engineered wood substrates require moisture-resistant core boards with stable thickness tolerance.
- Packaging:Low-specification industrial crating absorbs commodity-grade particleboard with minimal formaldehyde compliance burden.
Furniture commands the highest certification premiums per cubic meter; construction represents the fastest-growing trajectory driven by Southeast Asian urbanization.
Technology:
Process selection determines output flexibility, with hot pressing dominating structural grades while cold pressing captures decorative surface premiums.
- Hot Pressing:Multi-daylight hydraulic systems cure resin bonds under 150-200°C for structural integrity in load-bearing applications. Dominates particleboard and MDF output across China and Southeast Asia, though MEE emission enforcement is accelerating biomass energy recovery investments at mill sites.
- Cold Pressing:Room-temperature adhesive curing preserves veneer surface fidelity for decorative laminates and high-end furniture components. Japanese commercial buyers specify cold-pressed surfaces for visible interior applications where aesthetic consistency commands margin premiums.
- Veneering:Thin decorative wood layers bonded to substrate cores for premium architectural interiors.
- Laminating:Paper or foil overlay systems provide wear-resistant surfaces for flooring and worktop applications.
Hot pressing retains the largest installed base; cold pressing is gaining share fastest in premium decorative segments.
Application:
Use-case specifications fragment demand between visible interior surfaces requiring aesthetic grade standards and hidden structural components governed by engineering performance alone.
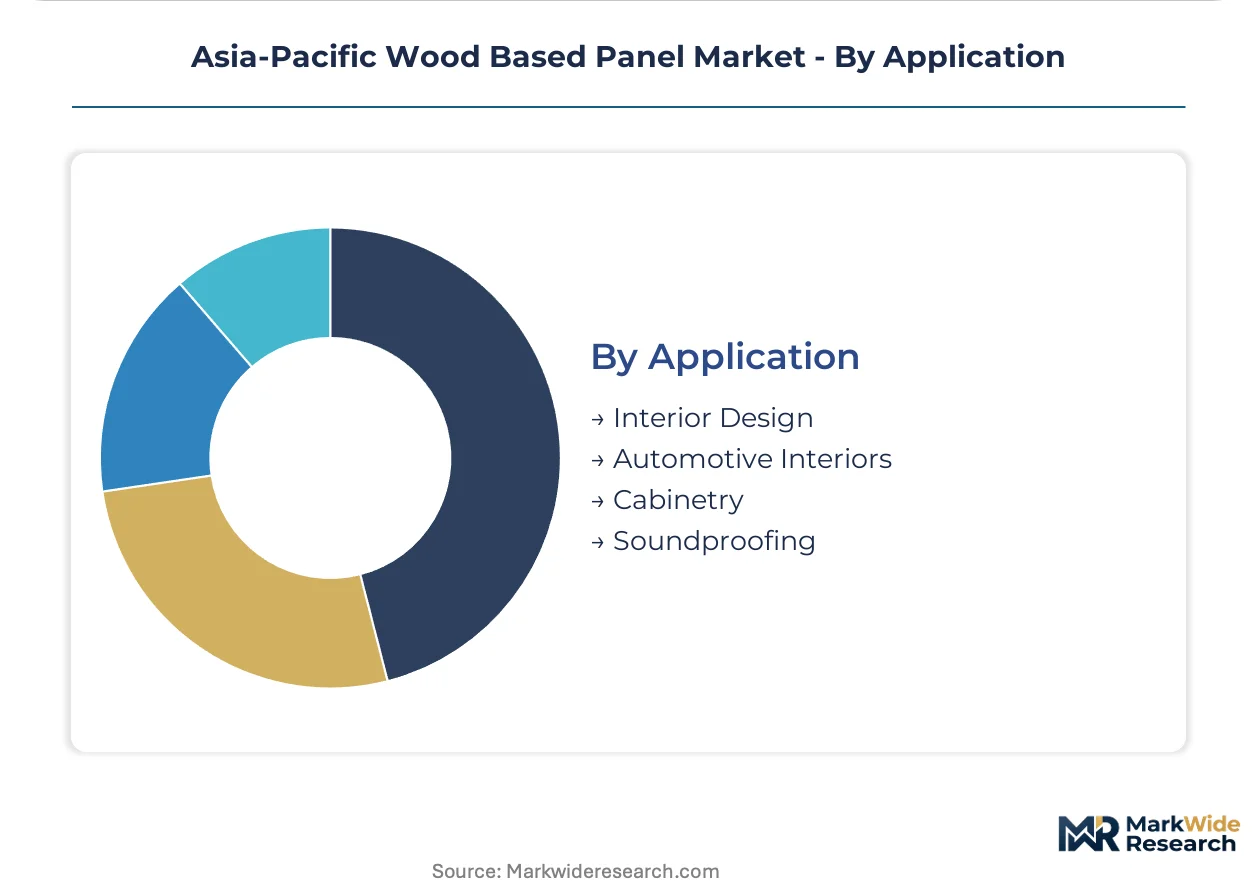
- Interior Design:Visible architectural surfaces including wall paneling, ceiling systems, and decorative partitions demand consistent grain pattern and color matching. Shanghai and Beijing contractors now specify E0 or ENF-grade products exclusively under compressed GB 18580-2017 formaldehyde limits.
- Cabinetry:Built-in storage systems and kitchen components require machinable cores with stable screw-holding capacity. India's tier-two urban markets drive direct-to-installer distribution models bypassing traditional wholesale layers.
- Automotive Interiors:Lightweight, low-emission panels for vehicle headliners and door trim panels.
- Soundproofing:Acoustic panel systems for commercial and residential noise control applications.
Interior design absorbs the bulk of certified sustainable supply; cabinetry is expanding most quickly through India's e-commerce distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune and Ahmedabad anchor India's urban furniture manufacturing corridors, absorbing rising MDF volumes for cabinetry and built-in storage systems. Southeast Asian construction hubs in Vietnam and Indonesia absorb expanding particleboard shipments for residential fit-out. Japanese and Australian import buyers specify certified sustainable supply chains for commercial hospitality projects.
China
Guangdong and Jiangsu provinces consume mass particleboard volumes for commercial furniture and partition systems. MEE enforcement of GB 18580-2017 formaldehyde limits eliminates E2-grade panel circulation, forcing adhesive system upgrades. Shanghai and Beijing contractors now specify E0 or ENF-grade products exclusively, compressing emission thresholds below 0.025 mg/m³.
India
Pune-Ahmedabad clusters drive MDF absorption for modular cabinetry through e-commerce distribution channels. BIS certification for structural plywood governs public infrastructure procurement and limits informal supplier participation. Tier-two urban markets expand direct-to-installer distribution models that bypass traditional wholesale layers.
Japan
Tokyo-Osaka corridor projects mandate FSC chain-of-custody documentation as a bid qualifier for large-scale hospitality and office fit-out. METI decarbonization incentives accelerate biomass co-generation integration at industrial facilities. JIS standards create compliance hurdles for regional exporters seeking premium positioning in commercial furniture.
Vietnam
Ho Chi Minh City industrial zones attract greenfield mill investment targeting tariff-advantaged export positioning to Japanese buyers. Underpenetrated construction markets absorb rising structural panel volumes for mid-rise residential developments. Building Code of Australia compliance requirements shape export-grade product specifications for Australian-bound shipments.
Australia
Sydney and Melbourne construction codes specify continuous-pressed dimensional stability for automated furniture fabrication. Import procurement concentrates around certified sustainable supply chains with FSC documentation. Specialty plywood demand leverages British Columbia coastal fiber access through re-export channels.
Asia-Pacific Wood Based Panel Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade tiers, with export-certified supply commanding substantial premiums over domestic construction grades. Continuous press technology consolidates supply among fewer, larger-scale facilities capable of meeting multi-jurisdiction requirements simultaneously. Three archetypes dominate: European technical-standard exporters, Chinese mass-volume producers, and coastal softwood fiber specialists. Competitive moves center on capacity expansion in Southeast Asian greenfield sites and backward integration into adhesive formulation capabilities.
Among European-anchored technical-standard exporters, EGGER Group exemplifies premium MDF positioning through European technical standards. West Fraser Timber Co Ltd occupies a position among coastal softwood fiber specialists extending BC fiber advantages. Dare Wood-Based Panels Group Co Ltd represents the mass-volume Chinese archetype dominating particleboard output for interior fit-out.
| Leading Market Players |
|---|
| EGGER Group |
| West Fraser Timber Co Ltd |
| Dare Wood-Based Panels Group Co Ltd |
| ARAUCO |
| Georgia-Pacific |
| Daiken Corporation |
| Kastamonu Entegre |
| Nelson Pine Industries Ltd |
| Kronoplus Limited |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between E0/ENF-grade export panels and E2-grade domestic commodity supply manifests in divergent pricing power and procurement network structures across Asia-Pacific. Premium certified products command substantial margin premiums through dedicated FSC chain-of-custody channels serving Japanese and Australian buyers, while commodity grades flow through spot-market procurement layers concentrated in China's interior fit-out sector.
Pricing Analysis
Value-based pricing anchored to formaldehyde emission performance and certification tier dominates Asia-Pacific wood based panel transactions. Three-tier pricing structure across premium certified, standard compliant, and economy commodity levels reflects JIS standards, GB marking, and BCA compliance burdens respectively. Cost compression in particleboard runs through petrochemical resin input volatility tied to crude pricing cycles. Project-based construction buyers exhibit highest price sensitivity, while hospitality procurement in the Tokyo-Osaka corridor shows lowest sensitivity given mandatory FSC documentation requirements.
Supply Chain Analysis
Softwood fiber supply rests on British Columbia coastal log access, Russian Far East timber concessions, and New Zealand radiata pine plantations. Formaldehyde-based resin chemistry, continuous press line equipment, and veneer peeling capacity constitute critical input dependencies. Single-source vulnerability concentrates in specialty plywood producers dependent on coastal softwood log access disrupted by trade policy shifts. Distribution runs through mill-direct relationships with Japanese trading houses and tiered wholesale layers serving India's furniture manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific wood based panel manufacturing is consolidating around multi-jurisdiction certification capability as MEE emission enforcement eliminates subscale domestic producers. Regulatory compliance capital requirements force weaker players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into low-formaldehyde adhesive formulation capabilities to secure supply chain control against European and Japanese technical centers. Expand continuous press capacity in Vietnam and Indonesia greenfield sites to capture tariff-advantaged export positioning. Cross-laminated timber substitution in mid-rise commercial construction above six stories threatens structural panel demand; defend through biomass co-generation integration aligning with METI decarbonization incentives. For New Entrants and Emerging Players: Direct-to-installer digital channels targeting India's tier-two urban furniture markets bypass entrenched wholesale layers and capture margin compression opportunities. Underpenetrated Southeast Asian construction markets in Vietnam and Indonesia offer white-space entry points for certified supply serving Australian Building Code of Australia compliance requirements. Prioritize cold-press decorative surface capabilities where aesthetic consistency commands premium positioning over commodity structural grades. For Investors and Strategic Acquirers: Re-rating potential sits with coastal softwood fiber specialists possessing integrated veneer peeling and specialty plywood finishing capacity given British Columbia supply disruption premiums. Long-term viability favors assets with simultaneous JIS, BCA, and GB certification capability across the 5-10 year projection horizon. The signal to watch is MEE enforcement intensity eliminating E2-grade circulation and accelerating mill consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Co-generation Integration | Waste heat recovery systems align with METI decarbonization incentives for Japanese industrial facilities. |
| Continuous Press Capacity Expansion | Consolidates supply among larger-scale facilities capable of meeting multi-jurisdiction certification requirements simultaneously. |
| Low-Formaldehyde Adhesive Backward Integration | Captive resin formulation reduces dependency on European and Japanese technical centers for compliance-grade chemistry. |
| Southeast Asian Greenfield Site Development | Vietnam and Indonesia locations offer tariff-advantaged export positioning to Japanese and Australian certified buyers. |
| FSC Chain-of-Custody Certification Investment | Mandatory bid qualifier for Tokyo-Osaka corridor hospitality and office fit-out procurement concentration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific wood based panel market assessment. Primary interviews with mill operations directors, adhesive formulation chemists, Japanese trading house procurement managers, and Indian furniture manufacturing corridor distributors combined with secondary validation from China MEE enforcement records, Japan JIS standard documentation, and Australia BCA compliance guidelines. Bottom-up capacity modeling across Guangdong, Jiangsu, Pune, and Ahmedabad production clusters triangulated against top-down trade flow analysis.
Data-stream reconciliation across production capacity surveys, import-export statistics, and end-use consumption estimates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry concentration, press technology configuration, and application specification grade. CAGRs were derived from elasticity-adjusted demand projections incorporating India's urban furniture corridor expansion, China's dual carbon goal compliance cycles, and Southeast Asian construction market penetration rates.
The model holds under stable MEE enforcement intensity and continued Japanese FSC procurement mandates; deviation in British Columbia fiber supply disruption severity or cross-laminated timber substitution acceleration would shift capacity expansion trajectories. A small set of named triggers—MEE GB standard revision timing, METI biomass incentive renewal, and Australian BCA structural code amendments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Metal Stamping Market
Industrial Materials
Static Mixer Market
Industrial Materials
Mineral Wool Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
Wood Protein Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Saudi Arabia Industrial Insulation Market