
 Global Cenospheres Market | 2026-2036
Global Cenospheres Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cenospheres Market Foresight
REACH compliance is consolidating the cost-of-entry calculus for European cenosphere suppliers, forcing investment in traceability systems and chemical safety documentation. CenoStar Corporation leverages its North American sourcing network to sustain consistent feedstock access despite regulatory tightening. Dennert Poraver GmbH anchors its competitive position through specialized grading capabilities that differentiate its product lines across industrial grades.
Cenospheres are hollow, spherical alumino-silicate microspheres formed during high-temperature coal combustion, typically measuring 20–500 microns in diameter with bulk densities of 0.3–0.8 g/cm³, valued primarily as lightweight fillers that reduce composite weight without sacrificing compressive strength. Fly ash cenospheres dominate volume flows due to abundant power plant sourcing, while oil well drilling applications are expanding fastest as deepwater operators specify lower-density cement systems for well integrity. Mechanical separation technology leads installed processing capacity, though air classification systems are gaining share where producers target narrow particle-size distributions for aerospace-grade specifications.
The EPA's Coal Combustion Residuals rule and REACH registration requirements are reshaping feedstock access and product certification pathways across multiple jurisdictions, with India's BIS standards adding another compliance layer for construction-grade exports. ISO 14001 environmental management certification is becoming a baseline qualification for tender participation in European and North American buyer frameworks. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which recovery and processing investments will unlock premium segment access.
Market Dynamics
The EPA's Coal Combustion Residuals rule is compressing fly ash feedstock availability for cenosphere producers, forcing processors to secure alternative sourcing networks or invest in advanced recovery systems to maintain output volumes.
Growth Catalysts
- Deepwater drilling specifications:Offshore operators in the Gulf of Mexico are mandating lower-density cement systems for well integrity, pulling cenospheres into completion fluids at accelerating rates.
- REACH registration pathways:European chemical safety documentation requirements are filtering out non-compliant suppliers, concentrating volume among certified producers with traceable supply chains.
- India's infrastructure buildout:National highway and metro projects are specifying lightweight concrete formulations, creating sustained import demand for construction-grade cenospheres.
Market Restraints
- Feedstock concentration risk:Quality cenospheres derive predominantly from specific coal combustion profiles, tying processor viability to aging US and Chinese power plant output.
- Hollow glass microsphere substitution:Synthetically produced alternatives offer tighter particle-size control for aerospace and automotive applications, eroding premium segment pricing power.
- EPA CCR rule compliance costs:Enhanced monitoring, groundwater testing, and landfill closure requirements are elevating recovery expenses for domestic fly ash processors.
Strategic Opportunities
- Brazilian construction vertical:Pre-salt offshore platform development and stadium infrastructure renewal are opening import channels for high-strength lightweight fillers.
- Carbon capture co-benefit positioning:Cenosphere recovery from flue gas streams aligns with EU Green Deal industrial decarbonization incentives, qualifying producers for green procurement tenders.
- 3D printing feedstock convergence:Binder jet and selective laser sintering systems are testing cenospheres as porosity-control agents in metal matrix composites.
Industry Challenges
- Particle characterization expertise gap:Few laboratories maintain ISO 13320-compliant laser diffraction capabilities for certifying narrow distribution batches demanded by aerospace buyers.
- Multi-jurisdiction certification timelines:Simultaneous BIS, REACH, and EPA compliance documentation creates 18-24 month product qualification cycles for export-oriented processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cenospheres Market |
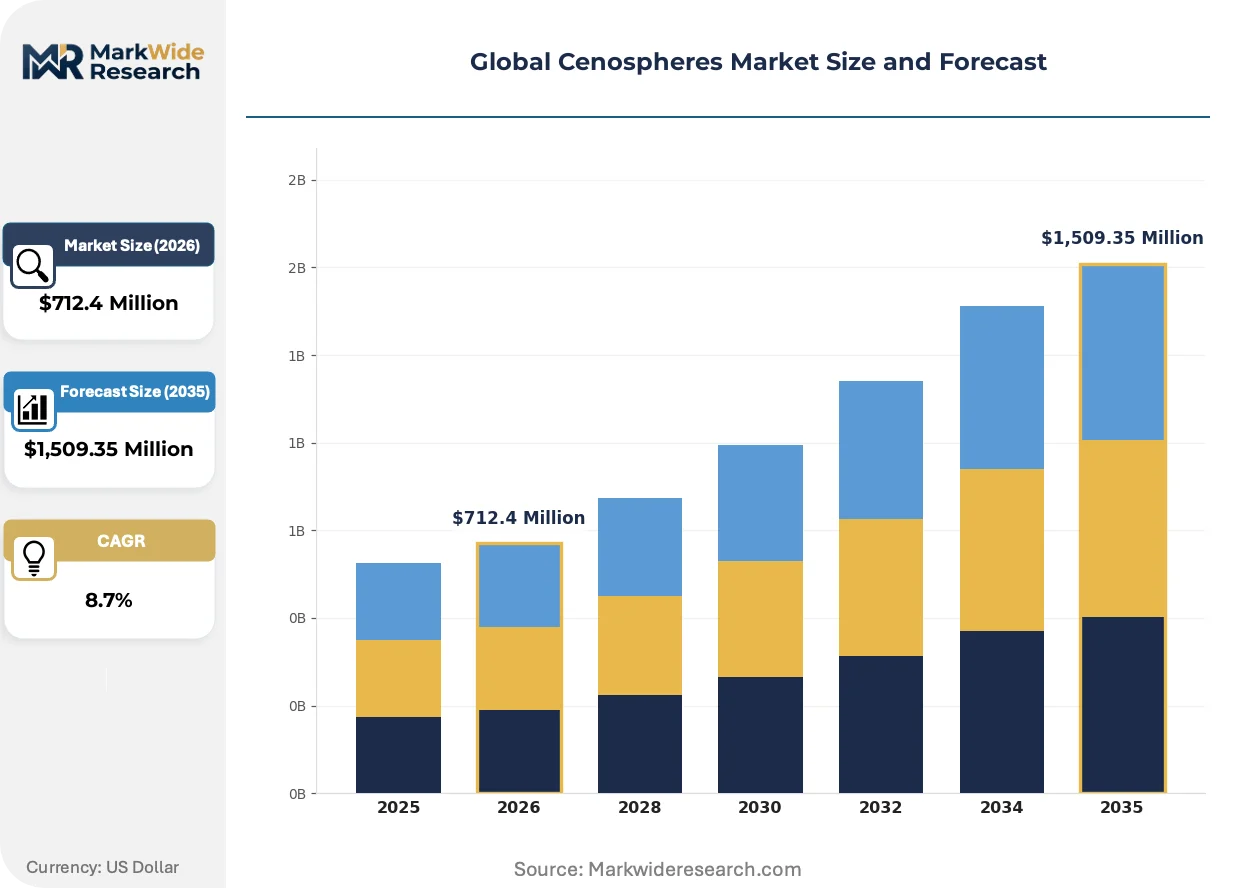
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,509.35 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash Cenospheres, Pulverized Coal Ash, Furnace Bottom Ash, Silica Fume End Use Industry: Construction, Paints & Coatings, Aerospace Manufacturing, Polymer Composites Technology: Mechanical Separation, Air Classification, Wet Processing, Magnetic Separation Application: Lightweight Fillers, Thermal Insulation, Oil Well Drilling, Abrasives |
| Companies Covered | Omya International AG, CenoStar Corporation, Microspheres SA, Dennert Poraver GmbH, Delamin Limited, LKAB Minerals AB, Cenospheres Trade & Engineering S.A., Qingdao Eastchem Inc., Ashtech India Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cenospheres Market Shifts & Advancements
Processing technology is bifurcating between high-volume mechanical separation for construction grades and precision air classification for aerospace specifications, with regulatory compliance systems becoming the decisive competitive differentiator.
Air classification systems are consolidating market share among producers targeting aerospace-grade specifications. Tier-1 composite manufacturers in Germany and Japan now require sub-20-micron cut points with sphericality indices above 0.85, specifications mechanical sieving cannot achieve. This capability compression is forcing mid-tier processors to exit premium segments or form toll-processing partnerships with specialized equipment owners.
REACH registration deadlines are tightening chemical safety documentation requirements for all alumino-silicate microsphere imports into the European Economic Area. ECHA's updated guidance on nanomaterial characterization now captures fine fractions below 100 nanometers, compelling producers to submit extended toxicity datasets. Construction-grade exporters from India and China are responding by segregating production lines to isolate nano-fractions before certification testing.
Buyer concentration among oilfield service companies is compressing procurement cycles and unbundling technical service components. Halliburton and Schlumberger now specify cenospheres through centralized global category managers rather than regional engineers, replacing relationship-based purchasing with certified vendor lists and automated reorder systems. This shift is most visible in US Permian Basin operations, where spot-market purchases have declined in favor of multi-year supply agreements with guaranteed density specifications.
Global Cenospheres Market Segmentation
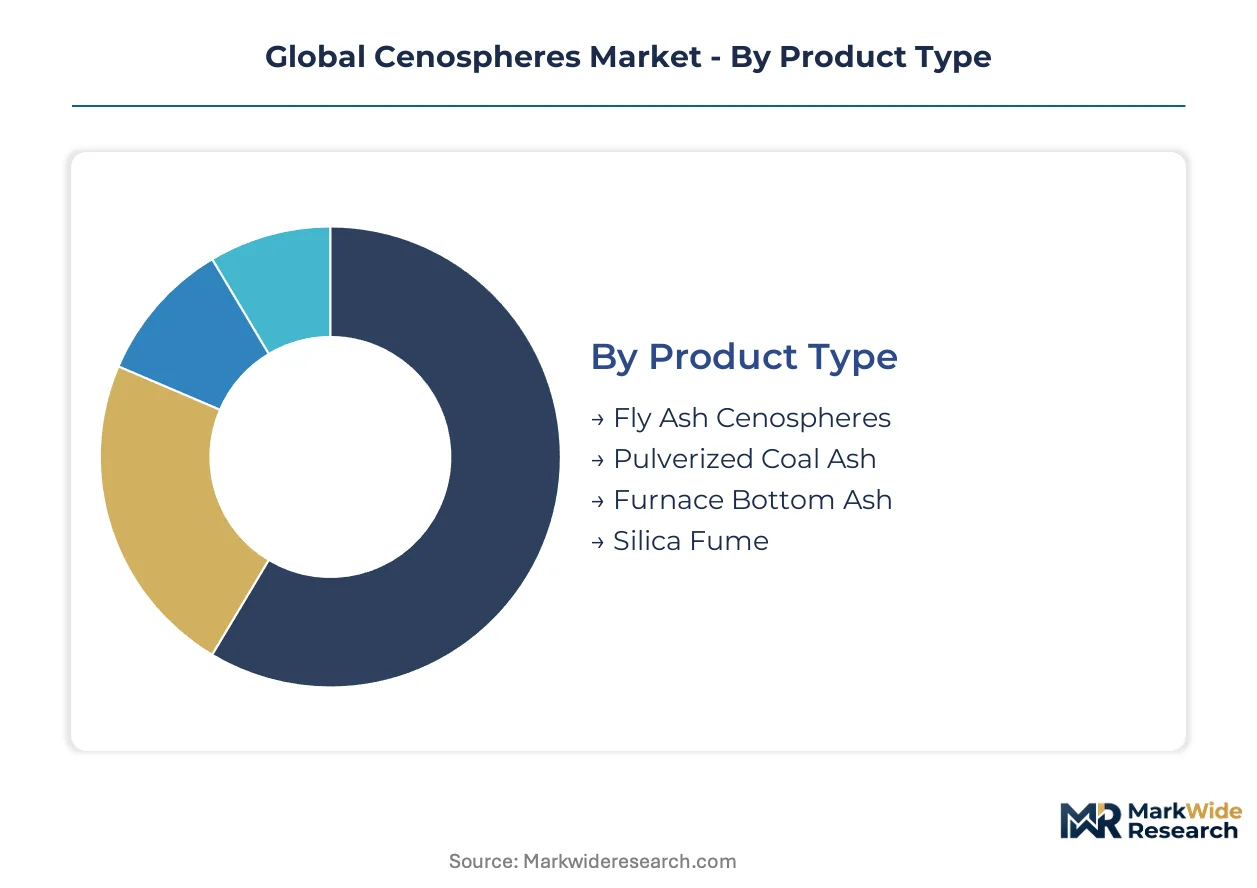
Cenospheres derive from heterogeneous coal combustion byproducts, and product quality varies sharply by feedstock source and recovery method. Segmentation clarity enables buyers to match density specifications, thermal performance requirements, and certification standards to specific supplier capabilities across construction, energy, and advanced materials sectors.
Product Type:
Supply concentration centers on power plant geography and combustion technology, with feedstock quality determining downstream processing economics and end-use accessibility.
- Fly Ash Cenospheres:Hollow alumino-silicate spheres recovered from electrostatic precipitators and baghouses at coal-fired power stations, typically 20–500 microns with bulk densities of 0.3–0.8 g/cm³. Demand concentrates in US Permian Basin oil well cementing and Indian highway construction, where operators specify consistent density reduction in lightweight concrete and completion fluids.
- Pulverized Coal Ash:Finer fractions from pulverized coal combustion with higher carbon content variability, requiring additional beneficiation for high-purity applications. Aerospace manufacturers in Germany and Japan specify this grade for syntactic foam cores, driven by stringent sphericality and particle-size distribution requirements for satellite and aircraft structures.
- Furnace Bottom Ash:Coarser, denser material from boiler slag deposits with lower cenosphere yield, primarily serving regional construction markets in China and India as cost-driven filler alternatives.
- Silica Fume:Ultrafine amorphous silicon dioxide byproduct from ferrosilicon and silicon metal production, functioning as pozzolanic additive rather than hollow microsphere, absorbed by high-performance concrete specifications in Norway and Canada.
Fly Ash Cenospheres absorb the bulk of installed capacity; Pulverized Coal Ash is expanding most quickly.
End Use Industry:
Application maturity and margin structure diverge sharply between commoditized construction absorption and specification-driven aerospace procurement.
- Construction:Lightweight concrete formulations for high-rise buildings, precast panels, and highway infrastructure leverage cenospheres to reduce dead loads and improve thermal insulation. India's National Highway Authority and metro rail corporations drive sustained import demand, with domestic processors scaling mechanical separation capacity to displace Chinese supply.
- Oil Well Drilling:Deepwater and unconventional operators specify cenospheres for low-density cement slurries maintaining wellbore integrity under high-pressure, high-temperature conditions. Gulf of Mexico operators and Brazilian pre-salt developers anchor procurement volumes, with Halliburton and Schlumberger consolidating supply agreements around guaranteed density specifications.
- Paints & Coatings:Cenospheres reduce film weight and improve sandability in automotive underbody coatings and marine protective systems, with European automotive OEMs driving REACH-compliant sourcing requirements.
- Aerospace Manufacturing:Syntactic foams and ablative materials for satellite structures, radomes, and aircraft interiors demand sub-20-micron fractions with sphericality indices above 0.85, accessible only through precision air classification systems in Germany and Japan.
Construction commands the greatest volume throughput; Oil Well Drilling is climbing the fastest as deepwater specifications tighten.
Technology:
Capital intensity and capability boundaries separate high-volume mechanical processors from precision equipment operators serving premium segments.
- Mechanical Separation:Sieving and density-based classification systems dominate installed base, processing construction-grade cenospheres at high throughput with limited particle-size control. Chinese and Indian producers rely on this technology for cost-competitive export supply to Southeast Asian and Middle Eastern construction markets.
- Air Classification:Precision elutriation and centrifugal systems achieve narrow cut points below 20 microns for aerospace and specialty coating applications. German and Japanese equipment owners command toll-processing premiums, with capability scarcity forcing mid-tier processors into partnership arrangements.
- Wet Processing:Hydrocyclone and flotation systems remove carbon and heavy mineral impurities, essential for oil well drilling grades requiring low specific gravity consistency. US Gulf Coast processors deploy this technology to meet API cementing specifications.
- Magnetic Separation:Rare-earth drum and roll separators extract ferrous contaminants from furnace bottom ash streams, enabling marginal feedstock utilization in regional construction filler markets.
Mechanical Separation retains the largest equipment footprint; Air Classification is gaining share fastest among technology upgrade cycles.
Application:
Functional performance requirements determine pricing tier and certification burden, with density-critical applications commanding systematic premiums over bulk filler uses.
- Lightweight Fillers:Primary function across construction composites, automotive parts, and consumer goods, where cenospheres displace calcium carbonate and talc to reduce part weight 15–30% without structural compromise. Indian precast concrete producers and Chinese automotive suppliers anchor volume demand.
- Thermal Insulation:Refractory linings, fireproofing sprays, and high-temperature gaskets exploit low thermal conductivity and melt resistance above 1200°C. European steel and cement kiln operators specify this grade under EU Green Deal energy efficiency mandates.
- Oil Well Drilling:Cement slurry density reduction for well integrity in deepwater, HPHT, and unconventional reservoirs, with API specification 10A compliance mandatory for operator acceptance. US Permian and Brazil pre-salt developments concentrate procurement.
- Abrasives:Surface preparation and polishing applications utilize cenospheres' controlled hardness and spherical morphology, serving automotive refinishing and electronics manufacturing in South Korea and Taiwan.
Lightweight Fillers consume the majority of production volume; Oil Well Drilling is scaling fastest as offshore project pipelines expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Andhra Pradesh concentrate Indian cenosphere processing capacity, attracting duty exemptions for export-oriented units serving Gulf and Southeast Asian construction markets.
United States
Permian Basin operators absorb expanding cenosphere volumes for lightweight cement slurries in unconventional drilling. EPA Coal Combustion Residuals rule tightens fly ash recovery protocols, elevating compliance costs for domestic processors. Houston-Gulf Coast corridor hosts wet-processing facilities serving Halliburton and Schlumberger procurement networks.
Germany
Aerospace manufacturers in Bavaria and Baden-Württemberg specify sub-20-micron cenospheres for satellite syntactic foam cores. REACH registration requirements filter non-compliant suppliers, concentrating procurement among ECHA-certified producers with traceable supply chains. Eindhoven-Düsseldorf industrial corridor anchors precision air classification capacity for narrow particle-size distributions.
India
National Highway Authority and metro rail corporations drive construction-grade cenosphere imports for lightweight concrete formulations. BIS certification mandates add compliance layers for domestic producers and exporters alike. Mundra and Visakhapatnam ports cluster import handling and mechanical separation facilities targeting precast panel manufacturers.
China
Pulverized coal combustion from aging power stations yields variable cenosphere quality for regional construction filler markets. MEE enforcement of dual carbon goals accelerates coal plant retirements, compressing long-term feedstock availability. Yangtze River Delta processors deploy high-volume mechanical separation for Southeast Asian export supply.
Brazil
Pre-salt offshore platform development pulls imported cenospheres for deepwater cementing specifications. ANVISA alignment with API standards streamlines oilfield chemical import pathways. Rio de Janeiro-São Paulo logistics corridor channels supply to Petrobras contractor networks.
Global Cenospheres Market Competitive Landscape
North American producers anchor the oilfield service tier; European specialists hold aerospace-grade positioning through precision processing capabilities. Market structure fragments across three capability bands: high-volume mechanical processors serving construction markets, precision air-classification operators commanding toll-processing premiums, and integrated power plant processors with captive fly ash access. Strategic archetypes include feedstock-secured regional processors, certification-heavy premium specialists, and toll-processing technology owners. Competitive dynamics center on backward integration into power plant partnerships and geographic expansion into Brazilian and Indian demand clusters.
Among Switzerland-based industrial mineral conglomerates, Omya International AG exemplifies scale-driven diversification across filler portfolios. CenoStar Corporation represents North American feedstock-secured positioning through power plant network relationships. Dennert Poraver GmbH anchors German precision-processing specialization, occupying a position within the premium-grade tier where narrow particle-size capabilities command systematic pricing premiums. These three archetypes illustrate how geographic origin and company structure correlate with strategic positioning: conglomerate breadth, regional feedstock control, and technology-intensive specialization each capture distinct margin pools.
| Leading Market Players |
|---|
| Omya International AG |
| CenoStar Corporation |
| Microspheres SA |
| Dennert Poraver GmbH |
| Delamin Limited |
| LKAB Minerals AB |
| Cenospheres Trade & Engineering S.A. |
| Qingdao Eastchem Inc. |
| Ashtech India Pvt Ltd |
| Others |
Supply & Pricing Matrix
Aerospace-grade certification tiers command systematic premiums over construction-grade commodity supply, with sub-20-micron sphericality specifications creating pricing power for German and Japanese precision processors while Indian and Chinese mechanical separation operators compete on volume discounts. This performance gap feeds directly into supply chain configuration: premium tiers require air classification equipment ownership and REACH documentation systems that commodity players cannot replicate, compressing procurement options for Halliburton and satellite manufacturers into qualified vendor lists with 18-24 month qualification cycles.
Pricing Analysis
Short lead-time premiums separate spot-market construction-grade transactions from multi-year aerospace offtake agreements with guaranteed density specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence: REACH-registered aerospace grades capture margin premiums, API-compliant oil well grades occupy mid-tier positioning, and BIS-construction grades face cost compression from Chinese import competition. Price differentiation hinges on sphericality index certification and particle-size distribution precision. Margins are tightening in construction tiers due to feedstock scarcity from EPA Coal Combustion Residuals compliance costs. Oilfield service buyers exhibit lowest price sensitivity given well integrity liability exposure; precast concrete producers in India demonstrate highest sensitivity with spot-market procurement dominance.
Supply Chain Analysis
REACH and BIS qualification gating concentrates supply chain access among certified processors with traceable power plant feedstock networks. Geographic concentration centers on the United States, India, and China: US Gulf Coast wet-processing facilities serve oilfield service procurement; Indian mechanical separation capacity feeds domestic infrastructure and Gulf export markets; Chinese processors anchor Southeast Asian construction supply. Raw material dependencies include coal combustion fly ash from aging power stations, rare-earth magnetic separation media, and hydrocyclone flotation reagents for carbon removal. Single-source vulnerability runs through Chinese pulverized coal ash variability as MEE enforcement accelerates plant retirements. Distribution runs through Houston-Gulf Coast corridor hubs for oilfield chemicals, Mundra-Visakhapatnam port clusters for Indian construction supply, and Eindhoven-Düsseldorf precision processing toll networks for European aerospace.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA Coal Combustion Residuals rule investments create barrier-to-entry moats for feedstock-secured processors capable of absorbing enhanced monitoring and groundwater testing burdens.
For Market Incumbents: Lock in power plant partnership agreements before additional CCR rule tightening compresses fly ash access further. Secure wet-processing capacity additions along the Houston-Gulf Coast corridor to capture Halliburton and Schlumberger procurement consolidation into multi-year supply agreements. Hollow glass microsphere substitution threat in aerospace segments demands precision air classification capability acquisition or toll-processing partnerships with German equipment owners to defend premium segment positioning. For New Entrants and Emerging Players: A mid-tier price-point gap between REACH-certified European supply and unregistered Chinese construction imports creates white-space opportunity for Indian processors achieving BIS certification with mechanical separation cost structures. Target Brazilian pre-salt offshore platform development for oil well drilling grade penetration given ANVISA-API alignment streamlining import pathways. Go-to-market execution should anchor on carbon capture co-benefit positioning to qualify for EU Green Deal green procurement tender access. For Investors and Strategic Acquirers: Re-rating potential sits with precision air classification equipment owners given aerospace specification tightening and capability scarcity forcing mid-tier processors into toll-processing dependency relationships. Long-term viability across the analysis window favors feedstock-secured regional processors with captive power plant access over commodity construction-grade competitors facing Chinese import price erosion. Signal to monitor: EPA CCR rule enforcement intensity against remaining US coal plant fleet as inflection indicator for domestic feedstock availability compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Plant Partnerships | Secures fly ash feedstock access ahead of EPA CCR rule tightening and plant retirements. |
| Precision Air Classification Capacity Expansion | Captures aerospace-grade toll-processing premiums as German and Japanese demand outstrips qualified supply. |
| REACH Registration Completion | Unlocks European Economic Area procurement channels filtering non-compliant Indian and Chinese competitors. |
| Long-term Supply Agreement with Oilfield Service Majors | Aligns with Halliburton and Schlumberger procurement consolidation away from spot-market purchasing. |
| Carbon Capture Co-benefit Certification | Qualifies producers for EU Green Deal industrial decarbonization incentive programs and green procurement tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across plant managers at cenosphere processing facilities, procurement leads at Halliburton and Schlumberger, technical R&D directors at German aerospace composite manufacturers, and distribution channel partners in Indian construction supply networks. Secondary validation drew from EPA Coal Combustion Residuals compliance databases, ECHA REACH registration records, BIS certification listings, and USGS mineral commodity surveys. Bottom-up volume estimates triangulated against top-down construction spending and oil well cementing activity indicators.
Data-stream reconciliation across feedstock recovery rates, processing capacity utilization, and end-use absorption patterns informed the analytical framework. Segmentation dimensions modeled include product type tier, end-use industry vertical, processing technology class, and regional regulatory cluster. CAGRs derived from regression analysis against infrastructure spending trajectories and deepwater drilling project pipelines. Industry-specific forecast inputs incorporated coal plant retirement schedules under MEE dual carbon goals and Permian Basin drilling intensity projections.
Underlying measurement precision varies by segment; aerospace-grade specifications with ISO 13320-compliant laser diffraction certification carry tighter precision than construction-grade mechanical separation output. Forecasts reflect assumptions on EPA CCR rule enforcement trajectory, REACH registration deadline adherence, and oilfield service procurement centralization pace. A model refresh is warranted upon material change in coal plant retirement acceleration or hollow glass microsphere cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Fly Ash Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Injection Molding Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Industrial Brushes Market