
 Flat Enameled Wires Market | 2026-2036
Flat Enameled Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Enameled Wires Market Analysis
The EU Green Deal is shifting insulation material specifications across European supply chains. Superior Essex Inc. leverages its North American manufacturing footprint to serve automotive OEMs with high-temperature polyesterimide grades. Sumitomo Electric Industries, Ltd. anchors Japanese domestic supply for precision electronics winding applications. Furukawa Electric Co. Ltd. specializes in ultra-thin flat enameled conductors for compact motor designs in hybrid powertrains.
Flat enameled wires are rectangular or square cross-section conductors coated with thermosetting polymer insulation, typically applied through continuous enameling ovens at controlled temperatures to achieve precise dielectric strength and thermal endurance ratings. These wires maximize slot fill in electric motors and transformers, reducing copper losses and enabling higher power density in confined geometries. Multi-layer insulation configurations command premium positioning due to their superior thermal index ratings for automotive traction motors. Litz wire constructions are gaining traction in high-frequency renewable energy inverters where skin effect minimization determines efficiency outcomes. Standard thickness grades still occupy the largest volume share across industrial transformer rebuild markets.
The EPA enforces insulation volatile organic compound limits under stationary source air quality rules, while REACH restricts certain phthalate-based plasticizers in European coating formulations. China's MEE implements dual carbon goals that pressure enameling plants toward solvent recovery and energy-intensive process upgrades. Stakeholders must monitor evolving thermal class certification requirements from IEC and NEMA as next-generation wide-bandgap semiconductors push operating temperatures beyond conventional insulation limits.
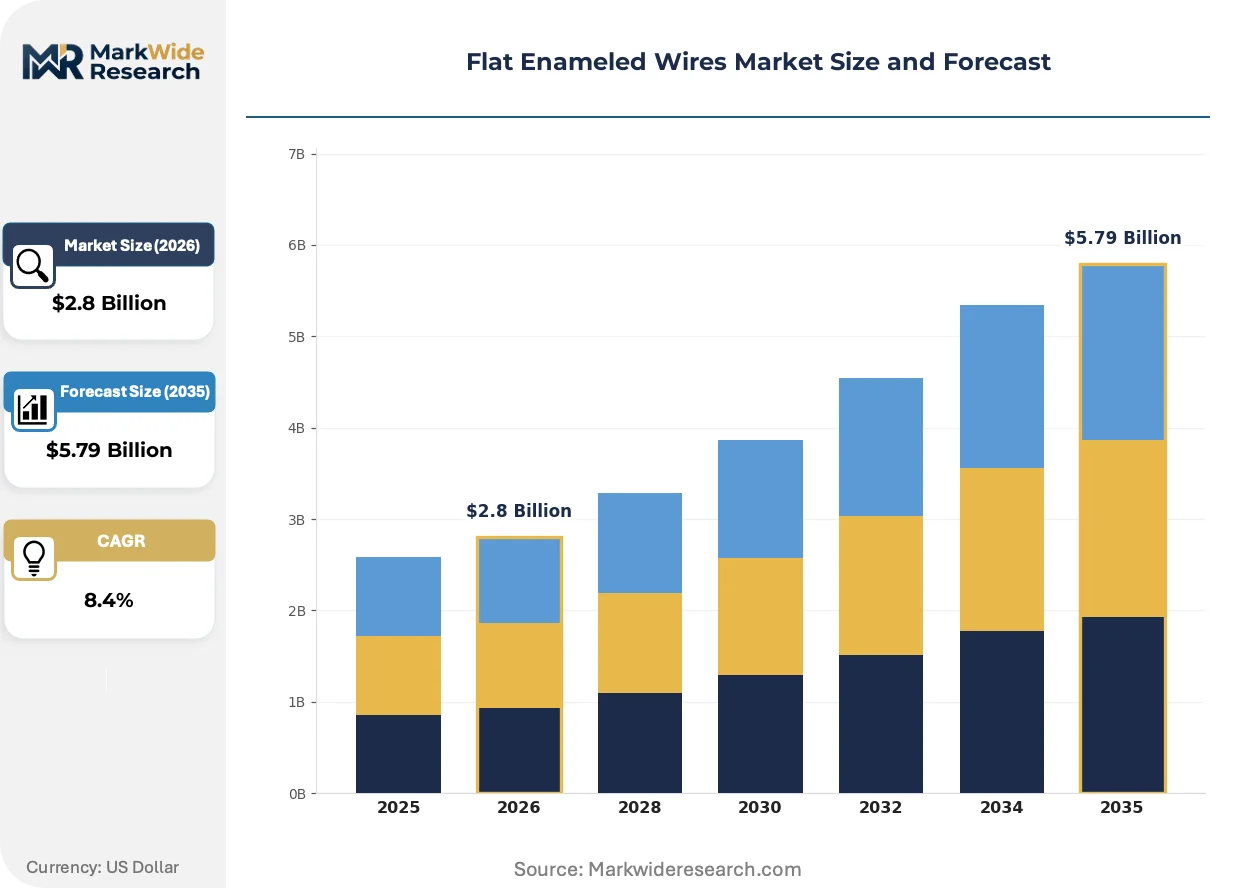
Market Dynamics
Automotive electrification is compressing thermal class requirements across motor winding supply chains, forcing insulation suppliers to certify materials beyond traditional 180°C ratings as wide-bandgap semiconductors push operating temperatures higher.
Growth Catalysts
- EU Green Deal insulation mandates:European motor manufacturers must source halogen-free enamel coatings by 2027, redirecting procurement toward compliant Asian suppliers with certified solvent-recovery systems.
- Hybrid powertrain motor miniaturization:Japanese and German OEMs specify ultra-thin rectangular conductors below 0.8mm thickness to maximize slot fill in compact traction motors.
- China's dual carbon enforcement:Jiangsu and Zhejiang enameling plants face MEE emissions audits that favor integrated producers with captive solvent recovery, consolidating regional supply.
Market Restraints
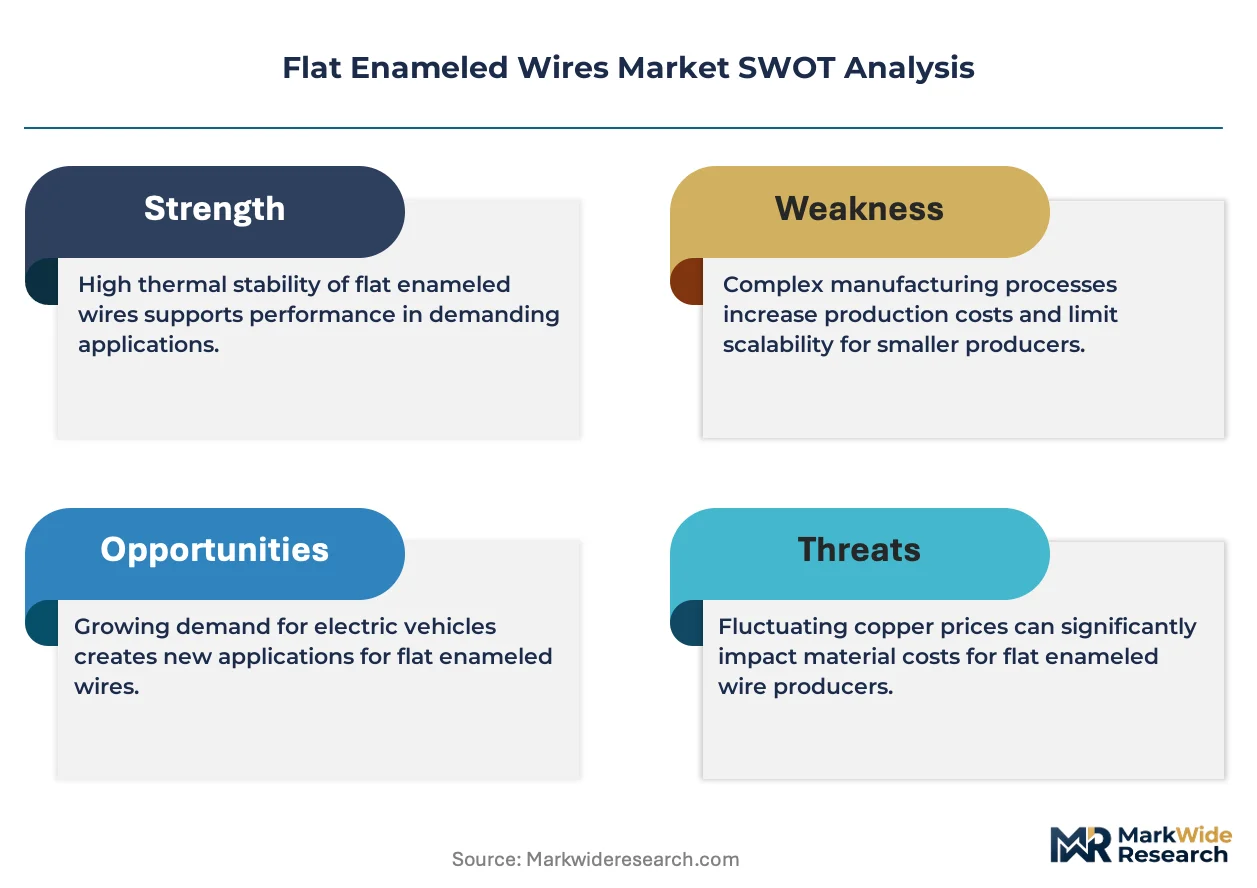
- Copper price volatility:Cathode price swings above 15% annually compress enameling plant margins and deter long-term supply contracts with automotive Tier-1s.
- REACH plasticizer restrictions:ECHA's phthalate limitations force reformulation of polyesterimide coatings, extending qualification timelines by 8-14 months for European suppliers.
- Polyamide-imide resin concentration:Three chemical conglomerates control 70% of high-temperature resin supply, creating single-source vulnerability for multi-layer insulation grades.
Strategic Opportunities
- India PLI scheme for EV components:Domestic motor manufacturing incentives under the Ministry of Heavy Industries attract wire enameling joint ventures with Korean and Japanese technology partners.
- Litz wire convergence with SiC inverters:High-frequency winding constructions address skin effect losses in 800V electric architectures, opening premium positioning for specialized flat conductor geometries.
- Direct OEM supply channel development:Automotive manufacturers bypass traditional distributor networks for thermal class 200+ materials, enabling volume commitments and co-development agreements.
Industry Challenges
- IEC thermal index certification backlog:Testing laboratory capacity constraints delay new insulation system approvals by 6-9 months, freezing product launches for automotive qualification cycles.
- Legacy enameling oven retrofit requirements:Solvent-based process lines require nitrogen atmosphere upgrades to meet emerging volatile organic compound limits, demanding capital deployment without guaranteed volume recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Enameled Wires Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Wire Type: Single Layer, Multi Layer, Flattened, Litz Insulation Material: Polyester, Polyamide, Polyesterimide, Other End Use Industry: Electronics, Automotive, Renewable Energy, Telecommunication Thickness: Thin, Standard, Thick, Extra Thick |
| Companies Covered | Superior Essex Inc., Sumitomo Electric Industries, Ltd., Furukawa Electric Co. Ltd., LS Cable & System Ltd., REA Magnet Wire Company, LLC, Southwire Company, LLC, MWS Wire Industries, Mitsubishi Electric Wire Co., Ltd, Shanghai Yayang Electric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Enameled Wires Market Emerging Trajectories
Polymer chemistry advances and semiconductor thermal envelopes are jointly redefining insulation performance thresholds, while procurement centralization among automotive OEMs compresses supplier qualification windows and favors integrated material-coil producers.
Polyetherimide coating systems are electrifying high-temperature motor applications through continuous vapor deposition processes that achieve 220°C thermal index ratings without traditional solvent-based enameling. German and Korean automotive suppliers specify these materials for 800V traction motors where conventional polyesterimide degrades under combined thermal and electrical stress. The technology is electrifying competitive positioning by enabling direct conductor-to-laminate bonding that eliminates inter-turn insulation layers and reduces motor stack length by 12-18%.
REACH Annex XVII amendments are phasing out medium-chain chlorinated paraffins in wire coating plasticizers, forcing European enameling plants to validate bio-based alternatives through accelerated aging protocols. The restriction compresses formulation flexibility for multi-layer insulation systems that rely on specific plasticizer combinations for flexibility at sub-zero temperatures. Automotive winding suppliers in Hungary and Poland face the steepest compliance costs as they serve German OEMs with the shortest substitution deadlines.
Automotive OEM technical teams now embed conductor specifications into motor platform architectures 36-48 months ahead of production, collapsing traditional sampling and qualification cycles. Tier-2 enameling plants must commit to capacity expansion before design freeze, transferring volume risk from OEMs to material suppliers. This pattern concentrates most visibly in China's Yangtze River Delta, where BYD and NIO motor divisions co-locate procurement teams with wire suppliers to compress iteration cycles.
Flat Enameled Wires Market Segmentation
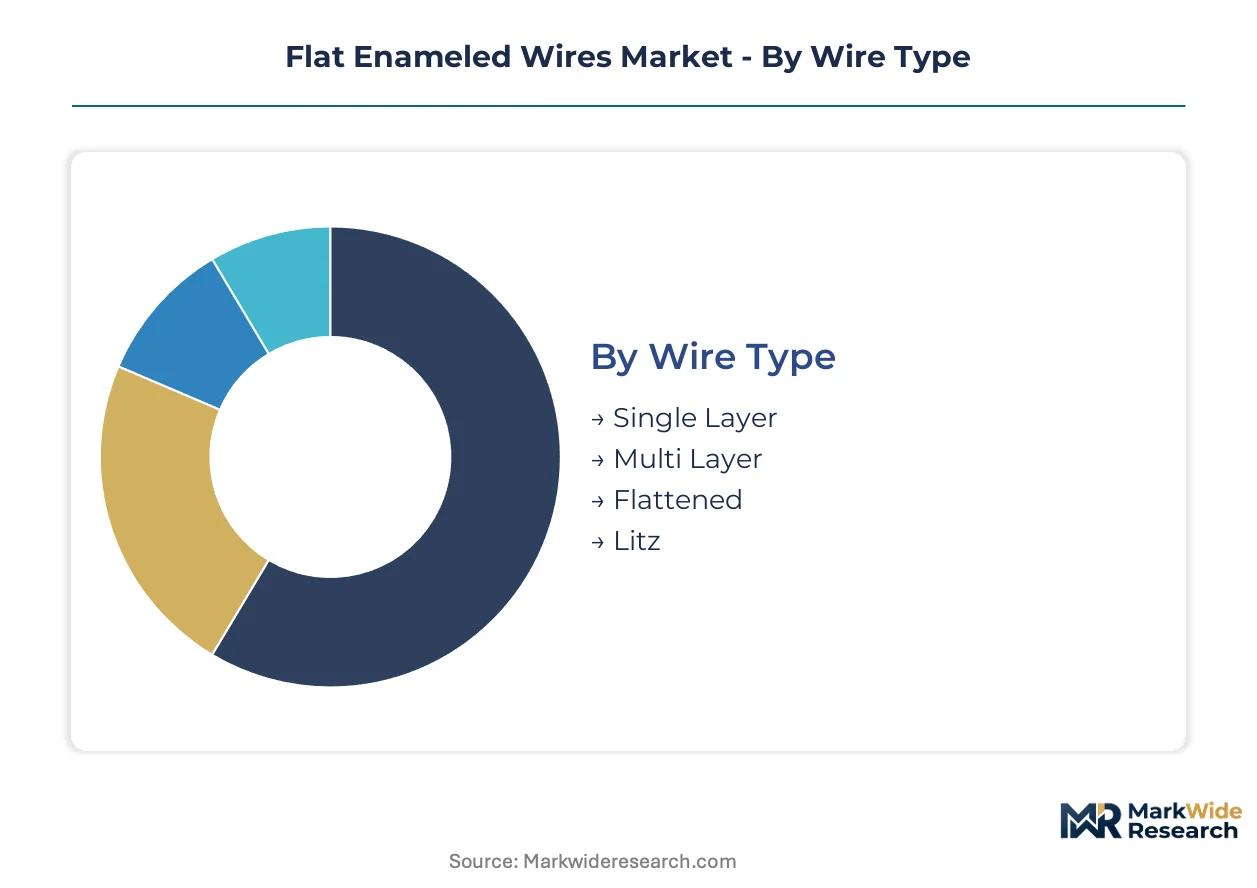
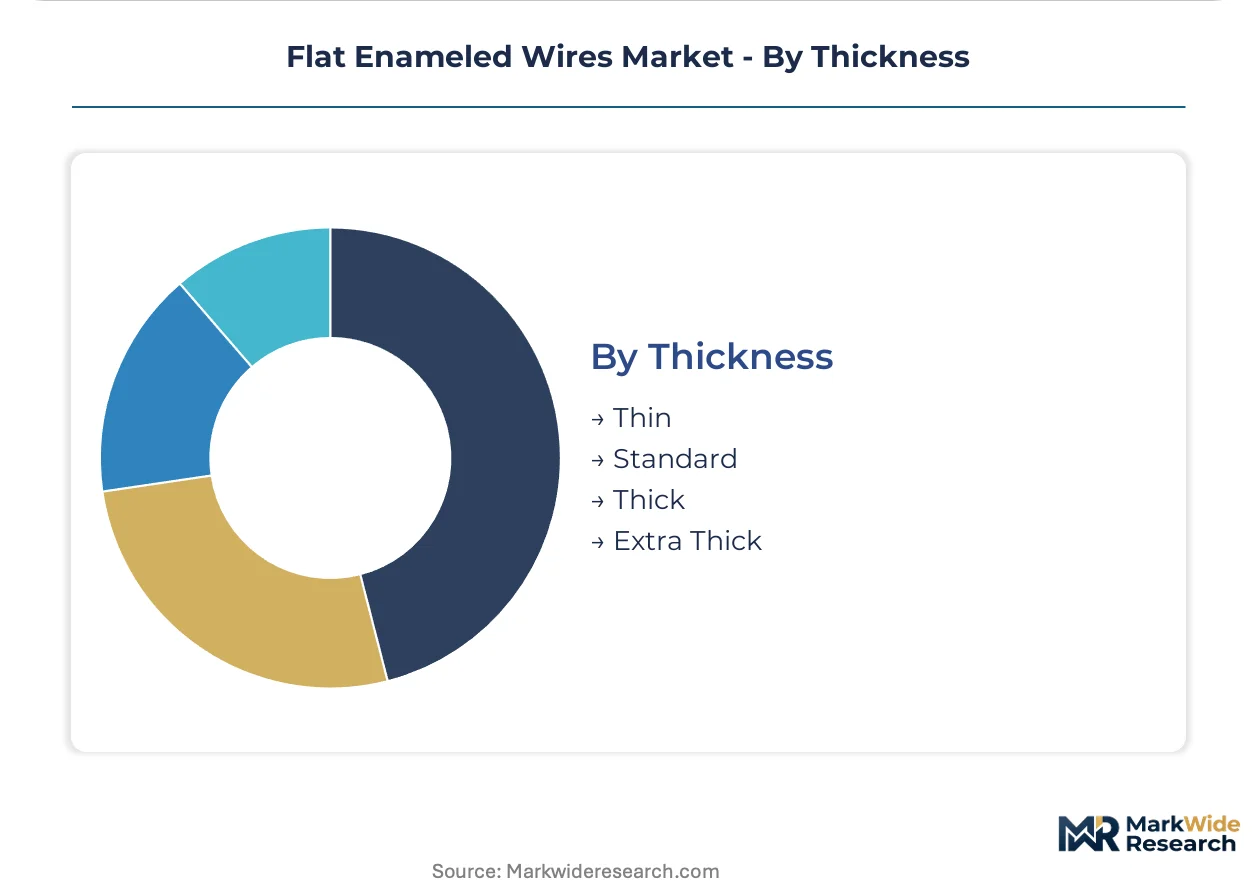
Segmentation in flat enameled wires reveals how thermal performance requirements and manufacturing complexity fragment procurement patterns across motor winding supply chains. Buyers prioritize different specifications based on whether they serve automotive traction systems, industrial transformers, or precision electronics.
Wire Type:
Buyers differentiate primarily by the complexity of their thermal management needs and the sophistication of their winding equipment.
- Multi Layer:Complex insulation stacks combining polyesterimide basecoats with polyamide-imide overcoats achieve thermal class 200 ratings for 800V electric vehicle motors. BYD and NIO specify these conductors exclusively for their latest traction motor platforms in China's Yangtze River Delta manufacturing corridor, where integrated enameling plants co-locate with motor assembly.
- Litz:Braided constructions of individually insulated strands minimize skin effect losses in high-frequency SiC inverter applications above 20kHz. German renewable energy inverter manufacturers are consolidating procurement of rectangular Litz configurations for next-generation wind turbine generators.
- Single Layer:Polyester or polyurethane coatings serve cost-sensitive industrial motor rebuild markets with thermal class 155 ratings.
- Flattened:Round wire compression-formed into rectangular profiles offers intermediate slot fill improvement without dedicated rectangular conductor drawing capacity.
Single Layer leads volumes today; Multi Layer is gaining share fastest.
Insulation Material:
Material selection tracks directly against operating temperature envelopes and regulatory compliance timelines in target export markets.
- Polyesterimide:Hybrid polymer systems balance thermal class 180 performance with solvent-based process economics. Korean automotive suppliers specify these materials for hybrid powertrain motors where cost targets preclude full polyamide-imide systems.
- Polyamide:Nylon-based coatings provide excellent mechanical abrasion resistance for random-wound industrial motors subjected to high insertion forces.
- Polyester:Standard-grade materials dominate replacement transformer winding markets in India under PLI scheme domestic manufacturing incentives.
- Other:Polyetherimide vapor-deposited systems and bio-based alternatives emerge as REACH-compliant options for European automotive supply chains.
Polyesterimide dominates automotive procurement today; polyetherimide and bio-based alternatives are climbing the fastest.
End Use Industry:
End-use segmentation reflects fundamentally different qualification cycles and technical risk tolerances across buyer organizations.
- Automotive:Traction motor windings demand thermal class 200+ materials with 36-48 month advance procurement commitments. Japanese OEMs anchor specifications for ultra-thin rectangular conductors below 0.8mm thickness to maximize slot fill in compact hybrid architectures.
- Renewable Energy:Wind turbine generators and solar inverters drive demand for large-gauge rectangular conductors with multi-layer insulation systems rated for 20+ year service life.
- Electronics:Precision winding applications in Japanese domestic supply chains specify tight dimensional tolerances for miniature inductors and transformers.
- Telecommunication:Base station power supplies and data center infrastructure require consistent dielectric performance across humidity and temperature cycling.
Automotive commands premium positioning today; renewable energy is expanding most quickly.
Thickness:
Thickness categories align with motor power density targets and the mechanical constraints of automatic winding equipment.
- Thin:Conductors below 0.8mm thickness enable maximum slot fill in compact traction motors where German and Japanese OEMs push miniaturization limits.
- Standard:Mid-range dimensions serve broad industrial motor replacement markets with established winding infrastructure.
- Thick:Heavy-gauge conductors address high-current busbar applications and large-frame industrial motors.
- Extra Thick:Specialized dimensions for utility-scale transformer windings and direct-current fast charging infrastructure.
Standard thickness leads volumes today; thin conductors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision enameling techniques for industrial motors during the post-war manufacturing expansion, establishing technical standards that persist in today's automotive winding specifications. Japanese producers later refined ultra-thin conductor processing for compact electronics, while China's Yangtze River Delta emerged as the dominant volume center through integrated copper processing and motor manufacturing clusters.
China
BYD and NIO motor divisions are compressing procurement cycles through co-located technical teams in Jiangsu and Zhejiang provinces. MEE dual carbon enforcement is eliminating smaller enameling plants lacking solvent recovery infrastructure. Suzhou and Ningbo manufacturing corridors now concentrate multi-layer insulation capacity serving 800V traction motor platforms.
Germany
Volkswagen and BMW electrification programs are specifying thermal class 200+ materials with 36-month advance procurement commitments. EU Green Deal halogen-free mandates by 2027 are redirecting coating formulation development toward vapor-deposited polyetherimide systems. Bavarian motor suppliers in Ingolstadt and Munich anchor European demand for ultra-thin rectangular conductors below 0.8mm thickness.
Japan
Toyota and Honda hybrid powertrain miniaturization is driving specifications for precision-wound compact motors with sub-zero temperature flexibility requirements. METI industrial standards govern thermal index certification protocols that domestic suppliers leverage for competitive positioning. Nagoya and Osaka manufacturing basins concentrate precision electronics winding capacity for miniature inductor applications.
United States
EPA stationary source air quality rules are enforcing volatile organic compound limits on solvent-based enameling processes across Midwest industrial corridors. Tesla and Rivian are qualifying domestic enameling plants for direct OEM supply of high-temperature winding materials. Michigan and Ohio automotive supplier networks are consolidating procurement relationships with integrated copper-enameled wire producers.
South Korea
Hyundai and Kia electrification roadmaps are accelerating qualification of polyesterimide-coated conductors for cost-optimized hybrid motor designs. Korean automotive suppliers specify intermediate thermal class 180 materials where full polyamide-imide systems exceed cost targets. Busan-Ulsan manufacturing clusters concentrate wire enameling joint ventures with Japanese technology partners serving regional motor assembly.
Flat Enameled Wires Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across distinct strategic positions in flat enameled wire supply. Integrated copper smelter-enameler operations command raw material cost advantages and captive solvent recovery infrastructure. Specialist enameling plants without upstream metal processing rely on technical service relationships and rapid qualification turnaround. Three strategic archetypes dominate: integrated metal-coating conglomerates, regional automotive-focused enamelers, and precision electronics specialists. Competitive intensity centers on thermal class certification speed and direct OEM supply channel development rather than price competition alone.
Among Japanese industrial conglomerates, Sumitomo Electric Industries, Ltd. and Furukawa Electric Co. Ltd. occupy positions exemplifying the integrated precision electronics archetype, while Superior Essex Inc. represents North American automotive-focused enameling with established direct OEM relationships. These companies anchor distinct geographic supply positions without overlapping segment concentration.
| Leading Market Players |
|---|
| Superior Essex Inc. |
| Sumitomo Electric Industries, Ltd. |
| Furukawa Electric Co. Ltd. |
| LS Cable & System Ltd. |
| REA Magnet Wire Company, LLC |
| Southwire Company, LLC |
| MWS Wire Industries |
| Mitsubishi Electric Wire Co., Ltd |
| Shanghai Yayang Electric Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Precision enameling technician pools in China's Jiangsu and Zhejiang provinces anchor labor-cost differentials that drive pricing-tier spreads across thermal class 155 through 220 materials, with European solvent-recovery compliance requirements compressing margins for non-integrated producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates multi-layer polyamide-imide systems for 800V traction motors from polyesterimide hybrid grades and single-layer industrial rebuild materials. Price differentiation rests on IEC thermal index certification tier and captive copper smelter integration. Cost compression in standard-grade polyester coatings is intensifying because REACH plasticizer reformulation extends qualification timelines. Industrial motor rebuild buyers exhibit highest price sensitivity; automotive OEMs purchasing thermal class 200+ materials directly show lowest.
Supply Chain Analysis
Scrap conductor reclamation and solvent recovery loops flow backward through integrated enameling plants in China, Germany, and Japan to recapture copper and reduce virgin cathode dependence. Raw material supply draws from Chilean copper cathode, polyamide-imide resin from three chemical conglomerates, and polyesterimide basecoat polymers. Single-source vulnerability concentrates in high-temperature resin supply for multi-layer insulation grades. Distribution runs through direct OEM channels for automotive traction materials and distributor networks for industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flat enameled wires market compounds steadily as automotive electrification mandates thermal class escalation across every motor platform generation, embedding recurring specification upgrades into OEM procurement cycles.
For Market Incumbents: Acquire solvent recovery infrastructure and captive copper processing capacity to defend against margin compression from volatile cathode pricing. Integrated Jiangsu and Zhejiang producers with MEE-compliant emissions systems consolidate regional supply as smaller enameling plants face audit-driven elimination. Certification investment in IEC thermal index 220+ ratings locks out non-integrated competitors from 800V traction motor platforms. For New Entrants and Emerging Players: Vapor-deposited polyetherimide coating technology without traditional solvent-based enameling offers entry into EU Green Deal halogen-free compliance segments where incumbent reformulation lags. White-space targets include Indian PLI scheme joint ventures for domestic EV motor manufacturing and Litz wire constructions for SiC inverter applications above 20kHz. Go-to-market through Korean and Japanese technology licensing partnerships accelerates qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional automotive-focused enamelers lacking direct OEM supply relationships but possessing thermal class 200 certification and solvent recovery infrastructure. Five-to-ten year viability hinges on backward integration into copper processing and polyamide-imide resin supply security. Monitor IEC testing laboratory capacity expansion and MEE enforcement intensity in Jiangsu province as inflection indicators for qualification cycle compression and supply consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelting | Cathode price volatility from Chilean supply disruptions threatens unintegrated enameling plant margins. |
| Solvent Recovery Infrastructure Deployment | MEE dual carbon audits in Jiangsu eliminate competitors lacking nitrogen atmosphere oven upgrades. |
| Thermal Class 220+ Certification Investment | Wide-bandgap semiconductor adoption in 800V architectures pushes insulation beyond traditional 180°C ratings. |
| Direct OEM Supply Channel Development | BYD and NIO co-located procurement teams in Yangtze River Delta bypass traditional distributor markups. |
| Vapor-Deposited Polyetherimide Scale-Up | EU Green Deal halogen-free mandates by 2027 invalidate solvent-based coating formulations for European automotive supply. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with enameling plant operations managers, automotive Tier 1 procurement directors, IEC testing laboratory technical leads, and copper cathode trading specialists against secondary validation from SEC filings of listed wire manufacturers, Chinese MEE emissions disclosure databases, ECHA REACH restriction amendments, and customs trade flow records for enameled copper conductor categories. Bottom-up capacity assessments across Jiangsu and Zhejiang manufacturing corridors triangulated against top-down automotive motor production forecasts.
Historical reference periods anchored the projection horizon through verified installation base data for industrial motor rebuild markets and OEM platform roadmaps for traction motor specifications. Segmentation modeling spanned wire type complexity, insulation material thermal index, end-use industry qualification cycle, and geographic regulatory cluster. CAGRs derived from elasticity analysis between copper price movements and enameling plant margin structures, with automotive electrification penetration curves and renewable energy inverter deployment rates as sector-specific demand inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wide-bandgap semiconductor thermal envelope evolution and polyamide-imide resin supply concentration. Practitioners should monitor IEC testing laboratory capacity expansion, MEE enforcement intensity in Chinese manufacturing corridors, and ECHA plasticizer restriction timelines for early signals of qualification cycle disruption and formulation reformulation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Paint Knife Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Felt Gasket Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Polyurethane Processing Machine Market