
 Protective Goggles Market | 2026-2036
Protective Goggles Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Goggles Market Analysis
The capital-intensity divergence between automated lens-coating facilities and conventional assembly lines is collapsing as mid-tier manufacturers adopt shared foundry models. 3M Company leverages captive resin production to anchor margin control across its eyewear portfolio. Honeywell International Inc. competes through integrated distribution networks serving North American industrial accounts. Uvex Safety Group specializes in precision optics for European laboratory and chemical processing environments.
Protective goggles are sealed eyewear devices engineered to shield ocular tissue from mechanical impact, chemical splash, optical radiation, or biological hazards, typically constructed with polycarbonate lenses rated to ANSI Z87.1 or EN 166 impact standards and formed through injection molding or thermoforming processes. Their primary purpose is to prevent workplace eye injuries in hazardous occupational settings while maintaining optical clarity and wearer comfort over extended use periods. Safety goggles and chemical goggles occupy the largest volume positions due to universal mandates across construction and manufacturing sectors, while laser goggles command premium pricing tied to wavelength-specific coating complexity and medical device certification requirements. Polycarbonate materials dominate unit economics given superior impact resistance and lighter weight compared to glass alternatives, though glass retains niche positions in high-temperature foundry applications.
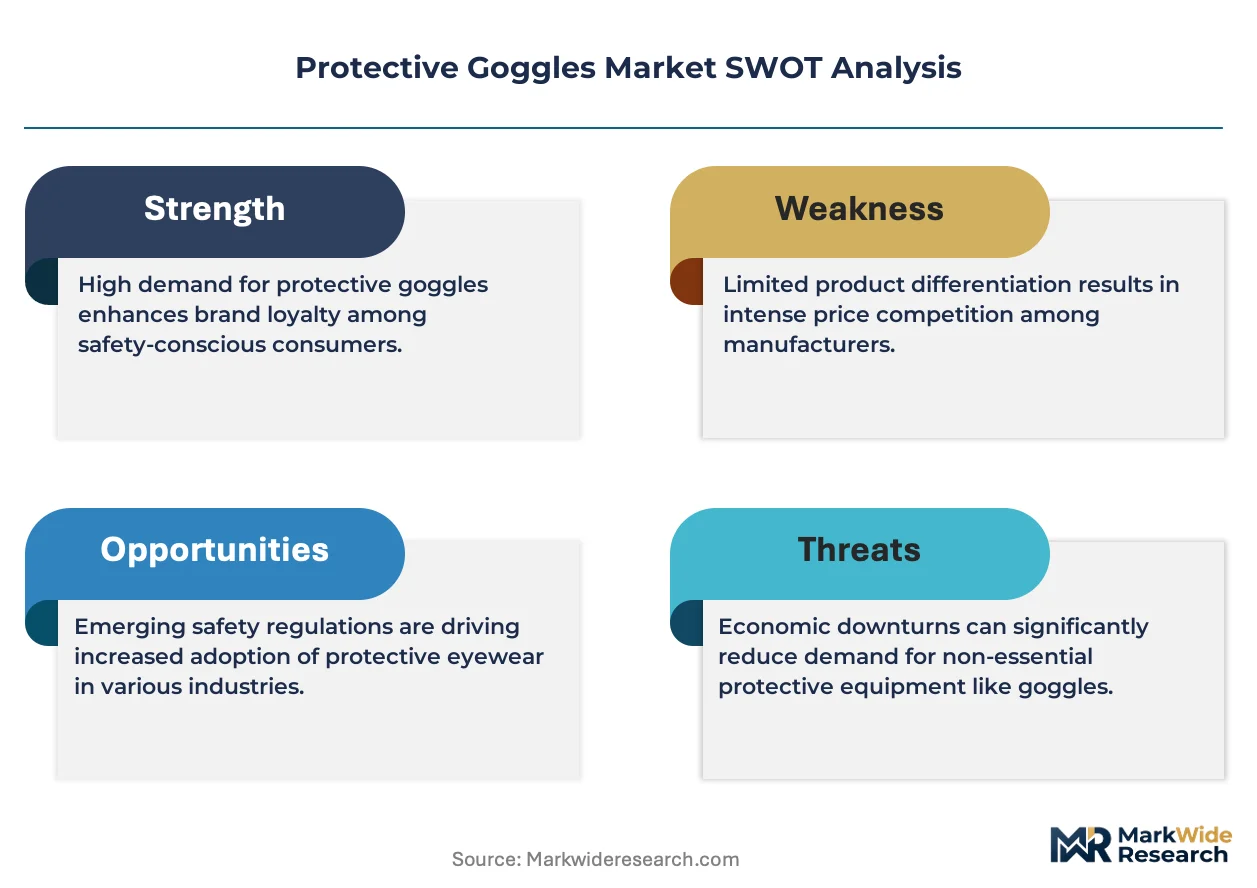
FDA oversight of laser goggles as medical devices, OSHA eye protection mandates under 29 CFR 1910.133, and EN 166 certification requirements administered by EU notified bodies collectively establish compliance barriers that filter non-certified suppliers from institutional procurement channels. The EU AI Act and evolving CSRD disclosure rules are beginning to pressure manufacturers toward documented supply chain transparency for lens polymers and frame materials. Stakeholders must monitor alignment between emerging sustainability reporting obligations and existing product safety certifications to anticipate which compliance investments will determine competitive access.
Market Dynamics
ECHA's tightened workplace exposure limits for chemical splash hazards are forcing German manufacturers to replace legacy vented eyewear with sealed goggle systems, compressing procurement cycles and reshaping supplier qualification criteria across European industrial channels.
Growth Catalysts
- OSHA 29 CFR 1910.133 enforcement:Heightened inspection protocols in US construction and manufacturing are converting residual safety glass users to ANSI Z87.1-rated goggles, particularly in metalworking clusters across Ohio and Texas.
- Polycarbonate injection molding scale:Mid-tier foundries in China and India now achieve optical-grade clarity at volume, collapsing cost barriers that previously limited goggle penetration in price-sensitive industrial corridors.
- Laboratory safety audits:Academic and pharmaceutical research facilities in Switzerland and the Netherlands are mandating laser-specific eyewear inventories tied to wavelength-classified equipment zones.
Market Restraints
- Optical resin supply concentration:Four Asian petrochemical complexes control over 70% of high-purity polycarbonate feedstock for lens applications, exposing downstream manufacturers to input volatility.
- EN 166 certification friction:EU notified body backlogs extend type-examination timelines to 14-18 months, freezing non-certified suppliers from institutional tenders.
- Contact lens substitution:Prescription-integrated safety eyewear with permanent anti-fog coatings is displacing goggle-over-glasses configurations in controlled manufacturing environments.
Strategic Opportunities
- CSRD-aligned material traceability:Early compliance with EU supply chain disclosure rules positions manufacturers for preferred supplier status in ESG-mandated procurement frameworks.
- Smart goggle integration:Convergence of heads-up display modules with existing sealed eyewear form factors creates premium positioning in aviation maintenance and precision assembly verticals.
- Direct-to-facility e-commerce:Industrial distributors in India are bypassing traditional safety equipment dealers through B2B platforms serving mid-size chemical processors in Gujarat and Maharashtra.
Industry Challenges
- Coating technician scarcity:Specialized workforce for anti-scratch and anti-fog deposition processes is concentrated in German and Japanese optical clusters, constraining foundry expansion elsewhere.
- Legacy ERP integration:Batch-level traceability requirements for FDA laser goggle records clash with decades-old manufacturing execution systems at mid-cap US facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Goggles Market |
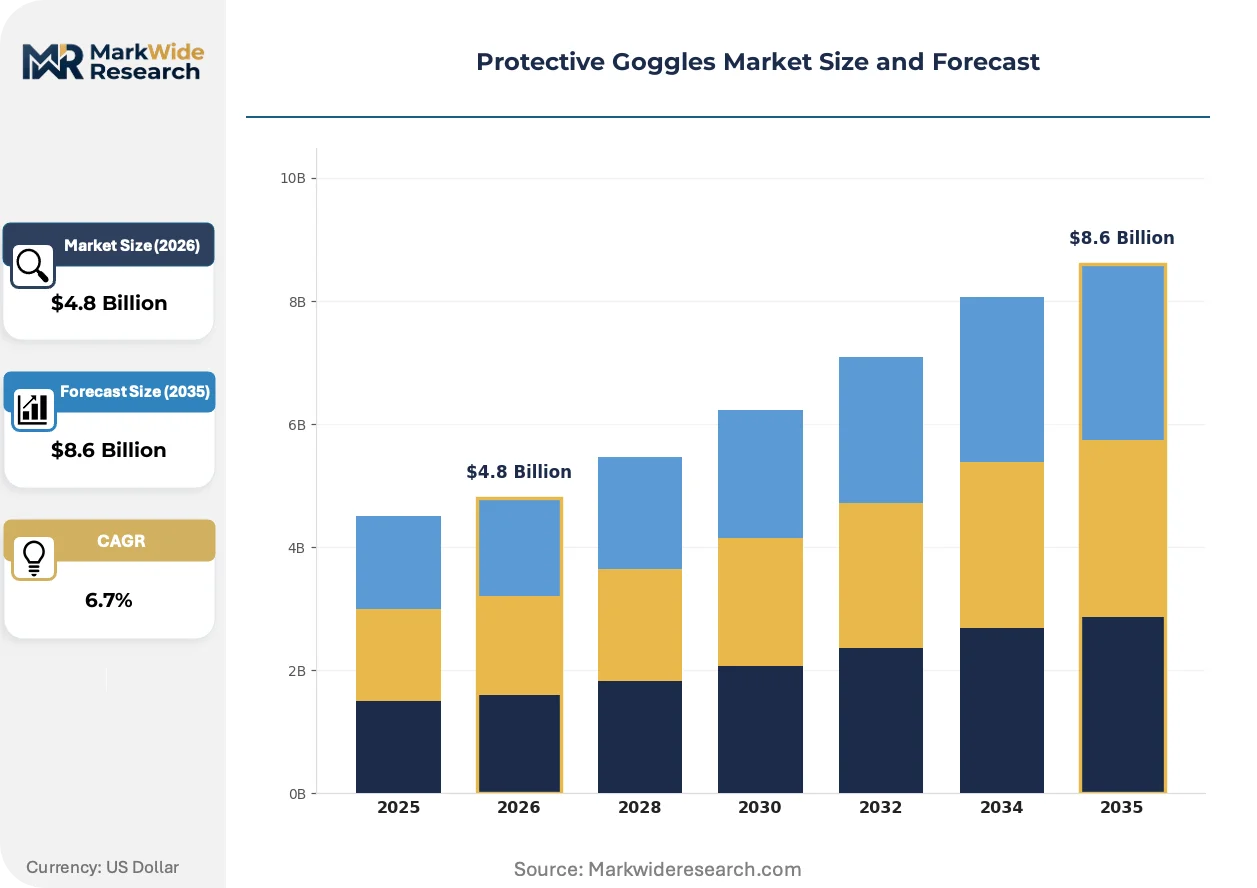
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Goggles, Chemical Goggles, Laser Goggles, Sports Goggles Application: Construction, Laboratories, Sports, Healthcare Material: Polycarbonate, Glass, Plastic, Acrylic End User: Industrial Workers, Healthcare Professionals, Athletes, Students |
| Companies Covered | 3M Company, Honeywell International Inc., Uvex Safety Group, MCR Safety, Pyramex Safety Products, Bollé Safety, Radians Inc., Gateway Safety, Edge Eyewear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Goggles Market Emerging Trajectories
Active reshaping in protective eyewear centers on coating sophistication, regulatory data integration, and procurement channel fragmentation. These forces are compressing traditional product lifecycles while opening premium positioning for compliance-embedded offerings.
Photochromic lens technology is bifurcating the industrial safety segment. Dual-phase materials that darken under optical radiation exposure now serve welding and laser processing applications from a single SKU. German automotive suppliers and Japanese electronics assemblers are adopting these at replacement-cycle velocity. The technology is bifurcating procurement patterns between facilities that consolidate eyewear SKUs and those that maintain task-specific inventories.
EU AI Act documentation requirements are penetrating medical device classifications for laser goggles. Manufacturers must now maintain algorithmic transparency records for any automated coating thickness verification systems. French notified bodies and German technical services are interpreting this as mandatory for CE marking renewal. Premium-positioned suppliers are embedding compliance documentation into product data sheets as a competitive discriminator.
Consolidated safety procurement contracts are fragmenting as multi-site industrial operators unbundle eyewear from broad personal protective equipment agreements. Large chemical processors in the US Gulf Coast now negotiate goggle supply separately from gloves and respiratory equipment, seeking specialized technical support. This pattern is most visible in Texas and Louisiana petrochemical corridors where site-specific hazard assessments override corporate standardization mandates.
Protective Goggles Market Segmentation
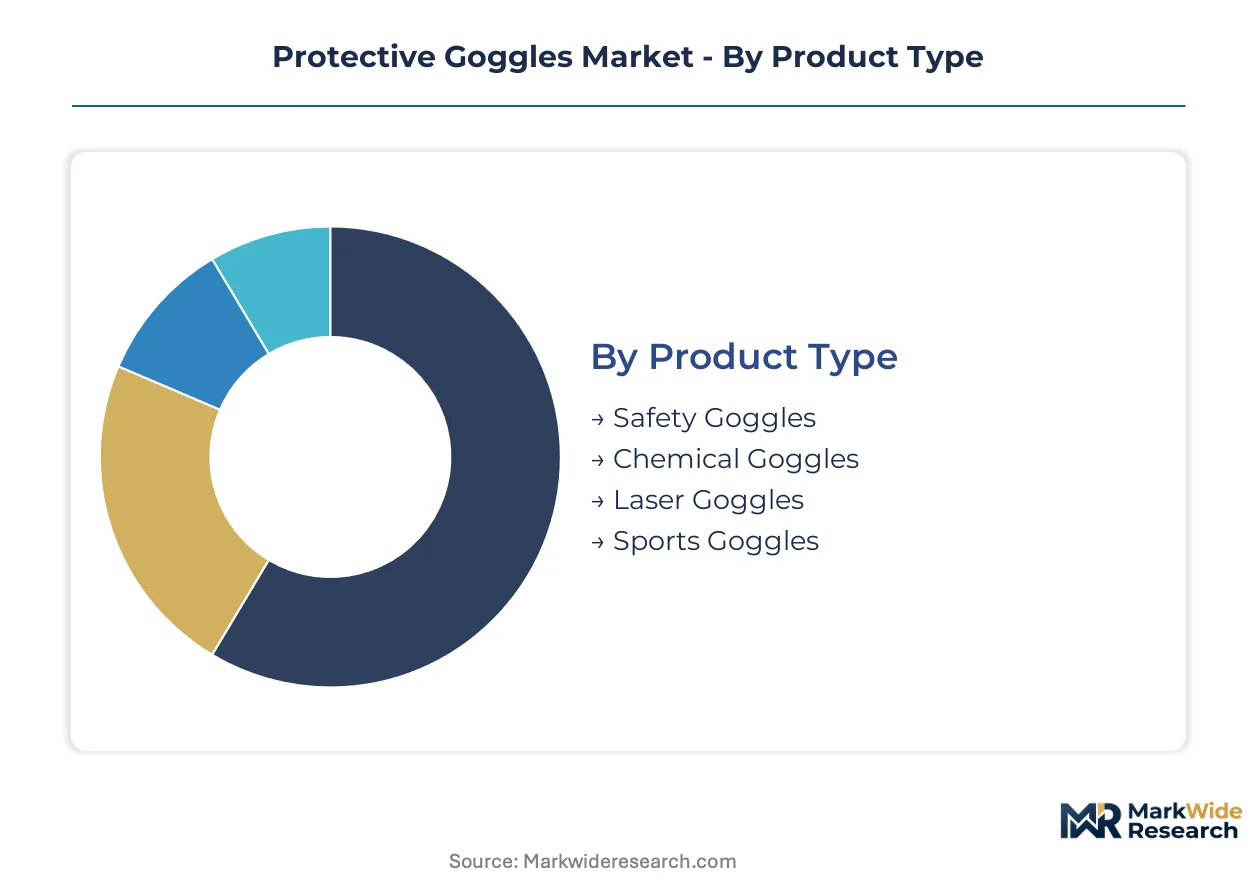
Margin capture in protective goggles hinges on matching material specifications to hazard intensity and regulatory tier. Procurement patterns diverge sharply between bulk industrial tenders and premium-certified medical device channels.
Product Type:
Premium margin pools concentrate in wavelength-specific optical coatings and medical device certifications, while volume economics favor standardized impact-rated sealed eyewear.
- Safety Goggles:ANSI Z87.1-rated sealed eyewear with indirect ventilation channels dominates construction and metalworking procurement in Ohio and Texas industrial clusters. OSHA 29 CFR 1910.133 enforcement is converting residual safety glass users to polycarbonate-based sealed systems.
- Chemical Goggles:Non-vented sealed designs with elastomeric frames meet ECHA tightened workplace exposure limits for chemical splash hazards. German chemical manufacturers are compressing replacement cycles as they phase out legacy vented configurations.
- Laser Goggles:FDA Class II medical devices with wavelength-specific absorption filters command premium positioning tied to optical density ratings and CE marking under EU MDR.
- Sports Goggles:Impact-rated eyewear with anti-fog coatings serves competitive athletics and recreational cycling segments under ASTM F803 standards.
The dominant share belongs to Safety Goggles, while Laser Goggles is closing the gap fastest.
Application:
Application-based demand splits between mandated occupational use and discretionary consumer purchase, with regulatory enforcement intensity determining contract value.
- Construction:OSHA-mandated eye protection drives bulk procurement of ANSI Z87.1-rated polycarbonate goggles across US commercial building sites.
- Laboratories:Swiss and Dutch academic and pharmaceutical research facilities now mandate laser-specific eyewear inventories tied to wavelength-classified equipment zones.
- Sports:ASTM-certified impact protection serves organized youth athletics and professional cycling with replacement-cycle velocity.
- Healthcare:FDA-regulated laser goggles for surgical and dermatological applications require medical device quality systems and 510(k) clearance pathways.
Construction commands the volume base, though Healthcare is expanding most quickly on procedure volume and device certification premiums.
Material:
Material selection trades impact resistance against optical clarity, thermal stability, and coating compatibility for specific hazard environments.
- Polycarbonate:Thermoplastic polymer with superior impact resistance and 40% weight reduction versus glass dominates industrial unit economics. Chinese and Indian mid-tier foundries now achieve optical-grade clarity at volume.
- Glass:Borosilicate and tempered soda-lime compositions retain niche positioning in high-temperature foundry applications above 120°C where polycarbonate softens.
- Plastic:Cellulose acetate and propionate variants serve disposable chemical splash protection in price-sensitive procurement channels.
- Acrylic:PMMA materials offer intermediate impact resistance with superior scratch hardness for light-duty industrial and consumer applications.
Polycarbonate holds the cost-performance sweet spot, while Glass maintains defensible positioning in thermal extremes.
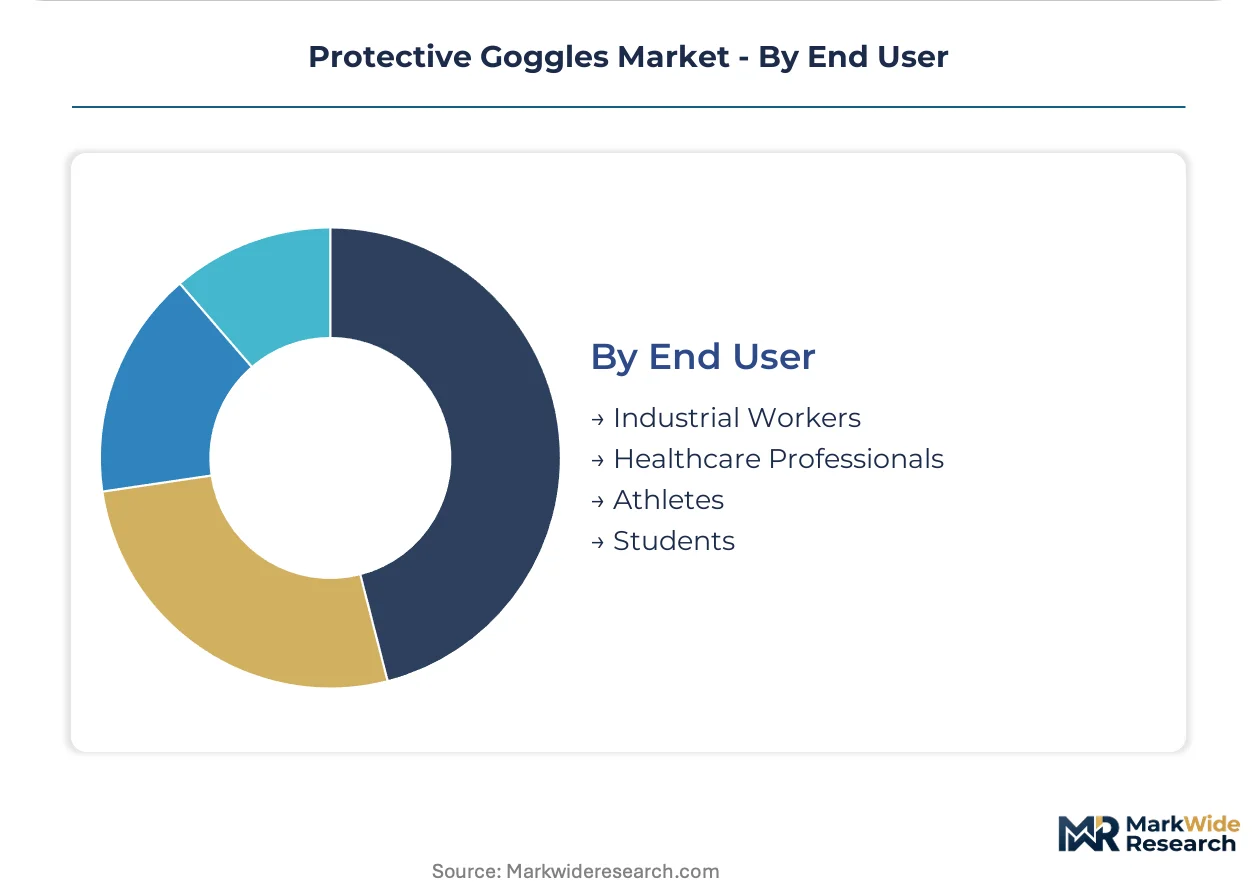
End User:
End user segmentation maps directly to procurement authority structures, from enterprise safety departments to individual athletic purchase decisions.
- Industrial Workers:Enterprise procurement through integrated distributors serves North American manufacturing accounts with site-specific hazard assessments.
- Healthcare Professionals:Hospital supply chains and outpatient surgical centers source FDA-cleared laser protection through medical device distributors.
- Athletes:Direct-to-consumer and specialty retail channels serve cycling, racquet sports, and skiing with brand-differentiated performance positioning.
- Students:Academic laboratory procurement through institutional safety offices drives standardization around EN 166-certified chemical goggles.
Industrial Workers anchor volume demand, while Healthcare Professionals is gaining share fastest on procedure expansion and certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processors deploy sealed goggles under ECHA-mandated exposure limits, while US construction clusters convert legacy safety glass users through intensified OSHA enforcement. Indian mid-tier foundries now supply optical-grade polycarbonate at volume, collapsing prior cost barriers in price-sensitive industrial corridors.
United States
OSHA 29 CFR 1910.133 enforcement protocols are converting residual safety glass users to ANSI Z87.1-rated polycarbonate goggles across metalworking clusters in Ohio and Texas. Heightened inspection activity in commercial construction sites drives bulk procurement of sealed eyewear. Large chemical processors in the Gulf Coast petrochemical corridors now negotiate goggle supply separately from broader PPE agreements.
Germany
ECHA tightened workplace exposure limits for chemical splash hazards force manufacturers to replace legacy vented eyewear with sealed goggle systems. Procurement cycles compress as facilities phase out non-compliant configurations. Industrial safety distributors in the Rhine-Ruhr and Bavarian chemical processing zones report accelerated replacement velocity.
China
Mid-tier foundries in the Yangtze River Delta and Pearl River Delta now achieve optical-grade polycarbonate clarity at production scale. GB standards alignment with EN 166 certification requirements opens export pathways to European institutional tenders. Domestic construction and electronics assembly sectors absorb rising volumes of injection-molded sealed eyewear.
India
Industrial distributors in Gujarat and Maharashtra bypass traditional safety equipment dealers through B2B platforms serving mid-size chemical processors. Polycarbonate injection molding scale economies from domestic foundries collapse prior import dependency. Construction activity in the Delhi-Mumbai Industrial Corridor drives ANSI-equivalent goggle penetration.
Switzerland
Academic and pharmaceutical research facilities mandate laser-specific eyewear inventories tied to wavelength-classified equipment zones. Swissmedic oversight of medical device classifications elevates documentation requirements for surgical laser protection. Precision optics demand from Basel and Zurich biotech clusters supports premium positioning for certified suppliers.
Protective Goggles Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with margin control flowing from captive resin production and distribution network density. The market structure compresses toward two strategic archetypes: vertically integrated polymer-to-eyewear manufacturers and precision optics specialists serving regulated medical device channels. Competitive moves concentrate on shared foundry partnerships for mid-tier scale and CSRD-aligned supply chain documentation for EU institutional access.
Among integrated industrial safety conglomerates, 3M Company and Honeywell International Inc. occupy positions anchored by captive material production and North American distribution density. Uvex Safety Group exemplifies the precision optics specialist archetype, with positioning tied to European laboratory and chemical processing certifications. These three represent the dominant competitive vectors: polymer integration, distribution scale, and regulatory-specialized optics.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Uvex Safety Group |
| MCR Safety |
| Pyramex Safety Products |
| Bollé Safety |
| Radians Inc. |
| Gateway Safety |
| Edge Eyewear |
| Others |
Supply Flow & Price Mechanics
Polycarbonate resin substitution for glass lens substrates simultaneously shifts production gravity toward Asian petrochemical corridors and compresses unit economics at the standard-grade tier. This material transition rewards manufacturers with captive polymer supply while squeezing margin pools for foundries dependent on spot resin markets.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between multinational industrial distributors and integrated manufacturers, insulating volume buyers from resin price volatility. Price differentiation hinges on certification tier—FDA-cleared laser goggles command substantial premiums over ANSI Z87.1-rated industrial units—and geographic delivery cost to remote facility clusters. Cost compression in standard-grade safety goggles is intensifying as Chinese and Indian foundries achieve optical-grade clarity at scale. Construction procurement teams exhibit highest price sensitivity, while healthcare facility buyers prioritize certification compliance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites polycarbonate feedstock delivery from South Korean and Thai petrochemical complexes to downstream lens manufacturers. High-purity polycarbonate granules, anti-fog coating precursors, and elastomeric frame compounds feed from concentrated Asian chemical production. Single-source vulnerability concentrates in four petrochemical complexes controlling specialized optical resin grades. Distribution runs through integrated industrial safety distributors serving North American and European institutional accounts with site-specific technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated multi-site industrial operators unbundling eyewear from broad PPE agreements, fragmenting procurement patterns that previously favored bundled suppliers.
For Market Incumbents: Shield margin pools by deepening backward integration into polycarbonate resin production or securing long-term offtake agreements with Korean and Thai petrochemical suppliers. Invest in EN 166 and FDA certification maintenance to preserve institutional tender access against emerging foundry competitors. Channel control through dedicated industrial distributor relationships remains critical as procurement unbundling accelerates. For New Entrants and Emerging Players: After-sales technical service gaps in laser goggle calibration and wavelength-matching support present entry points for specialized regional players. Target mid-size chemical processors in Gujarat and Maharashtra through direct B2B platforms bypassing traditional dealer networks. Pursue smart goggle integration partnerships with heads-up display module suppliers to capture aviation maintenance vertical premiums. For Investors and Strategic Acquirers: EU AI Act documentation requirements for automated coating verification systems reshape the acquisition landscape toward manufacturers with embedded compliance infrastructure. Five-to-ten-year viability favors precision optics specialists with European laboratory certifications over commodity industrial foundries. Watch EN 166 certification backlog resolution timelines at German and French notified bodies as inflection indicators for competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Resin | Captive supply from Korean petrochemical complexes anchors margin control against feedstock volatility. |
| EN 166 Certification Fast-Track Investment | Accelerated type-examination timelines unlock frozen European institutional tender participation. |
| Smart Goggle Heads-Up Display Partnership | Aviation maintenance and precision assembly verticals command premium positioning through embedded AR modules. |
| CSRD-Aligned Material Traceability System | Documented supply chain transparency secures preferred supplier status in ESG-mandated procurement frameworks. |
| Direct-to-Facility B2B Platform Launch | Bypassing traditional safety equipment dealers captures mid-size chemical processor accounts in Gujarat and Maharashtra. |
Methodological Framework
Initial hypotheses were tested against primary input from plant safety managers, industrial procurement leads, optical coating technicians, and distribution channel partners and refined through secondary validation. Sources included customs and trade data for polycarbonate resin flows, OSHA enforcement activity reports, ECHA regulatory filings, and SEC 10-K disclosures from integrated safety conglomerates. Bottom-up facility-level demand estimates triangulated with top-down market sizing across product type, application, material, and end-user segments.
Variance decomposition across the projection horizon isolates volume drivers—regulatory enforcement intensity, construction activity indices, laboratory safety audit frequency—from price effects tied to resin cost pass-through and certification tier premiums. Segmentation dimensions modeled include product type, application, material composition, end-user procurement authority, and regional regulatory cluster. CAGRs derive from regression against historical enforcement data and forward-looking capital expenditure announcements in chemical processing and construction sectors.
Underlying assumptions cover sustained OSHA and ECHA enforcement protocols, polycarbonate resin supply continuity through Malacca transit routes, and certification body capacity expansion, with deviation risk concentrated in petrochemical complex outages and notified body backlog extensions. Practitioners should keep alternative scenarios live as EU AI Act documentation interpretations and CSRD disclosure timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Barricade Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Portable Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market