
 FIDO Authentication Market | 2026-2036
FIDO Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
FIDO Authentication Market Analysis
Subscription-based key lifecycle management is repositioning vendor revenue models toward recurring security service contracts. Yubico leverages its hardware-authenticator ecosystem to anchor enterprise loyalty through managed key provisioning. Thales competes across government and defense channels with FIPS-certified biometric modules. Daon, Inc. specializes in cloud-native identity orchestration that extends FIDO2 protocols into mobile banking workflows.
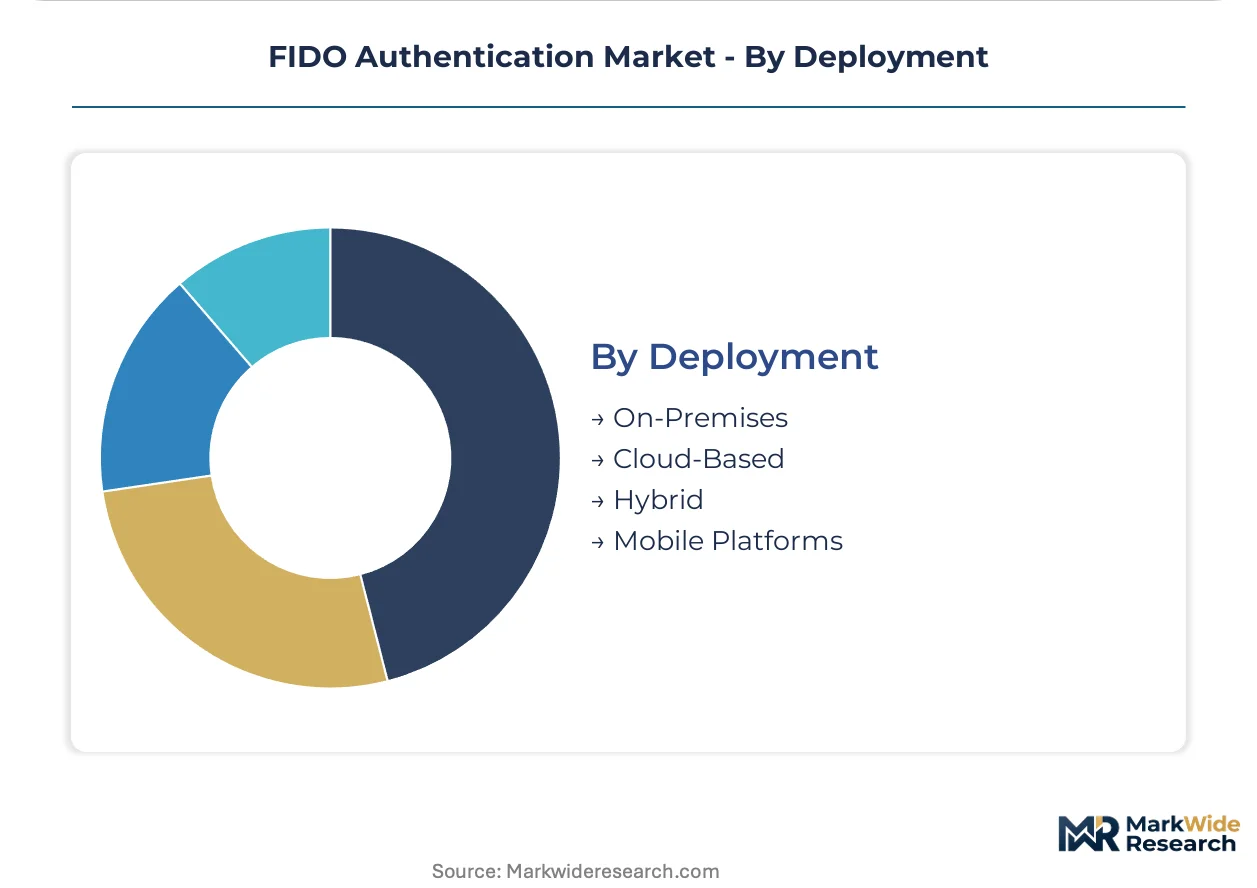
FIDO authentication denotes standards-based cryptographic login protocols that replace passwords with public-key credentials bound to registered devices, typically operating through challenge-response exchanges over TLS-secured channels. The technology eliminates shared secrets, reducing phishing surface area for organizations managing thousands of workforce or customer identities. Biometric authentication leads product type revenue due to enterprise preference for frictionless user experience, while passwordless solutions represent the fastest-growing category as WebAuthn browser support becomes universal across Chromium, Safari, and Firefox engines. Cloud-based deployment captures expanding share among mid-market enterprises seeking outsourced key management, though on-premises installations retain dominance in regulated financial and government sectors where data residency requirements constrain SaaS adoption.
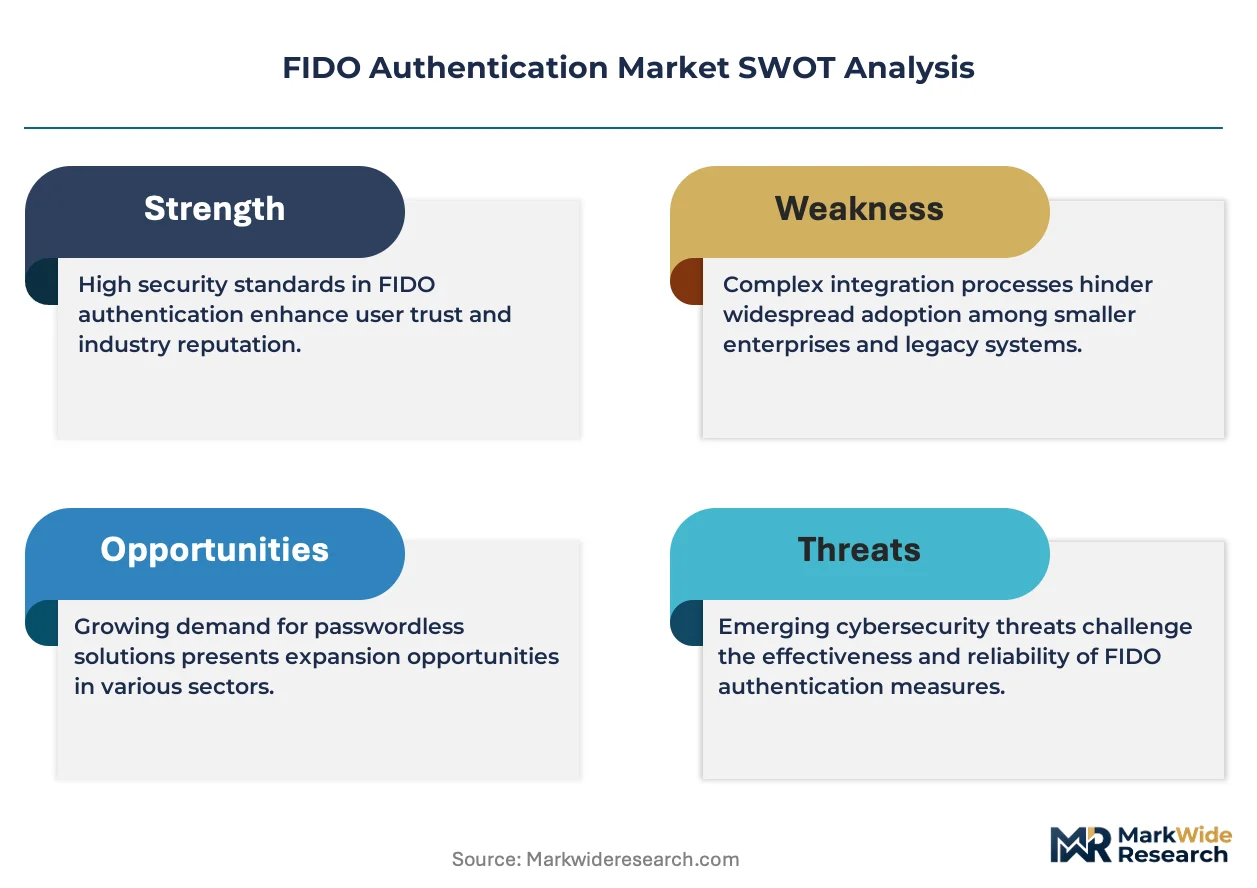
The National Institute of Standards and Technology zero-trust architecture guidelines and the EU Cybersecurity Act certification frameworks are reshaping procurement specifications, requiring FIDO2 Level 2+ authenticator certifications for federal and critical-infrastructure contracts. HIPAA security rule enforcement in US healthcare and PCI-DSS 4.0 requirements for payment processors are mandating phishing-resistant authentication, directly expanding addressable demand across hospital networks and merchant acquirers. Stakeholders must monitor evolving browser attestation format standards and regional certification reciprocity agreements to anticipate compliance-driven replacement cycles and avoid stranded inventory in multi-national deployments.
Market Dynamics
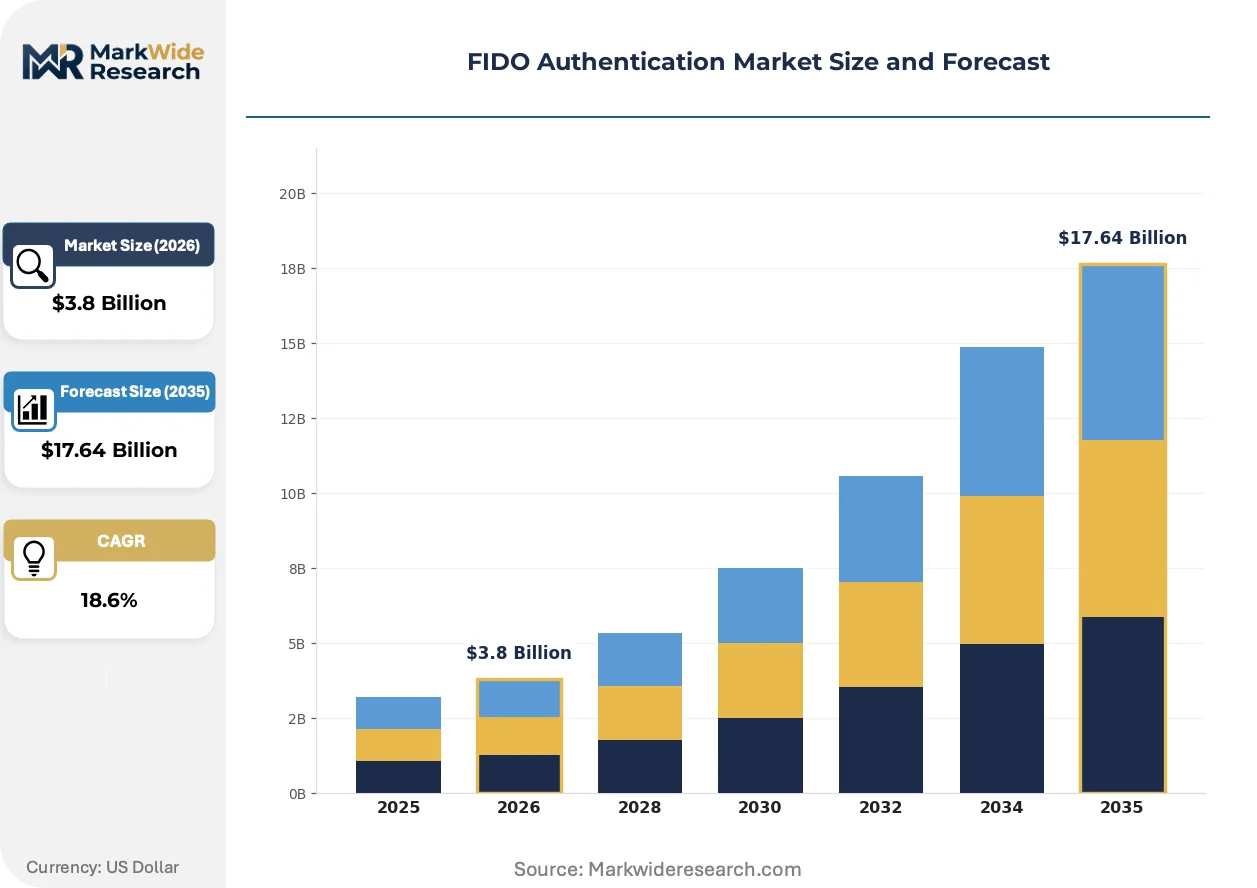
Zero-trust security mandates from the US federal government are compressing enterprise procurement cycles for FIDO2-certified authenticators, forcing vendors to accelerate FIPS 140-2 validation timelines while expanding managed key-lifecycle service portfolios.
Growth Catalysts
- EU AI Act biometric certification:The European Union's risk-based classification system for AI systems is compelling financial institutions to deploy certified FIDO2 biometric modules that satisfy Level 2+ assurance requirements for high-risk applications.
- Healthcare ransomware exposure:HIPAA security rule enforcement actions against US hospital networks suffering credential-based breaches are mandating phishing-resistant authentication for remote clinical access.
- WebAuthn browser ubiquity:Native support across Chromium, Safari, and Firefox engines is eliminating client-side deployment friction for passwordless workforce authentication.
Market Restraints
- FIPS 140-2 validation backlog:Cryptographic module certification queues at NIST-accredited laboratories extend vendor time-to-market by 12-18 months for government-eligible hardware.
- Biometric sensor supply concentration:Fingerprint and facial recognition component manufacturing concentrates in East Asian foundries, exposing authenticator OEMs to geopolitical supply disruption.
- Legacy identity infrastructure:Enterprise Active Directory and LDAP deployments with decades-old certificate architectures resist protocol migration without expensive middleware bridging.
Strategic Opportunities
- India digital public infrastructure:The country's Aadhaar-linked authentication ecosystem creates a ready channel for FIDO2 integration into government benefit distribution and financial inclusion programs.
- IoT device authentication:Constrained-device FIDO standards are opening machine-to-machine credentialing for industrial control systems and connected medical devices.
- Subscription key lifecycle:Managed provisioning services are displacing perpetual hardware sales with recurring revenue contracts that embed automatic certificate rotation and decommissioning.
Industry Challenges
- Attestation format fragmentation:Competing browser implementations of device provenance verification force vendors to maintain multiple attestation statement formats.
- Cross-border certification reciprocity:Divergent national cryptographic approval regimes strand inventory and delay multi-national enterprise rollouts.
- Biometric template interoperability:Proprietary encoding schemes across fingerprint, facial, and iris modalities complicate user re-enrollment during vendor transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FIDO Authentication Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Authentication, Security Keys, Passwordless Solutions, Multi-Factor Authentication End User: Enterprises, Government Agencies, Financial Institutions, Healthcare Providers Technology: WebAuthn, U2F, FIDO2, Security Protocols Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Platforms |
| Companies Covered | Thales, Daon, Inc., Yubico, NEC Corporation, HYPR Corp., OneSpan Inc., Infineon Technologies AG, Intercede, Aware, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FIDO Authentication Market Emerging Trajectories
Authentication technology is converging with cloud-native identity orchestration platforms, compressing the boundary between credential issuance, lifecycle management, and risk analytics into unified control planes.
Passkey synchronization across device ecosystems is rewriting how consumer-facing platforms manage credential recovery and cross-platform continuity. Banking applications in the United States and European Union are deploying passkey vaults that bind FIDO credentials to encrypted cloud backups, eliminating SMS-based account recovery. This architecture is compressing fraud rates while raising new questions about platform provider control over identity portability.
The EU Cybersecurity Act certification framework is mandating Common Criteria evaluations for hardware authenticators deployed in critical infrastructure. European energy utilities and telecommunications operators must now source FIDO2 devices evaluated against EAL4+ assurance levels. German and French national cybersecurity agencies are publishing procurement templates that embed these requirements, creating a two-tier market split between certified and uncertified product tiers.
Enterprise buyers are consolidating authentication spend under zero-trust architecture programs that bundle FIDO deployment with network segmentation and privileged access management. US federal contractors responding to Cybersecurity Maturity Model Certification requirements are issuing multi-year managed service contracts that outsource authenticator provisioning, helpdesk reset handling, and compliance reporting to specialized security providers. This bundling is visible most acutely in defense industrial base supply chains where DFARS clause enforcement has accelerated since 2023.
FIDO Authentication Market Segmentation
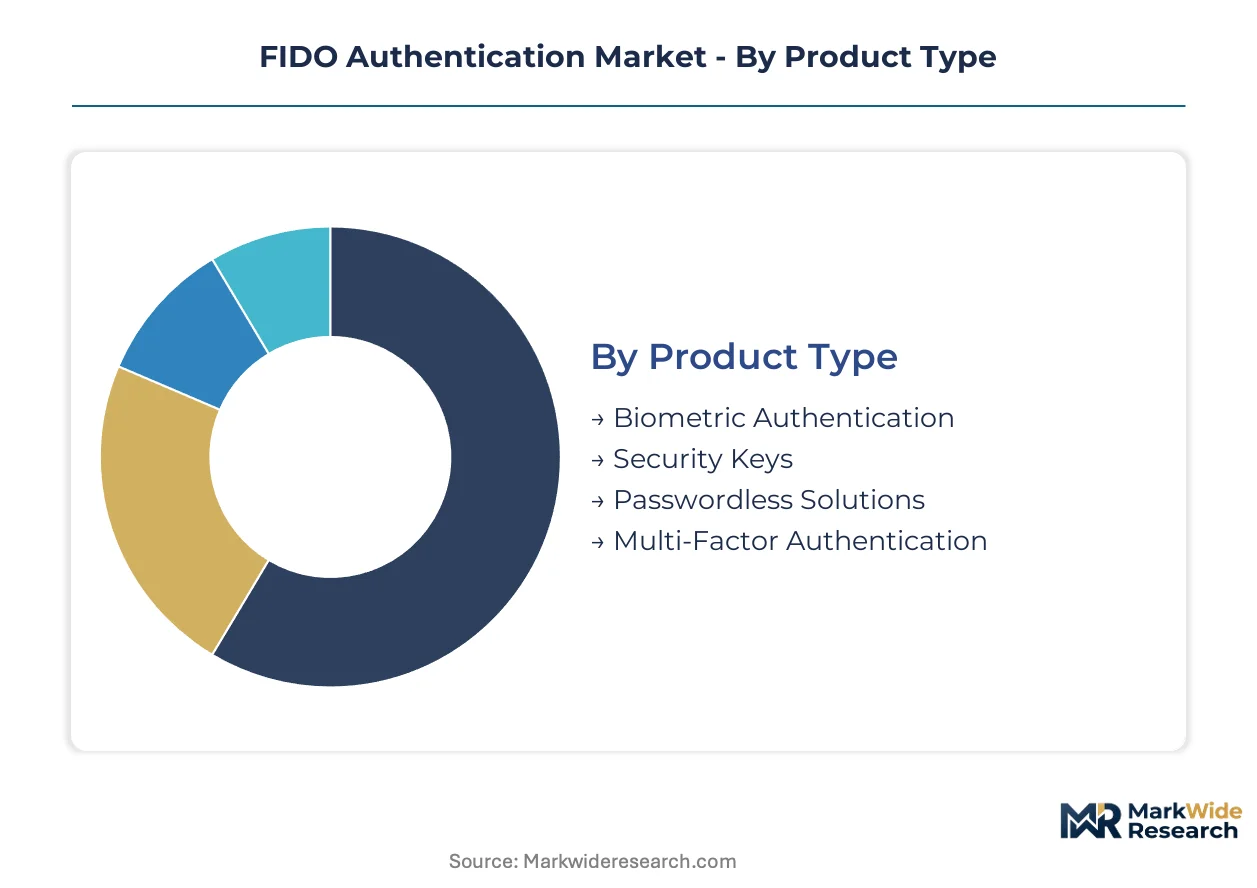
FIDO authentication markets fragment across credential form factors, organizational risk profiles, and infrastructure maturity levels. Segment boundaries blur as biometric modules embed into security keys and cloud orchestration layers absorb on-premises policy engines.
Product Type:
Standalone hardware authenticators operate independently of host device capabilities, while embedded biometric subsystems integrate directly into endpoint motherboards and mobile secure elements.
- Biometric Authentication:Fingerprint, facial, and iris recognition modules bind cryptographic keys to physiological characteristics through secure enclaves. US healthcare networks and German automotive suppliers are consolidating procurement around FIPS 140-2 certified sensors to satisfy HIPAA and EU AI Act assurance requirements.
- Passwordless Solutions:WebAuthn-native credential flows eliminate password entry entirely through device-bound private keys synchronized across ecosystem vaults. Financial institutions in the United States and Netherlands are deploying passkey architectures to displace SMS one-time codes and reduce account takeover fraud exposure.
- Security Keys:USB-A, USB-C, and NFC hardware tokens provide portable second-factor authentication for workforce and consumer applications.
- Multi-Factor Authentication:Layered verification combining possession, inherence, and knowledge factors into sequential or risk-adaptive challenge flows.
Volume placements concentrate in Biometric Authentication; the faster expansion belongs to Passwordless Solutions.
End User:
Risk tolerance and regulatory exposure determine procurement sophistication, with regulated sectors demanding certified hardware and managed lifecycle services.
- Enterprises:Technology, manufacturing, and professional services firms deploy workforce authentication at scale, prioritizing SSO integration and helpdesk cost reduction. US federal contractors responding to CMMC requirements are bundling FIDO2 deployment with zero-trust network segmentation programs.
- Government Agencies:Defense, civilian, and intelligence entities mandate FIPS 140-2 Level 2+ or Common Criteria EAL4+ certifications for hardware authenticators. NIST zero-trust architecture guidelines are compressing procurement cycles across federal departments and state-level equivalents.
- Financial Institutions:Banks, payment processors, and insurance carriers face PCI-DSS 4.0 phishing-resistance mandates.
- Healthcare Providers:Hospital networks and telehealth platforms require HIPAA-compliant remote access for clinical staff.
Procurement scale favors Enterprises; steepest compliance-driven replacement cycles are occurring in Government Agencies.
Technology:
Protocol generations stack in backward-compatible layers, with newer specifications subsuming earlier cryptographic capabilities while expanding attestation and resident key features.
- FIDO2:The current specification unifying WebAuthn client protocols with CTAP authenticator standards, supporting resident keys for passwordless single-factor operation. Browser ubiquity across Chromium, Safari, and Firefox engines is eliminating client-side deployment friction for workforce authentication.
- WebAuthn:W3C-standardized browser API enabling websites to register and authenticate users through public-key credentials without browser plugins.
- U2F:Legacy universal second-factor protocol providing phishing-resistant hardware token authentication through challenge-response signatures.
- Security Protocols:TLS 1.3, COSE, and CBOR encoding standards underlying credential transport and attestation statement formatting.
Deployment share clusters in FIDO2; specification evolution is accelerating most quickly through WebAuthn browser integration.
Deployment:
Infrastructure location determines key custody models, with regulated sectors retaining on-premises hardware security modules and mid-market buyers accepting cloud-resident credential management.
- On-Premises:Hardware security modules and identity provider software deployed within organizational data centers, satisfying data residency and air-gapped network requirements. German energy utilities and French defense contractors maintain this posture to comply with national cybersecurity agency procurement templates.
- Cloud-Based:SaaS identity orchestration platforms outsourcing key lifecycle management, certificate rotation, and compliance reporting to specialized security providers.
- Hybrid:Split architectures retaining sensitive credential operations on-premises while leveraging cloud analytics and policy distribution.
- Mobile Platforms:Smartphone and tablet native authenticators leveraging secure enclaves and biometric sensors for consumer and workforce authentication.
Installed base dominance rests with On-Premises; Cloud-Based deployment is climbing the fastest among mid-market enterprises seeking outsourced key management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware authenticator manufacturing concentrates in East Asian foundries, while enterprise demand clusters in North American and European regulated sectors. Procurement patterns diverge sharply between federal compliance markets and commercial cloud-native deployments.
United States
Federal zero-trust mandates from NIST and CMMC requirements are compressing procurement cycles for FIPS 140-2 certified authenticators. HIPAA security rule enforcement actions against hospital networks suffering credential breaches mandate phishing-resistant authentication for remote clinical access. Defense industrial base contractors in Virginia and California are bundling FIDO2 deployment with zero-trust network segmentation programs.
Germany
Automotive suppliers and energy utilities demand Common Criteria EAL4+ evaluations for hardware authenticators under EU Cybersecurity Act frameworks. The national cybersecurity agency publishes procurement templates embedding these requirements, creating certified versus uncertified product tiers. Industrial manufacturers in Bavaria and Baden-Württemberg are consolidating procurement around FIPS 140-2 certified biometric sensors.
India
The Aadhaar-linked authentication ecosystem creates immediate channels for FIDO2 integration into government benefit distribution and financial inclusion programs. RBI guidelines on digital payment security are accelerating bank procurement of certified biometric modules. Technology services clusters in Bengaluru and Hyderabad are deploying workforce authentication at scale for export-oriented IT services.
United Kingdom
Financial conduct authority guidance on operational resilience is driving bank procurement of passwordless solutions to reduce account takeover fraud exposure. NHS digital transformation programs mandate phishing-resistant authentication for clinical staff accessing patient records. London-based fintechs are deploying passkey architectures to displace SMS one-time codes.
Japan
METI industrial cybersecurity guidelines are shaping procurement specifications for critical infrastructure operators. Manufacturing conglomerates in the Chubu and Kansai regions are integrating FIDO2 protocols into supply chain access management. Domestic technology providers are specializing in secure element integration for enterprise mobile deployments.
FIDO Authentication Market Vendor Landscape
Top-tier vendors anchor federal and defense certification channels, while mid-tier specialists compete on cloud-native identity orchestration and subscription key lifecycle services. The vendor base stratifies across hardware authenticator OEMs, biometric module suppliers, and managed security service providers. Three archetypes dominate: FIPS-certified hardware specialists, cloud-native orchestration platforms, and subscription-based key lifecycle managers. Competitive positioning hardens through FIPS 140-2 validation acceleration and managed service contract bundling.
Among hardware-centric vendors, Thales and Yubico occupy positions anchoring enterprise loyalty through certified authenticator ecosystems and managed key provisioning. Daon, Inc. exemplifies the cloud-native tier, specializing in identity orchestration that extends FIDO2 protocols into mobile banking workflows. These three represent the strategic archetype spectrum from hardware certification dominance to software-first orchestration.
| Leading Market Players |
|---|
| Thales |
| Daon, Inc. |
| Yubico |
| NEC Corporation |
| HYPR Corp. |
| OneSpan Inc. |
| Infineon Technologies AG |
| Intercede |
| Aware, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FIPS 140-2 Level 2+ hardware and uncertified commodity authenticators manifests in parallel supply chain configurations: premium tiers anchor in NIST-accredited validation pipelines with 12-18 month certification queues, while standard tiers source from East Asian foundries with compressed lead times but elevated geopolitical exposure. This bifurcation concentrates pricing power with validated vendors serving federal and healthcare procurement channels.
Pricing Analysis
Margin tightening in certified hardware tiers reflects NIST laboratory capacity constraints that elongate validation timelines and inflate compliance overhead. Three-tier pricing structure across certified-premium, enterprise-standard, and volume-economy authenticators segments buyers by assurance requirement: government agencies and hospital networks absorb premium pricing for FIPS validation, while mid-market enterprises gravitate toward standard tiers with managed service bundling. Cost-down pressure on economy USB-A and NFC tokens accelerates as browser-native WebAuthn support commoditizes basic second-factor functionality. Price sensitivity concentrates in mid-market cloud deployments, where SaaS-tiered subscription models displace perpetual hardware purchases.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles coordinate hub-and-spoke fulfillment patterns for hardware authenticators destined for federal contractors and healthcare networks. Manufacturing concentrates in Taiwan, South Korea, and mainland China for fingerprint sensors, secure elements, and cryptographic processors. Raw material dependencies span silicon wafers, biometric sensor arrays, and tamper-resistant packaging substrates. Single-source vulnerability in East Asian foundry capacity exposes authenticator OEMs to export control disruptions and tariff escalations. Distribution runs through specialized cybersecurity value-added resellers and direct federal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FIDO authentication markets operate under supply-constrained conditions where NIST validation laboratory capacity caps certified hardware throughput, propping pricing premiums for government-eligible authenticators.
For Market Incumbents: Cement federal channel loyalty by accelerating FIPS 140-2 Level 3 validation investments before competitor queue positions mature, while embedding subscription key lifecycle services to displace hardware-only margins. Vertical integration into secure element sourcing mitigates East Asian foundry concentration risk. Certification investment remains the priority defensive lever against cloud-native orchestration platforms eroding hardware attach rates. For New Entrants and Emerging Players: Enter via India's Aadhaar-linked financial inclusion programs, where RBI guidelines on digital payment security create immediate procurement demand for certified biometric modules without entrenched incumbent relationships. White-space targets include mid-market healthcare networks seeking HIPAA-compliant managed authentication services and European energy utilities navigating EU Cybersecurity Act EAL4+ mandates. Cloud-native identity orchestration with passkey vault integration offers the most penetrable go-to-market angle against hardware-centric legacy vendors. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native identity orchestration platforms given EU AI Act biometric certification mandates compressing enterprise procurement cycles toward software-first deployment models. Long-term viability favors vendors with recurring revenue contracts embedding automatic certificate rotation and decommissioning. Acquisition target archetype: FIDO2-certified biometric module suppliers with existing NIST validation queue positions. The signal to watch is browser attestation format standardization eliminating multi-format maintenance overhead.| Strategic Initiative | Industry Significance |
|---|---|
| FIPS 140-2 Level 3 Validation Acceleration | Shortens NIST laboratory queue position for federal and healthcare procurement eligibility. |
| Subscription Key Lifecycle Service Launch | Displaces perpetual hardware sales with recurring revenue contracts embedding automatic certificate rotation. |
| EU Cybersecurity Act EAL4+ Certification | Unlocks German energy utility and French defense contractor procurement under national agency templates. |
| India Aadhaar Integration Partnership | Positions FIDO2 protocols within government benefit distribution and RBI-guided digital payment infrastructure. |
| Passkey Vault Cloud Backup Architecture | Eliminates SMS-based account recovery for US and EU banking applications while compressing fraud exposure. |
Methodological Framework
Document review covered FIDO Alliance specification documents, NIST SP 800-63 guidelines, EU Cybersecurity Act certification frameworks, and SEC filings from publicly traded authentication vendors, complemented by interviews with CISOs at US hospital networks, federal procurement officers, biometric sensor engineering directors, and identity orchestration platform product managers. Secondary validation drew from FIDO Alliance deployment statistics, NIST accredited laboratory certification queues, and RBI circulars on digital payment security. Bottom-up unit economics triangulated against top-down addressable market sizing across deployment models and end-user segments.
Cross-reference between historical FIDO2 adoption curves and panel input from enterprise IT procurement officers shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user risk profile, deployment infrastructure location, and protocol generation maturity. CAGRs derived from installed base replacement cycles, compliance-driven procurement mandates, and browser capability expansion trajectories. Industry-specific forecast inputs incorporated NIST zero-trust architecture guideline implementation timelines and EU AI Act biometric system risk classification enforcement patterns.
Revisions become necessary when NIST laboratory validation capacity expands or contracts, when browser attestation format standards consolidate or fragment further, or when export control regimes disrupt East Asian foundry supply. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and browser vendor protocol support. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Biometrics Banking Market