
 Personal Protective Equipment Packaging Market | 2026-2036
Personal Protective Equipment Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Protective Equipment Packaging Market Outlook
Modular kit configurations for multi-item PPE sets is pivoting how institutional buyers evaluate total cost of ownership against single-SKU convenience. WestRock leverages its corrugated structural design capabilities to dominate hospital-system contracts for consolidated mask-glove-gown dispensers. Berry Global anchors its position through in-house production of multilayer sterile films that integrate with downstream form-fill-seal automation.
Personal Protective Equipment Packaging encompasses engineered containment systems—sterile barrier pouches, thermoformed blisters, rigid clamshells, and corrugated shipper boxes—fabricated from medical-grade plastics, coated papers, or aluminum-composite laminates to maintain product integrity through sterilization, distribution, and point-of-use deployment. Bags and blisters command the largest volume share in healthcare sterile applications where peel-open aseptic presentation is mandatory, while composite materials represent the fastest-expanding material class as manufacturers seek to reconcile moisture barrier performance with fiber-based sustainability targets. Reusable containment systems for industrial respirator decontamination cycles are gaining specification traction in manufacturing end-use segments where total lifecycle cost models displace single-use economics.
FDA 21 CFR Part 820 quality system regulations and ISO 11607 sterile barrier standards govern medical-grade packaging validation requirements in the United States, while EU MDR and REACH chemical compliance frameworks shape material selection and market access across European supply chains. OSHA respiratory protection standards indirectly drive packaging specifications through fit-testing kit bundling requirements that influence box and insert configurations. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions that threaten incumbent moisture-barrier coatings and force material transitions with uncertain qualification timelines.
Market Dynamics
Sterile barrier qualification timelines and EPA chemical restrictions are compressing material substitution windows, forcing packaging converters to validate alternatives before incumbent coatings face phase-out.
Growth Catalysts
- OSHA respiratory protection mandates:Fit-testing kit bundling requirements expand box and insert specifications for industrial distributors serving manufacturing facilities.
- EU MDR sterile packaging compliance:European medical device manufacturers must demonstrate validated sterile barrier systems, accelerating pouch and blister procurement from qualified converters.
- China domestic PPE manufacturing scale:Export packaging standardization to ISO 11607 and FDA 510(k) alignment drives demand for medical-grade films and validation documentation.
Market Restraints
- Aluminum-laminate feedstock volatility:Moisture barrier films depend on aluminum foil supply concentrated among Chinese smelters, exposing converters to price swings and quota restrictions.
- PFAS coating phase-out uncertainty:EPA restrictions on per- and polyfluoroalkyl substances threaten grease and moisture barriers without qualified drop-in replacements, freezing qualification pipelines.
- Ethylene-vinyl acetate supply concentration:Seal layer resins for sterile pouches rely on petrochemical complexes clustered along the US Gulf Coast, creating hurricane-related disruption exposure.
Strategic Opportunities
- India hospital infrastructure expansion:Central government health scheme procurement is specifying pre-sterilized surgical kits requiring validated primary and secondary packaging systems.
- Reusable respirator decontamination cycles:Industrial manufacturing segments in Germany and Japan are adopting lifecycle cost models that specify durable containment systems over single-use disposables.
- Digital printing for lot-level traceability:Convergence of thermal inkjet and UV-cure technologies enables variable data printing directly on sterile barriers, replacing adhesive labels.
Industry Challenges
- ISO 11607 validation engineering scarcity:Sterile barrier qualification requires specialized microbiology and materials science expertise that packaging converters struggle to staff.
- Legacy form-fill-seal line retrofit costs:Transitioning from PVC to multilayer polyolefin films demands capital-intensive sealing jaw and temperature control modifications.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face 16-24 month queues at accredited laboratories, delaying new material launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Protective Equipment Packaging Market |
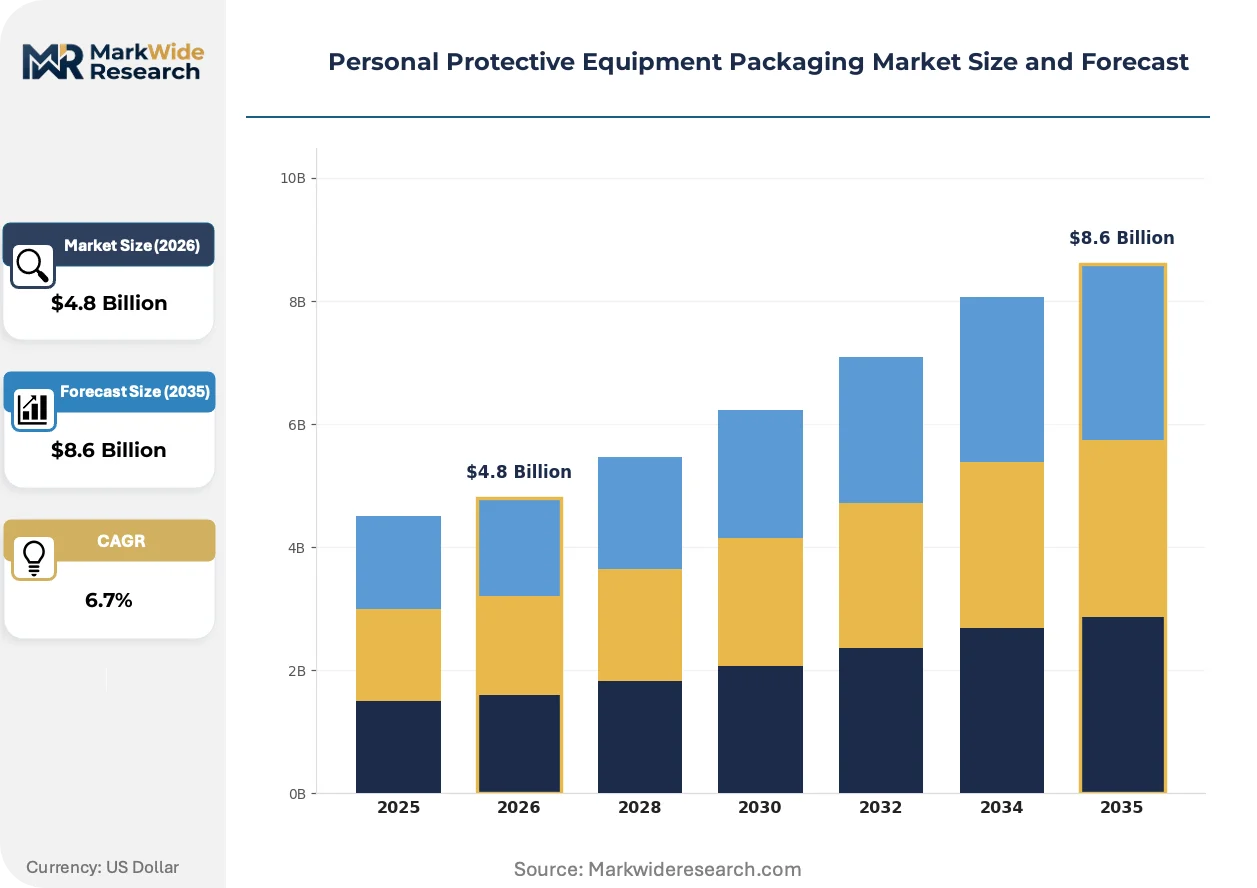
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Blisters, Wrappers Material: Plastic, Paper, Metal, Composite End User: Healthcare, Construction, Manufacturing, Transportation Containment Level: Single-Use, Reusable, Sterile, Non-Sterile |
| Companies Covered | KRB Safety & Packaging, WestRock, Jamestown Container Companies, Packaging Corporation of America, Berry Global, Witmore Enterprises, International Paper Co., Pactiv Evergreen Inc., Production Packaging Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Protective Equipment Packaging Market Strategic Shifts
Digital manufacturing and regulatory chemistry shifts are reconfiguring how sterile barriers are designed, produced, and qualified across healthcare and industrial supply chains.
Polymer-based moisture barrier coatings are decentralizing sterile pouch production away from aluminum-laminate dependency. Mid-size converters in the United States and Germany are adopting aqueous dispersion technologies that deposit nanoclay or bio-based barrier layers onto medical-grade papers. Hospital procurement teams are accepting these alternatives where validation data demonstrates equivalent sterility maintenance, compressing the addressable market for traditional foil laminates.
REACH chemical restriction expansions are forcing material substitutions across European sterile packaging supply chains. ECHA substance of very high concern listings now target phthalate plasticizers and certain epoxy curing agents common in rigid tray coatings. German and Swiss medical device packagers are accelerating qualification of bio-based polyesters and radiation-stable thermoplastic elastomers to maintain CE marking compliance ahead of sunset dates.
Consolidated mask-glove-gown dispenser procurement is reshaping hospital-system buying patterns. Large integrated delivery networks in the United States are specifying modular kit configurations that combine multiple PPE categories into single-SKU dispensers, displacing individual item purchasing. This concentration is visible most acutely in Texas and California health systems where standardization committees mandate unified packaging formats across facility networks.
Personal Protective Equipment Packaging Market Segmentation
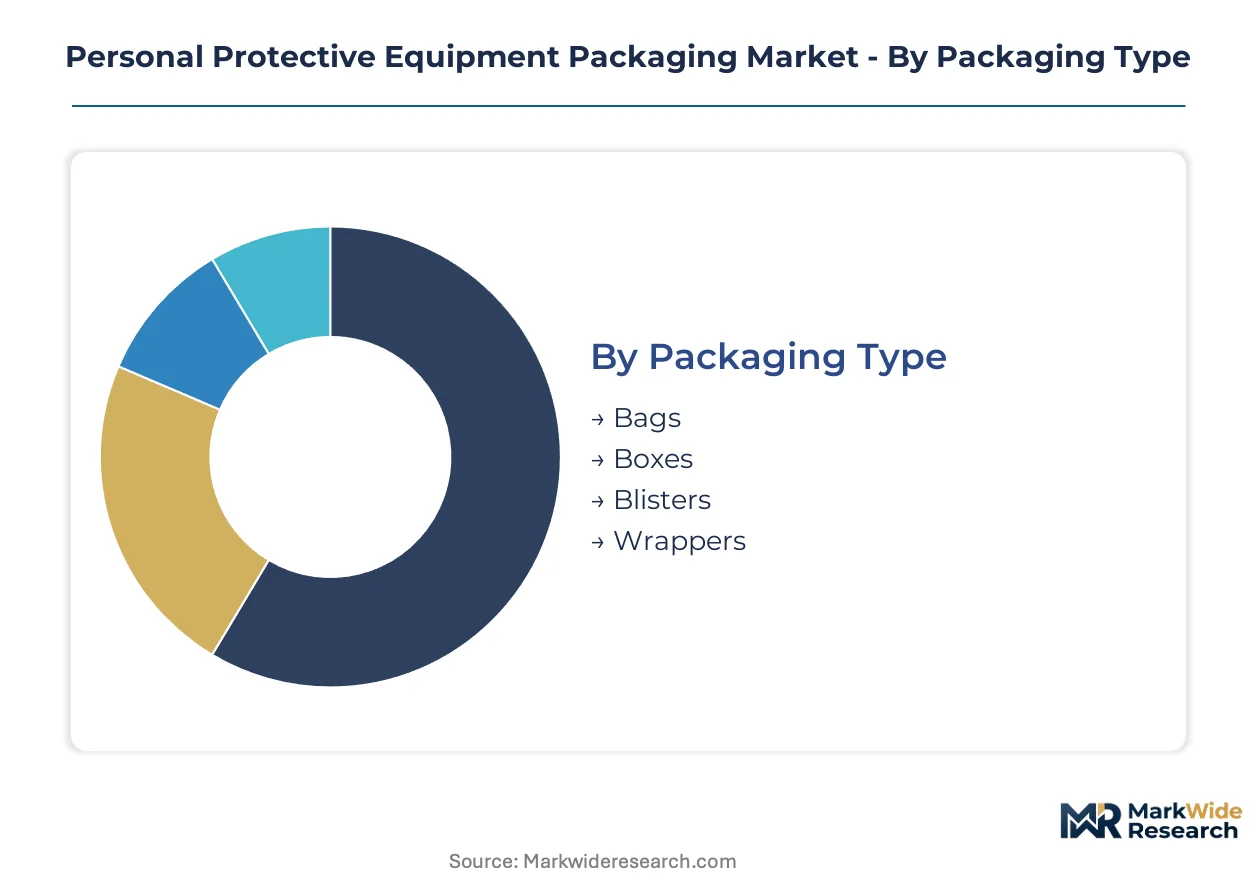
PPE packaging segmentation reveals how sterile barrier requirements, material substitution pressures, and end-use compliance mandates fragment converter capabilities across distinct specification tiers. Each dimension carries divergent qualification timelines and capital intensity that reshape competitive positioning.
Packaging Type:
Supply concentration among specialized pouch and tray converters has created tiered qualification barriers that favor incumbents with validated sterile barrier lines.
- Bags:Peel-open sterile barrier pouches fabricated from multilayer films dominate surgical glove and respirator packaging where aseptic presentation is mandatory. Hospital procurement in Texas and California health systems is consolidating mask-glove-gown kits into single-SKU bag configurations.
- Blisters:Thermoformed rigid trays with lidding films secure N95 respirators and face shields against compression damage through distribution. German industrial distributors specify these for fit-testing kit bundling under OSHA respiratory protection mandates.
- Boxes:Corrugated shipper systems with coated liners consolidate multi-item PPE sets for institutional dispensers. WestRock structural design capabilities anchor hospital-system contracts in the United States.
- Wrappers:Lightweight paper-based enclosures with moisture barrier coatings wrap disposable gowns and coveralls for bulk shipment. Aqueous dispersion nanoclay technologies from mid-size United States and German converters are displacing aluminum-laminate dependency.
Bags absorb the bulk of installed capacity; blisters are expanding most quickly.
Material:
Cost tier stratification separates premium medical-grade laminates from economy fiber-based alternatives, with composite materials commanding intermediate positioning.
- Plastic:Multilayer polyolefin films and ethylene-vinyl acetate seal layers form the backbone of sterile pouch construction. Berry Global in-house production integrates with downstream form-fill-seal automation.
- Composite:Aluminum-polymer laminates and emerging bio-based barrier layers reconcile moisture protection with sustainability targets. Polymer-based coatings are decentralizing production away from Chinese aluminum foil supply concentration.
- Paper:Medical-grade kraft and coated papers serve non-sterile industrial PPE wrapping where fiber-based disposal is preferred. REACH chemical restrictions are accelerating substitution of phthalate-coated grades.
- Metal:Pure aluminum foil and rigid aluminum trays persist in high-barrier pharmaceutical-grade PPE applications. Feedstock volatility among Chinese smelters exposes converters to quota-related disruption.
Plastic commands the largest production footprint; composite materials are climbing the fastest.
End User:
Application-specific validation requirements create customer-type silos where healthcare sterile barriers and industrial durability specifications rarely overlap.
- Healthcare:Surgical centers and hospitals demand ISO 11607-validated sterile barriers with peel-open aseptic presentation for gloves, gowns, and respirators. EU MDR compliance is accelerating pouch and blister procurement from qualified European converters.
- Manufacturing:Industrial facilities specify reusable containment systems for respirator decontamination cycles where lifecycle cost models displace single-use economics. German and Japanese manufacturing segments lead this specification shift.
- Construction:Job site distributors prioritize crush-resistant corrugated dispensers for dust masks and disposable coveralls. OSHA workplace safety mandates drive fit-testing kit bundling requirements.
- Transportation:Aviation and logistics operators require lightweight, stackable shipper configurations for crew PPE provisioning. Export packaging standardization to ISO 11607 aligns with international medical device regulations.
Healthcare dominates current volume; manufacturing reusable systems are gaining share fastest.
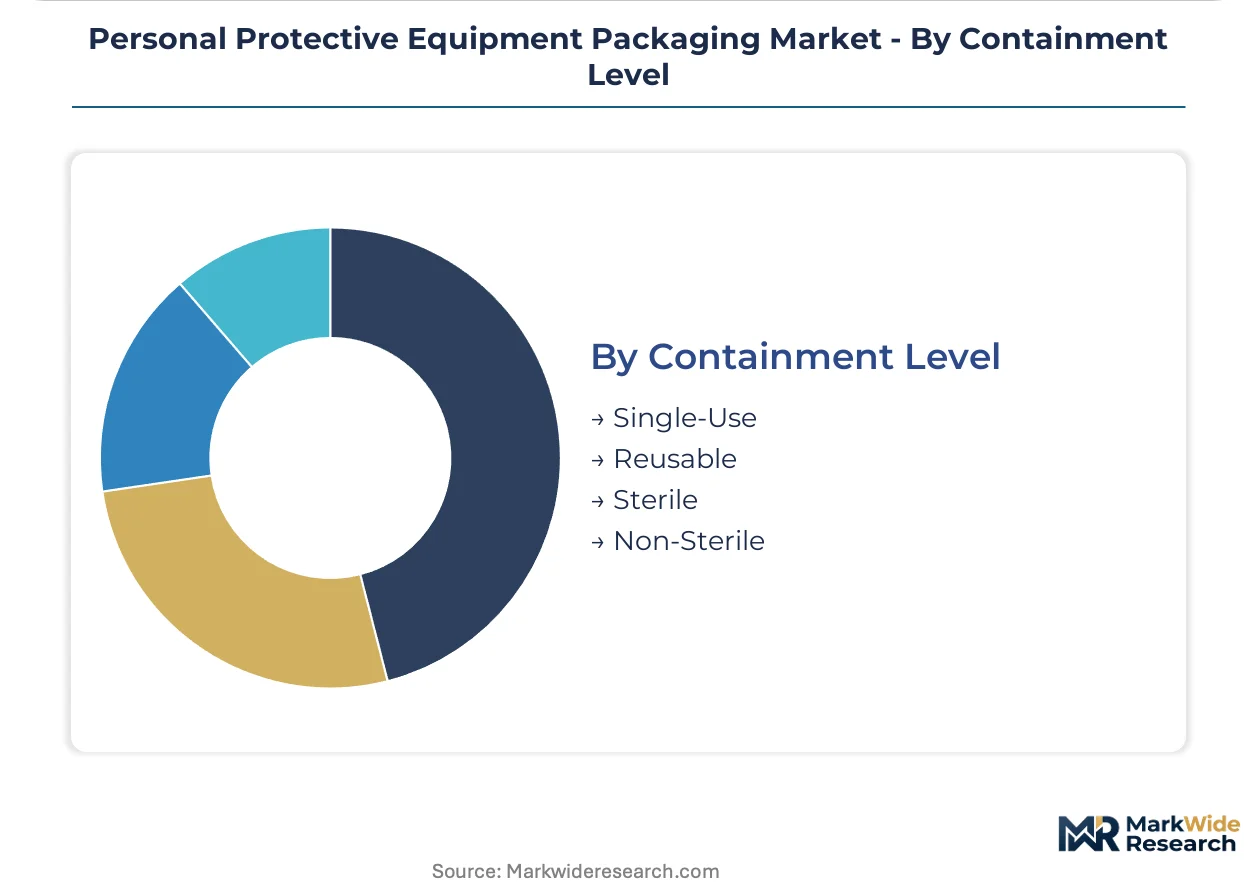
Containment Level:
Maturity gradients separate established single-use sterile barriers from nascent reusable qualification protocols that demand extended durability testing.
- Sterile:Validated barrier systems maintaining aseptic integrity through sterilization, distribution, and point-of-use deployment. FDA 21 CFR Part 820 and ISO 11607 govern validation requirements in the United States.
- Single-Use:Disposable packaging designed for one-time product protection without reuse or reprocessing. This segment spans both sterile and non-sterile applications across healthcare and industrial end uses.
- Reusable:Durable containment systems engineered for multiple decontamination cycles in industrial respirator applications. Germany and Japan manufacturing segments are adopting lifecycle cost models that specify these over disposables.
- Non-Sterile:Basic protective enclosures without microbiological barrier validation for industrial PPE where contamination risk is managed through other controls. Construction and transportation end users specify these for cost-sensitive procurement.
Sterile barriers command the deepest qualification expertise; reusable systems are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of sterile barrier films and aluminum laminates while the United States and Germany consume the most validated packaging for healthcare and industrial applications. This production-consumption divide shapes trade flows and qualification requirements across major markets.
United States
Hospital procurement consolidation in Texas and California health systems drives demand for modular mask-glove-gown dispensers. OSHA respiratory protection mandates expand fit-testing kit specifications for industrial distributors. WestRock anchors hospital-system contracts through corrugated structural design capabilities concentrated in Southeastern manufacturing clusters.
China
Domestic PPE manufacturing scale has created captive demand for medical-grade films and validation documentation aligned with FDA 510(k) and ISO 11607 standards. NMPA regulatory convergence with international medical device frameworks accelerates export packaging standardization. Yangtze River Delta converters dominate aluminum-laminate production for moisture barrier applications.
Germany
Industrial manufacturing segments specify reusable containment systems for respirator decontamination cycles under lifecycle cost models. ECHA REACH chemical restrictions target phthalate plasticizers and epoxy curing agents in rigid tray coatings. Bavarian and Swiss medical device packagers accelerate bio-based polyester qualification to maintain CE marking compliance.
India
Central government health scheme procurement specifies pre-sterilized surgical kits requiring validated primary and secondary packaging systems. CDSCO medical device regulations tighten sterile barrier documentation requirements for imported films. Maharashtra and Gujarat healthcare infrastructure expansion concentrates converter qualification activity in Western industrial corridors.
Japan
Manufacturing facilities adopt durable containment specifications for industrial respirator reuse protocols ahead of single-use displacement trends. METI industrial standards influence packaging durability testing protocols for decontamination cycles. Kansai and Chubu regional industrial clusters specify these systems for automotive and electronics manufacturing PPE provisioning.
Personal Protective Equipment Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered qualification barriers in sterile barrier systems. The vendor base separates into three strategic archetypes: integrated paper and corrugated converters with hospital-system contracting scale, multilayer film specialists with in-house extrusion and form-fill-seal automation, and regional packaging equipment fabricators with retrofit service capabilities. Dominant competitive moves include backward integration into captive film extrusion and strategic partnerships with sterilization validation laboratories to compress qualification timelines.
Among North American-based converters, WestRock and Berry Global exemplify divergent scale strategies within the healthcare sterile barrier segment. WestRock represents the integrated paper and corrugated archetype with structural design-led hospital-system contracting. Berry Global occupies the multilayer film specialist position through in-house production integration with downstream automation. KRB Safety & Packaging anchors the regional equipment and fabrication tier serving mid-size converters with legacy line retrofit requirements.
| Leading Market Players |
|---|
| KRB Safety & Packaging |
| WestRock |
| Jamestown Container Companies |
| Packaging Corporation of America |
| Berry Global |
| Witmore Enterprises |
| International Paper Co. |
| Pactiv Evergreen Inc. |
| Production Packaging Equipment |
| Others |
Value Chain & Pricing Dynamics
Aluminum-laminate feedstock volatility transmits directly through sterile barrier pricing tiers, as Chinese smelter quota restrictions and petrochemical complex concentration along the US Gulf Coast force converters to absorb or pass through input cost swings across healthcare and industrial customer segments.
Pricing Analysis
Margin tightening in multilayer film tiers reflects aluminum foil supply concentration among Yangtze River Delta smelters and ethylene-vinyl acetate seal layer dependencies on Gulf Coast petrochemical infrastructure. Three-tier pricing structure across premium medical-grade laminates, intermediate composite materials, and economy fiber-based alternatives separates validated ISO 11607-compliant systems from non-sterile industrial wrapping. Cost-down pressure on mid-size converters accelerates as hospital procurement consolidation in Texas and California health systems demands volume-scale discounts for modular kit configurations. Manufacturing end users exhibit highest price sensitivity due to lifecycle cost model adoption, while healthcare sterile barrier buyers prioritize qualification reliability over unit economics.
Supply Chain Analysis
Reverse-logistics flows for reusable respirator containment systems in Germany and Japan create secondary distribution channels that compete with single-use disposable supply chains for industrial manufacturing segments. Primary production concentrates in China for aluminum-laminate films, the United States for multilayer polyolefin extrusion, and Germany for precision thermoforming equipment. Raw material dependencies rest on Chinese aluminum foil, US Gulf Coast petrochemical feedstocks, and European REACH-compliant coating chemistries. Single-source vulnerability in aluminum smelter concentration exposes converters to quota-related disruption. Distribution runs through hospital-system consolidated procurement in the United States, industrial distributor networks in Germany, and central government health scheme tendering in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive film extrusion and sterilization validation partnerships determine qualification timeline advantages over competitors dependent on outsourced substrate supply.
For Market Incumbents: Lock in hospital-system contracts through corrugated structural design capabilities and backward integration into multilayer film production, defending against mid-size converters adopting aqueous dispersion nanoclay technologies that threaten aluminum-laminate incumbency. Prioritize sterilization validation laboratory partnerships to compress ISO 11607 qualification pipelines before EPA PFAS restrictions freeze material substitution timelines. For New Entrants and Emerging Players: Direct-to-industrial-distributor digital channels offer the most penetrable route for reusable respirator containment systems in German and Japanese manufacturing segments where lifecycle cost models displace single-use economics. Target decontamination cycle specification gaps with durable containment designs validated to METI industrial standards, leveraging retrofit service capabilities for legacy form-fill-seal line modifications. For Investors and Strategic Acquirers: ECHA REACH chemical restriction sunset dates for phthalate plasticizers and epoxy curing agents are the leading indicator that bio-based polyester qualification capabilities will command acquisition premiums in European medical device packaging. Mid-size converters with validated aqueous barrier coating technologies and established CDSCO documentation pathways in India represent the most defensible long-term positioning. Monitor EPA PFAS restriction enforcement timelines for signals of incumbent coating phase-out acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Multilayer Film Extrusion | Captive supply of ethylene-vinyl acetate seal layers insulates converters from Gulf Coast hurricane disruption exposure. |
| Sterilization Validation Laboratory Partnership | Compressed ISO 11607 qualification timelines enable faster market entry for polymer-based moisture barrier alternatives. |
| Reusable Containment System Development | German and Japanese manufacturing lifecycle cost models specify durable systems over single-use disposables. |
| Digital Printing for Lot-Level Traceability | Thermal inkjet and UV-cure convergence enables variable data directly on sterile barriers, displacing adhesive labels. |
| Hospital-System Modular Kit Configuration | Texas and California health system standardization committees mandate unified packaging formats across facility networks. |
Study Parameters
Trade publications, customs records, and SEC 10-K filings formed the secondary backbone, cross-referenced against primary interviews with sterile barrier validation engineers, hospital procurement managers, industrial distributor category buyers, and form-fill-seal equipment operators. Bottom-up and top-down triangulation reconciled converter capacity announcements with end-user procurement database tracking across healthcare and manufacturing segments.
Bottom-up modeling aggregated segment-level volume assumptions across packaging type, material class, end-user industry, and containment level specifications, while top-down validation tested aggregate figures against macroeconomic healthcare infrastructure spend patterns. CAGRs were derived from regression analysis of historical procurement data and projected regulatory compliance deadlines. Key inputs included ISO 11607 validation pipeline queues, EPA PFAS restriction implementation timelines, and CDSCO medical device regulation convergence milestones.
The model holds under stable regulatory enforcement schedules and raw material supply continuity; deviation in ECHA sunset date acceleration or Chinese aluminum export quota tightening would shift growth trajectories. Practitioners should monitor EPA enforcement guidance and NMPA-FDA regulatory alignment announcements for early signals of material substitution demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market