
 Industrial Potato Graders Market | 2026-2036
Industrial Potato Graders Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Potato Graders Market Outlook
EU Machinery Directive compliance is broadening the cost-of-entry calculus for new entrants into the European market. Key Technology leverages optical sorting expertise to sustain premium positioning across processing plant installations. DOWNS anchors its competitive stance through geographic dominance in Northern European markets. EMVE differentiates via specialized handling systems for delicate potato varieties.
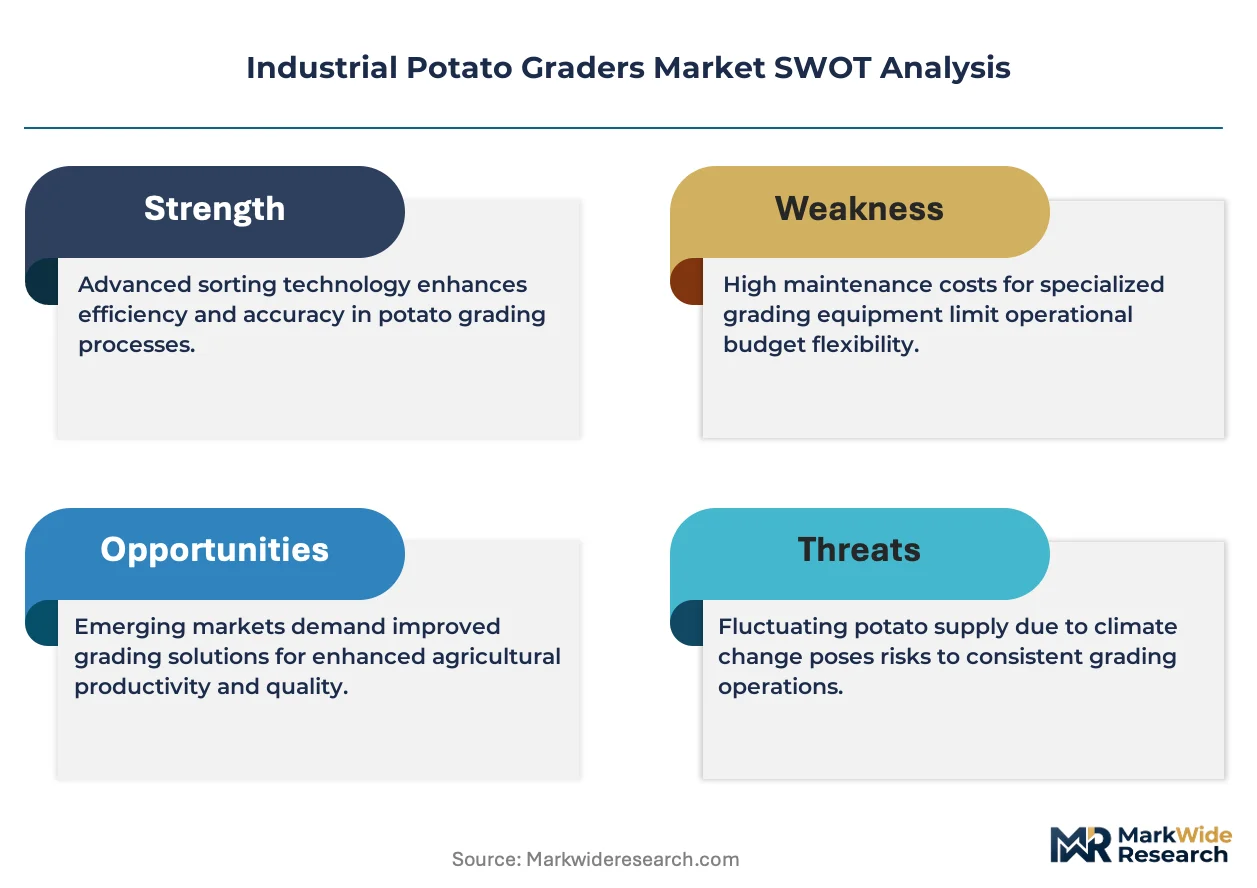
Industrial potato graders are electromechanical systems engineered to classify tubers by size, shape, weight, and surface quality, typically processing 5–50 tonnes per hour depending on configuration. Their primary commercial purpose centers on reducing manual labor, minimizing waste, and ensuring batch consistency for downstream french fry, chip, and dehydrated product manufacturing. Optical sorters within the product type dimension command expanding share as defect-detection thresholds tighten across retail-facing supply chains. Electronic and automated technology segments attract capital allocation faster than mechanical alternatives, though hybrid systems retain relevance in transitional installations serving mid-scale agricultural producers.
FDA food safety modernization requirements in the United States, EU Machinery Directive standards enforced by national regulators, and ISO 9001 quality management frameworks collectively shape equipment certification timelines and cross-border market access. Processing plants and retail chains increasingly specify compliant systems to preempt supply chain disqualification. Stakeholders must weigh upgrade cycles against emerging AI grading capabilities that promise to redefine throughput benchmarks and labor economics.
Market Dynamics
Machine vision and AI-driven defect detection are compressing upgrade cycles across processing plant installations, forcing equipment buyers to reassess depreciation schedules against emerging throughput benchmarks.
Growth Catalysts
- EU Machinery Directive compliance mandates:European processing plants face expanded certification requirements for automated handling equipment, accelerating replacement of legacy mechanical systems with compliant optical sorters.
- French fry manufacturing scale-up:North American quick-service restaurant supply chains are specifying tighter defect-detection thresholds, pulling capital allocation toward high-capacity grading lines.
- Netherlands processing infrastructure density:Concentrated potato processing clusters in Dutch agricultural regions sustain premium equipment procurement rates unmatched by dispersed production geographies.
Market Restraints
- Stainless steel input volatility:Electromechanical grading systems rely heavily on food-grade stainless steel fabrication, exposing equipment margins to commodity price swings in global metals markets.
- Optical component supply concentration:Machine vision subsystems depend on specialized sensor suppliers concentrated in East Asian manufacturing corridors, creating single-source vulnerability for European and North American integrators.
- Mechanical system residual value:Functional legacy graders retain operational utility in mid-scale agricultural operations, extending replacement timelines and compressing new equipment absorption rates.
Strategic Opportunities
- Dehydrated potato product expansion:Growing demand for shelf-stable potato ingredients in prepared foods is creating specification pull for graders capable of handling lower-moisture tuber varieties with minimal bruising.
- USDA processing facility modernization incentives:Federal grant programs targeting rural agricultural infrastructure are lowering effective capital barriers for automated grading adoption among cooperative processors.
- AI-vision and robotic handling convergence:Integration of deep-learning defect classification with adaptive robotic pick-and-place systems opens premium positioning for equipment bundling beyond standalone sorting.
Industry Challenges
- Machine vision technician scarcity:Processing plants face recruitment friction for personnel capable of calibrating AI-driven optical systems, extending commissioning timelines and elevating service contract dependency.
- Legacy line integration complexity:Retrofitting automated graders into existing wash-and-sort sequences requires custom mechanical interfacing, inflating project engineering costs and delaying ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Potato Graders Market |
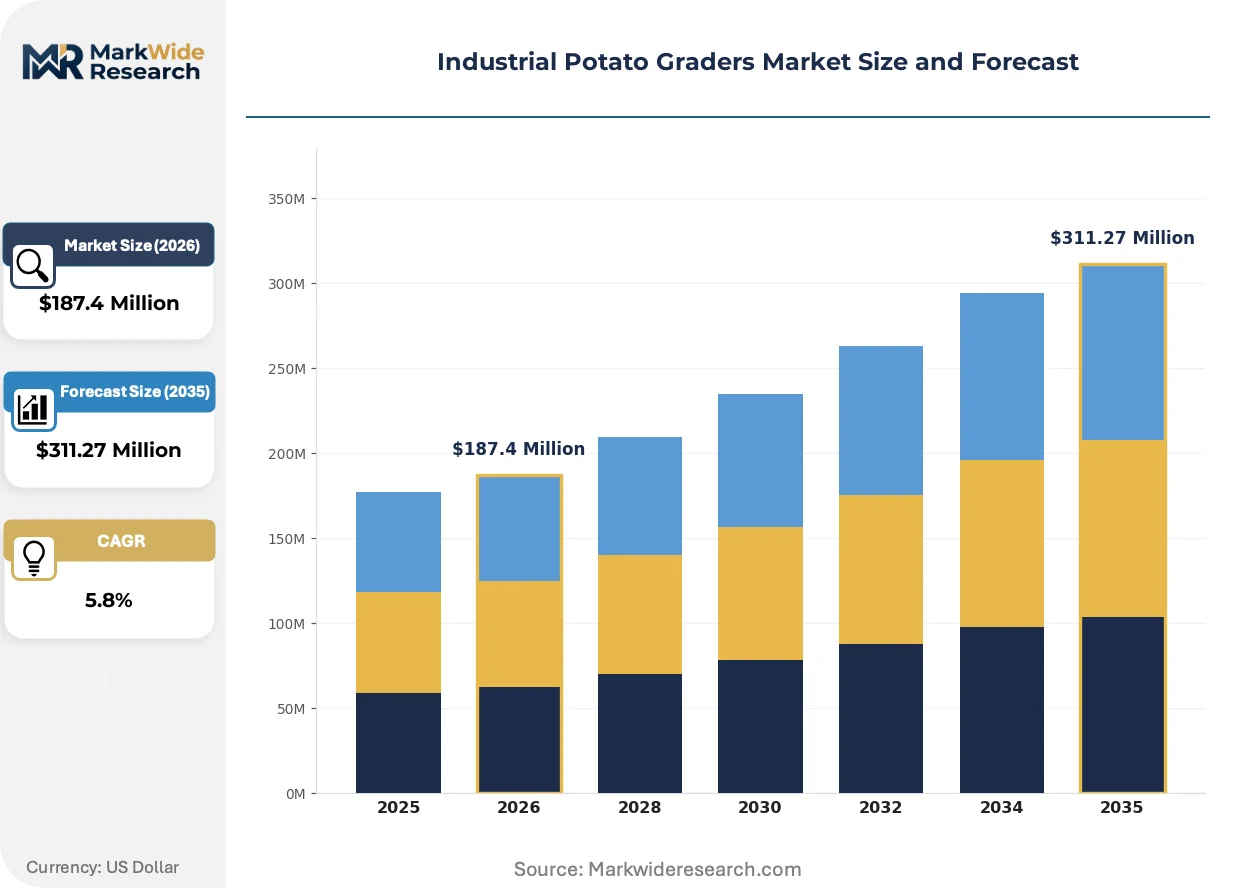
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Graders, Horizontal Graders, Optical Sorters, Weight Graders Technology: Mechanical, Electronic, Automated, Hybrid End User: Agricultural Producers, Processing Plants, Retail Chains, Distributors Installation: On-site, Off-site, Modular, Integrated |
| Companies Covered | Key Technology, DOWNS, EMVE, Tong Engineering, Haith Tickhill Group, Dewulf, Bijlsma Hercules, Ekko Maskiner A/S, Osaw Agro Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Potato Graders Market Strategic Shifts
Optical sorting architectures are absorbing functionality from adjacent inspection technologies, compressing the equipment stack while elevating performance thresholds that mechanical systems cannot match.
Hyperspectral imaging systems are absorbing near-infrared spectroscopy capabilities for internal defect detection, enabling simultaneous surface and subsurface quality assessment in single-pass configurations. High-volume french fry processors in the United States and the Netherlands are piloting these integrated systems at 30-50 tonne-per-hour throughputs. This convergence is absorbing capital previously allocated to separate laboratory sampling infrastructure, compressing quality assurance staffing models.
EU Machinery Directive 2006/42/EC amendments are mandating enhanced safety interlocks and cybersecurity documentation for networked grading equipment, extending certification timelines by four to six months. Processing plant engineering departments are front-loading compliance costs into capital budgets to preempt supply chain disqualification. Optical sorter installations face the steepest compliance burden due to their reliance on embedded software and remote diagnostic connectivity.
After-sales service unbundling is fragmenting traditional equipment procurement relationships, with processing plants negotiating predictive maintenance subscriptions separately from hardware acquisition. German and Dutch cooperatives are leading this disaggregation, treating grading equipment as connected assets with performance-based uptime guarantees. This shift is compressing OEM service margins while elevating third-party technical service provider market entry.
Industrial Potato Graders Market Segmentation
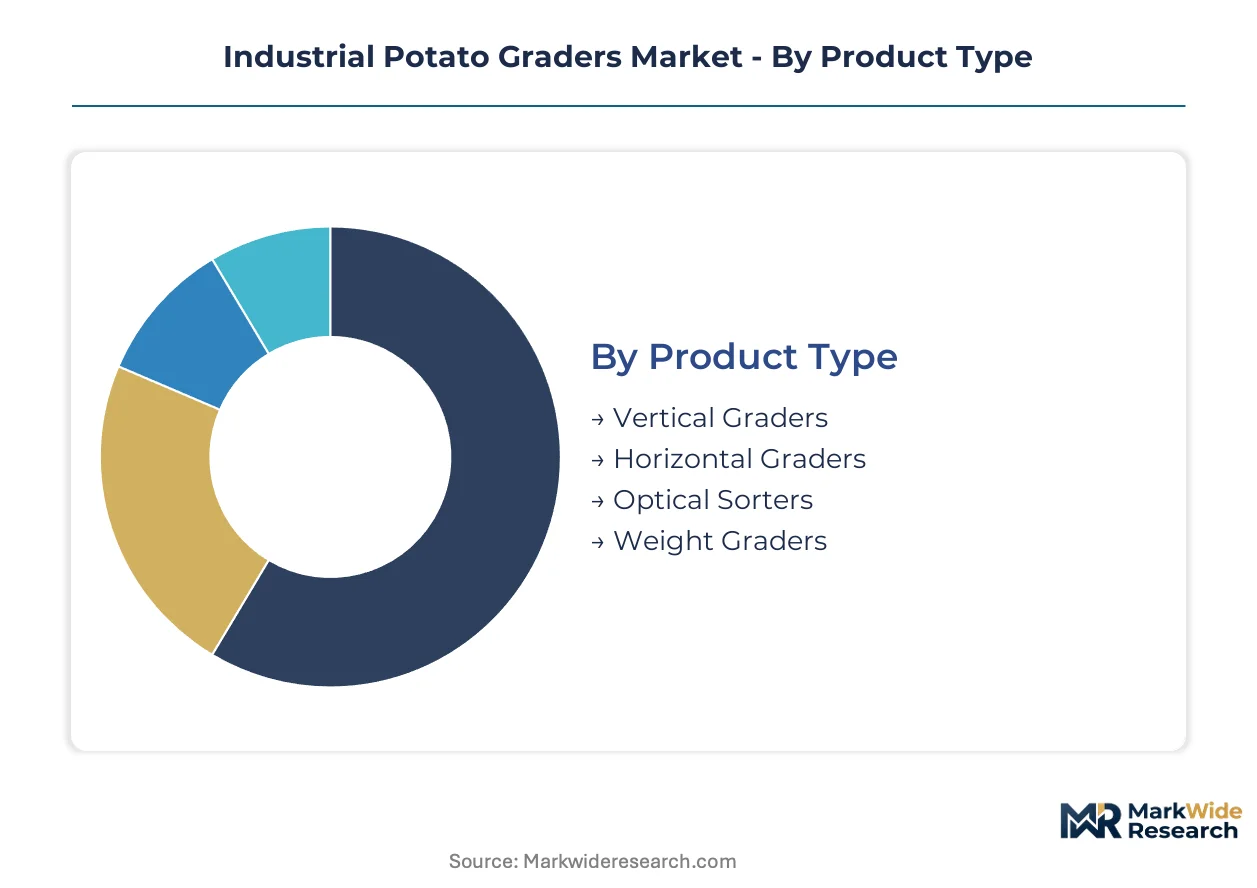
Industrial potato grader procurement varies sharply by operational scale and quality requirements. Equipment specifications diverge between high-volume processors demanding sub-millimeter optical precision and agricultural cooperatives prioritizing mechanical durability over technological sophistication.
Product Type:
Customization intensity spans from standardized mechanical platforms to bespoke optical configurations engineered for specific defect-detection thresholds.
- Vertical Graders:These systems employ gravity-fed roller mechanisms to separate tubers by diameter across stacked sizing decks. Dutch processing clusters in Noord-Brabant and Flevoland specify vertical configurations for their compact footprint and gentle handling of delicate varieties destined for premium chip manufacturing. Leading the category by volume: Vertical Graders. Growing fastest: Optical Sorters.
- Horizontal Graders:Belt-driven lateral conveying enables higher throughputs with modular expansion capacity for seasonal volume spikes. North American french fry processors along the Columbia River Basin favor horizontal architectures for integration with continuous wash-and-peel sequences. The mechanical simplicity supports extended operational lifespans in high-duty-cycle environments.
- Optical Sorters:Machine vision arrays with AI-driven defect classification achieve simultaneous surface blemish detection and subsurface quality inference through hyperspectral imaging. Deployment concentrates in USDA-inspected facilities serving quick-service restaurant supply chains with zero-tolerance foreign object protocols.
- Weight Graders:Load-cell-based mass classification systems provide batch consistency for dehydrated product specifications where moisture content variability demands precise portion control. Agricultural cooperatives in Idaho and Wisconsin deploy weight graders upstream of bulk storage to optimize freight economics.
Leading the category by volume: Vertical Graders. Expanding most quickly: Optical Sorters.
Technology:
Capital allocation intensity separates established mechanical installations from emerging autonomous platforms requiring specialized commissioning expertise.
- Mechanical:Roller-and-screen architectures with minimal electronic content dominate mid-scale agricultural operations where technician availability constrains maintenance complexity. These systems retain relevance in regions with intermittent power reliability.
- Electronic:Sensor-integrated platforms with programmable logic controllers enable size-sorting precision unattainable through purely mechanical means. European processing plants facing EU Machinery Directive compliance deadlines favor electronic retrofits as transitional investments.
- Automated:Fully autonomous grading lines with robotic handling and real-time quality feedback loops command premium positioning. Deployment concentrates in Netherlands-based facilities where labor costs and throughput requirements justify comprehensive automation.
- Hybrid:Configurations blending mechanical conveying with optical inspection stations offer phased upgrade pathways for capital-constrained operations. USDA rural development grant recipients frequently specify hybrid architectures to balance immediate compliance needs against future AI-vision integration.
Highest installation base: Mechanical systems. Steepest adoption trajectory: Automated platforms.
End User:
Procurement sophistication correlates with downstream quality liability exposure and batch traceability requirements.
- Agricultural Producers:Grower-owned cooperatives prioritize equipment durability and field-service accessibility over detection sensitivity. These buyers represent the most price-elastic segment, often deferring replacement until mechanical failure forces capital deployment.
- Processing Plants:Dedicated french fry, chip, and dehydrated product manufacturers specify graders capable of 30-50 tonne-per-hour throughputs with integrated data logging for HACCP documentation. FDA Food Safety Modernization Act compliance mandates drive accelerated replacement cycles in this segment.
- Retail Chains:Private-label potato product programs impose upstream quality specifications that cascade to contracted grading equipment. These buyers rarely own graders directly but influence procurement through approved supplier lists and audit protocols.
- Distributors:Bulk handling intermediaries require rapid grade segregation to optimize mixed-origin shipments. Equipment specifications emphasize throughput flexibility across variable tuber quality profiles rather than detection precision.
Dominant procurement volume: Processing Plants. Fastest specification tightening: Retail Chains.
Installation:
Site configuration flexibility determines project engineering complexity and commissioning timeline duration.
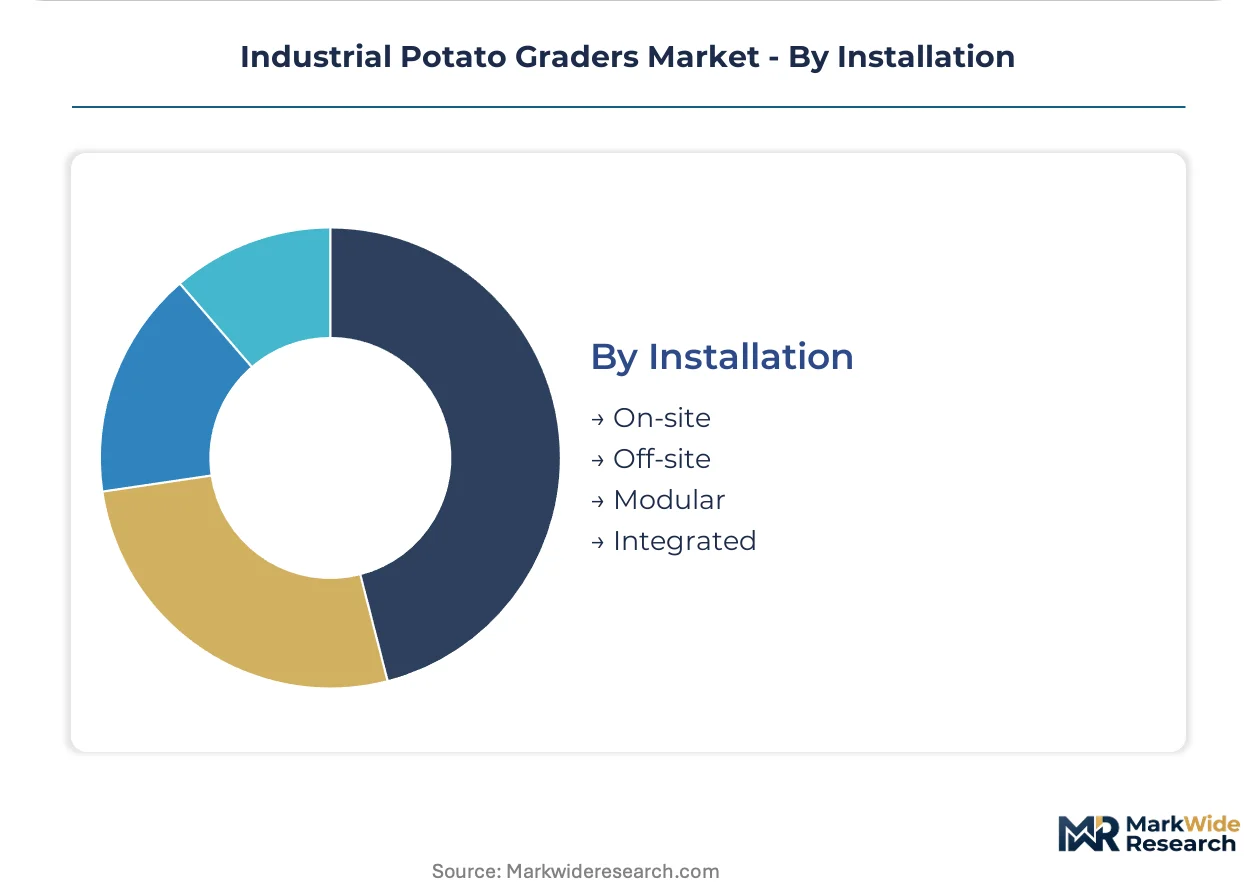
- On-site:Permanent foundations with custom material handling integration suit high-capacity processing plants with stable throughput forecasts. These installations require extensive civil engineering and utility provisioning.
- Off-site:Centralized grading facilities serving multiple agricultural producers enable equipment utilization rates unattainable through dispersed ownership. Dutch cooperative structures favor this model to amortize capital across grower memberships.
- Modular:Containerized or skid-mounted platforms support seasonal deployment patterns and rapid relocation between harvest regions. USDA facility modernization incentives increasingly specify modular architectures for rural cooperative processors.
- Integrated:Grading subsystems embedded within continuous processing lines demand precise mechanical interfacing with upstream washing and downstream packaging equipment. These configurations carry the highest engineering risk and longest commissioning schedules.
Most prevalent deployment: On-site installations. Gaining share fastest: Modular configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch agri-tech SEZs and USDA rural development zones concentrate capital deployment for automated grading infrastructure. Equipment procurement clusters mirror downstream processing density.
United States
USDA facility modernization grants and quick-service restaurant supply chain specifications drive optical sorter adoption. FDA Food Safety Modernization Act mandates compress replacement cycles for legacy mechanical installations. Columbia River Basin processing corridors in Washington and Oregon anchor high-capacity french fry grading line deployments.
Netherlands
Noord-Brabant and Flevoland processing clusters sustain premium equipment procurement unmatched by dispersed geographies. EU Machinery Directive 2006/42/EC amendments extend certification timelines for networked grading equipment. Wageningen-adjacent R&D corridors pilot hyperspectral imaging integration at 50-tonne-per-hour throughputs.
Germany
Baden-Württemberg mechanical engineering traditions support precision fabrication for export-oriented grading systems. CE marking and cybersecurity documentation requirements inflate compliance costs for software-embedded optical sorters. Bavarian agricultural cooperatives negotiate predictive maintenance subscriptions separately from hardware acquisition.
Canada
Prairie Provinces potato production corridors deploy modular grading configurations for seasonal harvest mobility. Health Canada and CFIA food safety protocols align with USDA specifications for cross-border supply chain integration. Alberta processing facilities leverage federal agricultural infrastructure programs for automated line upgrades.
United Kingdom
East Anglia and Lincolnshire growing regions face post-EU regulatory divergence in machinery certification timelines. HSE machinery safety standards and evolving UKCA marking requirements create transitional compliance friction for continental equipment suppliers. Yorkshire-based cooperatives balance mechanical durability against AI-vision upgrade pathways.
Industrial Potato Graders Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base separates into three strategic archetypes: optical technology integrators, mechanical fabrication traditionalists, and hybrid system assemblers serving transitional installations. Consolidation pressure concentrates among mid-scale European fabricators facing EU compliance cost escalation. Dominant competitive moves include geographic expansion into North American processing corridors and technology licensing partnerships for AI-vision subsystems.
Within the optical specialization tier, Key Technology and DOWNS exemplify divergent geographic anchoring strategies. Key Technology represents North American technology integration approaches. DOWNS occupies a position within Northern European market concentration patterns. EMVE exemplifies handling-system specialization for delicate variety applications. Tong Engineering and Haith Tickhill Group sit within British mechanical fabrication traditions serving Commonwealth agricultural markets.
| Leading Market Players |
|---|
| Key Technology |
| DOWNS |
| EMVE |
| Tong Engineering |
| Haith Tickhill Group |
| Dewulf |
| Bijlsma Hercules |
| Ekko Maskiner A/S |
| Osaw Agro Industries |
| Others |
Value Chain & Pricing Dynamics
EU Machinery Directive 2006/42/EC cybersecurity documentation mandates gate qualified supply access for optical sorter manufacturers, forcing premium-tier pricing for compliant systems while excluding non-certified fabricators from Dutch and German processing plant procurement.
Pricing Analysis
Lead-time compression commands measurable premiums in this market, with expedited optical sorter delivery attracting 15-25% markups over standard schedules while spot mechanical inventory clears at discounted rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by AI-vision integration depth and CE marking completeness. Cost compression in mechanical tiers is intensifying because stainless steel input volatility transfers directly to bill-of-materials exposure. Agricultural cooperatives in Idaho and Wisconsin exhibit highest price elasticity, while Netherlands-based french fry processors demonstrate lowest sensitivity due to throughput-dependent ROI calculations.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European equipment logistics, with hub-and-spoke patterns radiating toward Noord-Brabant processing clusters and Columbia River Basin installations. Component sourcing draws from Germany for precision mechanical fabrication, the Netherlands for optical subsystem integration, and East Asia for specialized machine vision sensors. Single-source vulnerability concentrates in CMOS sensor supply from Taiwanese and South Korean foundries. Distribution runs through OEM-direct channels for large processing plants and agricultural equipment dealers serving cooperative buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial potato graders occupy a technology-transition phase where AI-driven optical sorting is systematically displacing mechanical roller architectures across high-volume processing installations.
For Market Incumbents: Anticipate margin compression from hyperspectral imaging commoditization by securing captive supply of specialized optical components through backward integration into sensor distribution partnerships. Prioritize EU Machinery Directive certification pre-loading to accelerate commissioning timelines against emerging competitors lacking compliance infrastructure. For New Entrants and Emerging Players: Begin with modular hybrid configurations targeting USDA rural development grant recipients in Prairie Provinces and American Midwest cooperative processors, where capital constraints favor phased automation pathways over comprehensive optical installations. Emphasize predictive maintenance subscription bundling to differentiate from established OEM service relationships. For Investors and Strategic Acquirers: First hyperspectral imaging pilot deployments achieving 50-tonne-per-hour throughput without laboratory sampling infrastructure is the leading indicator that AI-vision convergence has reached commercial tipping point. Target acquisition archetypes include specialized handling system fabricators with established Dutch agricultural relationships and optical subsystem integrators possessing FDA-compliant software documentation. Monitor EU Machinery Directive amendment enforcement timelines as regulatory acceleration signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Imaging Integration | Absorbs laboratory sampling capital while compressing quality assurance staffing at USDA-inspected facilities. |
| Predictive Maintenance Subscription Unbundling | Transforms equipment economics toward performance-based uptime guarantees for Dutch cooperative structures. |
| EU Machinery Directive Pre-Certification | Compresses four-to-six month approval timelines that disqualify non-compliant competitors from tender participation. |
| Modular Containerized Deployment | Enables seasonal mobility across Prairie Provinces harvest corridors while qualifying for federal infrastructure incentives. |
| Robotic Handling Convergence | Opens premium bundling beyond standalone sorting through AI-vision and adaptive pick-and-place integration. |
Study Parameters
Document review covered EU Machinery Directive amendment filings, FDA Food Safety Modernization Act guidance documents, and USDA facility modernization grant disclosures, complemented by interviews with plant engineering directors at french fry processors, agricultural cooperative procurement managers, and aftermarket service heads at optical subsystem integrators. Secondary validation drew from SEC equipment manufacturer filings, Dutch agri-tech SEZ investment databases, and Columbia River Basin processing corridor development records. Bottom-up installation data triangulated against top-down capital expenditure estimates across the analysis window.
Segment-level outputs reflect modeling across product type, technology tier, end-user sophistication, and installation configuration dimensions throughout the forecast period. CAGRs derived from equipment replacement cycle compression rates and regulatory mandate acceleration curves. Industry-specific inputs included stainless steel price volatility indices, machine vision technician wage inflation, and hyperspectral imaging patent filing velocity.
Underlying measurement precision varies by segment; optical sorter and automated technology tiers carry tighter precision than mechanical legacy categories due to concentrated vendor disclosure. Forecasts reflect documented assumptions regarding EU enforcement timelines, USDA grant continuation, and AI-vision component cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Lawn Shredder Market