
 Horse Drawn Farming Equipment Market | 2026-2036
Horse Drawn Farming Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Horse Drawn Farming Equipment Market Foresight
Specialty agricultural retail channels are tilting toward heritage and organic farming networks as mainstream farm-supply distributors reduce shelf space for non-mechanized tools. B W Macknair & Son leverages its Scottish craftsmanship heritage to dominate premium plow exports across Northern Europe. Pioneer Equipment Inc. anchors its position in North America through dedicated Amish and Mennonite community relationships. I&J Manufacturing competes on cast-iron durability for heavy-soil applications in the American Midwest.
Horse drawn farming equipment encompasses tillage, planting, and cultivation implements pulled by draft animals rather than tractor power, typically constructed with steel frames and hardwood handles designed for manual depth adjustment and animal-harness compatibility. These tools serve small-acreage farmers, heritage agriculture educators, and organic certification holders seeking fossil-fuel-free cultivation methods. Plows and harrows occupy the largest equipment-type share due to their foundational role in primary tillage across diverse soil conditions. Steel and cast iron materials command preference among commercial smallholders prioritizing implement longevity over the lighter weight of aluminum alternatives. The end-user base fragments across full-time farmers requiring production-scale reliability and hobbyist segments valuing historical authenticity.
The United States Department of Agriculture administers organic certification standards that indirectly validate horse-powered cultivation as compliant with synthetic-input restrictions, while the European Union's CE marking and machinery safety directives govern import eligibility for non-powered implements. ISO standards for agricultural equipment durability testing provide voluntary benchmarks that quality-focused manufacturers adopt to differentiate in premium segments. Stakeholders must monitor evolving organic subsidy structures and draft-animal welfare regulations that could either accelerate or constrain equipment replacement cycles.
Market Dynamics
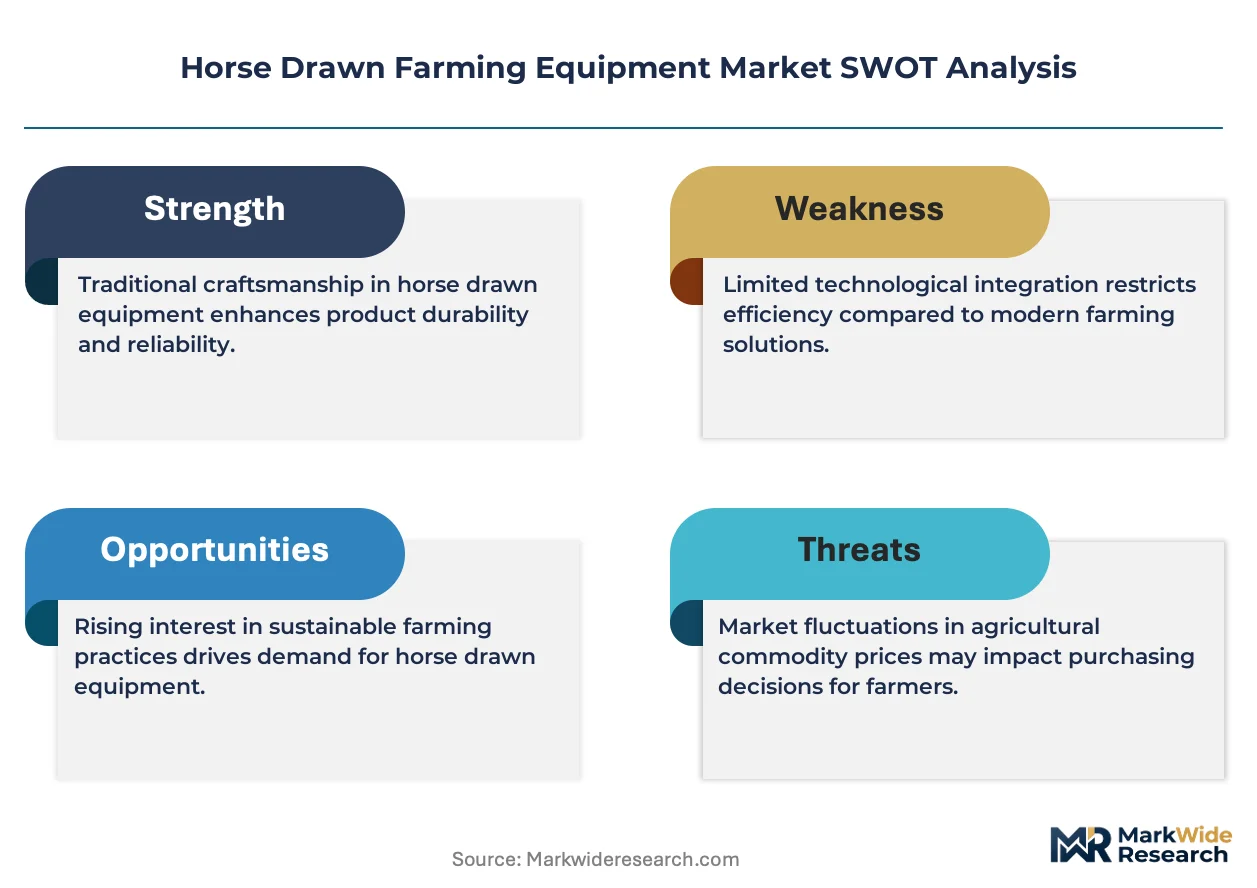
Heritage farming collectives and organic certification requirements are pulling draft-animal cultivation from historical preservation into active production agriculture, restructuring equipment demand around durability standards and fossil-fuel compliance rather than nostalgia alone.
Growth Catalysts
- USDA Organic Certification:Synthetic-input restrictions validate horse-powered tillage as compliant cultivation, expanding addressable acreage for draft-animal operations across certified smallholdings.
- Poland's Agricultural Heartland:Organic cooperatives are revitalizing draft-horse practices, concentrating equipment demand in Central European soil conditions requiring heavy-duty cast-iron implements.
- F-Gas Regulation:The European Union's tightening machinery safety directives and fluorinated gas restrictions indirectly favor non-powered equipment imports by raising compliance costs for mechanized alternatives.
Market Restraints
- Steel Input Volatility:Cast-iron and steel frame costs fluctuate with scrap metal and foundry energy prices, compressing margins for manufacturers serving price-sensitive hobbyist segments.
- CE Marking Friction:The European Union's machinery safety directives create import eligibility barriers for small-scale producers lacking certification infrastructure, concentrating supply among established Northern European craftsmen.
- Tractor Mechanization:Compact utility tractors and two-wheel tractor substitutes offer comparable acreage coverage with lower labor intensity, threatening replacement demand in transitional farming operations.
Strategic Opportunities
- Amish and Mennonite Networks:Dedicated community relationships in North American plain-sect agriculture represent captive demand for production-scale reliability and animal-harness compatibility standards.
- Heritage Education Channels:Agricultural museums and historical farming programs are emerging as institutional purchasers, creating equipment specifications distinct from commercial durability requirements.
- ISO Durability Benchmarks:Voluntary adoption of agricultural equipment testing standards allows quality-focused manufacturers to differentiate premium segments from commodity alternatives.
Industry Challenges
- Draft-Animal Husbandry Expertise:Declining veterinary and farrier training programs constrain operator supply, lengthening equipment payback periods for new entrants lacking animal-management skills.
- Manual Depth Adjustment Calibration:Hardwood handle and steel frame interfaces require skilled fitting for soil-specific performance, creating service bottlenecks where dealer networks are sparse.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horse Drawn Farming Equipment Market |
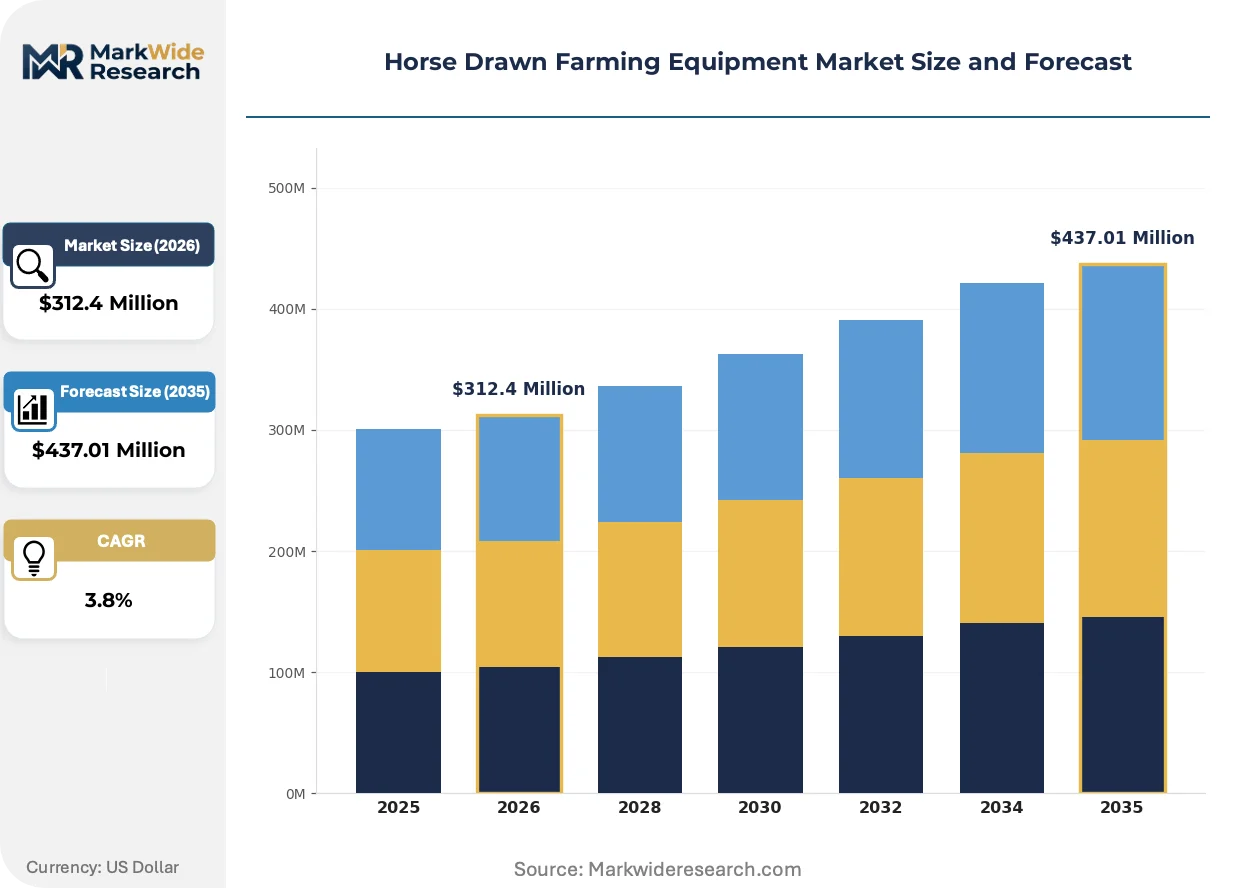
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Plows, Harrows, Seeders, Cultivators Material: Wood, Steel, Cast Iron, Aluminum Application: Agriculture, Gardening, Landscaping, Soil Preparation End User: Farmers, Hobbyists, Educational Institutions, Community Gardens |
| Companies Covered | John Deere, Case IH, B W Macknair & Son, Pioneer Equipment Inc., Allen Machinery & Equipment, I&J Manufacturing, Avril Industrie, Hesston Corporation, Capodanno Villa Mazzucchelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horse Drawn Farming Equipment Market Shifts & Advancements
Digital documentation tools and precision measurement systems are virtualizing traditional equipment specifications, enabling remote fitting and standardization across dispersed heritage farming networks.
Composite reinforcement materials are penetrating hardwood handle construction, reducing weight while maintaining shock absorption for animal-harness compatibility. Heritage equipment restorers in Scotland and Pennsylvania are adopting these hybrids for export markets. The technology is virtualizing the trade-off between implement longevity and draft-animal fatigue, compressing replacement cycles for premium segments.
REACH chemical restrictions and the EU Green Deal's embodied-carbon tracking requirements are reshaping import documentation for steel and cast-iron components. Northern European manufacturers face heightened disclosure obligations for foundry energy sources. Polish organic cooperatives are responding by prioritizing CE-marked suppliers with verified low-carbon production, tilting procurement toward established Scottish and German craftsmen.
Specialty agricultural retail is fragmenting as mainstream farm-supply distributors reduce shelf space for non-mechanized tools. Amish buying cooperatives and heritage farming collectives are consolidating purchase volumes through direct manufacturer relationships, bypassing traditional dealer markups. This channel disintermediation is most visible in the American Midwest, where I&J Manufacturing and Pioneer Equipment Inc. maintain dedicated community sales structures.
Horse Drawn Farming Equipment Market Segmentation
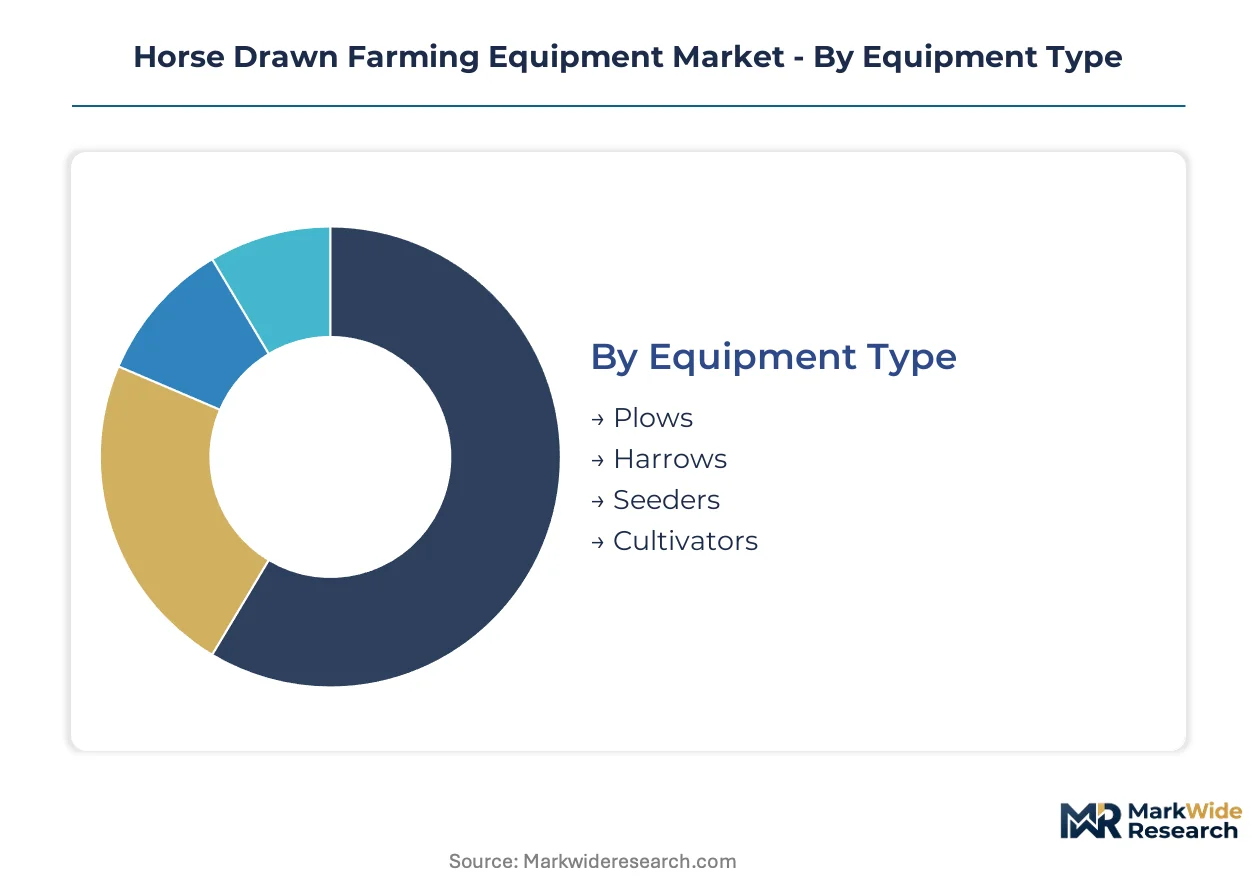
Segmentation in horse drawn farming equipment reveals how distinct user requirements reshape material specifications and durability expectations. Heritage agriculture educators prioritize historical authenticity over soil performance, while commercial organic operators demand cast-iron longevity under heavy tillage cycles.
Equipment Type:
Primary tillage operations span soil-breaking, seedbed preparation, and between-row cultivation across varying acreage scales and draft-animal team sizes.
- Plows:Moldboard and disc configurations cut and invert soil for initial cultivation passes. Demand concentrates in Poland's organic cooperatives where heavy clay soils require reinforced steel shares and adjustable coulter depth mechanisms.
- Harrows:Chain, disc, and spring-tooth designs pulverize clods and level seedbeds after primary tillage. Amish farming networks in Pennsylvania and Ohio drive specification requirements for frame durability across rocky glacial till soils.
- Seeders:Broadcast and row-drop mechanisms meter seed distribution behind draft-animal teams. Heritage farming collectives in Scotland specify hardwood seed boxes with brass fittings for heritage wheat varietal preservation.
- Cultivators:Sweep and shovel attachments perform between-row weed control in standing crops. Community gardens in North American urban centers favor lightweight aluminum frame cultivators for raised-bed vegetable production.
The dominant share belongs to Plows, while Cultivators are gaining share fastest through urban agriculture expansion.
Material:
Component selection trades weight against fatigue resistance, with foundry energy costs and embodied-carbon tracking reshaping procurement priorities.
- Steel:High-carbon alloy frames and wear components deliver tensile strength for heavy-soil tillage. Polish organic cooperatives prioritize CE-marked suppliers with verified low-carbon foundry production under EU Green Deal requirements.
- Cast Iron:Ductile iron moldboards and frog assemblies withstand abrasive soil conditions across extended service intervals. Scottish craftsmanship heritage dominates premium export specifications for Northern European heritage agriculture networks.
- Wood:White oak and hickory handles provide shock absorption and manual adjustment ergonomics. REACH chemical restrictions constrain preservative treatments for EU import eligibility.
- Aluminum:Extruded frame sections reduce implement weight for single-animal operations and elderly operators. Hobbyist segments in American suburban markets favor aluminum for garage storage portability.
Cast Iron commands the volume lead in commercial applications, though Aluminum is expanding most quickly through entry-level hobbyist channels.
Application:
Task-specific implement geometry varies by soil disturbance depth, residue management requirements, and crop rotation complexity.
- Agriculture:Production-scale tillage and planting across certified organic acreage. USDA Organic Certification validates fossil-fuel-free cultivation methods for synthetic-input restricted operations.
- Soil Preparation:Initial site conversion and amendment incorporation for new cultivation areas. Poland's agricultural heartland concentrates demand for deep-ripening subsoilers in grassland-to-arable transitions.
- Gardening:Small-scale vegetable and flower bed maintenance with single-animal or hand-guided implements. Community gardens in Minneapolis and Portland specify narrow-track cultivators for intensive raised-bed systems.
- Landscaping:Ornamental turf establishment and maintenance in estate and park settings. Scottish estate managers commission decorative moldboard plows for heritage demonstration events.
Agriculture holds the established revenue base, while Soil Preparation is climbing the fastest through grassland reversion programs.
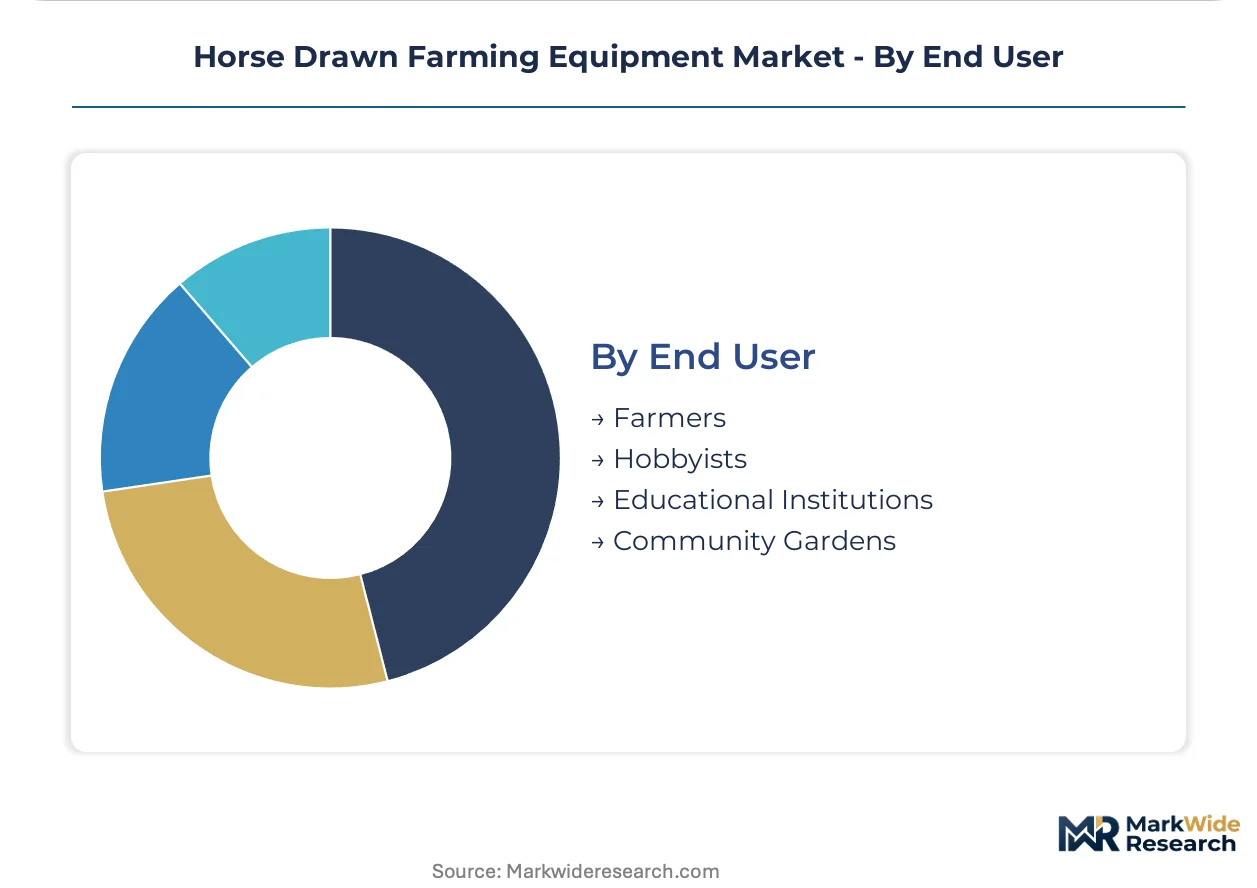
End User:
Purchasing authority fragments across production economics, educational mission requirements, and volunteer coordination structures.
- Farmers:Full-time operators requiring production-scale reliability and animal-harness compatibility. Amish and Mennonite networks in Indiana and Wisconsin represent captive demand through dedicated manufacturer relationships.
- Hobbyists:Part-time practitioners valuing historical authenticity and mechanical simplicity. Heritage equipment restorers in Pennsylvania adopt composite-reinforced hardwood handles for reduced draft-animal fatigue.
- Educational Institutions:Agricultural museums and university programs demonstrating pre-mechanized cultivation techniques. Living history sites in Scotland specify museum-grade finishes for public demonstration durability.
- Community Gardens:Volunteer-coordinated urban agriculture projects with shared implement pools. Direct manufacturer relationships bypass traditional dealer markups in Midwestern cooperative buying structures.
Farmers retain the dominant procurement volume, though Educational Institutions are expanding most rapidly through heritage agriculture curriculum investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA anchors North American demand through organic certification standards that validate draft-animal cultivation methods. Equipment procurement concentrates where heritage farming networks intersect with fossil-fuel compliance requirements.
United States
Amish and Mennonite farming communities in Pennsylvania, Ohio, and Indiana drive specification requirements for animal-harness compatibility and production-scale durability. The USDA's National Organic Program indirectly validates horse-powered tillage as compliant with synthetic-input restrictions. Lancaster County, Pennsylvania, anchors the densest concentration of plain-sect equipment procurement through dedicated manufacturer relationships.
Poland
Organic cooperatives in the agricultural heartland are revitalizing draft-horse cultivation practices across heavy clay soil conditions. The EU's F-Gas Regulation and machinery safety directives raise compliance costs for mechanized alternatives, indirectly favoring non-powered imports. The Masovian and Podlaskie Voivodeships concentrate demand for CE-marked cast-iron implements from Scottish and German suppliers.
Germany
Heritage agriculture educators and organic smallholders in Bavaria and Baden-Württemberg prioritize ISO durability benchmarks for tillage equipment. The EU Green Deal's embodied-carbon tracking requirements reshape procurement toward verified low-carbon foundry production. The Black Forest region hosts equipment restoration networks that export museum-grade specifications across Northern Europe.
United Kingdom
Scottish craftsmanship heritage dominates premium plow exports through Northern European heritage agriculture networks. REACH chemical restrictions constrain preservative treatments for hardwood handle components. The Scottish Borders and Aberdeenshire concentrate foundry capacity serving heritage farming collectives with verified carbon-disclosure documentation.
Canada
Heritage education channels in Ontario and Quebec agricultural museums drive institutional procurement distinct from commercial durability requirements. Health Canada and PMRA administer pesticide regulations that indirectly validate fossil-fuel-free cultivation for organic certification holders. The Ottawa Valley and Eastern Townships host living history sites specifying decorative moldboard plows for public demonstration.
Horse Drawn Farming Equipment Market Competitive Landscape
Craft heritage specialists and production-scale fabricators split the market along authenticity-versus-durability lines. The vendor base concentrates among regional foundries with multi-generational tooling expertise rather than diversified agricultural machinery conglomerates. Two strategic archetypes dominate: Scottish and Northern European craftsmen leveraging heritage positioning for premium export segments, and North American fabricators embedding within plain-sect community networks for captive demand. Competitive moves center on direct manufacturer relationships that bypass traditional dealer markups, plus CE marking investments that unlock EU import eligibility.
Within the craft heritage tier, B W Macknair & Son exemplifies Scottish foundry positioning across Northern European heritage networks. Pioneer Equipment Inc. and I&J Manufacturing occupy complementary positions in North American plain-sect agriculture, with the former anchoring Amish and Mennonite community relationships and the latter representing production-scale durability specifications for heavy-soil Midwestern applications. John Deere and Case IH represent diversified agricultural machinery conglomerates whose presence in this niche reflects portfolio breadth rather than strategic concentration.
| Leading Market Players |
|---|
| John Deere |
| Case IH |
| B W Macknair & Son |
| Pioneer Equipment Inc. |
| Allen Machinery & Equipment |
| I&J Manufacturing |
| Avril Industrie |
| Hesston Corporation |
| Capodanno Villa Mazzucchelli |
| Others |
Supply & Pricing Matrix
The Scottish Borders foundry cluster anchors premium cast-iron capacity for Northern European heritage agriculture networks, translating multi-generational tooling expertise into pricing power over CE-marked plow exports. Polish organic cooperatives absorb these premiums to satisfy EU Green Deal embodied-carbon documentation requirements, compressing margins for non-certified competitors.
Pricing Analysis
Geographic price spreads between Scottish premium exports and Midwestern production-scale fabricators exceed two-to-one ratios for comparable moldboard specifications. Three-tier pricing structure across heritage-craft, commercial-durable, and entry-hobbyist levels separates buyers by certification requirements and animal-harness compatibility standards. Cost compression in the aluminum-entry tier is intensifying because scrap metal volatility and foundry energy expenses squeeze hobbyist-segment margins. Amish buying cooperatives exhibit the lowest price sensitivity due to captive community relationships, while urban community gardens drive hardest bargaining through direct manufacturer negotiations.
Supply Chain Analysis
Contract manufacturing concentrates among Scottish heritage foundries, Pennsylvania plain-sect metalworkers, and Polish agricultural equipment fabricators holding regional CE-marking infrastructure. Raw material flows draw from Swedish specialty steel mills, domestic scrap metal recovery networks, and Baltic hardwood suppliers for handle components. Single-source vulnerability runs through the Scottish Borders for museum-grade cast-iron frog assemblies, where generational tooling knowledge resists rapid replication. Distribution runs through Amish buying cooperatives and heritage farming collectives that bypass traditional agricultural retail markups through direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as USDA Organic Certification and EU F-Gas Regulation simultaneously validate fossil-fuel-free cultivation methods and raise compliance costs for mechanized alternatives, accelerating draft-animal equipment penetration beyond historical preservation niches.
For Market Incumbents: Entrench position through backward integration into certified low-carbon foundry capacity and CE-marking documentation infrastructure that emerging competitors cannot rapidly replicate. Pioneer Equipment Inc. and B W Macknair & Son must deepen captive supply of specialty steel alloys and hardwood handle stock to defend against aluminum-substitute entrants targeting price-sensitive hobbyist segments. Channel control through dedicated Amish and Mennonite community relationships represents the priority defensive lever.
For New Entrants and Emerging Players: Establish a beachhead in North American urban community garden networks where aluminum-frame cultivators and lightweight seeders address unmet demand for raised-bed vegetable production. Heritage education channels at agricultural museums and university programs offer white-space procurement specifications distinct from commercial durability requirements, enabling premium positioning without competing directly on cast-iron longevity. Direct-to-institution sales structures bypass entrenched cooperative buying networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage-craft specialists with verified carbon-disclosure documentation and ISO durability benchmarking capabilities over commodity fabricators lacking certification infrastructure. The five-to-ten year viability window hinges on sustained regulatory pressure favoring non-powered cultivation and draft-animal welfare compliance expansion. Acquisition targets should demonstrate CE-marking eligibility and established export relationships with Polish organic cooperatives. Monitor quarterly organic acreage certification data and EU machinery safety directive amendment schedules as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Investment | Unlocks EU import eligibility for Polish organic cooperative procurement under machinery safety directives. |
| Heritage Education Partnership | Agricultural museums in Scotland and Pennsylvania create institutional demand distinct from commercial specifications. |
| Composite Handle Development | Hybrid hardwood reinforcement reduces draft-animal fatigue while maintaining shock absorption for harness compatibility. |
| Direct Community Sales Structure | Amish buying cooperatives bypass dealer markups and lock in production-scale reliability requirements. |
| Low-Carbon Foundry Certification | EU Green Deal embodied-carbon tracking tilts procurement toward verified Scottish and German suppliers. |
Research Methodology
A spread of perspectives from heritage equipment manufacturers, Amish community procurement coordinators, organic certification officers, veterinary extension specialists, and agricultural museum curators converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with foundry operators in Scotland and Pennsylvania alongside secondary validation through USDA National Organic Program documentation, EU machinery safety directive texts, ISO agricultural equipment durability standards, customs trade data for cast-iron implement exports, and heritage farming collective procurement records. Bottom-up equipment shipment tallies and top-down organic acreage expansion estimates were triangulated to anchor volume assumptions.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation modeled by equipment type, material specification, application task, and end-user procurement authority. CAGRs were derived from equipment replacement cycle analysis and draft-animal herd expansion trajectories in key cultivation regions. Forecast inputs incorporated EU F-Gas Regulation compliance cost projections for mechanized alternatives, organic certification growth rates, and veterinary training program capacity constraints affecting operator supply.
Stress conditions across steel input cost volatility, CE-marking regulatory friction, and compact tractor substitution threats were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about heritage agriculture curriculum investments and draft-animal welfare regulation expansion. Quarterly review of organic certification statistics, foundry energy cost indices, and EU machinery safety directive amendment schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Stock Tanks Market