
 Food Bucket Elevators Market | 2026-2036
Food Bucket Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
Food Bucket Elevators Market Foresight
China is tilting investment toward automated grain logistics infrastructure, expanding domestic manufacturing capacity for food-grade conveying equipment. BEUMER Group GmbH & Co KG leverages its engineering depth in heavy-duty chain systems for high-throughput grain terminals. KWS Manufacturing Co Ltd anchors North American supply through specialized bucket fabrication for agricultural cooperatives. Sukup Manufacturing Co dominates on-farm storage integration, extending its elevator offerings into complete material handling circuits.
Food bucket elevators are vertical conveying machines that transport granular and powdered food materials using buckets attached to a belt or chain drive, typically operating at speeds of 1.0 to 2.5 meters per second with capacities ranging from 10 to over 1,000 tons per hour. These systems serve grain elevators, flour mills, and food processing plants where gentle handling and contamination prevention preserve product integrity. Chain bucket elevators lead in heavy-load grain applications due to tensile strength and durability under abrasive conditions, while belt bucket elevators gain ground in flour and sugar handling where speed and cleanability reduce cross-contamination risk. Plastic bucket elevators occupy a growing niche in seed and pulse conveying, as polymer materials resist corrosion and meet hygienic standards without metallic contamination.
FDA food contact surface regulations and EU MDR-aligned hygienic design standards shape equipment specifications, mandating smooth welds, quick-release components, and traceable stainless steel grades. China's SAMR enforces GB standards for food machinery safety, creating compliance thresholds for imported equipment. India's FSSAI and BIS certification requirements for food processing infrastructure are tightening, redirecting procurement toward certified suppliers. Stakeholders must monitor evolving regional certification regimes and align capital planning with compliance timelines that vary across destination markets.
Market Dynamics
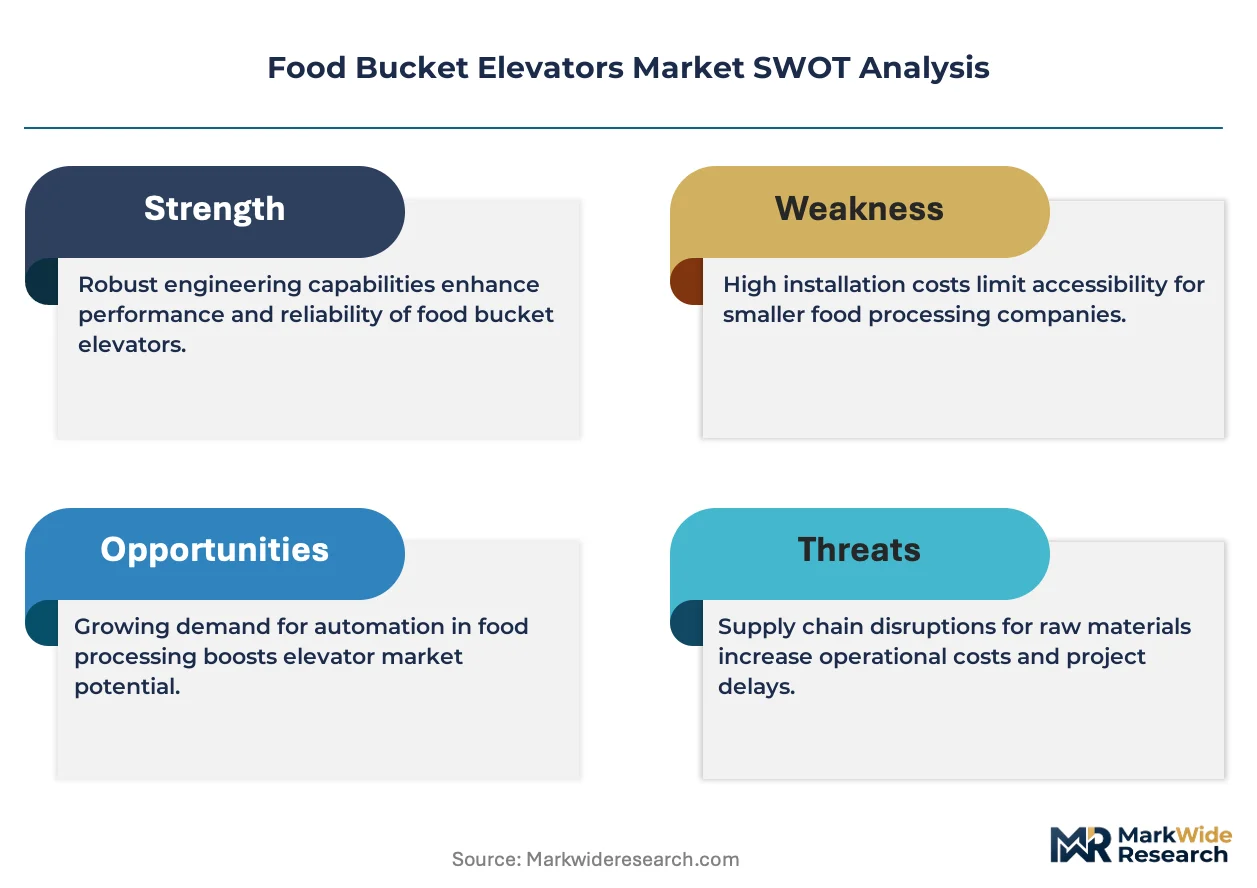
Grain handlers confront a structural pivot where FDA and EU hygienic design mandates are forcing wholesale replacement of legacy carbon steel elevators with stainless steel systems, compressing equipment replacement cycles and redrawing supplier qualification thresholds.
Growth Catalysts
- EU MDR-Aligned Hygienic Standards:European grain terminals face mandatory equipment upgrades to eliminate contamination vectors, creating pull for quick-release bucket assemblies and traceable stainless steel grades.
- China's Automated Grain Logistics Push:SAMR enforcement of GB food machinery safety standards is accelerating mechanized handling investments at provincial grain reserves and port terminals.
- Abrasion-Resistant Polymer Buckets:Seed and pulse processors adopt plastic elevator systems to eliminate metallic contamination risks while reducing maintenance intervals in corrosive environments.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price swings squeeze fabrication margins, forcing equipment makers to absorb cost spikes or risk order deferrals from price-sensitive agricultural cooperatives.
- Specialized Fabrication Concentration:Heavy-duty chain bucket production clusters in Germany and the United States, exposing buyers to extended lead times when regional capacity saturates.
- Belt Speed Limitations in Heavy Grain:Belt-driven systems face tensile stress thresholds that restrict throughput below chain alternatives in high-capacity terminal applications.
Strategic Opportunities
- India's FSSAI Certification Gap:Domestic grain handlers lack certified suppliers, creating first-mover advantage for equipment makers achieving BIS compliance ahead of enforcement tightening.
- Precision Agriculture Convergence:Integration of IoT sensors with elevator control systems enables real-time moisture monitoring and automated discharge routing at large-scale storage facilities.
- US IRA Clean Energy Provisions:Grain cooperatives accessing tax credits for facility modernization are bundling elevator upgrades with broader automation investments.
Industry Challenges
- Welding Certification Scarcity:FDA-mandated smooth weld standards for food contact surfaces exceed capabilities of general fabrication shops, constraining qualified installation capacity.
- Legacy System Integration Friction:New hygienic-design elevators must interface with existing grain handling circuits built to older dimensional and control protocols, complicating retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Bucket Elevators Market |
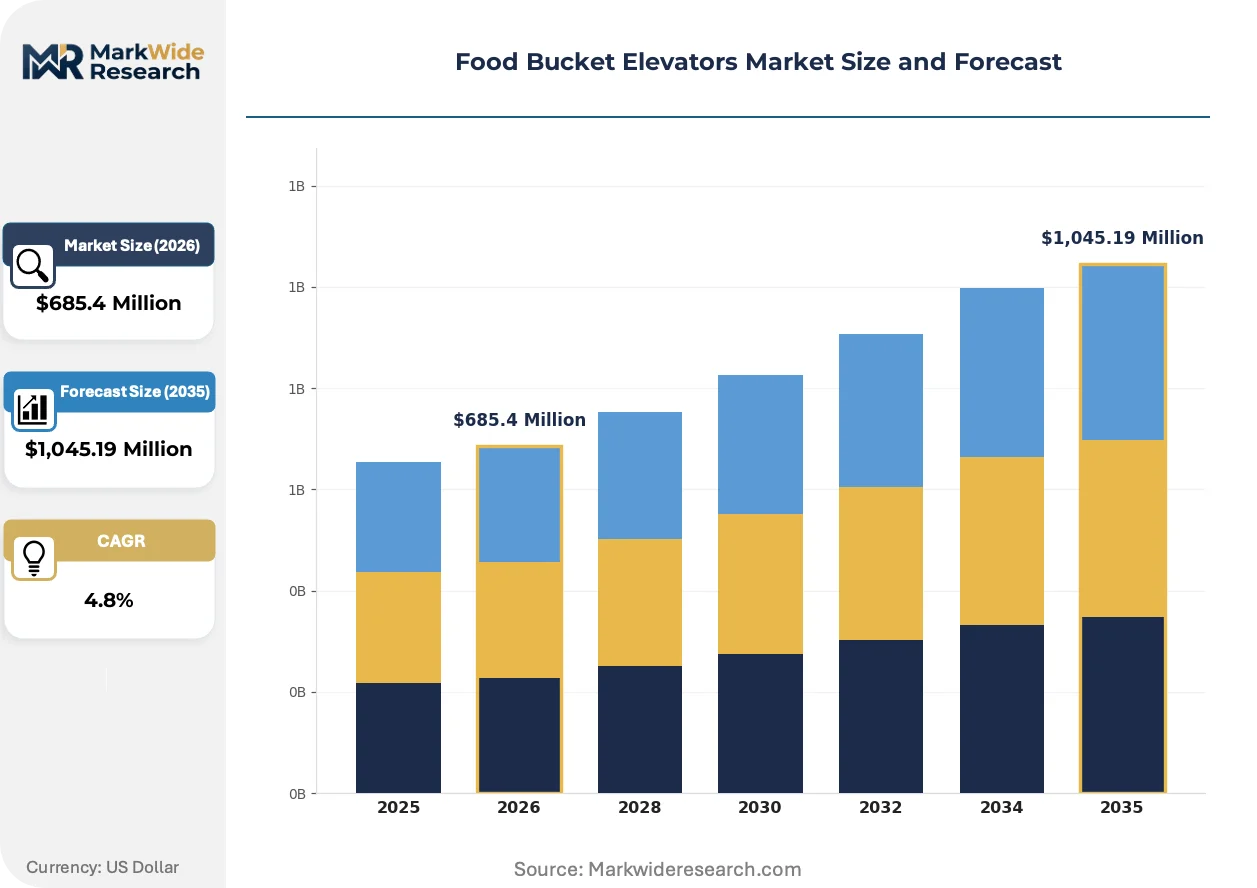
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain Bucket Elevators, Belt Bucket Elevators, Plastic Bucket Elevators, Metal Bucket Elevators, Heavy Duty Bucket Elevators Material Type: Grains, Pulses, Seeds, Flour, Sugar, Salt Application: Food Processing Plants, Feed Mills, Grain Storage Facilities, Baking Units, Confectionery Production End User: Agricultural Cooperatives, Food Distributors, Grain Handlers, Bulk Storage Providers |
| Companies Covered | Sukup Manufacturing Co, FEECO International Inc, BEUMER Group GmbH & Co KG, KWS Manufacturing Co Ltd, Sweet Manufacturing Company, AGCO Corporation, GSI Group, Skandia Elevator AB, Ryson International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Bucket Elevators Market Shifts & Advancements
Equipment specification is pivoting from throughput maximization toward contamination traceability and predictive maintenance integration, reshaping R&D priorities across the supplier base.
Continuous weld seam monitoring using machine vision is rendering obsolete manual weld inspection protocols that created bottlenecks in stainless steel bucket fabrication. Large grain terminals in Germany and the United States are specifying vision-certified units to compress commissioning timelines. This technology is compressing supplier qualification periods from months to weeks for critical food safety applications.
REACH chemical restriction expansions are pressuring equipment makers to eliminate hexavalent chromium coatings from chain components and pivot toward nickel-free surface treatments. The regulation is forcing reformulation of corrosion protection systems across European supply chains. Flour millers in France and Italy face accelerated replacement schedules as existing inventories approach compliance deadlines.
Grain handlers are unbundling equipment purchase from lifecycle service contracts, preferring to negotiate maintenance separately with regional specialists rather than accepting captive OEM service terms. This fragmentation is disrupting traditional single-source procurement models at agricultural cooperatives. The shift is most pronounced in the United States, where cooperative buying groups now tender service contracts independently from capital equipment.
Food Bucket Elevators Market Segmentation
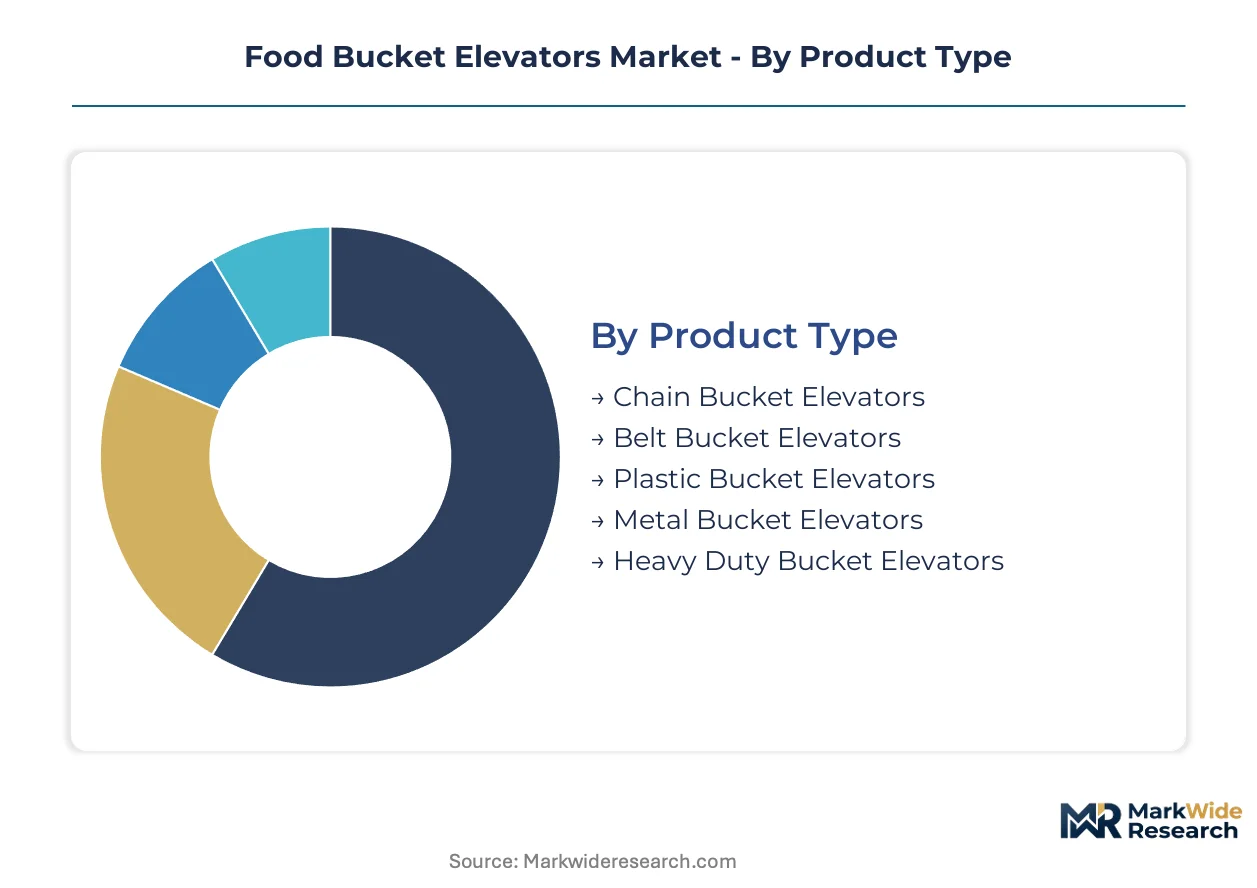
Equipment specification in food bucket elevators diverges sharply across product architectures and material handling requirements, with regulatory compliance and throughput demands driving distinct procurement patterns. Segmentation reveals how chain systems anchor heavy-grain terminals while belt and plastic configurations capture hygiene-sensitive applications.
Product Type:
Cost tier separates equipment architectures, with capital intensity and operating durability determining adoption across grain terminal scales.
- Chain Bucket Elevators:Heavy-duty chain drives with hardened steel linkages withstand abrasive grain loads exceeding 500 tons per hour. High-capacity port terminals in Germany and the United States specify these systems for continuous operation under tensile stress that would degrade belt alternatives.
- Belt Bucket Elevators:Synthetic belting with spaced polymer or steel buckets operates at higher speeds for gentle handling of flour and sugar. FDA food contact compliance and cleanability advantages position belt systems for confectionery plants and baking units where cross-contamination protocols dominate specification.
- Plastic Bucket Elevators:Corrosion-resistant polymer construction eliminates metallic contamination risks in seed and pulse conveying. Agricultural cooperatives in moisture-prone regions favor these units for reduced maintenance intervals.
- Metal Bucket Elevators:Stainless steel bucket assemblies meet EU MDR-aligned hygienic standards for food contact surfaces. European flour millers specify traceable steel grades for regulatory audit trails.
- Heavy Duty Bucket Elevators:Reinforced frame construction and oversized drive components accommodate extreme throughput demands at inland grain terminals. China's provincial grain reserves deploy these systems for automated logistics hubs.
Chain systems hold installed capacity. Plastic configurations are rotating up the share rankings.
Material Type:
Application severity varies by material abrasiveness and contamination sensitivity, dictating bucket composition and speed calibration.
- Grains:Corn, wheat, and rice handling requires abrasion-resistant chain systems at high-capacity terminals. China's SAMR-enforced grain reserve modernization is accelerating mechanized handling investments.
- Pulses:Lentil and chickpea conveying favors plastic bucket systems to prevent splitting and preserve seed integrity. Indian agricultural cooperatives are expanding pulse processing capacity under FSSAI compliance timelines.
- Seeds:Oilseed and specialty crop handling demands gentle speed control to maintain germination rates. Seed processors specify belt elevators with adjustable discharge points.
- Flour:Powdered material creates dust explosion hazards requiring spark-resistant construction and grounded assemblies. European milling operations specify ATEX-compliant equipment under ECHA safety frameworks.
- Sugar:Crystal and powdered sugar handling prioritizes smooth interior surfaces and quick-release components for washdown protocols. Confectionery producers in France and Italy specify FDA-grade stainless systems.
- Salt:Corrosive crystalline material accelerates wear on standard steel components. Coastal processing facilities specify polymer-lined or specialty alloy construction.
Grain handling commands volume leadership. Flour and sugar applications are expanding most quickly on hygiene mandates.
Application:
Customer operational scale determines automation depth, with large centralized facilities separating from distributed on-farm installations.
- Food Processing Plants:Integrated conveying circuits connect receiving, storage, and processing lines with traceable material flow. US facilities accessing IRA clean energy provisions bundle elevator upgrades with broader automation investments.
- Grain Storage Facilities:Elevator towers and silo complexes require vertical conveying capacity exceeding 1,000 tons per hour. Germany's port terminals specify heavy-duty chain systems with predictive maintenance integration.
- Feed Mills:Mixed ingredient handling tolerates moderate abrasion with emphasis on batch accuracy and formulation flexibility. Regional cooperatives in the United States favor modular belt systems for recipe changeover speed.
- Baking Units:Flour receiving and sifting operations demand contamination-free conveying with magnetic separation compatibility. European bakers specify EU MDR-aligned hygienic design standards.
- Confectionery Production:Sugar handling requires explosion-proof construction and temperature-controlled environments. Italian producers face accelerated replacement schedules as REACH chemical restrictions phase out hexavalent chromium coatings.
Grain storage facilities anchor installed base. Food processing plants are gaining share fastest on integrated automation demand.
End User:
Procurement authority concentrates differently across cooperative structures, with buying group scale influencing supplier qualification thresholds.
- Agricultural Cooperatives:Member-owned grain handlers negotiate collective equipment tenders with lifecycle service unbundled from capital purchase. US cooperative buying groups now tender maintenance contracts independently from OEM supply.
- Grain Handlers:Commercial elevator operators face compressed replacement cycles as FDA and EU mandates force carbon steel phaseout. Large operators specify vision-certified weld quality to compress commissioning timelines.
- Food Distributors:Bulk ingredient intermediaries require flexible handling systems for varied commodity receipts. Distributors prioritize quick-release bucket assemblies for multi-product flexibility.
- Bulk Storage Providers:Third-party logistics operators monetize throughput capacity with uptime guarantees driving predictive maintenance adoption. German terminals integrate IoT sensors for real-time moisture monitoring and automated discharge routing.
Grain handlers dominate procurement volume. Agricultural cooperatives are rotating up the share rankings on collective buying consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food contact surface regulations anchor equipment specification in the United States, while SAMR-enforced GB standards and EU MDR-aligned hygienic mandates reshape procurement across China and Germany respectively.
United States
Grain cooperatives and agricultural handlers drive mechanized handling investments to reduce post-harvest losses. The Inflation Reduction Act's clean energy provisions enable tax credit access for facility modernization bundling elevator upgrades with automation investments. The Midwest grain belt concentrates large-scale storage modernization programs where cooperative buying groups tender equipment and service contracts separately.
Germany
Port terminals and grain elevators face mandatory equipment upgrades under EU MDR-aligned hygienic design standards eliminating contamination vectors. REACH chemical restriction expansions pressure elimination of hexavalent chromium coatings from chain components. Heavy-duty chain system fabrication clusters in industrial regions supply high-throughput terminals with predictive maintenance integration.
China
Provincial grain reserves and port terminals accelerate mechanized handling investments under SAMR enforcement of GB food machinery safety standards. Automated grain logistics infrastructure expansion drives domestic manufacturing capacity growth for food-grade conveying equipment. Yangtze River Delta logistics hubs deploy reinforced heavy-duty systems for automated grain distribution networks.
India
Agricultural cooperatives expand pulse processing capacity under tightening FSSAI compliance timelines and BIS certification requirements. Domestic grain handlers lack certified suppliers, creating procurement redirection toward qualified equipment makers. Gujarat and Maharashtra processing clusters favor plastic bucket systems for lentil and chickpea conveying to preserve seed integrity.
France
Flour millers and confectionery producers face accelerated replacement schedules as REACH compliance deadlines approach for existing equipment inventories. ATEX-compliant specifications dominate milling operations under ECHA safety frameworks addressing dust explosion hazards. Northern France baking clusters specify EU MDR-aligned hygienic design standards for contamination-free flour receiving operations.
Food Bucket Elevators Market Competitive Landscape
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified agricultural equipment conglomerates. The supplier base organizes into three tiers: heavy-duty chain system specialists, integrated grain handling solution providers, and regional fabrication shops serving cooperative buyers. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into predictive maintenance service contracts.
Within the heavy-duty engineering tier, BEUMER Group GmbH & Co KG and KWS Manufacturing Co Ltd exemplify divergent strategic positions. The German GmbH & Co KG structure anchors European supply for high-throughput terminal applications, while the North American Co Ltd format serves agricultural cooperative demand through specialized fabrication. Sukup Manufacturing Co occupies a position bridging on-farm storage integration with complete material handling circuit extension.
| Leading Market Players |
|---|
| Sukup Manufacturing Co |
| FEECO International Inc |
| BEUMER Group GmbH & Co KG |
| KWS Manufacturing Co Ltd |
| Sweet Manufacturing Company |
| AGCO Corporation |
| GSI Group |
| Skandia Elevator AB |
| Ryson International Inc |
| Others |
Supply & Pricing Matrix
Nickel and chromium price volatility in stainless steel feedstock determines both the premium-to-economy equipment spread and the geographic reconfiguration of fabrication networks. Agricultural cooperatives face compressed margins when alloy surges coincide with procurement cycles, forcing suppliers to absorb spikes or risk order deferrals from price-sensitive grain handlers.
Pricing Analysis
German and US port terminals command 15-25% premiums over Indian and Chinese domestic markets due to certification-grade welding requirements and traceable steel documentation. Three-tier pricing structure across FDA-certified premium, CE-marked standard, and economy-grade carbon steel alternatives separates procurement tiers. Pricing pressure stems from nickel futures volatility squeezing fabrication margins in stainless-intensive configurations. Agricultural cooperatives exhibit highest price sensitivity, while multinational grain traders prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier-buyer negotiations as equipment makers absorb working capital strain. Heavy-duty chain fabrication clusters in Germany, the United States, and China, with specialty polymer bucket molding concentrated in Italy and India. Raw material dependencies center on nickel-chromium stainless grades, hardened steel linkages, and engineered polymer resins. Single-source vulnerability looms in precision welding certification capacity. Distribution runs through OEM-direct channels for large terminals and agricultural cooperative buying groups for on-farm installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified weld certification scarcity constrains supplier expansion, creating durable competitive moats for incumbents with in-house training pipelines and inspector accreditation. The gap between FDA-mandated surface finish standards and general fabrication capability widens annually.
For Market Incumbents: Entrench position by acquiring regional welding certification programs to captive qualified installation capacity before competitors replicate training infrastructure. Backward integration into nickel-grade stainless distribution hedges against alloy price spikes that threaten margin stability in premium equipment tiers. Defend against emerging Chinese manufacturers by bundling predictive maintenance software with hardware contracts.
For New Entrants and Emerging Players: Pursue India's FSSAI certification gap before enforcement tightening closes the window for unqualified suppliers. Target plastic bucket elevator segments in moisture-prone agricultural regions where corrosion-resistant polymers displace metal alternatives. Establish beachhead through regional service partnerships with existing grain handling integrators rather than direct OEM competition.
For Investors and Strategic Acquirers: EU MDR-aligned hygienic standard enforcement reshapes the acquisition landscape toward stainless-specialist fabricators with weld-vision certification capabilities. Five-to-ten year viability favors equipment makers with installed base conversion potential from carbon steel legacy systems. Monitor SAMR GB standard compliance timelines in China as the signal for accelerated domestic manufacturing consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Weld Vision Certification Investment | Machine vision systems compress commissioning timelines at German port terminals requiring FDA-grade surface documentation. |
| Polymer Bucket Material Pivot | Corrosion-resistant polymer formulations capture seed and pulse applications in India's FSSAI-regulated processing clusters. |
| Predictive Maintenance Platform Launch | IoT sensor integration enables real-time moisture monitoring for US grain cooperatives accessing IRA modernization credits. |
| Regional Service Partnership Expansion | Independent maintenance contracts align with US cooperative buying groups unbundling lifecycle service from capital purchase. |
| Stainless Steel Grade Traceability Program | Documented steel sourcing satisfies EU MDR audit requirements for French and Italian flour milling operations. |
Research Methodology
Operator-level perspectives from grain elevator maintenance directors, agricultural cooperative procurement managers, food plant engineers, and OEM sales engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA warning letter databases, EU MDR technical documentation filings, SAMR GB standard enforcement notices, and customs trade data on stainless steel equipment imports. Bottom-up equipment shipment analysis triangulated against top-down grain handling capacity expansion announcements across major producing regions.
Scenario-bracketing around regulatory enforcement intensity and alloy price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material handling application, end-user scale, and regional certification regime. CAGRs derived from installed base replacement cycles, grain storage modernization program announcements, and mechanization penetration curves in emerging markets. Forecast inputs incorporated stainless steel price elasticity coefficients and welding certification capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in grain commodity prices, central bank agricultural lending rates, or nickel futures volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Planter Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Lawn Aerators Market