
 Bird Scarer and Repellent Market | 2026-2036
Bird Scarer and Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
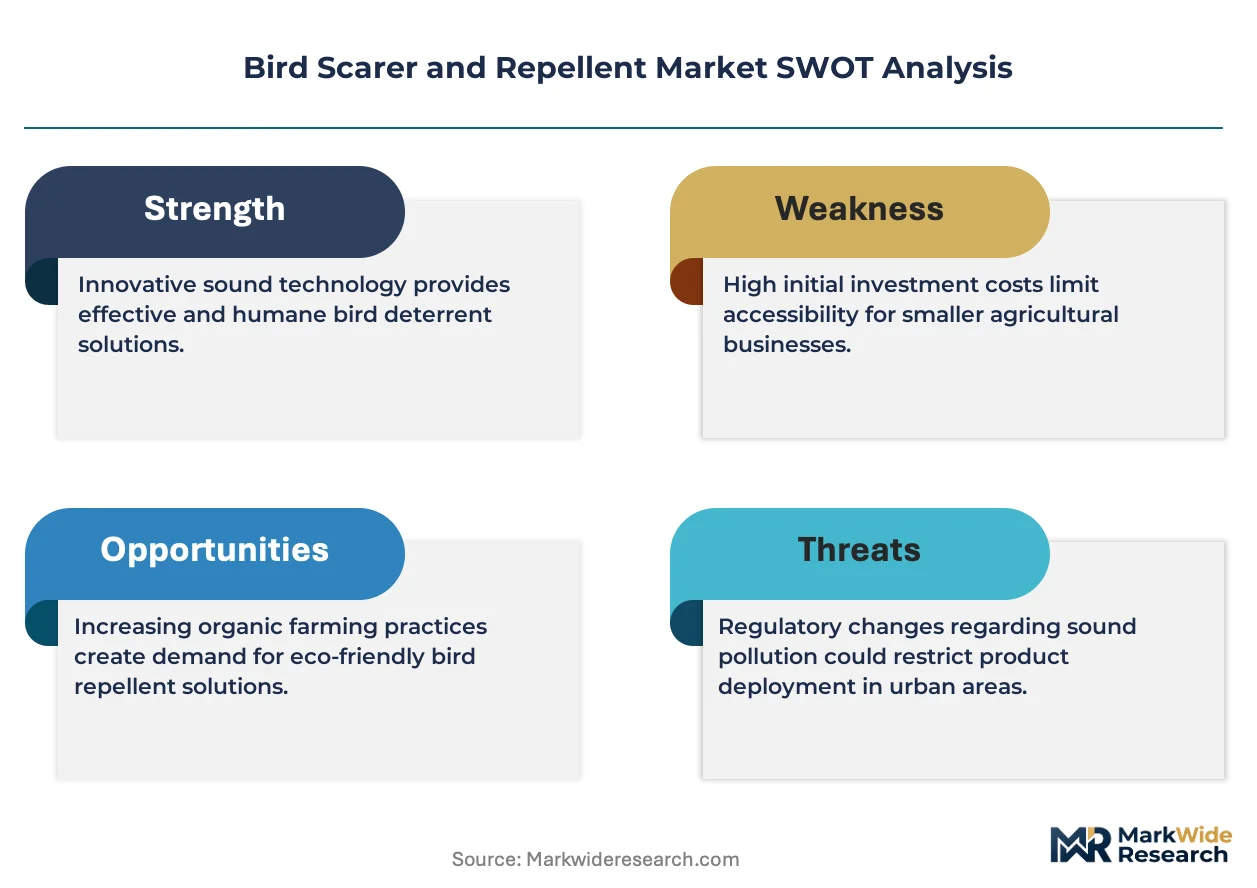
Bird Scarer and Repellent Market Analysis
CE marking under the EU Machinery Directive is redrawing competitive access for electronic scaring systems sold into European aviation and agricultural channels. Bird B Gone, Inc. leverages extensive distributor networks across North American retail and commercial channels. Bird-X sustains technology leadership through its portfolio of ultrasonic and laser-based deterrent platforms. Bird Control Group anchors its position in European airport contracts with species-specific laser systems that comply with EASA wildlife management guidelines.
Bird scarers and repellents comprise physical, chemical, electronic, and optical devices engineered to disrupt avian landing, roosting, or feeding behaviors through sensory stimulation at frequencies, wavelengths, or concentrations calibrated to target species without permanent harm; typical electronic units operate at sound pressure levels between 100 and 120 decibels or emit laser beams at 405 to 650 nanometers to exploit avian retinal sensitivity. Ultrasonic devices and auditory scare devices command the largest installed base across agricultural fields, though motion-activated electronic systems capture the fastest growth trajectory as precision agriculture and smart perimeter monitoring converge. Chemical repellents occupy a mature margin pool where methyl anthranilate and polybutene formulations face tightening residue scrutiny under EPA and EFSA frameworks.
The EPA regulates avian chemical repellents under FIFRA, while the FAA mandates wildlife hazard assessments at certificated airports under Part 139; EASA coordinates parallel standards through its aerodrome certification specifications. These overlapping frameworks elevate product testing costs but create durable competitive moats for manufacturers with established regulatory dossiers. Stakeholders must monitor evolving restrictions on auditory deterrent noise emissions in residential-adjacent agricultural zones, as municipal ordinances in multiple jurisdictions are tightening decibel limits and operational hour constraints.
Market Dynamics
Laser-based avian deterrent systems are fragmenting procurement patterns across North American aviation infrastructure as FAA wildlife hazard mandates harden compliance thresholds and displace legacy propane cannon deployments.
Growth Catalysts
- Airport Infrastructure Grants:Federal funding mechanisms in the United States now require integrated bird management protocols, forcing certificated facilities to upgrade from passive to active electronic scaring systems.
- EASA Wildlife Guidelines:European aerodrome certification specifications are accelerating laser system validation for species-specific deterrence, creating procurement pull from Amsterdam Schiphol to Frankfurt Main.
- Precision Agriculture Convergence:Motion-activated electronic systems are capturing agricultural perimeter contracts as smart monitoring platforms integrate avian detection with automated response triggers.
Market Restraints
- Semiconductor Input Volatility:Laser diode and sensor component costs fluctuate with foundry capacity constraints in East Asian supply chains, compressing margins on electronic scaring hardware.
- Residue Scrutiny Under EPA FIFRA:Methyl anthranilate and polybutene chemical repellents face intensifying environmental fate testing, extending registration renewal timelines and raising compliance expenditures.
- Auditory Emission Limits:Municipal noise ordinances in residential-adjacent agricultural zones are tightening decibel caps and operational hour restrictions on propane cannons and sonic devices.
Strategic Opportunities
- CE Marking Pathways:Machinery Directive compliance for electronic scaring systems opens distribution channels across German, French, and Italian agricultural cooperatives currently underserved by certified suppliers.
- Ultrasonic-Laser Convergence:Hybrid platforms combining 100-120 decibel auditory output with 405-650 nanometer retinal stimulation are penetrating vineyard and orchard protection contracts.
- Smart Perimeter Integration:API-enabled deterrent systems that feed avian activity data into farm management software platforms are capturing premium positioning in precision agriculture budgets.
Industry Challenges
- Species-Specific Calibration Expertise:Ornithological competency gaps among installation technicians delay deployment timelines and degrade deterrent efficacy in multi-species environments.
- Legacy System Integration:Retrofitting electronic scaring platforms into existing airport perimeter security architectures requires custom middleware development, extending project delivery cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bird Scarer and Repellent Market |
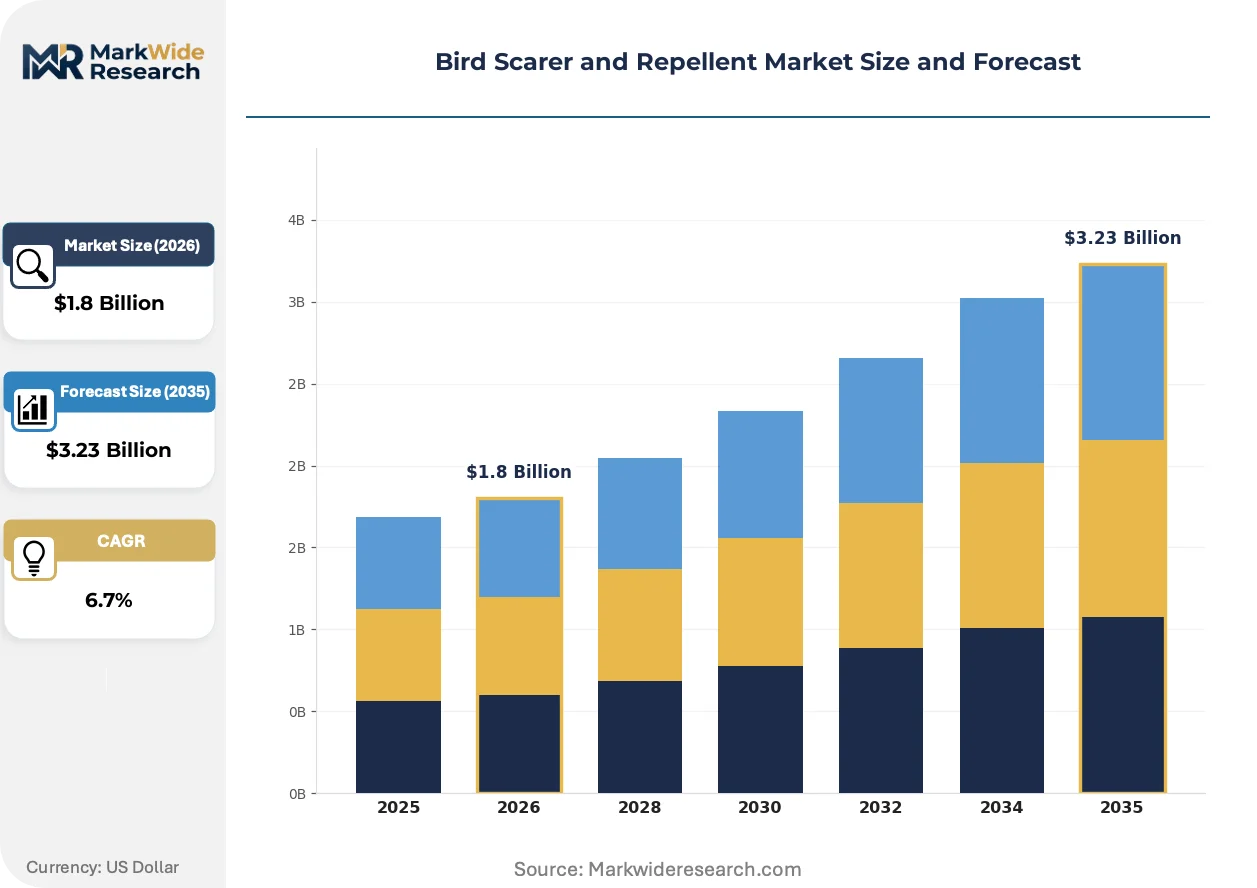
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Devices, Chemical Repellents, Visual Deterrents, Auditory Scare Devices Application: Agricultural Fields, Residential Areas, Commercial Spaces, Airports Technology: Electronic Scaring Systems, Non-Toxic Sprays, Reflective Surfaces, Motion-Activated Devices End User: Farmers, Gardeners, Wildlife Management Agencies, Airport Authorities |
| Companies Covered | Bird B Gone, Inc., Bird-X, Bird Control Group, Bird Barrier America, Inc., Birdstoppers, Nixalite of America, Inc., Leaven Enterprises, Bird Gard LLC, Martley Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bird Scarer and Repellent Market Emerging Trajectories
Avian deterrence technology is pivoting from single-modality hardware toward integrated sensory platforms that combine optical, auditory, and motion-detection layers. This convergence is compressing replacement cycles and elevating software-enabled service components.
Autonomous laser deterrent units are fragmenting competitive positioning in aviation security procurement. These systems emit calibrated 405-650 nanometer beams that exploit avian retinal sensitivity without permanent harm. Denver International and Dallas-Fort Worth are deploying species-specific algorithms that adjust sweep patterns based on real-time flock behavior. The technology is fragmenting vendor hierarchies by enabling smaller laser specialists to displace integrated aviation service incumbents on technical performance metrics alone.
EPA enforcement under FIFRA is intensifying environmental fate testing requirements for chemical repellent active ingredients. Methyl anthranilate formulations now require extended aquatic toxicity dossiers before registration renewal. Agricultural distributors in California's Central Valley are responding by diversifying into electronic and optical alternatives, compressing chemical repellent shelf space in retail channels.
Outcome-based deterrent service contracts are displacing capital equipment sales in large-scale agricultural operations. Vineyard managers in Napa and Sonoma counties now prefer per-hectare protection fees that bundle hardware, maintenance, and efficacy guarantees. This model transfers species-migration risk from buyer to supplier and locks in multi-season revenue streams for technology-integrated service providers.
Bird Scarer and Repellent Market Segmentation
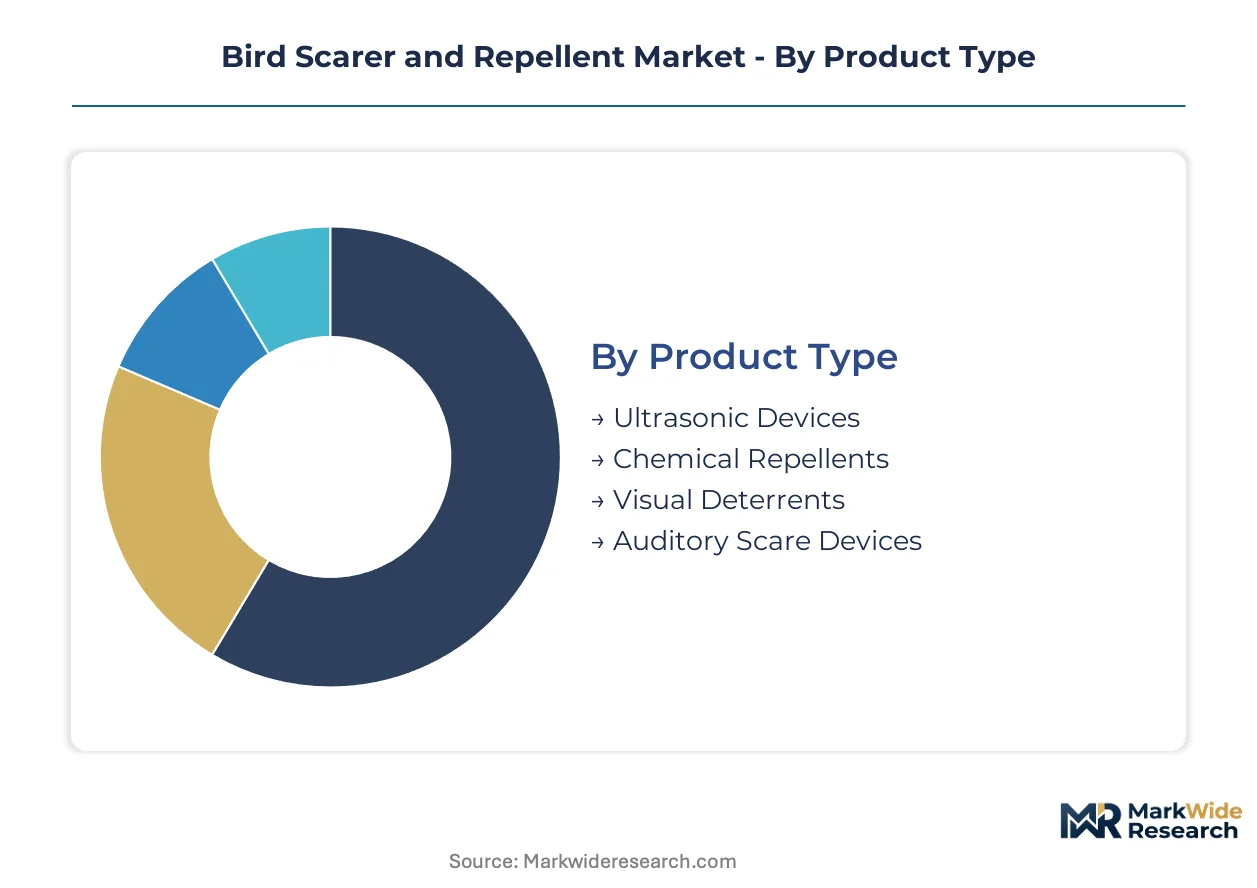
Procurement patterns across the Bird Scarer and Repellent Market diverge sharply by channel, with aviation infrastructure favoring capital-intensive electronic systems while agricultural buyers prioritize cost-per-acre efficiency. Understanding these segment-channel pairings reveals where margin pools concentrate and which technology platforms capture repeat purchase loyalty.
Product Type:
Distribution channels segment sharply by product complexity, with electronic systems flowing through specialized aviation contractors and chemical formulations dominating agricultural retail cooperatives.
- Ultrasonic Devices:These units emit high-frequency sound waves between 20 and 45 kHz calibrated to avian hearing ranges, typically deployed in vineyard and orchard settings where noise ordinances restrict auditory alternatives. Demand concentrates in California's Central Valley and Italian wine regions where municipal decibel caps are tightening.
- Chemical Repellents:Methyl anthranilate and polybutene formulations create gustatory aversion through non-toxic sensory irritation, applied via aerial or ground spray systems. EPA FIFRA registration requirements elevate compliance costs, compressing shelf space at agricultural distributors facing residue scrutiny.
- Visual Deterrents:Reflective tapes, predator eye balloons, and holographic ribbons exploit avian neophobia through movement and flash patterns.
- Auditory Scare Devices:Propane cannons and electronic sirens generate 100-120 decibel pressure waves; noise emission limits in residential-adjacent zones are accelerating displacement by laser alternatives.
By volume, Chemical Repellents leads. By growth pace, Ultrasonic Devices is climbing the fastest.
Application:
End-use concentration determines technology selection, with high-stakes aviation environments justifying premium autonomous systems and price-sensitive agricultural buyers favoring modular, scalable deployments.
- Airports:FAA Part 139 mandates require certificated facilities to maintain active wildlife hazard management protocols, driving procurement of integrated laser and radar-detection platforms. Denver International and Dallas-Fort Worth anchor North American demand for species-specific autonomous units.
- Agricultural Fields:Row-crop and permanent-crop operations deploy perimeter-based deterrent networks, with motion-activated systems gaining traction as precision agriculture budgets expand. Napa and Sonoma vineyard managers now favor outcome-based service contracts over capital purchases.
- Residential Areas:Homeowner associations and individual property owners prioritize low-cost, low-maintenance solutions with minimal aesthetic intrusion.
- Commercial Spaces:Retail rooftops, warehouse perimeters, and food-processing facilities balance efficacy against liability exposure from bird-related contamination.
Airports command the highest per-site expenditure. Agricultural Fields delivers the deepest installed base.
Technology:
Supply-side specialization fragments by core competency, with laser diode manufacturers, sensor integrators, and formulation chemists occupying distinct competitive tiers with limited overlap.
- Electronic Scaring Systems:Integrated platforms combining auditory output, laser emission, and motion detection through centralized control software. EASA wildlife management guidelines are accelerating validation protocols at Amsterdam Schiphol and Frankfurt Main.
- Motion-Activated Devices:Radar and infrared sensors trigger targeted deterrent responses, reducing energy consumption and false activation versus timer-based alternatives. API-enabled units feeding farm management software capture premium positioning in precision agriculture.
- Non-Toxic Sprays:Water-based and oil-carrier formulations requiring reapplication after precipitation events.
- Reflective Surfaces:Passive deterrents dependent on wind movement and sunlight angle for efficacy.
Electronic Scaring Systems dominates R&D investment. Motion-Activated Devices shows the steepest expansion trajectory.
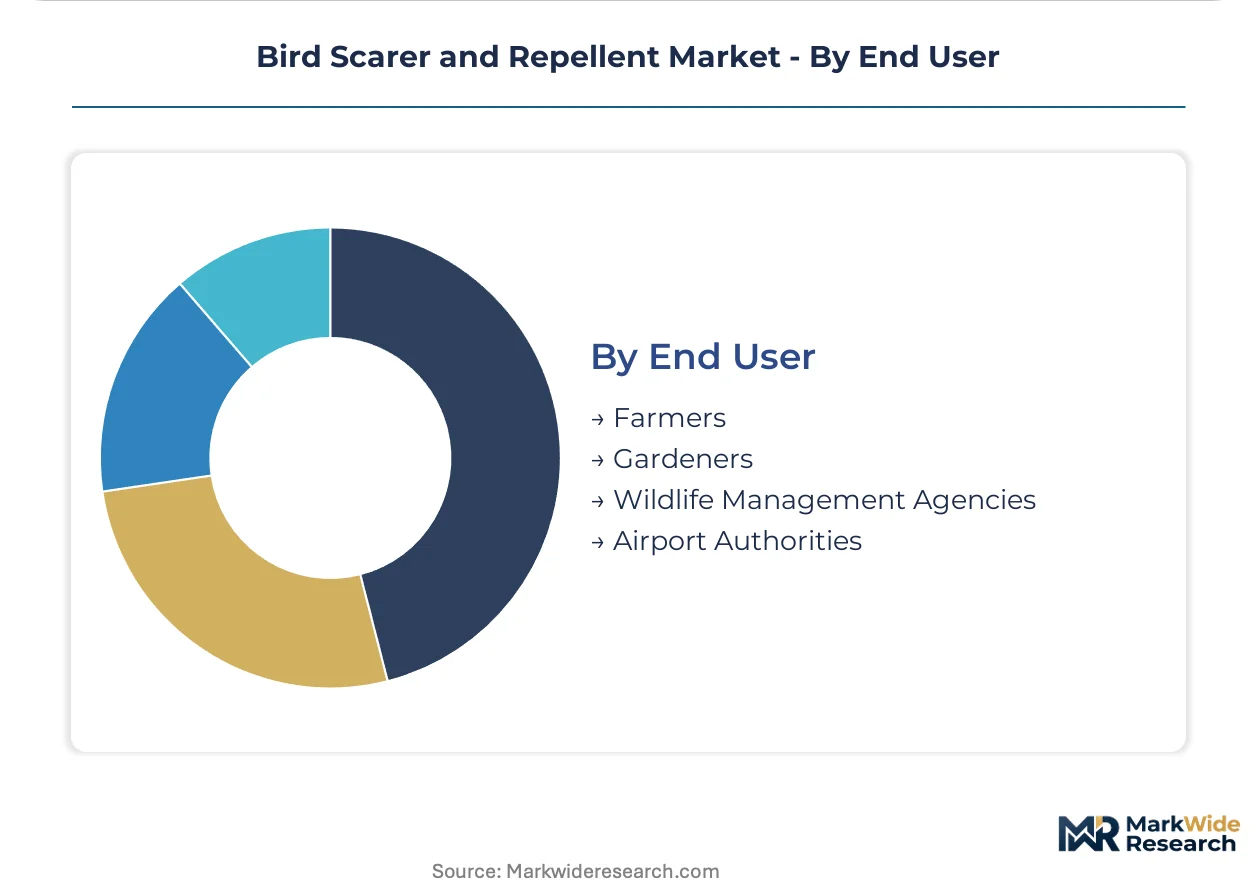
End User:
Buyer sophistication spans from institutional procurement teams with dedicated ornithological consultants to individual gardeners making discretionary retail purchases.
- Airport Authorities:Federal infrastructure grants in the United States now require integrated bird management protocols, forcing facility upgrades from passive to active deterrent systems. Procurement teams prioritize EASA- and FAA-compliant platforms with documented species-specific efficacy.
- Farmers:Cooperative buying groups and large-scale operators negotiate volume pricing, while smaller holdings rely on agricultural retail channels. Outcome-based service contracts are displacing equipment sales in premium wine-growing regions.
- Wildlife Management Agencies:Government entities balancing ecological protection with agricultural productivity mandates.
- Gardeners:Price-sensitive consumers prioritizing ease of installation and immediate visual confirmation of function.
Farmers represent the broadest addressable base. Airport Authorities deliver the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airport authorities and agricultural cooperatives concentrate procurement in jurisdictions with hardened wildlife hazard mandates and precision agriculture adoption curves.
United States
Federal airport infrastructure grants now require integrated bird management protocols at certificated facilities. FAA Part 139 mandates drive procurement of laser-based deterrent systems at Denver International and Dallas-Fort Worth. California's Central Valley agricultural distributors are diversifying into electronic alternatives as EPA FIFRA residue scrutiny intensifies.
Germany
CE marking under the EU Machinery Directive is redrawing competitive access for electronic scaring systems sold into agricultural cooperatives. EASA wildlife management guidelines accelerate laser system validation at Frankfurt Main. Bavarian and North Rhine-Westphalian vineyard operators favor ultrasonic devices where municipal noise ordinances restrict propane cannons.
Netherlands
Amsterdam Schiphol anchors European aviation demand for species-specific autonomous laser units with real-time flock behavior algorithms. Dutch agricultural technology clusters around Wageningen integrate motion-activated deterrents with farm management software platforms. National environmental regulations favor non-toxic optical solutions over chemical spray alternatives.
Australia
Grain-growing regions in New South Wales and Victoria deploy perimeter-based electronic networks against cockatoo and corella damage. The country's national agricultural regulator maintains strict residue protocols for methyl anthranilate formulations. Queensland sugar cane operators are piloting API-enabled deterrent systems feeding avian activity data into precision agriculture dashboards.
Canada
Prairie province grain handlers face intensifying pressure from blackbird and starling roosting in elevator complexes. Transport Canada coordinates with FAA-aligned wildlife hazard assessment protocols at Toronto Pearson and Vancouver International. Ontario and Manitoba agricultural retailers are expanding shelf space for ultrasonic devices as municipal noise bylaws tighten.
Bird Scarer and Repellent Market Vendor Landscape
Player mix skews toward specialized deterrent technology developers with ornithological calibration expertise and aviation-certified hardware portfolios. Market structure shows moderate consolidation around three to four integrated platform providers with established regulatory dossiers, flanked by numerous regional distributors and single-modality hardware specialists. Two strategic archetypes dominate: laser diode manufacturers with species-specific algorithm capabilities, and full-service aviation contractors bundling detection, deterrence, and compliance documentation. Competitive moves concentrate on CE marking pathway expansion for Machinery Directive compliance and outcome-based service contract proliferation in premium agricultural zones.
Among North American deterrent specialists, Bird B Gone, Inc., Bird-X, and Bird Control Group occupy distinct positioning tiers. Bird B Gone, Inc. exemplifies the distributor-network archetype with extensive retail and commercial channel penetration. Bird-X represents the technology-integrated platform model, anchoring its position through ultrasonic and laser-based deterrent portfolios. Bird Control Group sits within the European aviation specialist tier, securing airport contracts through EASA guideline alignment.
| Leading Market Players |
|---|
| Bird B Gone, Inc. |
| Bird-X |
| Bird Control Group |
| Bird Barrier America, Inc. |
| Birdstoppers |
| Nixalite of America, Inc. |
| Leaven Enterprises |
| Bird Gard LLC |
| Martley Electronics |
| Others |
Supply Flow & Price Mechanics
Ninety-day laser diode lead times from East Asian foundries compress margin flexibility for electronic scaring system manufacturers while amplifying pricing power for vertically integrated suppliers with captive component inventories. This inventory tension concentrates procurement leverage among aviation contractors capable of absorbing working capital spikes, forcing smaller agricultural distributors toward chemical repellent alternatives with shorter replenishment cycles.
Pricing Analysis
Cost-plus contracts indexed to semiconductor commodity benchmarks dominate procurement for airport-grade electronic scaring systems. Pricing stratifies across aviation-certified, agricultural-commercial, and residential-economy tiers, with FAA Part 139 compliance documentation commanding substantial premiums over CE-marked agricultural equivalents. Pricing pressure stems from foundry capacity constraints in Taiwan and South Korea, which inflate laser diode input costs. Airport authorities exhibit lowest price sensitivity due to federal infrastructure grant coverage, while vineyard cooperatives in residential-adjacent zones face acute budget constraints from municipal noise ordinance compliance costs.
Supply Chain Analysis
Inventory cycles for motion-activated sensor arrays currently stretch across twelve-to-sixteen week bands, reflecting foundry allocation priorities toward automotive and consumer electronics customers. Manufacturing concentration centers on China for laser diode fabrication, Germany for precision optical assembly, and the United States for aviation-certified system integration. Raw material dependencies include gallium arsenide substrates, infrared sensor wafers, and methyl anthranilate active ingredients. Single-source vulnerability in 405-650 nanometer laser diode supply creates exposure to export licensing disruptions. Distribution runs through specialized aviation contractors, agricultural retail cooperatives, and direct-to-farm service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among airport procurement teams with dedicated ornithological consultants and multi-year federal grant commitments, fragmenting pricing leverage for smaller agricultural buyers without volume aggregation.
For Market Incumbents: Compound regulatory dossier advantages by accelerating EASA wildlife guideline alignment ahead of European aviation procurement waves. Deepen backward integration into laser diode supply through long-term offtake agreements with Taiwanese foundries, defending against emerging Chinese optical specialists with state-subsidized capacity expansion. Prioritize species-specific algorithm development to maintain technical differentiation as propane cannon displacement accelerates. For New Entrants and Emerging Players: CE marking fast-track through Notified Body partnerships in Germany opens underserved agricultural cooperative channels in Bavaria and North Rhine-Westphalia currently constrained by Machinery Directive compliance gaps. Target outcome-based service contracts in Napa and Sonoma vineyard regions where capital equipment sales are commoditizing. Penetrate through API-enabled platform integration with precision agriculture software dashboards, capturing recurring revenue streams unavailable to hardware-only incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because overlapping FAA, EPA, and EASA frameworks create durable competitive barriers for established dossier holders. Acquisition targets should display ornithological calibration expertise paired with aviation-certified hardware portfolios. Watch for EPA FIFRA registration renewal delays on methyl anthranilate formulations as an inflection signal accelerating electronic alternative adoption.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | Machinery Directive compliance unlocks German, French, and Italian agricultural cooperative distribution. |
| Species-Specific Algorithm Development | Autonomous laser systems with real-time flock behavior adjustment displace legacy propane cannons at FAA-mandated airports. |
| Outcome-Based Service Contract Proliferation | Per-hectare protection fees transfer migration risk from vineyard buyers to technology-integrated suppliers. |
| API-Enabled Platform Integration | Farm management software connectivity captures premium positioning in precision agriculture budgets. |
| Backward Integration into Laser Diode Supply | Captive component sourcing insulates margins from East Asian foundry allocation volatility. |
Methodological Framework
Cross-validation between primary interviews with airport wildlife management officers, agricultural cooperative procurement leads, ornithological calibration specialists, and electronic system integrators anchors the qualitative findings against secondary validation from FAA Part 139 compliance documentation, EPA FIFRA registration databases, EASA aerodrome certification specifications, and agricultural trade association procurement surveys. Bottom-up unit economics from vineyard service contracts and top-down aviation infrastructure grant allocations were triangulated to constrain estimate variance.
Sensitivity analysis across semiconductor input cost scenarios, regulatory timeline assumptions, and species-specific efficacy parameters frames the projection horizon. Segmentation dimensions modeled include product type complexity tiers, application risk profiles, technology integration levels, and end-user procurement sophistication. CAGRs were derived from installed base replacement cycles and penetration rate assumptions across precision agriculture adoption curves. Forecast inputs incorporate municipal noise ordinance expansion timelines and federal airport infrastructure grant authorization patterns.
Decision-makers should treat outputs as directional under stable regulatory enforcement and uninterrupted East Asian semiconductor supply assumptions; material deviation in EPA FIFRA renewal timelines or export licensing disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Bean Harvester Market
Agricultural Equipment
Global Yield Monitoring Devices Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Stock Tanks Market