
 Aquarium Pumps and Filters Market | 2026-2036
Aquarium Pumps and Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Aquarium Pumps and Filters Market Outlook
Chinese OEM pump manufacturing is decoupling from legacy European supply chains as domestic producers scale brushless DC motor output. Fluval leverages captive R&D in biological media to sustain premium positioning across North American specialty retailers. Eheim anchors its reputation on German-engineered canister durability, while Sunsun competes aggressively on cost-optimized submersible units for emerging Asian markets.
Aquarium pumps and filters are electromechanical water circulation and purification systems, typically rated by flow rate in gallons per hour and pressure head in feet, designed to maintain dissolved oxygen levels and remove nitrogenous waste from closed aquatic environments. Canister filters dominate margin pools in the premium residential segment due to multi-stage mechanical-biological-chemical capacity and extended service intervals. Submersible pumps represent the fastest-growing product category as aquarists prioritize energy-efficient, low-noise designs for open-tank aquascaping. Power filters occupy the mature mass-market tier, while UV sterilization technology is displacing traditional chemical filtration in commercial systems handling high bioloads.
The US EPA regulates effluent discharge from commercial aquaculture operations, indirectly mandating filtration performance standards that cascade into equipment procurement specifications. China's SAMR enforces motor efficiency grades under GB standards that directly constrain pump design parameters for domestic and export markets. Germany's ECHA administers REACH restrictions on impeller coatings and seal materials, forcing reformulation of wetted components. Stakeholders must monitor how efficiency regulations in major manufacturing jurisdictions reshape cost structures and determine which technology platforms achieve cross-border compliance without performance trade-offs.
Market Dynamics
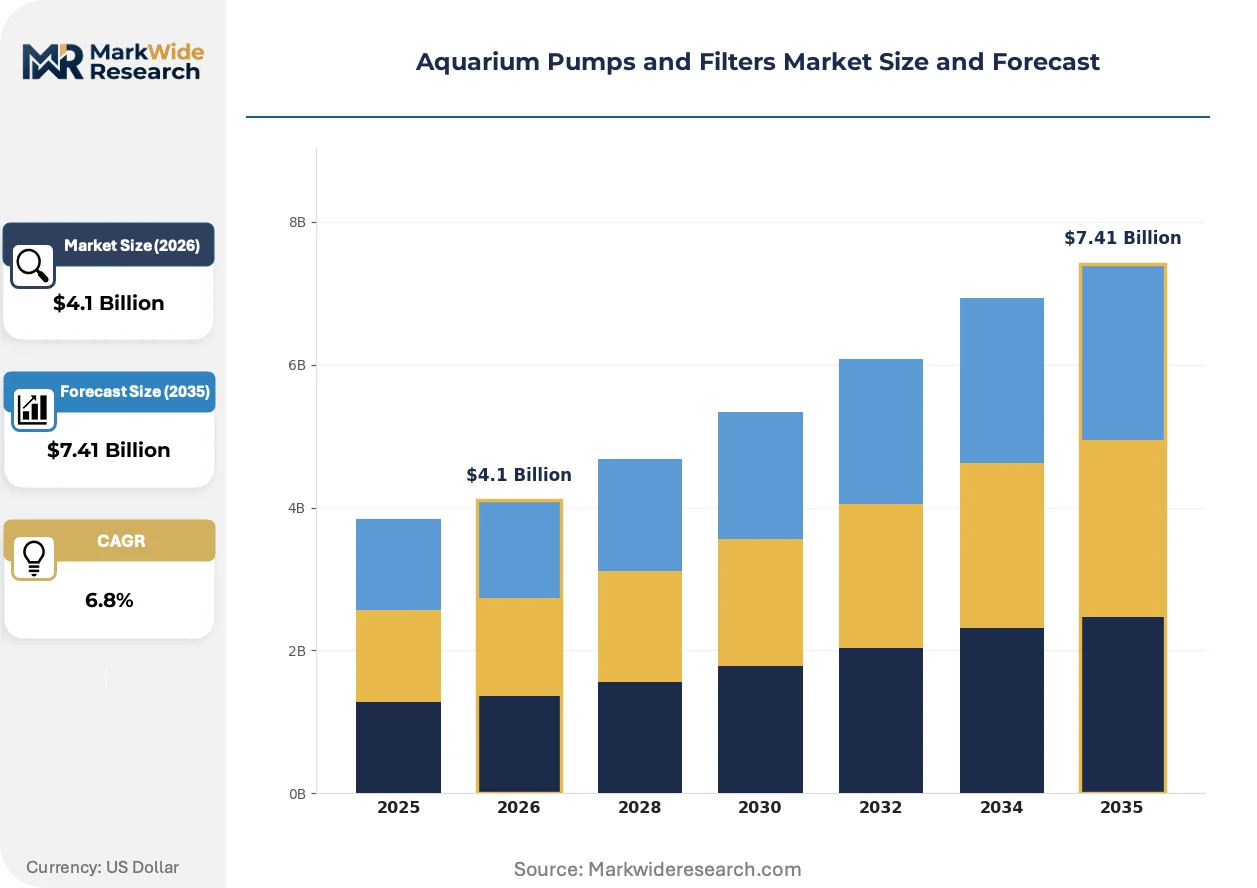
The aquarium pumps and filters market is restructuring around brushless DC motor adoption and recirculating aquaculture system mandates, as efficiency regulations in China and water discharge rules in the US compress legacy product margins while opening premium tier expansion.
Growth Catalysts
- Brushless DC motor platforms:China's SAMR efficiency grades under GB 18613 are forcing pump redesigns that simultaneously cut energy consumption and extend operational lifespan in commercial recirculating systems.
- Intensive aquaculture clusters:Vietnam's Mekong Delta shrimp farming operations are deploying multi-stage canister filtration to meet export certification requirements for antibiotic-free production.
- REACH chemical reformulation:Germany's ECHA restrictions on wetted component coatings are accelerating compliant seal material development that transfers across EU and Asian export markets.
Market Restraints
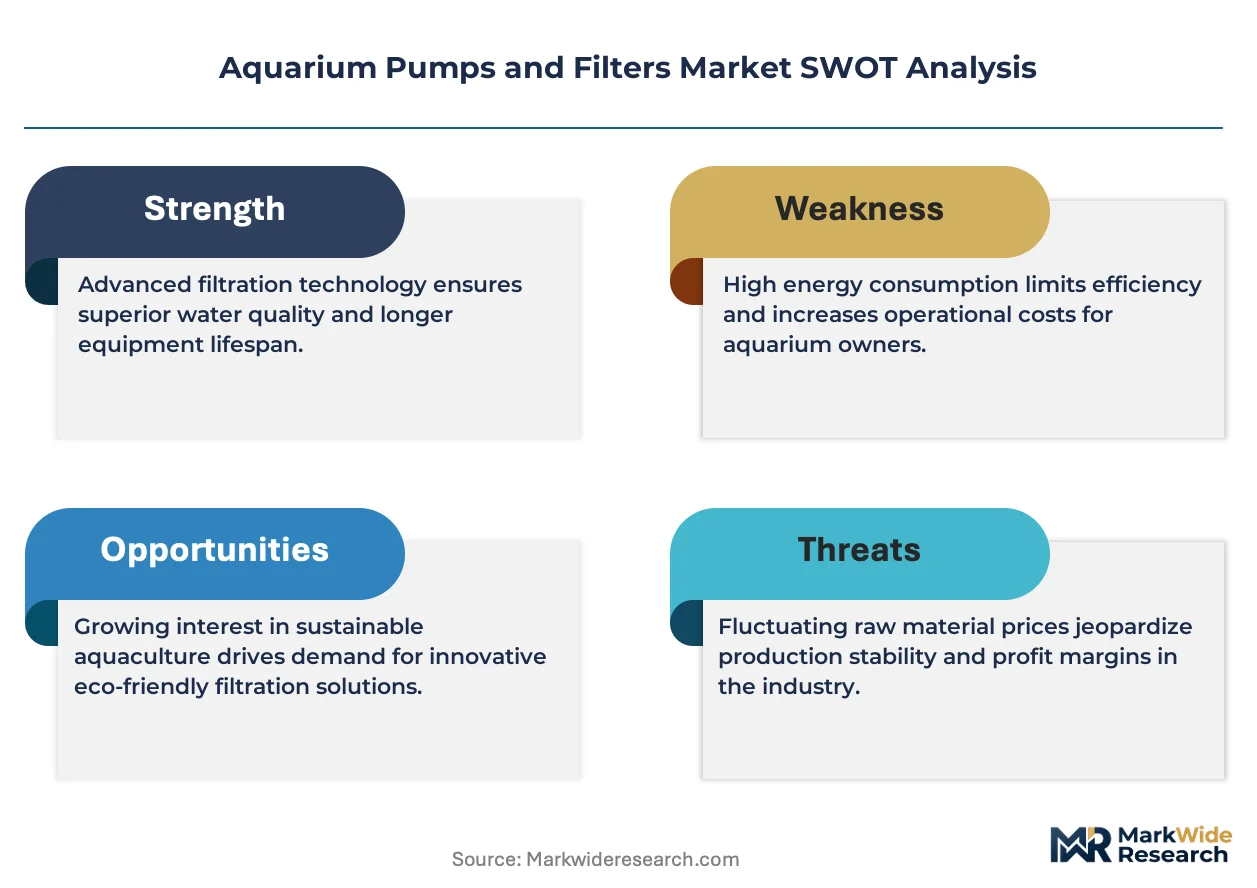
- Rare earth magnet supply concentration:Neodymium sourcing dependence on Chinese processing facilities creates input cost volatility for high-efficiency brushless motor production.
- Canister filter technical ceiling:Multi-stage biological media capacity faces physical scaling limits in residential tanks below 40 gallons, constraining premium segment addressable market.
- UV sterilization substitution threat:Commercial aquaculture operators are bypassing traditional chemical filtration entirely in favor of closed-loop UV-C systems for high-bioload environments.
Strategic Opportunities
- Indonesia aquaculture underpenetration:Archipelago nation marine farming operations remain below regional filtration intensity averages, presenting first-mover positioning for recirculating system suppliers.
- IoT-enabled predictive maintenance:Sensor-integrated pumps allowing flow-rate optimization and failure prediction are unifying hardware sales with recurring software revenue in North American specialty retail.
- US EPA effluent compliance tailwind:Discharge mandate enforcement from commercial aquaculture facilities is cascading into mandatory equipment procurement specifications that favor certified filtration performance tiers.
Industry Challenges
- Biological media formulation IP complexity:Proprietary ceramic and sintered glass compositions from established manufacturers create licensing barriers for new entrants seeking equivalent nitrification surface area.
- Cross-border certification timeline friction:Simultaneous GB standard compliance for China, REACH conformity for Germany, and EPA discharge alignment for US markets extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquarium Pumps and Filters Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Canister Filters, Power Filters, Air Pumps End User: Aquarists, Retailers, Wholesale Distributors, Aquatic Centers Technology: Mechanical Filtration, Biological Filtration, Chemical Filtration, UV Sterilization Capacity: Small Aquariums, Medium Aquariums, Large Aquariums, Commercial Systems |
| Companies Covered | Fluval, Eheim, AquaClear, Tetra, Marineland, Hydor, Sunsun, Aqueon, Juwel Aquarium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquarium Pumps and Filters Market Strategic Shifts
Active unification of hardware and digital control layers is compressing traditional equipment margins while opening service-based revenue streams. Three convergent developments are restructuring competitive positioning across residential and commercial segments.
Variable frequency drive technology is unifying pump flow control with real-time dissolved oxygen monitoring in commercial recirculating systems. Salmon and shrimp RAS operators in Norway and Chile are retrofitting existing infrastructure with sensor-integrated units that modulate output based on biomass loading. This convergence is compressing energy expenditure per kilogram of production while elevating equipment specification complexity beyond commodity pump procurement.
China's MIIT is tightening motor efficiency enforcement through expanded GB standard coverage that now captures submersible pump categories previously exempt. Domestic manufacturers are redesigning impeller geometries and magnetic coupling systems to meet Grade 1 efficiency thresholds. Export-oriented producers in Guangdong and Zhejiang provinces are absorbing compliance costs into premium product lines rather than economy tiers, reshaping competitive segmentation in Southeast Asian distribution channels.
Specialist aquascaping retailers are unbundling after-sales service from equipment transactions, shifting toward subscription-based media replacement and system calibration programs. North American hobbyist channels are piloting this model most aggressively, with independent stores in California and Texas restructuring staff roles from sales to ongoing maintenance advisory. This behavioral pivot is elevating lifetime customer value metrics over point-of-sale margin capture in distributor negotiations.
Aquarium Pumps and Filters Market Segmentation
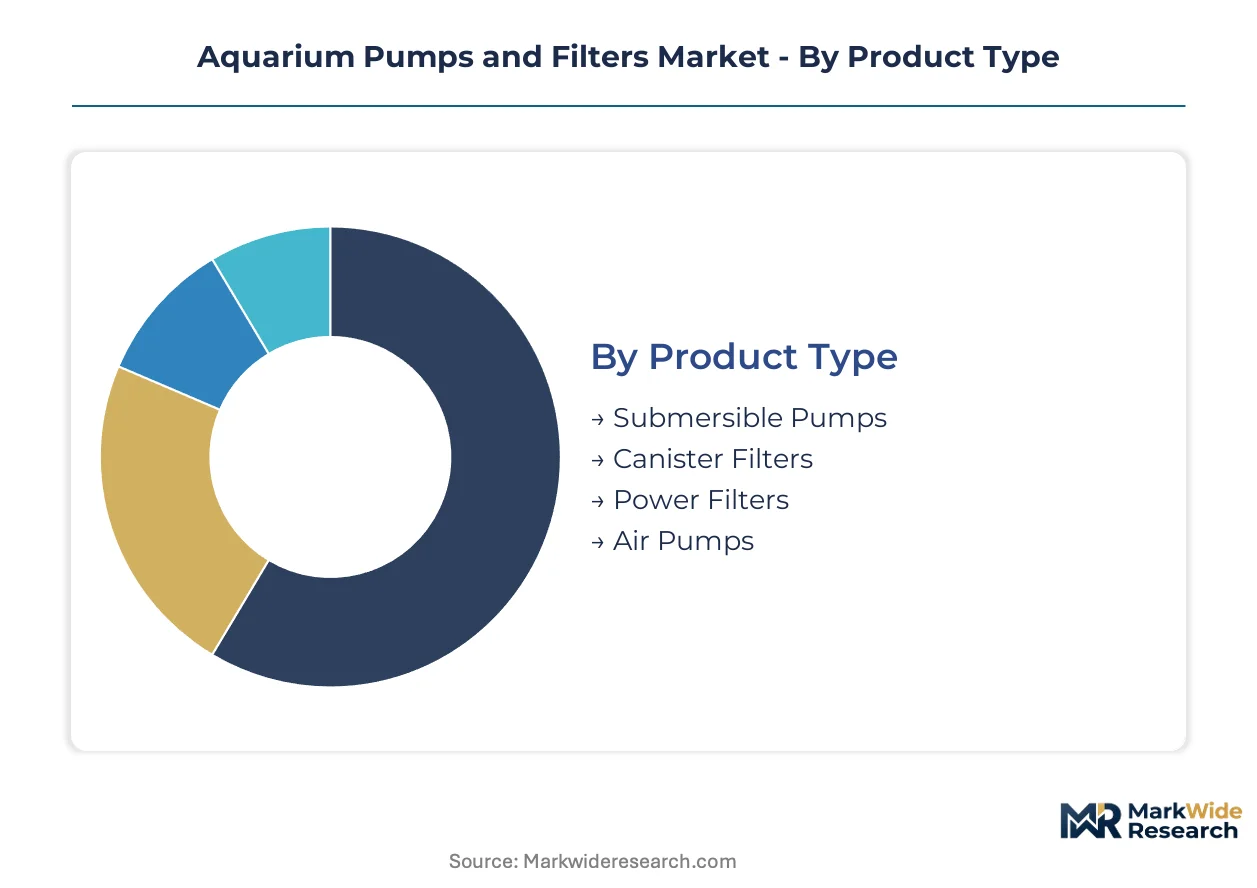
Segmentation in aquarium pumps and filters reveals how capital deployment, technical complexity, and regulatory exposure fragment procurement behavior across residential hobbyists and commercial operators. Equipment specifications diverge sharply between low-volume retail channels and intensive recirculating aquaculture systems.
Product Type:
Capital intensity escalates from air-driven circulation to multi-stage pressurized filtration, with motor technology and housing materials driving upfront cost differentials.
- Submersible Pumps:Magnetically coupled brushless DC motors deliver flow rates from 80 to 3,000 gallons per hour through compact waterproof housings. Vietnam's Mekong Delta shrimp farms are specifying submersible units with Grade 1 efficiency ratings under China's GB 18613 standards to cut energy expenditure in 24-hour recirculating operations.
- Canister Filters:Pressurized multi-chamber systems accommodate mechanical, biological, and chemical media stages with service intervals extending to six months. North American specialty retailers capture premium margins on canister installations in planted aquascaping segments where dissolved nutrient control commands hardware investment.
- Power Filters:Hang-on-back designs integrate pump and filtration in single units for entry-level residential tanks.
- Air Pumps:Diaphragm-driven aeration systems serve basic oxygenation needs in breeding and quarantine applications.
Most installed capacity flows through submersible pumps. Expansion is steepest in canister filtration.
End User:
Procurement sophistication deepens from individual hobbyists to institutional buyers, with compliance documentation and volume pricing restructuring channel economics.
- Aquarists:Individual consumers purchasing through brick-and-mortar specialty stores and direct-to-consumer platforms. Germany's REACH-compliant seal specifications are filtering down to enthusiast segments through retailer sourcing requirements that exclude non-conforming inventory.
- Retailers:Independent aquascaping shops and pet store chains holding inventory for immediate fulfillment. California and Texas operators are restructuring toward subscription-based media replacement programs that unify equipment sales with recurring service revenue.
- Wholesale Distributors:Regional logistics intermediaries consolidating manufacturer output for fragmented retail networks.
- Aquatic Centers:Public aquariums and research facilities specifying redundant filtration for rare specimen survival.
Volume concentrates with wholesale distributors. Value capture is climbing fastest among aquatic centers.
Technology:
Biological treatment capacity commands the highest engineering investment, while UV hardware faces substitution pressure from chemical-free compliance mandates.
- Mechanical Filtration:Physical particulate removal through sponge, floss, or screen media with specified micron ratings. Indonesia's underpenetrated marine farming sector is deploying mechanical pre-filtration as the first stage in multi-tier systems before biological treatment.
- Biological Filtration:Ceramic and sintered glass media hosting nitrifying bacterial colonies on high-surface-area substrates. Proprietary media formulations from established manufacturers create licensing barriers that protect incumbent margin structures in premium residential segments.
- Chemical Filtration:Activated carbon and ion-exchange resins targeting dissolved organics and heavy metals.
- UV Sterilization:UV-C chamber systems disrupting pathogen and algae DNA without residual chemical load.
Biological filtration carries the largest installed base. UV sterilization is gaining share fastest in commercial aquaculture.
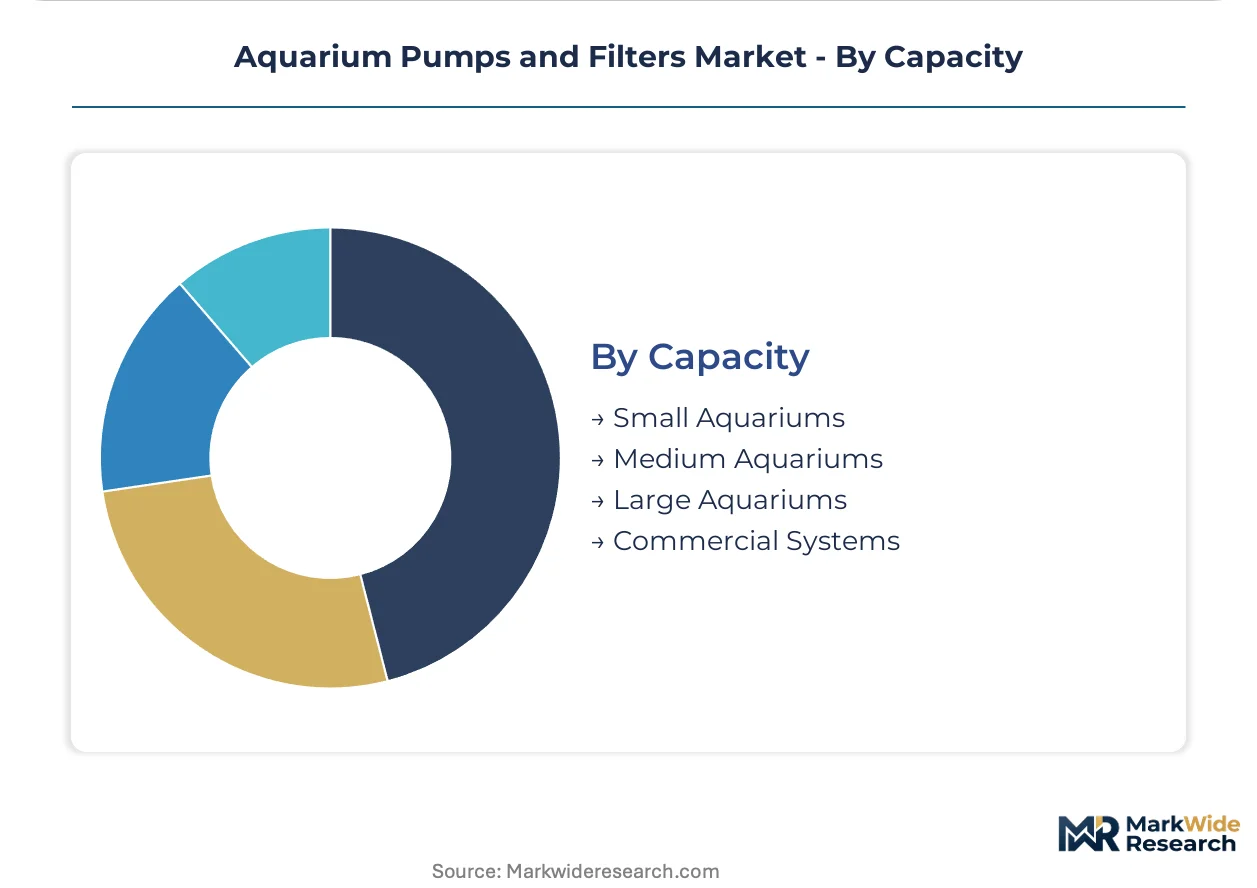
Capacity:
System scale determines pressure head requirements, multi-pump redundancy, and integration complexity with building infrastructure.
- Small Aquariums:Systems below 40 gallons utilizing single-point filtration with minimal head pressure. China's domestic OEM producers are scaling brushless DC output to capture economy-tier replacement demand in compact residential installations.
- Medium Aquariums:Tanks from 40 to 120 gallons requiring matched flow rates and supplemental aeration. US EPA effluent compliance for commercial breeding operations is cascading into medium-system specifications that favor certified performance tiers over commodity procurement.
- Large Aquariums:Residential installations exceeding 120 gallons with dedicated sump filtration.
- Commercial Systems:Recirculating aquaculture operations with tonnage-scale bioload management.
Commercial systems absorb the greatest capital deployment. Medium aquariums show the steepest expansion trajectory in absolute unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's export-oriented manufacturing clusters and Germany's precision engineering centers operate on fundamentally different competitive logics, yet both shape procurement patterns for aquarium equipment across Southeast Asian aquaculture markets.
United States
Commercial aquaculture operations in Louisiana and Mississippi are retrofitting recirculating systems to meet EPA effluent discharge mandates. The agency's enforcement cascade is pushing medium-scale breeders toward certified filtration tiers rather than commodity procurement. Florida's ornamental fish farming corridor around Tampa Bay is consolidating distributor relationships around documented compliance packages.
Germany
ECHA's REACH restrictions on wetted component coatings are forcing reformulation of seal materials and impeller coatings across European supply chains. Baden-Württemberg's precision manufacturing belt hosts engineering specialists serving premium residential segments. Bavaria's industrial pump fabricators are adapting magnetic coupling designs for aquarium-specific pressure head requirements.
China
SAMR's GB 18613 motor efficiency grades are capturing submersible pump categories previously exempt from compliance. Guangdong and Zhejiang export-oriented producers are absorbing Grade 1 certification costs into premium product lines rather than economy tiers. The Pearl River Delta's brushless DC motor clusters are scaling output for Vietnamese and Indonesian distribution channels.
Vietnam
Mekong Delta shrimp farming operations are deploying multi-stage canister filtration to meet export certification requirements for antibiotic-free production. The country's aquaculture regulator is tightening water quality documentation for EU-bound shipments. Intensive farming clusters around Cần Thơ are driving premium equipment adoption previously unseen in Southeast Asian markets.
Indonesia
Archipelago marine farming operations remain below regional filtration intensity averages, presenting positioning opportunities for recirculating system suppliers. The national fisheries ministry is drafting technical standards modeled on Chinese GB efficiency frameworks. Sulawesi and Sumatra aquaculture zones are piloting mechanical pre-filtration as first-stage infrastructure before biological treatment expansion.
Aquarium Pumps and Filters Market Competitive Environment
Chinese producers anchor the volume-driven tier; German specialists hold the premium engineering segment. The vendor base splits between scale-oriented OEM fabricators and R&D-intensive branded manufacturers. Three archetypes dominate: efficiency-certified exporters, biological media specialists, and integrated aquascaping solution providers. Capacity expansion and cross-border certification partnerships represent the dominant competitive moves as compliance timelines extend product launch cycles.
Within the premium-tier vector, Fluval and Eheim exemplify positioning anchored on captive R&D and regional engineering reputation. Sunsun occupies a position on the cost-optimized export vector serving emerging Asian markets. These three entities represent the geographic and strategic spread visible across the competitive set: North American specialty retail penetration, German durability engineering, and Chinese scale manufacturing.
| Leading Market Players |
|---|
| Fluval |
| Eheim |
| AquaClear |
| Tetra |
| Marineland |
| Hydor |
| Sunsun |
| Aqueon |
| Juwel Aquarium |
| Others |
Value Chain & Pricing Dynamics
Commercial aquaculture operators in Vietnam's Mekong Delta cluster concentrate procurement volume for Grade 1 efficiency-certified submersible pumps, anchoring a three-tier pricing structure across premium, standard, and economy levels that stratifies by certification grade and after-sales service bundling.
Pricing Analysis
Capacity additions in Guangdong and Zhejiang provinces are reshaping price floors for brushless DC motor platforms as domestic Chinese OEMs absorb GB 18613 compliance costs into premium product lines rather than economy tiers. Price differentiation hinges on motor efficiency certification under China's SAMR standards and geographic delivery cost to Southeast Asian distribution channels. Cost compression in the standard tier is intensifying because of rare earth magnet input volatility. Hobbyist segments through North American specialty retailers show least price sensitivity, while Indonesian marine farming operations exhibit highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
REACH conformity documentation and GB standard certification serve as the primary gating mechanisms for component suppliers seeking access to European and Chinese OEM channels. Manufacturing concentrates in China, Germany, and Vietnam, with neodymium magnet processing anchored in Chinese facilities and precision seal fabrication resting on Baden-Württemberg engineering clusters. Raw material dependencies include rare earth magnets, ceramic media substrates, and UV-C lamp quartz sleeves. Single-source vulnerability in neodymium processing creates structural exposure to export restriction shocks. Distribution runs through wholesale distributors consolidating fragmented retail networks across Southeast Asian aquaculture zones and North American specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Vietnam's antibiotic-free export certification requirements are shifting procurement toward premium filtration specifications with documented compliance packages.
For Market Incumbents: Cement biological media formulation advantages through captive R&D in ceramic and sintered glass compositions, creating licensing barriers against emerging Asian OEMs. Deepen upstream control over brushless DC motor supply through partnerships with Guangdong magnetic coupling specialists. UV sterilization substitution in commercial RAS environments represents the priority threat requiring defensive capability investment.
For New Entrants and Emerging Players: Capture Indonesia's underpenetrated marine farming sector by leading with mechanical pre-filtration systems as first-stage infrastructure before biological treatment expansion. Sulawesi and Sumatra aquaculture zones offer the most penetrable geographic entry point. Position through the national fisheries ministry's drafting technical standards modeled on Chinese GB efficiency frameworks.
For Investors and Strategic Acquirers: Industrial pump fabricators diversifying into aquarium-specific pressure head applications are the most active acquirer in this space. The five-to-ten year viability window favors targets with cross-border certification infrastructure spanning GB, REACH, and EPA compliance timelines. Acquisition target archetype: mid-cap specialists with established aquatic center relationships and redundant filtration engineering capabilities. Monitor enforcement intensity of US EPA effluent discharge mandates as the signal to watch for inflection in commercial procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| GB 18613 Grade 1 Certification Investment | SAMR efficiency enforcement captures previously exempt submersible categories, reshaping competitive segmentation. |
| Biological Media Formulation Partnership | Proprietary ceramic compositions from established manufacturers protect margin structures in premium residential segments. |
| Indonesia Distribution Channel Establishment | Archipelago marine farming operations remain below regional filtration intensity averages, presenting first-mover positioning. |
| IoT Sensor Integration Development | Flow-rate optimization and failure prediction capabilities unify hardware sales with recurring software revenue in North American specialty retail. |
| REACH-Compliant Seal Material Reformulation | ECHA restrictions on wetted component coatings force reformulation that transfers across EU and Asian export markets. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with commercial aquaculture operations managers, specialty retailer procurement leads, OEM plant engineers, and biological media R&D directors alongside secondary validation. Sources include customs and trade data on pump and filter shipments, SAMR GB standard enforcement documentation, ECHA REACH restriction updates, and EPA effluent discharge enforcement records. Bottom-up equipment unit deployment estimates triangulate against top-down market value reconstruction.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window. Segmentation dimensions modeled include product type, end user category, filtration technology, and system capacity tier alongside regional regulatory cluster alignment. CAGRs derive from fitted growth curves applied to equipment replacement cycles and aquaculture facility expansion pipelines. Industry-specific forecast inputs incorporate brushless DC motor efficiency adoption curves and recirculating aquaculture system mandate implementation timelines.
Regulatory enforcement delays, rare earth supply disruption, and UV sterilization technology cost curves are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on certification timeline friction and cross-border compliance cost absorption. A model refresh is warranted upon material change in China's MIIT motor efficiency enforcement scope or US EPA commercial aquaculture discharge mandate intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Powder Feed Center Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Global Yield Monitoring Devices Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Grafting Knives Market