
 Plucker Machine Market | 2026-2036
Plucker Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Plucker Machine Market Analytics
Equipment leasing and project finance is narrowing the competitive gap between capital-heavy incumbents and mid-tier entrants. Meyn Food Processing Technology B.V. leverages its vertical integration into upstream component supply to sustain margin control across European installations. Marel anchors its position through R&D intensity in vision-guided plucker alignment systems. Zhucheng Xinhaoyun Machinery Co., Ltd competes on manufacturing scale from its Shandong production base, shipping medium-duty units across Southeast Asia.
A plucker machine mechanically removes feathers from slaughtered poultry using rotating rubber fingers or discs, with drum speeds typically ranging from 150 to 300 RPM depending on bird weight class; the equipment serves commercial processing lines requiring throughput above 1,000 birds per hour. Automated pluckers now dominate new capital expenditure as processors replace batch-style mechanical units, while electric drive technology displaces pneumatic systems in facilities seeking energy recovery and reduced compressed-air infrastructure. The medium-size segment leads volume shipments in emerging markets, whereas extra-large configurations command the deepest margin pools at integrated poultry giants running continuous-line operations.
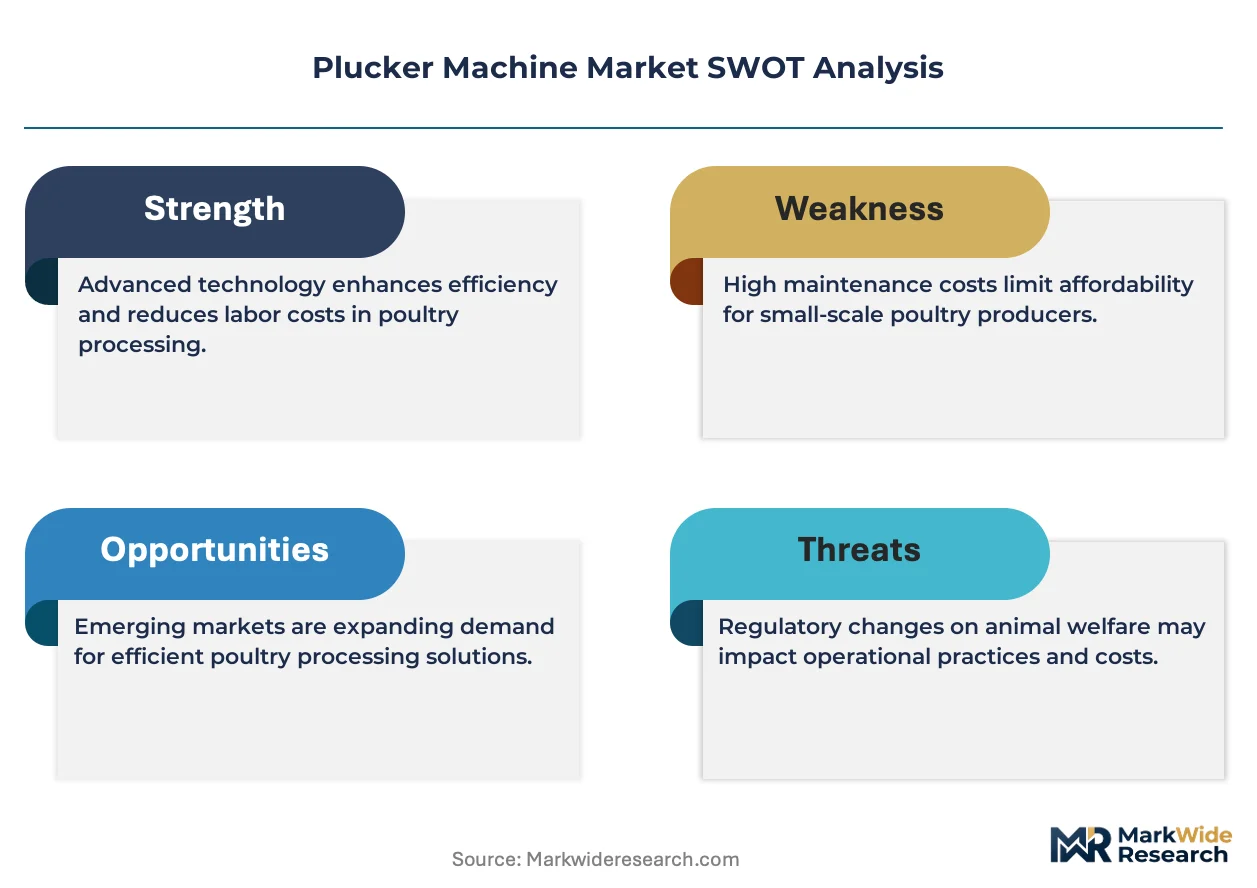
The USDA enforces sanitary equipment standards through its Food Safety and Inspection Service, mandating washdown-rated construction that shapes stainless-steel specification across US-bound production. China's SAMR implements GB standards for food-contact machinery safety, creating compliance layers for exporters targeting domestic processors. The EU MDR and CE marking frameworks extend to processing equipment hygiene design, conditioning market access for non-European suppliers. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional product variants.
Market Dynamics
Electric drive technology is collapsing the installed base of pneumatic pluckers as processors seek energy recovery and reduced compressed-air infrastructure, while the EU F-Gas Regulation accelerates refrigerant-related equipment redesign across European installations.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated greenhouse gases are forcing equipment makers toward electric drive systems, creating replacement demand across facilities running legacy pneumatic infrastructure.
- Commercial poultry farms in Brazil:Rising labor costs are scaling automated plucker adoption as processors replace manual batch operations with continuous-line configurations.
- Shandong province clustering:Zhucheng-based manufacturers concentrate medium-duty production, enabling cost-efficient export logistics into Southeast Asian markets.
Market Restraints
- Stainless-steel input volatility:Washdown-rated construction mandates from the USDA Food Safety and Inspection Service tie specification to commodity metal pricing, compressing margin predictability for fabricators.
- Component supply concentration:Rubber finger and disc sourcing clusters in select Asian manufacturing zones, exposing procurement to single-point disruption risk.
- Technical limitation in small-batch adaptation:Automated drum systems require throughput above 1,000 birds per hour to justify capital deployment, excluding artisanal and farm-gate processors from the technology curve.
Strategic Opportunities
- Underpenetrated Indonesia:Archipelago logistics and fragmented cold-chain infrastructure delay automated adoption, creating first-mover positioning for leasing-model entrants.
- Vision-guided alignment convergence:Machine vision paired with adaptive drum positioning enables precision plucking across variable bird weights, opening premium-tier contracts with integrated poultry giants.
- India PLI scheme:Production-linked incentives for food-processing machinery attract domestic assembly investment, reducing import duty exposure for multinational component suppliers.
Industry Challenges
- Electromechanical technician scarcity:Electric drive maintenance requires skill sets distinct from pneumatic system repair, stretching service coverage in remote processing regions.
- USDA-CE marking dual certification:Divergent hygiene-design standards between North American and European regulators extend product development timelines for platform-standardization strategies.
- Legacy batch-system integration:Retrofitting continuous-line pluckers into existing plant footprints demands custom engineering, delaying project commissioning and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plucker Machine Market |
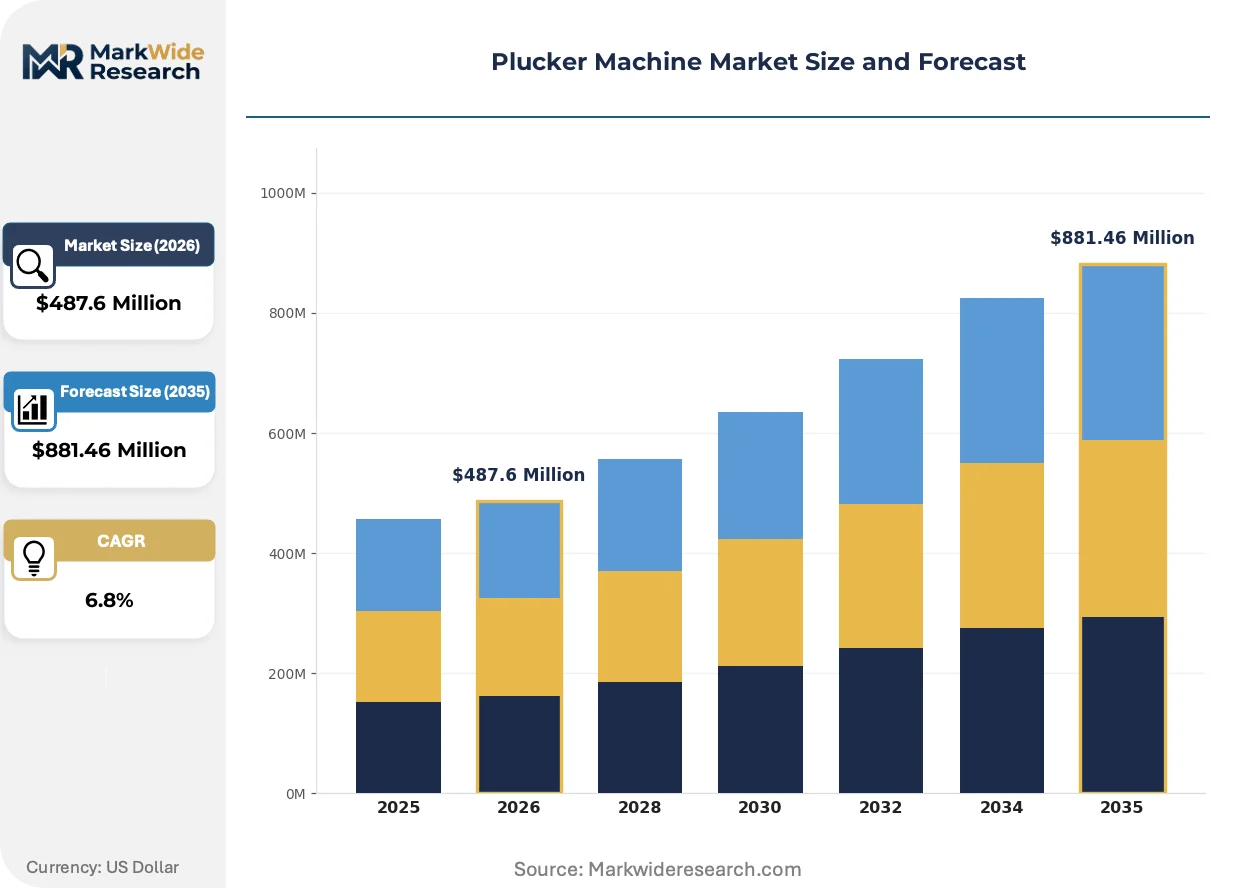
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Pluckers, Electric Pluckers, Handheld Pluckers, Automated Pluckers End User: Commercial Poultry Farms, Small-Scale Farms, Food Processing Companies, Households Technology: Pneumatic, Hydraulic, Electric, Hybrid Size: Small, Medium, Large, Extra Large |
| Companies Covered | Meyn Food Processing Technology B.V., Marel, Baader Group, Foodmate B.V., Zhucheng Xinhaoyun Machinery Co., Ltd, Zhucheng Xincheng Mingshun Machinery Co., Ltd, VEVOR, KITCHENER, Yardbird, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plucker Machine Market Evolving Landscape
Active transformation in plucker machine design centers on energy-system substitution, regulatory compliance architecture, and procurement model restructuring across buyer segments.
Direct-drive permanent magnet motors are collapsing the cost advantage of pneumatic infrastructure in new facility construction. Mid-scale processors in Thailand and Vietnam now specify electric configurations as standard, bypassing compressed-air capital entirely. The technology is collapsing the traditional two-tier market structure that separated pneumatic economy lines from electric premium tiers.
The EU F-Gas Regulation imposes phasedown quotas on hydrofluorocarbon refrigerants, extending compliance obligations to processing equipment with integrated cooling functions. European OEMs are redesigning thermal management subsystems to eliminate refrigerant dependency. Installations in Germany and the Netherlands face the tightest retrofit deadlines, accelerating replacement purchasing ahead of mandate enforcement.
Equipment leasing is displacing outright purchase in emerging-market capital deployment. Southeast Asian distributors now bundle maintenance and upgrade clauses into multi-year contracts, transferring obsolescence risk from processors to financiers. This pattern is most visible in Vietnam's Mekong Delta processing corridor, where project finance narrows the competitive gap between capital-heavy incumbents and mid-tier entrants.
Plucker Machine Market Segmentation
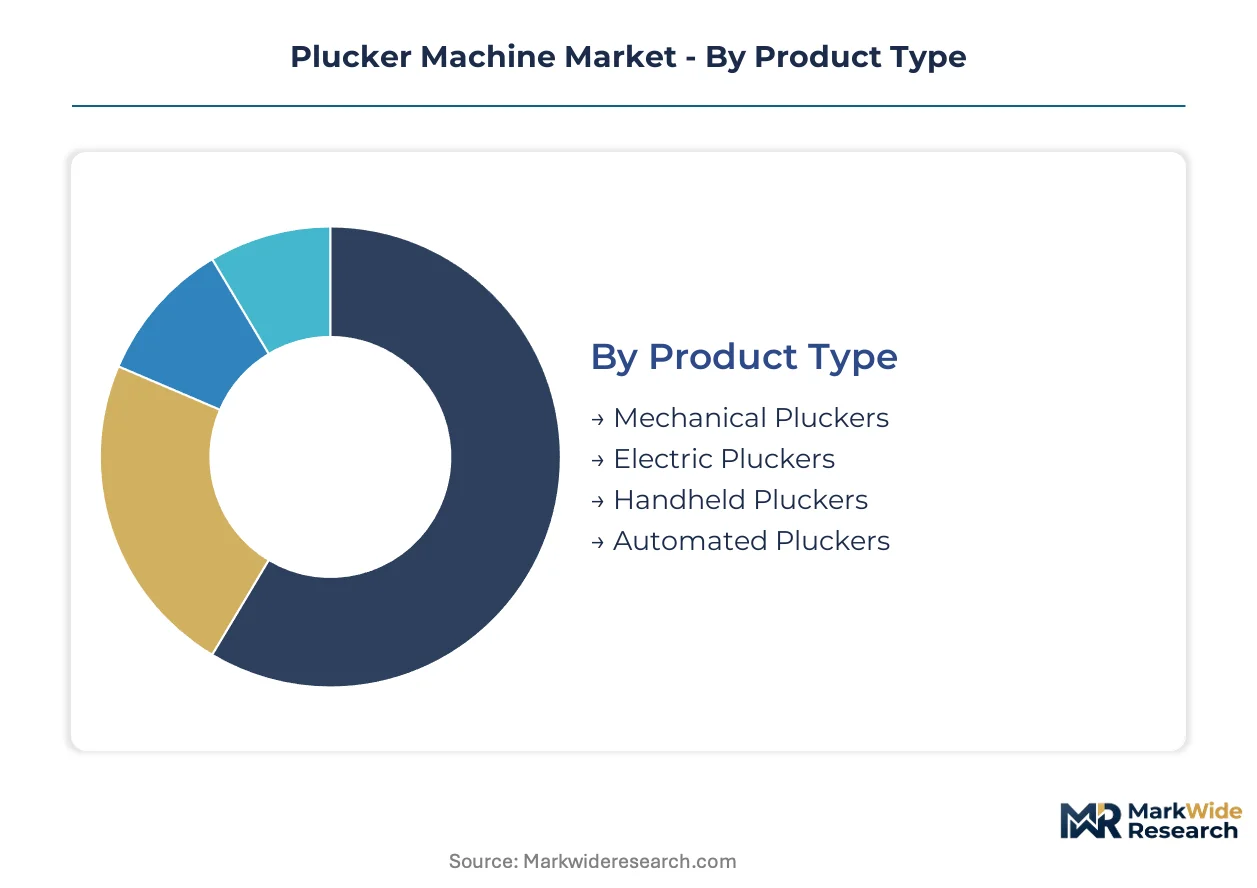
Segmentation in plucker machine procurement tracks the divergence between capital-intensive continuous-line installations and intermittent-use equipment serving smaller-scale operations. Cycle times vary dramatically across these boundaries, with replacement intervals stretching from 3-5 years for pneumatic batch units to 10-15 years for electric drive systems in integrated processing plants.
Product Type:
Replacement velocity distinguishes this category most sharply, with pneumatic mechanical units turning over fastest as processors abandon compressed-air infrastructure, while automated electric configurations embed for decade-long service lives.
- Mechanical Pluckers:Batch-style drum systems with rubber finger arrays driven by belt-and-pulley transmissions dominate legacy installations in Southeast Asian processing cooperatives. Thailand's central plains processors still specify these for throughput below 800 birds per hour where electric capital cannot be justified.
- Electric Pluckers:Direct-drive permanent magnet motors eliminate compressed-air dependency while enabling energy recovery through regenerative braking. Brazil's commercial poultry farms are scaling adoption as labor costs render manual batch operations uneconomical, with São Paulo state processors leading capital deployment.
- Handheld Pluckers:Portable units with DC motors serve farm-gate slaughter in Indonesia's outer islands where cold-chain gaps prevent centralized processing.
- Automated Pluckers:Vision-guided alignment systems with adaptive drum positioning command premium contracts from integrated poultry giants running continuous-line operations above 2,000 birds per hour.
Mechanical pluckers anchor the volume base in emerging markets while automated pluckers gain share at the steepest rate among integrated processors replacing batch infrastructure.
End User:
Procurement scale separates this category, with household units representing single-unit purchases against fleet orders spanning 20-50 machines for integrated processing complexes.
- Commercial Poultry Farms:Large-scale operations with biosecurity protocols and veterinary oversight mandate stainless-steel washdown-rated construction compliant with USDA Food Safety and Inspection Service standards. These buyers specify electric drive systems exclusively, treating pneumatic infrastructure as stranded asset risk.
- Small-Scale Farms:Operations processing 50-200 birds daily favor mechanical or handheld configurations with lower capital barriers and maintenance simplicity. Vietnam's Mekong Delta corridor concentrates this demand, where equipment leasing models now displace outright purchase.
- Food Processing Companies:Third-party toll processors serving multiple farm suppliers require quick-change drum configurations accommodating variable bird weights across contract batches.
- Households:Backyard poultry keepers in peri-urban China purchase compact electric units through e-commerce platforms, with Shandong province manufacturers dominating this price-sensitive segment.
Commercial poultry farms command the deepest margin pools while small-scale farms represent the largest addressable unit count.
Technology:
Energy architecture determines competitive positioning, with electric systems collapsing the historical cost advantage of pneumatic infrastructure in new facility construction.
- Pneumatic:Compressed-air drum actuation retains installed base in legacy plants but faces accelerated replacement as EU F-Gas Regulation compliance costs compound energy inefficiency. European OEMs have largely exited new pneumatic system development.
- Hydraulic:High-torque fluid power systems serve extra-large configurations processing turkeys and heavy breeders where electric motor sizing becomes prohibitive. These installations cluster in US Midwest integrated operations with in-house maintenance capabilities.
- Electric:Permanent magnet synchronous motors with variable frequency drives enable precision speed control across 150-300 RPM ranges matched to bird weight classes. Mid-scale processors in Thailand and Vietnam now specify electric as standard, bypassing compressed-air capital entirely.
- Hybrid:Combined electric-hydraulic architectures optimize torque delivery for mixed-species processing lines handling both broilers and turkeys on shared equipment.
Electric technology anchors current specification trends while hybrid configurations expand most quickly among diversified processors seeking species flexibility.
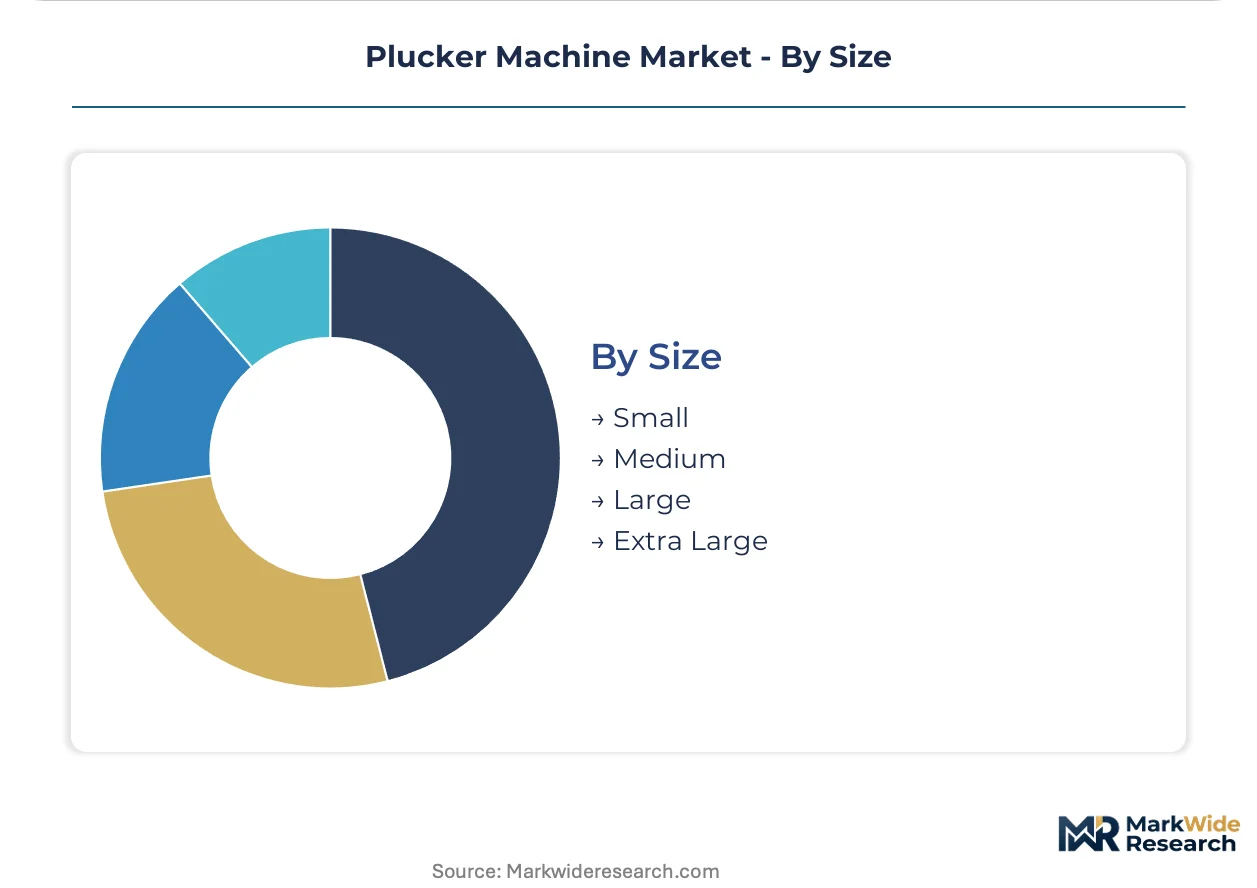
Size:
Throughput thresholds structure this category, with capital deployment justification requiring minimum viable scale that excludes smaller operations from automated technology curves.
- Small:Units processing under 500 birds per hour serve farm-gate and artisanal slaughter operations with batch-style loading. These configurations dominate household and small-farm procurement in Indonesia's archipelago logistics environment.
- Medium:Configurations rated 500-1,500 birds per hour concentrate production in China's Shandong province, with Zhucheng-based manufacturers achieving cost-efficient export logistics into Southeast Asian markets. This segment leads volume shipments across emerging economies.
- Large:Systems processing 1,500-3,000 birds per hour integrate into continuous-line operations at regional processing complexes. Brazil's southern poultry belt specifies these for export-oriented operations requiring FSIS-equivalent sanitary standards.
- Extra Large:Configurations exceeding 3,000 birds per hour command the deepest margin pools at integrated poultry giants with dedicated engineering staff and predictive maintenance programs. These installations require custom foundation work and represent decade-long capital commitments.
Medium-size units anchor shipment volumes in emerging markets while extra-large configurations capture the steepest margin expansion among top-tier integrated processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-tier contracts in Germany command pricing multiples above Shandong province exports, yet volume gravity concentrates where labor-cost pressures and regulatory retrofit deadlines intersect.
United States
Integrated poultry giants in the Midwest specify extra-large electric configurations above 3,000 birds per hour. USDA Food Safety and Inspection Service washdown mandates shape stainless-steel procurement across Arkansas and Georgia processing corridors. Equipment financing through agricultural credit cooperatives accelerates replacement cycles in the Southeast.
Brazil
Commercial farms in São Paulo state scale automated adoption as labor costs render manual batch operations uneconomical. ANVISA sanitary equipment protocols align with export-market FSIS equivalency requirements. Southern poultry belt processors concentrate capital deployment in Paraná and Rio Grande do Sul.
China
Shandong province manufacturers cluster medium-duty production in Zhucheng for cost-efficient Southeast Asian export logistics. SAMR GB standards for food-contact machinery safety create compliance layers for domestic-market targeting. Backyard poultry demand in peri-urban zones sustains compact electric unit shipments through e-commerce channels.
Germany
EU F-Gas Regulation phasedown quotas force refrigerant-dependent equipment redesign ahead of mandate enforcement. Dutch and German OEMs accelerate thermal management subsystem development. Installations in Lower Saxony poultry processing face the tightest retrofit deadlines, compressing replacement purchasing timelines.
Vietnam
Mekong Delta processors adopt equipment leasing models that displace outright purchase and transfer obsolescence risk to financiers. Mid-scale operators specify electric drive systems as standard, bypassing compressed-air capital entirely. Thai and Vietnamese distributors bundle maintenance clauses into multi-year contracts.
Plucker Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying rubber finger arrays and drive assemblies to multiple OEMs. Market structure consolidates around vertically integrated European incumbents and scale-driven Chinese fabricators, with mid-tier leasing entrants narrowing the competitive gap through project finance. Three archetypes dominate: full-line poultry processing system houses, regional machinery specialists with captive component production, and contract manufacturers serving private-label distributors. Capacity expansion in Shandong and strategic partnerships for Southeast Asian distribution represent the dominant competitive vectors.
Among Dutch full-line system houses, Meyn Food Processing Technology B.V. and Marel occupy positions defined by R&D intensity and vertical control over upstream supply. Baader Group and Foodmate B.V. exemplify the specialized European tier with concentrated poultry processing expertise. Zhucheng Xinhaoyun Machinery Co., Ltd and Zhucheng Xincheng Mingshun Machinery Co., Ltd represent the Shandong-based scale archetype, leveraging manufacturing concentration for export logistics efficiency into Southeast Asian markets. VEVOR, KITCHENER, and Yardbird populate the accessible-equipment tier serving small-farm and household demand through direct-to-retail channels.
| Leading Market Players |
|---|
| Meyn Food Processing Technology B.V. |
| Marel |
| Baader Group |
| Foodmate B.V. |
| Zhucheng Xinhaoyun Machinery Co., Ltd |
| Zhucheng Xincheng Mingshun Machinery Co., Ltd |
| VEVOR |
| KITCHENER |
| Yardbird |
| Others |
Value Network & Pricing Analysis
Shandong-to-Ho-Chi-Minh-City freight corridors concentrate medium-duty plucker unit logistics, with container rates feeding directly into Southeast Asian distributor markups and compressing margin pools for economy-tier fabricators while amplifying pricing power at European OEMs serving premium contracts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade—USDA FSIS washdown compliance versus CE marking—drives price differentiation alongside volume scale for fleet orders. Pricing pressure stems from stainless-steel input volatility compressing fabricator margins. Small-scale farm cooperatives exhibit highest price sensitivity; integrated poultry giants running continuous-line operations show lowest.
Supply Chain Analysis
Extended payment terms from Zhucheng-based manufacturers to Southeast Asian distributors now structure working capital flows across the procurement base. Component supply clusters in China, Thailand, and Vietnam for rubber finger arrays and drive assemblies. Single-source vulnerability in permanent magnet motor sourcing exposes procurement to disruption. Distribution runs through regional machinery distributors bundling maintenance into multi-year contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plucker machine market sits in early-cycle expansion as electric drive technology collapses pneumatic infrastructure economics and triggers replacement purchasing across installed bases.
For Market Incumbents: Harden margin control through captive supply of upstream drive assemblies and rubber finger arrays against mid-tier leasing entrants narrowing the competitive gap. Deepen certification investment in USDA-CE dual marking to extend platform standardization timelines. Channel control through distributor exclusivity in Vietnam's Mekong Delta processing corridor defends position against project finance competitors.
For New Entrants and Emerging Players: Pursue underpenetrated Indonesian archipelago markets where fragmented cold-chain infrastructure delays automated adoption. Target small-scale farm cooperatives in Vietnam with equipment leasing models displacing outright purchase. Go-to-market through Thai distributors bundling maintenance clauses captures first-mover positioning.
For Investors and Strategic Acquirers: Component-specialist fabricators with captive rubber finger production and Shandong manufacturing scale represent the priority acquisition archetype. Long-term viability centers on electric drive service ecosystem control as pneumatic installed base depreciates. Watch EU F-Gas Regulation enforcement timelines as inflection indicator for European replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Assemblies | Captive permanent magnet motor production insulates Meyn and Marel from supply disruption in Asian manufacturing zones. |
| Dual Certification Investment | USDA-CE marking convergence reduces product development timelines for platform-standardization strategies across Atlantic markets. |
| Equipment Leasing Model Deployment | Project finance narrows competitive gap between capital-heavy incumbents and mid-tier entrants in Southeast Asian markets. |
| Vision-Guided Alignment R&D | Machine vision paired with adaptive drum positioning opens premium-tier contracts with integrated poultry giants above 2,000 birds per hour. |
| Shandong Capacity Expansion | Zhucheng-based manufacturing concentration achieves cost-efficient export logistics into Vietnam and Indonesia processing corridors. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at integrated poultry processors, aftermarket service heads at European OEMs, procurement leads at Brazilian commercial farms, and distribution channel partners in Southeast Asia and refined through secondary validation against customs trade data, SEC filings from listed food-processing equipment manufacturers, ANVISA sanitary equipment protocol documentation, and EU F-Gas Regulation compliance databases. Bottom-up unit shipment estimates triangulated with top-down market sizing across technology and size segmentations.
Demand-supply balance modeling anchored the forecast framework across the analysis window. Segmentation dimensions included product type, end user, technology architecture, and size configuration alongside regional regulatory cluster differentiation. CAGRs derived from replacement cycle analysis and capital expenditure intention surveys. Industry-specific inputs encompassed labor cost trajectories in Brazilian poultry operations and EU refrigerant phasedown enforcement timelines.
Sensitivities concentrate around stainless-steel commodity pricing volatility, electromechanical technician scarcity in remote processing regions, and divergence between USDA and CE marking hygiene-design standards. Forecasts reflect documented assumptions on technology substitution rates and regional adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Plow Folding System Market