
 Global Precision Harvesting Market | 2026-2036
Global Precision Harvesting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Harvesting Market Intelligence
The substitution of traditional steel with lightweight composite materials in harvester components is repositioning equipment design for lower soil compaction and fuel efficiency. Deere & Company leverages its extensive dealer network and integrated technology stack to maintain a dominant market position. CNH Industrial NV competes through a multi-brand strategy, offering distinct product lines for different agricultural scales and regions.
Precision harvesting involves the use of technology to optimize crop collection based on real-time, in-field variability data. It integrates GPS guidance systems with sensors that measure parameters like crop yield and moisture content per square meter. GPS Guidance and Yield Monitoring technologies form the foundational layers of the market, while data analytics is the fastest-growing technology segment. Within equipment, combine harvesters represent the largest capital investment, but specialized units like cotton pickers offer higher margins for manufacturers.
Vehicle emissions standards, such as those set by the US EPA and included in Europe's F-Gas Regulation for mobile air conditioning, influence engine and component design. Data privacy rules, including the EU's GDPR, also shape how farm management platforms handle information collected by harvesting equipment. Stakeholders must decide whether to pursue open-platform data integration or develop proprietary, closed-loop technology ecosystems.
Market Dynamics
The convergence of onboard sensor data with artificial intelligence is the central force shaping the precision harvesting market. This shift moves the value proposition from purely mechanical efficiency to automated, data-driven decision-making that optimizes yield and resource use in real time.
Growth Catalysts
- AI-Powered Analytics:The integration of artificial intelligence with GPS guidance and sensor data enables predictive modeling for crop maturity and optimized harvesting paths, significantly boosting efficiency for large-scale cereal and oilseed farms.
- Government Incentives:Policies in jurisdictions like the European Union and the United States provide subsidies or tax credits for adopting precision agriculture technologies that support sustainability goals, such as reduced fuel consumption and optimized fertilizer use.
- Demand in Agricultural Hubs:Concentrated demand from agricultural powerhouses, including Brazil and Australia, for technologies that can manage vast, variable-terrain farms is pulling innovation and investment into higher-capacity, automated systems.
Market Restraints
- High Capital Investment:The significant upfront cost of advanced combine harvesters and specialized pickers equipped with full suites of sensors, GPS, and data processing units remains a substantial barrier for small to medium-sized farms.
- Data Interoperability Issues:A lack of standardization between proprietary OEM platforms creates data silos, preventing farmers from seamlessly integrating equipment and software from different manufacturers into a single farm management system.
- Regulatory Compliance Burden:Navigating complex data privacy regulations, such as the EU's GDPR, adds development costs and legal risks for manufacturers of farm management platforms that collect and process sensitive operational data.
Strategic Opportunities
- Specialty Crop Applications:Adapting precision harvesting technologies for high-value specialty crops, such as grapes, nuts, and berries, offers new, high-margin revenue streams beyond traditional row crops like corn and soy.
- Drone and Sensor Fusion:The convergence of aerial data from drones with ground-level data from harvester-mounted sensors provides an opportunity to create hyper-granular, multi-layered yield maps for enhanced field management.
- Expansion in Eastern Europe:The ongoing modernization of large agricultural enterprises in countries like Poland and Ukraine presents an underpenetrated market for advanced precision harvesting systems as they seek to improve competitiveness.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and agronomists with the dual expertise in agronomy and data science creates a bottleneck for the effective implementation and maintenance of precision systems on farms.
- Legacy System Integration:Farmers face significant operational friction and cost when attempting to integrate new, data-intensive precision harvesters with older farm machinery and disparate software that lack modern connectivity standards.
- Data Security Management:Protecting vast amounts of sensitive farm operational data from cybersecurity threats is a major and continuous challenge for both equipment manufacturers and cloud-based agricultural software providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Harvesting Market |
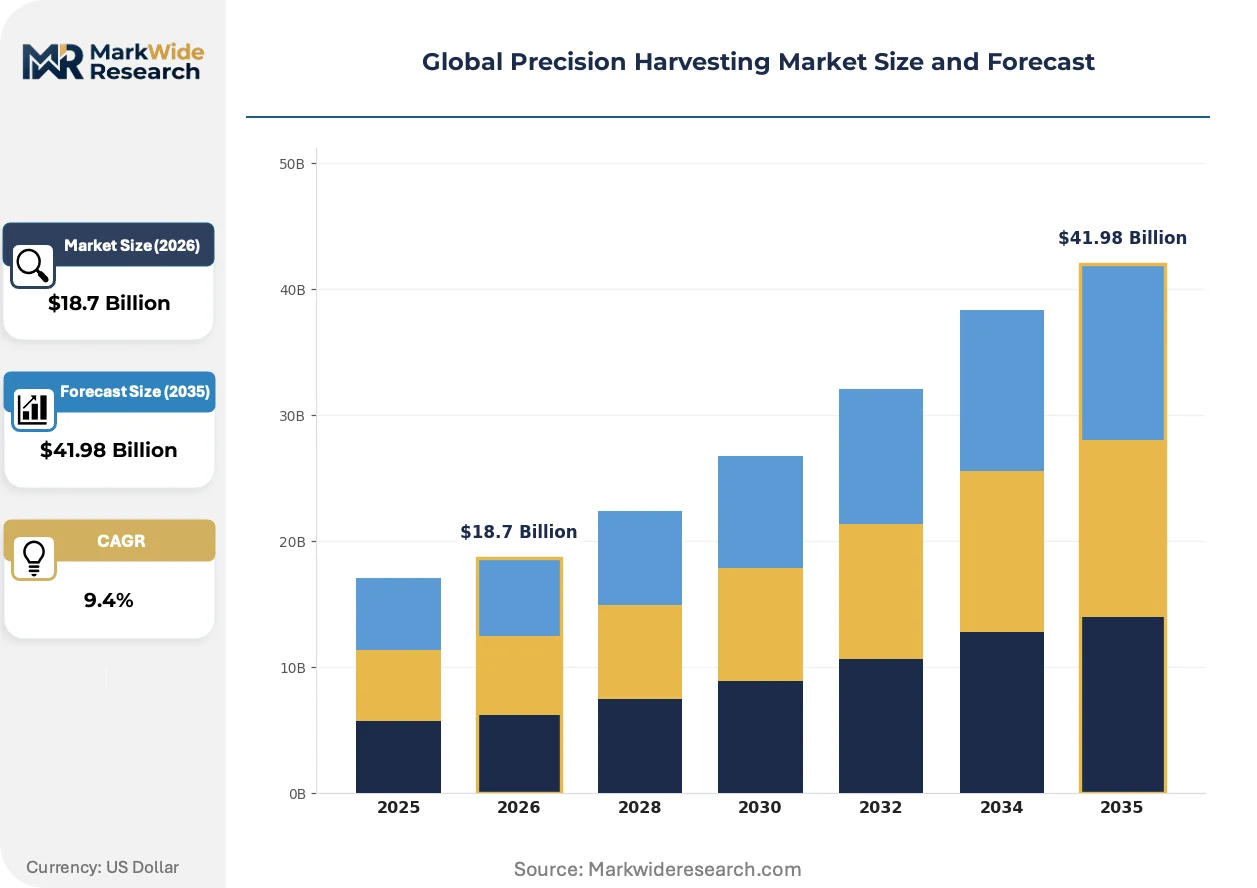
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Guidance, Variable Rate Technology, Yield Monitoring, Remote Sensing, Automation, Data Analytics Equipment Type: Combine Harvesters, Forage Harvesters, Cotton Pickers, Sugarcane Harvesters, Grain Headers, Swathers Application: Cereal Crops, Root Crops, Fiber Crops, Oilseeds, Pulses, Horticultural Crops End User: Large-scale Farmers, Agricultural Cooperatives, Contract Harvesting Services, Research Institutions, Agribusinesses, Equipment Rental Firms |
| Companies Covered | KUBOTA Corporation, Trimble Inc., Deere & Company, Raven Industries Inc., Topcon Corporation, CNH Industrial NV, CLAAS KGaA mbH, Ag Leader Technology, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Harvesting Market Strategic Shifts & Innovations
A fundamental re-engineering of equipment design, driven by material science and regulatory pressures, is reshaping the competitive landscape. The focus is shifting from raw power to intelligent efficiency, where data platforms and component choices define market leadership as much as the machinery itself.
Lightweight composite materials are a key product evolution. These materials reduce the overall weight of harvester components, directly lowering soil compaction and improving fuel economy. Large-scale agricultural operations managing extensive acreage are the primary adopters. This innovation is expanding into the structural frames and larger body panels of combine harvesters, moving beyond cosmetic applications to alter core equipment architecture.
Europe's F-Gas Regulation directly influences equipment design for any manufacturer selling into the region. The rule mandates a phase-down of high global warming potential (GWP) hydrofluorocarbons used in mobile air conditioning systems. This forces harvester OEMs to re-engineer cabin climate control units, affecting component selection and supply chain relationships, particularly for models destined for the EU market.
A clear behavioral shift is the growing farmer-led demand for open-platform data integration. This movement challenges the closed, proprietary ecosystems that some equipment manufacturers have built around their brands. Farmers are increasingly forming data cooperatives and choosing third-party software, forcing equipment makers to provide APIs for interoperability. This trend is most visible in the United States and Australia, where multi-brand equipment fleets are common.
Global Precision Harvesting Market Segmentation
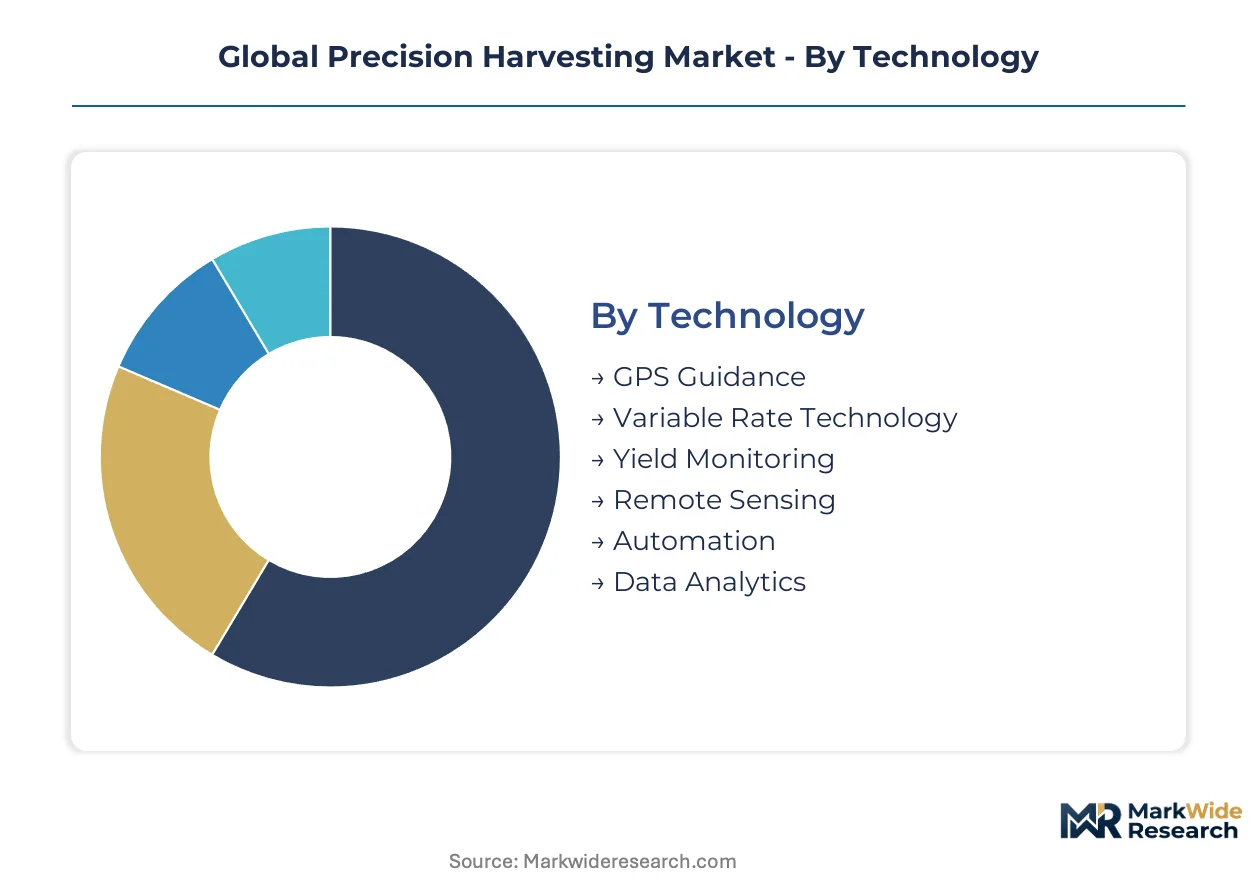
Understanding the distinct segments within the precision harvesting market is crucial for stakeholders to effectively target technological advancements and operational efficiencies. This segmentation clarifies where innovation is most impactful and how varying end-user needs shape product development and market penetration strategies globally.
Technology:
Precision harvesting technologies often require adherence to specific regulatory certifications, particularly regarding data privacy for collected farm information and operational safety for autonomous systems in various jurisdictions.
- Data Analytics:This technology involves processing vast datasets from sensors and GPS systems to generate actionable insights, optimizing crop yield and resource allocation. Demand is concentrating in agricultural powerhouses like Brazil and the United States, driven by the need for predictive modeling in large-scale cereal and oilseed operations.
- GPS Guidance:GPS Guidance systems provide highly accurate positioning data, enabling precise machine control for planting, spraying, and harvesting operations. Its foundational role in automated farm machinery sees strong demand in Australia, where large fields benefit from consistent pass-to-pass accuracy.
- Yield Monitoring:Sensors mounted on harvesters measure real-time crop output, providing granular data on field variability for post-harvest analysis.
- Remote Sensing:Drones and satellites capture aerial imagery, offering insights into crop health and field conditions to inform harvesting strategies.
- Automation:This segment encompasses automated steering, implement control, and robotic harvesting systems designed to reduce labor dependency and increase operational speed.
- Variable Rate Technology:Systems adjust input application and harvesting parameters based on real-time field data, optimizing resource use.
GPS Guidance sits at the top of the volume ranking, with Data Analytics climbing the fastest.
Equipment Type:
The cost tier of precision harvesting equipment varies significantly, influencing adoption rates among different farming operations.
- Combine Harvesters:These large, self-propelled machines perform multiple tasks—reaping, threshing, and winnowing—in a single pass for grains and oilseeds. They represent the largest capital investment for large-scale cereal farms in the United States, driving efficiency across vast acreage.
- Cotton Pickers:Specialized machinery designed to efficiently harvest cotton fiber from the plant, often employing spindle or stripper technology. Manufacturers achieve higher margins with these units due to their specialized function and concentrated demand in regions like the US Cotton Belt and Brazil.
- Forage Harvesters:Machines cut, chop, and unload various forage crops like corn or alfalfa for silage production, common in dairy farming.
- Sugarcane Harvesters:Heavy-duty equipment cuts, chops, and loads sugarcane stalks directly into transport vehicles, primarily used in tropical agricultural zones.
- Grain Headers:Interchangeable attachments for combine harvesters designed to cut and feed specific grain crops into the machine's threshing mechanism.
- Swathers:These machines cut crops and lay them into rows to dry before baling or combining, particularly for hay and some grains.
Supply concentration for combine harvesters remains high, while specialized units like cotton pickers cater to niche but high-value markets.
Application:
The volume of harvested produce significantly dictates the scale and type of precision technology deployed across different crop applications.
- Cereal Crops:This segment includes precision harvesting for grains such as wheat, corn, rice, and barley, which form staple foods globally. Large-scale operations in countries like the United States and Ukraine are primary adopters, seeking optimized yields across extensive fields.
- Oilseeds:Precision harvesting for crops like soybeans, sunflowers, canola, and rapeseed focuses on maximizing oil extraction efficiency and seed quality. Brazil and Argentina exhibit strong demand for these technologies, supporting their major roles in global oilseed production.
- Root Crops:Precision systems optimize the harvesting of potatoes, carrots, and sugar beets, minimizing damage and maximizing marketable yield.
- Fiber Crops:This category includes cotton and flax, where precision harvesting aims to preserve fiber quality and reduce foreign material contamination.
- Pulses:Lentils, chickpeas, and beans benefit from precision harvesting to minimize shattering losses and ensure uniform maturity for processing.
- Horticultural Crops:High-value fruits, vegetables, and nuts increasingly utilize precision harvesting for selective picking and quality preservation.
The market for cereal crop precision harvesting is mature, while horticultural applications show significant growth potential.
End User:
Different customer types exhibit distinct purchasing behaviors and operational requirements for precision harvesting solutions.
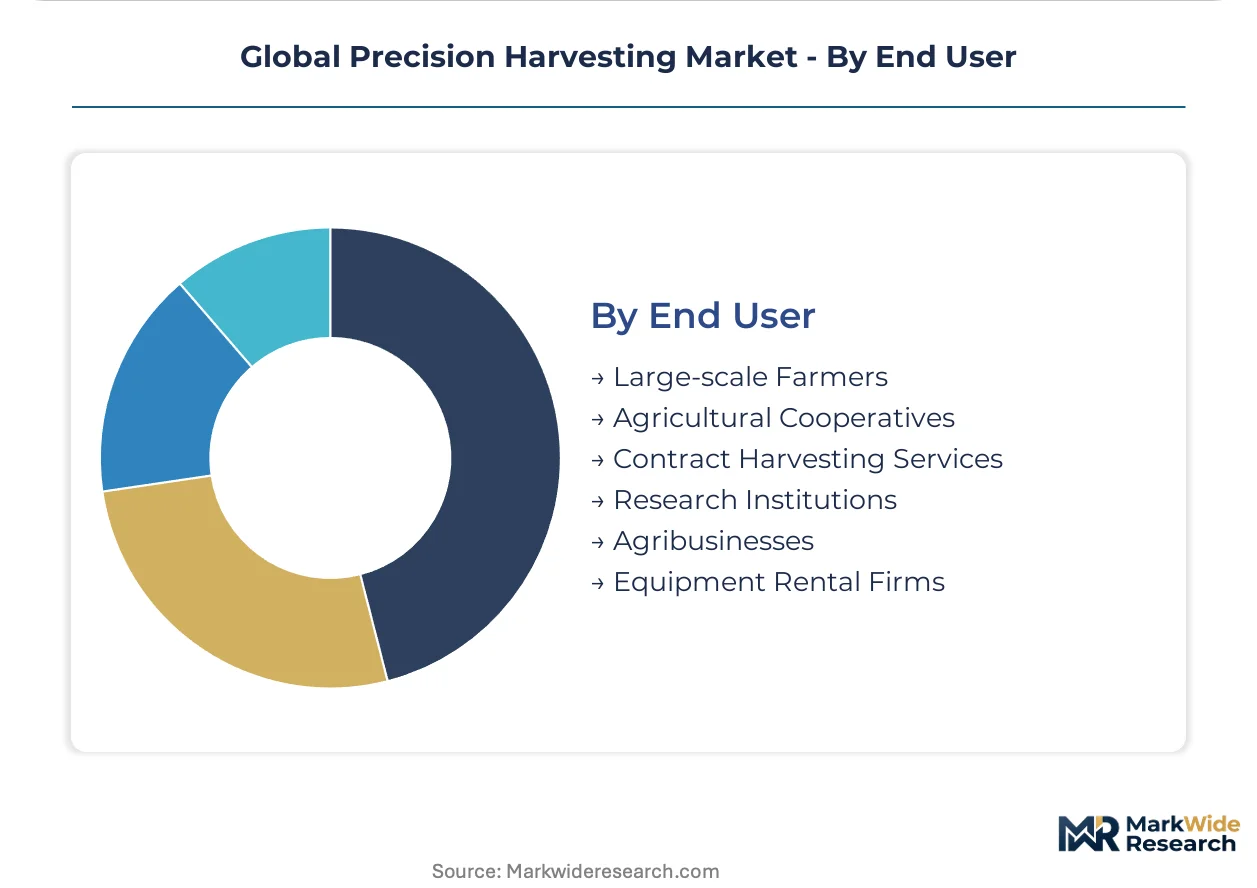
- Large-scale Farmers:These individual or corporate entities operate extensive acreage, often across multiple farms, focusing on high-volume commodity crops. They are the primary adopters of advanced precision harvesting systems in the United States and Australia, prioritizing efficiency and data-driven decisions.
- Agricultural Cooperatives:Member-owned organizations pool resources to collectively purchase and share expensive precision harvesting equipment and services. This model is prevalent in parts of Europe, allowing smaller farms to access advanced technology without individual capital investment.
- Contract Harvesting Services:Businesses own and operate fleets of harvesting equipment, providing services to multiple farms on a contractual basis.
- Research Institutions:Universities and government bodies use precision harvesting tools for field trials and data collection to advance agricultural science.
- Agribusinesses:Large integrated companies spanning farming, processing, and distribution leverage precision harvesting to optimize their supply chains.
- Equipment Rental Firms:These companies offer precision harvesting machinery for short-term use, catering to farmers who prefer operational flexibility over ownership.
Large-scale farmers command the highest equipment sales volume, while contract harvesting services offer strong recurring revenue opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale agricultural operations in the United States drive significant demand for precision harvesting technologies. This demand concentrates in regions with extensive cereal and oilseed production, necessitating advanced automation and data-driven insights for optimal yield.
United States
Demand for advanced combine harvesters and data analytics is strong among large-scale cereal and oilseed farms. Policies from the USDA provide subsidies for adopting precision agriculture technologies that enhance sustainability. The Midwest agricultural belt, particularly states like Iowa and Illinois, serves as a hub for both technology adoption and equipment manufacturing.
Brazil
Oilseed production, especially soybeans, drives substantial demand for precision harvesting systems in Brazil. Government incentives often support agricultural modernization and efficiency improvements across vast farmlands. The state of Mato Grosso, a major agricultural frontier, heavily invests in high-capacity, automated harvesting equipment.
Australia
Australian farmers require precision harvesting for managing vast, variable-terrain farms and optimizing cereal crop yields. The Australian government offers various grants and programs to encourage the adoption of innovative farm technologies. Western Australia's grain belt exemplifies a region where GPS guidance systems and yield monitoring are critical for operational success.
Poland
The modernization of large agricultural enterprises in Poland is creating an underpenetrated market for advanced precision harvesting systems. The European Union's Common Agricultural Policy (CAP) provides funding that supports the integration of sustainable farming practices. The Wielkopolska region, known for its extensive farming, experiences growing investment in automated harvesting solutions.
Germany
German agriculture seeks precision harvesting solutions to enhance efficiency and comply with strict environmental standards. The EU's F-Gas Regulation influences component design for climate control systems in harvesters sold within the region. Bavaria, a technologically advanced agricultural state, sees consistent demand for sophisticated farm machinery and data platforms.
Global Precision Harvesting Market Key Industry Players
Global majors compete with regional champions across technology integration and market reach. The precision harvesting market exhibits a tiered structure, with full-line equipment manufacturers offering comprehensive solutions alongside specialized technology providers. Strategic partnerships and technology licensing represent dominant competitive moves, enabling broader portfolio diversification and faster innovation cycles.
Among established full-line equipment manufacturers, Deere & Company and CNH Industrial NV exemplify firms leveraging extensive dealer networks and multi-brand strategies to maintain market presence. Trimble Inc. occupies a position as a leading technology provider, specializing in GPS guidance and data analytics solutions that integrate with various equipment platforms. These companies anchor the market by providing integrated systems that cater to diverse agricultural scales and regional requirements.
| Leading Market Players |
|---|
| KUBOTA Corporation |
| Trimble Inc. |
| Deere & Company |
| Raven Industries Inc. |
| Topcon Corporation |
| CNH Industrial NV |
| CLAAS KGaA mbH |
| Ag Leader Technology |
| AGCO Corporation |
| Others |
Cost & Logistics Intelligence
Composite material costs influence the final price of lightweight harvester components, impacting adoption rates across different farming scales. This cost pressure feeds into supply choices, particularly for specialized units.
Pricing Analysis
Input costs, particularly for advanced sensors and microprocessors, impact the final pricing of precision harvesting systems. The market primarily uses a value-based pricing model, where equipment and software bundles offer different tiers of functionality. Price differentiation stems from the level of automation and the integration of data analytics capabilities, alongside brand premium. Pricing softness reflects intense competition among equipment manufacturers to capture market share. Large-scale farmers exhibit lower price sensitivity due to the efficiency gains, while agricultural cooperatives are more cost-conscious.
Supply Chain Analysis
Domestic content mandates, such as those in the United States for government-subsidized projects, reshape sourcing strategies for components like steel and composite materials. Geographic supply concentration for advanced sensors and microprocessors centers on East Asian countries. The supply chain relies on specialized electronic components and high-strength alloys. A structural risk involves single-source vulnerability for niche, high-performance parts. Distribution runs through established dealer networks and direct sales channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision harvesting market presents a geographic-arbitrage play, as lower labor costs in Eastern Europe enable more competitive manufacturing of certain components compared to Western Europe.
For Market Incumbents:Deepen proprietary data ecosystems by integrating third-party sensor data via open APIs, countering the threat of data interoperability issues. Expand advanced manufacturing capabilities in regions like the United States and Germany to control quality and reduce logistics costs. This strategy leverages existing dealer networks and R&D investments, reinforcing market leadership against specialized technology providers.
For New Entrants and Emerging Players:Online platform sales for subscription-based data analytics services offer a direct channel to target tech-savvy farmers. Focus on specialty crop applications, such as high-value nuts and berries, represents a penetrable segment with significant growth potential. A go-to-market angle emphasizing rapid deployment and customizable software modules can attract early adopters seeking flexible solutions.
For Investors and Strategic Acquirers:Roll-up economics work for technology providers because market fragmentation exists in data analytics and sensor integration. Long-term viability rests on the continued demand for data-driven agriculture over the next decade. Acquisition targets should include vertically integrated mid-cap specialists in AI-powered analytics or drone-based remote sensing. The signal to watch is the acceleration of open-platform data exchange standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand AI-Powered Analytics Portfolios | Enhances predictive capabilities for yield optimization, driving higher farmer ROI in cereal and oilseed operations. |
| Invest in Lightweight Composite Material R&D | Reduces equipment weight, lowering soil compaction and improving fuel efficiency for large-scale agricultural operations. |
| Develop Open Data Integration Platforms | Addresses farmer demand for interoperability, fostering broader adoption across multi-brand equipment fleets. |
| Target High-Value Specialty Crop Applications | Unlocks new, high-margin revenue streams beyond traditional row crops like corn and soy. |
| Strengthen Eastern European Market Presence | Capitalizes on the modernization of large agricultural enterprises in countries like Poland and Ukraine. |
Research Approach
Direct dialogue with equipment manufacturers, technology developers, and large-scale farmers grounded the qualitative understanding of market dynamics. This primary research was validated against secondary sources including agricultural association reports, government publications from the USDA and EU, and corporate financial filings. Stakeholders interviewed included farm managers, agronomists, R&D directors, and procurement specialists. Both bottom-up and top-down triangulation methods ensured data consistency and accuracy.
A bottom-up analytical lens was applied, aggregating data from granular segmentations across technology, equipment type, application, and end-user categories. The model incorporated industry-specific forecast inputs such as crop yield projections and agricultural land use changes. CAGRs were derived by projecting growth rates for each segment based on historical trends and anticipated technological advancements over the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for autonomous harvesting systems would alter the outlook. Forecasts reflect assumptions regarding stable regulatory environments and sustained government incentives for precision agriculture. Specific risk factors, including global economic downturns or unforeseen climate events, could revise these projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Intelligent Milking Robot Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
OWD Moisture Meter Market