
 Grain Mill Grinder Market | 2026-2036
Grain Mill Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Mill Grinder Market Foresight
Multi-source equipment procurement is decoupling from the single-vendor legacy that dominated milling operations for decades. Bühler Group leverages its integrated technology platforms to sustain engineering leadership across large-scale installations. Satake Corporation anchors its position through precision optical sorting adjacent to grinding systems. Alapala Machine Industry & Trade Inc. competes on turnkey project delivery across emerging markets.
A grain mill grinder is a mechanical device that reduces cereal kernels into flour, meal, or coarse grits through abrasive shearing, impact, or compression forces, typically operating at throughput rates from kilograms per hour in stone mills to multiple tons per hour in industrial hammer mills. Its primary commercial purpose is to transform raw harvested grains into standardized intermediate products for food manufacturing, animal nutrition, and specialty ingredient production. Electric grinder systems dominate the product type landscape due to consistent particle size distribution and automation compatibility, while stone mill configurations retain premium positioning in artisanal and specialty grain applications. Industrial scale capacity equipment captures the deepest margin pools as feed manufacturers and integrated food processors prioritize throughput efficiency and energy recovery.
The FDA enforces preventive controls for human food under FSMA, requiring grain mill grinder operators to validate sanitation protocols and allergen management systems. OSHA sets permissible exposure limits for grain dust, compelling facility upgrades to enclosed grinding circuits and pneumatic conveying. USDA grading standards for wheat and corn indirectly shape grinder calibration requirements across commercial installations. Stakeholders must monitor how evolving food safety audits and energy efficiency mandates reshape capital allocation between refurbishment and greenfield capacity.
Market Dynamics
Fresh flour differentiation is compressing procurement cycles as commercial bakeries bypass centralized milling networks to install on-site grinding capacity, forcing equipment vendors to reconfigure service architectures around distributed footprints.
Growth Catalysts
- FSMA Preventive Controls:The FDA's sanitation validation requirements are compelling facility upgrades across US food manufacturing, expanding replacement demand for enclosed grinding systems with integrated allergen management.
- Optical Sorting Convergence:Precision color and defect detection systems adjacent to grinding lines are reducing downstream waste, attracting capital from integrated processors seeking single-pass efficiency.
- China Capacity Modernization:Wudeli Flour Mill Group and regional processors are retiring mechanical stone mills for automated roller systems, concentrating equipment procurement in Shandong and Henan provinces.
Market Restraints
- Steel Input Volatility:Grinding chamber alloys and hardened roller faces expose manufacturers to nickel and chromium price swings, compressing margin predictability on fixed-price turnkey contracts.
- Swiss-German Engineering Concentration:Precision spindle and bearing supply chains cluster around Stuttgart and Zurich industrial corridors, creating single-source vulnerability for high-throughput installations.
- Energy Recovery Limitations:Heat recapture from friction grinding remains thermodynamically inefficient below 50kW continuous load, capping sustainability claims for artisanal-scale equipment.
Strategic Opportunities
- India FSSAI Modernization:The Food Safety and Standards Authority of India's escalating inspection protocols for atta and maida processors are accelerating replacement demand for stainless-steel contact surfaces and CIP-compatible designs.
- Pulse and Alternative Grain Milling:Lentil, quinoa, and sorghum processing lines require modified shear profiles and adjustable gap settings, opening specification gaps that incumbent wheat-centric vendors have left unaddressed.
- Direct-to-Bakery Leasing:Equipment-as-service models bypassing traditional distributor networks are capturing independent bakeries in France and Italy seeking operational expenditure treatment for stone mill installations.
Industry Challenges
- Millwright Skill Attrition:Roller alignment and corrugation maintenance expertise is aging out of the workforce faster than vocational programs in Germany and the US can replenish certified technicians.
- Legacy Pneumatic Integration:Retrofitting enclosed grinding circuits into facilities with open-aspiration dust collection requires complete conveying re-engineering, extending project timelines and commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Mill Grinder Market |
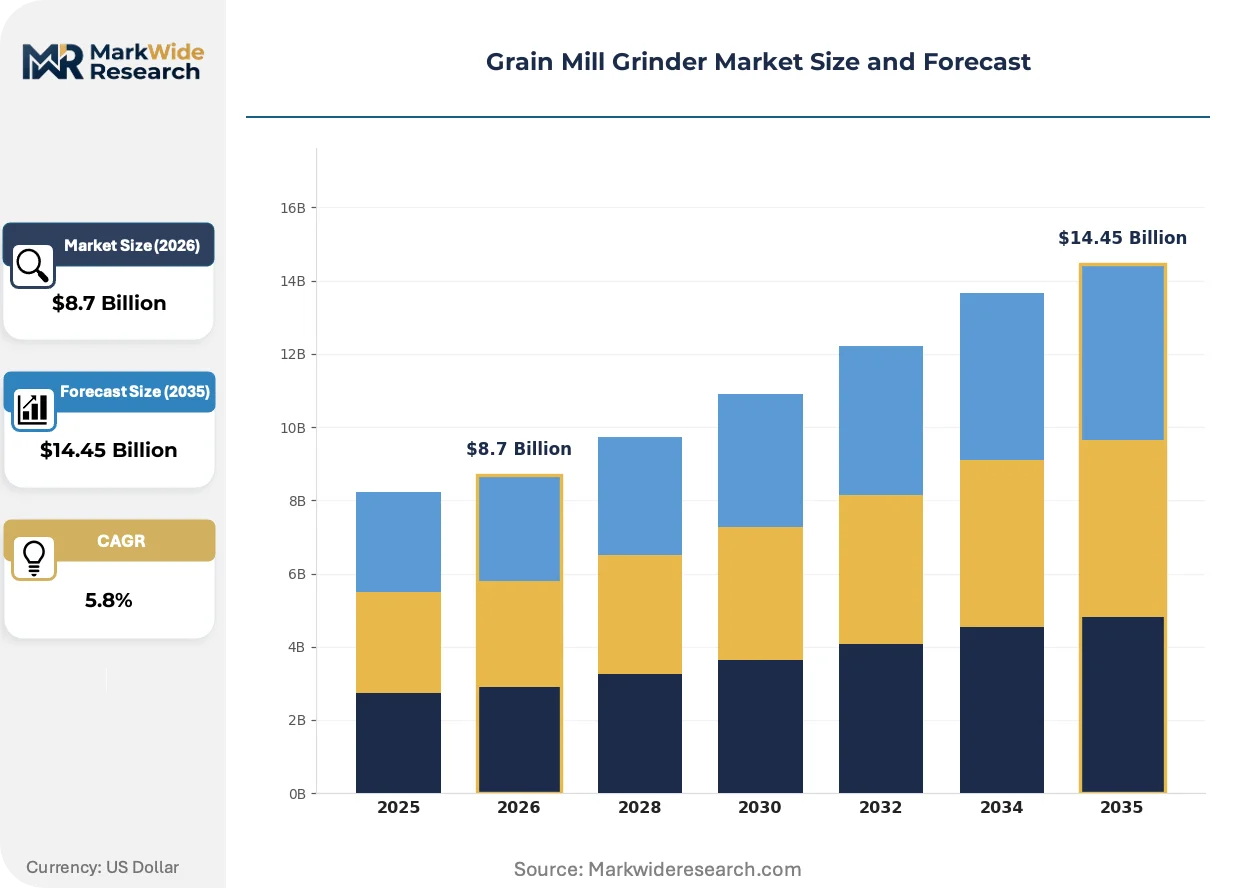
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stone Mill, Electric Grinder, Hand Mill, Hammer Mill End User: Home Users, Commercial Bakeries, Feed Manufacturers, Culinary Schools Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale Application: Cereal Processing, Flour Grinding, Animal Feed Production, Specialty Grains |
| Companies Covered | Bühler Group, Satake Corporation, Cargill, Incorporated, Alapala Machine Industry & Trade Inc., Ocrim S.p.A., Archer Daniels Midland Company, General Mills Inc., Ardent Mills, LLC, Wudeli Flour Mill Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Mill Grinder Market Shifts & Advancements
Automation architectures are fragmenting equipment control hierarchies, embedding sensor arrays directly at grinding contact points rather than centralizing data through legacy SCADA layers. This shift is compressing response latency and enabling predictive maintenance contracts.
Stone mill configurations paired with variable frequency drives and real-time particle size analyzers are decentralizing fresh flour production. Artisanal bakeries in Copenhagen and Melbourne are adopting these hybrid systems at 15-20% annual clip. The technology is decentralizing supply chain power from commodity flour distributors toward neighborhood-scale milling operations.
REACH substance restrictions on hexavalent chromium coatings are forcing grinding chamber manufacturers toward thermal spray ceramic alternatives. EU-based equipment vendors face 18-24 month requalification timelines for food-contact surface approvals. Industrial-scale installations in the Netherlands and Denmark are absorbing premium pricing for compliant systems to preempt enforcement windows.
After-sales service unbundling is disrupting traditional bundled maintenance contracts. Large feed manufacturers in Iowa and São Paulo are procuring grinding components and field service from separate vendors, compressing OEM service revenue pools. This pattern is most visible among integrated protein processors with in-house mechanical teams capable of bearing replacement and roll recorrugation.
Grain Mill Grinder Market Segmentation
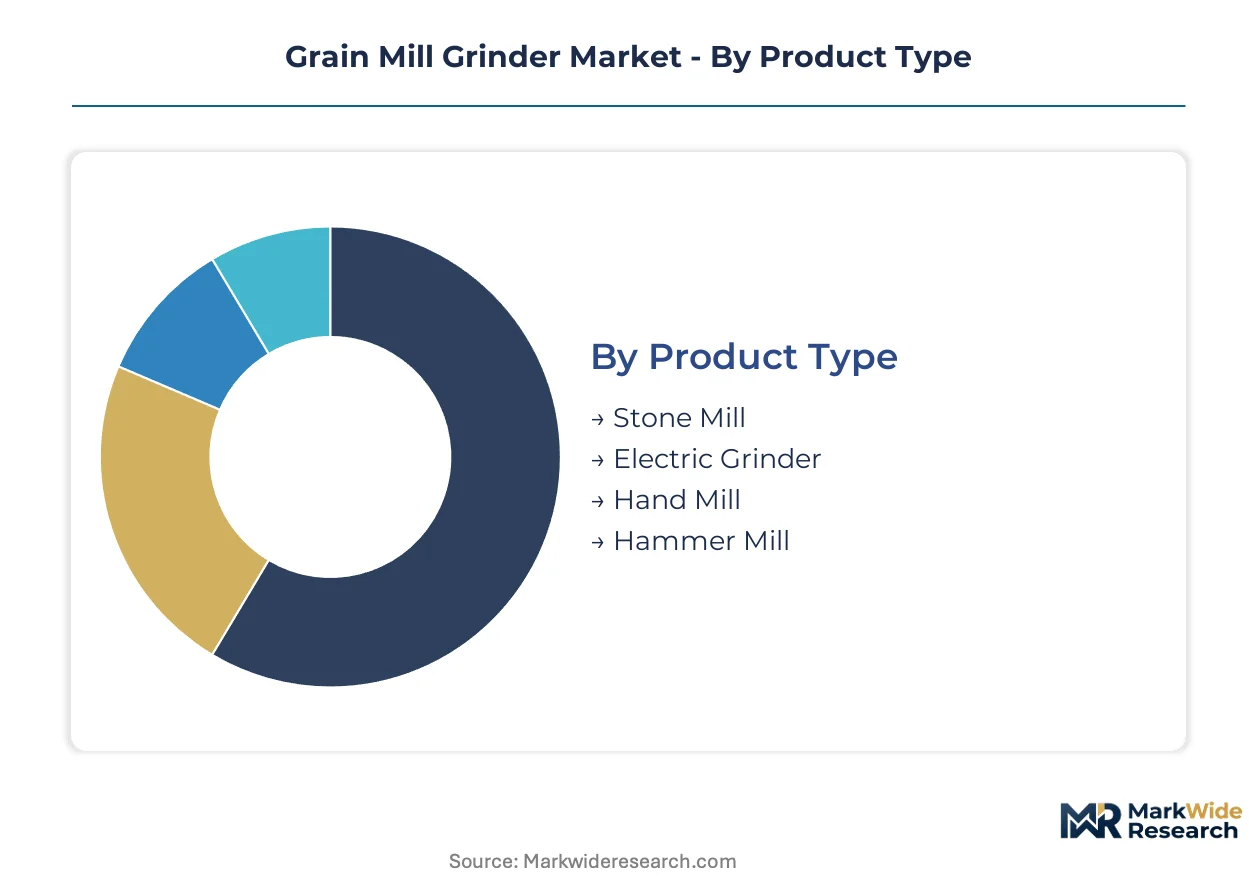
Equipment specification varies sharply across grinding applications, with FDA FSMA preventive controls and EU REACH surface coating rules creating divergent compliance burdens. Segmentation reveals where capital concentrates and which configurations command premium pricing.
Product Type:
Certification requirements split sharply: stone mills face minimal regulatory burden for artisanal use, while electric grinders must validate electromagnetic compatibility under FCC Part 15 and CE marking. Hammer mills trigger OSHA grain dust exposure limits, compelling enclosed aspiration designs.
- Electric Grinder:Motor-driven systems with variable frequency drives achieve consistent particle size distribution through automated gap control. Commercial bakeries in Copenhagen and Melbourne are installing these for fresh flour differentiation, though energy recovery remains thermodynamically inefficient below 50kW continuous load.
- Stone Mill:Abrasive shearing between dressed burr stones preserves enzymatic activity and lipid integrity in whole-grain flour. Artisanal bakeries in France and Italy lease these through equipment-as-service models, bypassing traditional distributor networks for operational expenditure treatment.
- Hammer Mill:High-velocity impact grinding suits animal feed production requiring coarse particle breakdown; hardened alloy faces expose manufacturers to nickel and chromium price volatility.
- Hand Mill:Manual compression devices serve emergency preparedness and off-grid applications; minimal regulatory exposure limits margin compression from compliance costs.
Leading the category by volume: Electric Grinder. Growing fastest: Stone Mill.
End User:
Procurement authority and technical sophistication determine specification complexity, with integrated processors demanding predictive maintenance integration while independent operators prioritize capital efficiency.
- Commercial Bakeries:Fresh flour differentiation compresses procurement cycles as operators bypass centralized milling networks. On-site grinding capacity in Copenhagen and Melbourne is expanding at 15-20% annual clip, forcing equipment vendors to reconfigure service architectures around distributed footprints.
- Feed Manufacturers:Large integrated protein processors in Iowa and São Paulo are unbundling after-sales service, procuring grinding components and field service from separate vendors to compress OEM service revenue pools.
- Home Users:Specialty grain enthusiasts and preparedness consumers drive demand for compact stone and hand mill configurations; price sensitivity limits attachment of premium automation features.
- Culinary Schools:Training institutions require multi-configuration exposure for curriculum breadth, creating fragmented order quantities that strain manufacturer minimum order requirements.
Highest specification intensity: Commercial Bakeries. Steepest expansion trajectory: Feed Manufacturers.
Capacity:
Scale determines energy recovery feasibility and automation depth, with thermodynamic efficiency thresholds creating natural segmentation in sustainability positioning.
- Industrial Scale:Continuous throughput systems above 10 tons per hour capture the deepest margin pools as integrated processors prioritize efficiency and energy recovery. Wudeli Flour Mill Group and regional Chinese processors are modernizing to automated roller systems in Shandong and Henan provinces.
- Large Scale:Mid-industrial installations serve regional flour mills and specialty ingredient processors; Swiss-German engineering concentration around Stuttgart and Zurich creates single-source vulnerability for precision spindle supply.
- Medium Scale:Flexible batch configurations suit contract millers and alternative grain processors; adjustable gap settings accommodate lentil, quinoa, and sorghum shear profiles that wheat-centric vendors have left unaddressed.
- Small Scale:Artisanal and neighborhood-scale operations in India face FSSAI escalating inspection protocols for atta and maida processors, accelerating replacement demand for stainless-steel contact surfaces.
Deepest margin capture: Industrial Scale. Specification gap opportunity: Medium Scale.
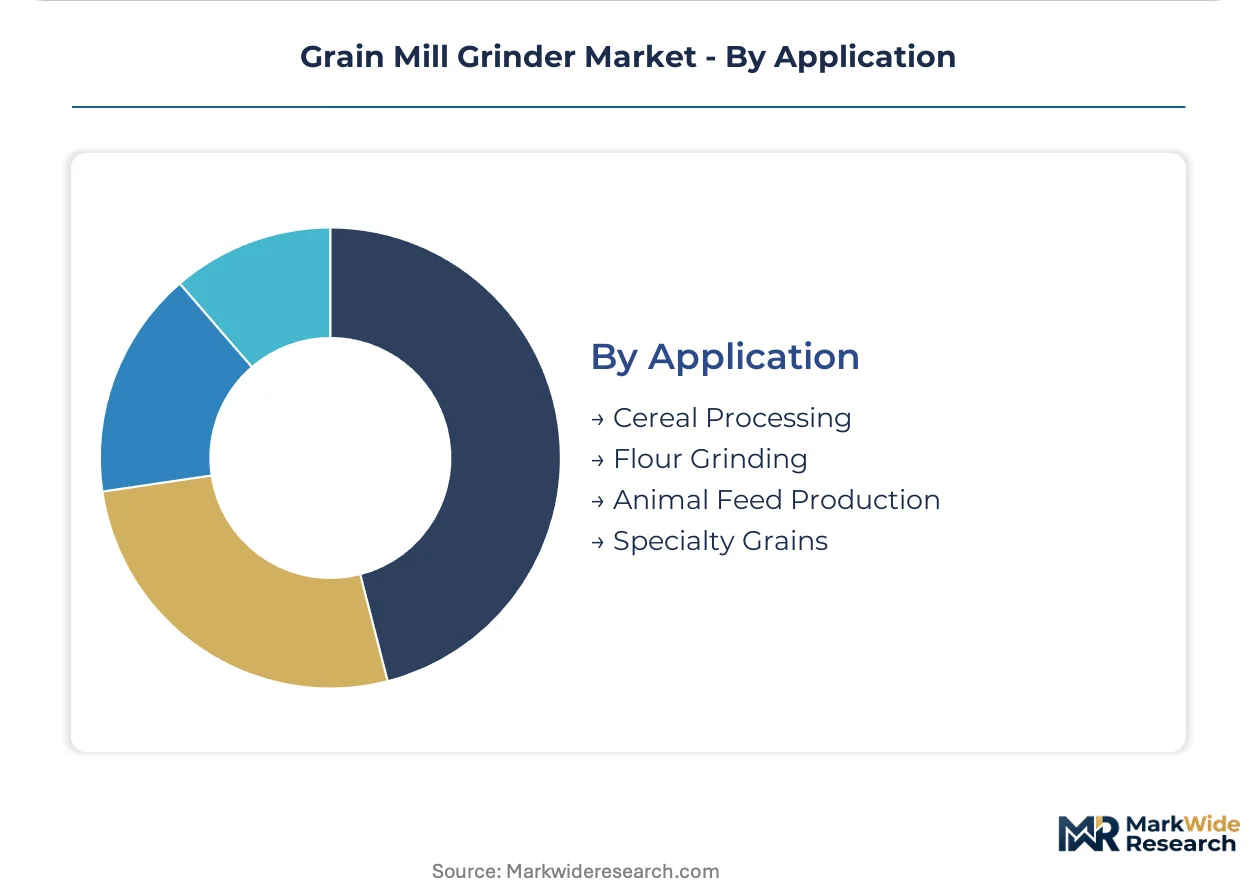
Application:
Raw material characteristics and finished product standards shape grinder calibration requirements, with alternative grains demanding modified engineering that incumbent vendors have underdeveloped.
- Flour Grinding:Standardized intermediate production for food manufacturing requires precise particle size distribution validation; FDA FSMA preventive controls mandate sanitation protocol documentation and allergen management systems.
- Animal Feed Production:Coarse grinding with lower fineness specifications tolerates higher throughput wear rates; Iowa and São Paulo integrated processors drive unbundled procurement patterns.
- Cereal Processing:Pre-grain conditioning and tempering integration demands process control sophistication; USDA grading standards for wheat and corn indirectly shape calibration requirements.
- Specialty Grains:Pulse and alternative grain milling requires modified shear profiles and adjustable gap settings; this specification gap opens competitive opportunity as wheat-centric vendors leave demand unaddressed.
Regulatory intensity peak: Flour Grinding. Fastest specification evolution: Specialty Grains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat cultivation belts in Shandong and Henan provinces anchor Chinese equipment procurement, while corn-soy rotations across Iowa and São Paulo drive feed-milling capacity decisions. Regional regulatory divergence creates distinct compliance architectures for grinder surface coatings, dust exposure limits, and preventive control documentation.
China
Wudeli Flour Mill Group and regional processors are retiring mechanical stone mills for automated roller systems, concentrating procurement in Shandong and Henan provinces. SAMR enforces GB standards for food-contact machinery, accelerating stainless-steel adoption in new installations. Dual carbon goals from MEE are pressuring energy recovery retrofits at facilities above 50kW continuous load.
United States
Commercial bakeries in Iowa and Nebraska are installing on-site grinding capacity to bypass centralized milling networks, compressing procurement cycles for enclosed aspiration designs. FDA FSMA preventive controls mandate sanitation protocol validation and allergen management systems. OSHA grain dust exposure limits are compelling facility upgrades to pneumatic conveying circuits across the Corn Belt.
India
FSSAI escalating inspection protocols for atta and maida processors are accelerating replacement demand for stainless-steel contact surfaces and CIP-compatible designs. Small-scale artisanal operations in Maharashtra and Gujarat face compliance deadlines that favor equipment modernization over grandfathered mechanical installations. BIS certification requirements for electric grinder systems are reshaping vendor qualification criteria.
Germany
Precision spindle and bearing supply chains cluster around Stuttgart and Zurich industrial corridors, creating single-source vulnerability for high-throughput installations. REACH substance restrictions on hexavalent chromium coatings are forcing grinding chamber manufacturers toward thermal spray ceramic alternatives. KBA-adjacent engineering standards indirectly shape calibration requirements for export-bound equipment.
Brazil
Integrated protein processors in São Paulo and Mato Grosso are unbundling after-sales service, procuring grinding components and field service from separate vendors. ANVISA food safety audits are tightening preventive control documentation for facilities supplying export markets. Corn-soy processing lines in the Center-West region are prioritizing hammer mill configurations with hardened alloy faces despite nickel price volatility.
Grain Mill Grinder Market Competitive Landscape
Global majors compete with regional champions across engineering depth and service proximity, producing a tiered structure where integrated technology platforms face off against turnkey specialists. The vendor base separates into precision-engineering houses with captive component supply, diversified food processors with captive milling divisions, and regional fabricators competing on project delivery speed. Two dominant competitive moves are reshaping positioning: M&A activity targeting optical sorting convergence capabilities, and geographic expansion through equipment-as-service models that bypass traditional distributor networks.
Within the precision-engineering tier, Bühler Group and Satake Corporation exemplify divergent strategic anchors—Swiss-based integrated technology platforms against Japanese specialists in optical sorting adjacencies. Alapala Machine Industry & Trade Inc. occupies a position among turnkey project delivery specialists competing across emerging markets. These three represent distinct archetypes: the engineering-led systems integrator, the precision-component specialist, and the regional project execution house.
| Leading Market Players |
|---|
| Bühler Group |
| Satake Corporation |
| Cargill, Incorporated |
| Alapala Machine Industry & Trade Inc. |
| Ocrim S.p.A. |
| Archer Daniels Midland Company |
| General Mills Inc. |
| Ardent Mills, LLC |
| Wudeli Flour Mill Group |
| Others |
Supply & Pricing Matrix
EU REACH substance restrictions on hexavalent chromium coatings gate qualified supply for food-contact grinding chambers, reserving premium-tier pricing access for vendors with thermal spray ceramic requalification timelines already complete. Buyers lacking compliant surface specifications face procurement exclusion from export-bound installations in the Netherlands and Denmark.
Pricing Analysis
Warranty and field service bundling separates premium system integrators from component vendors competing on unbundled procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth, with FDA FSMA-validated sanitation protocols commanding substantial premia. Cost compression in standard-tier electric grinders is intensifying because steel input volatility on nickel and chromium alloys compresses margin predictability. Feed manufacturers in Iowa and São Paulo exhibit highest price sensitivity through aggressive service unbundling, while artisanal bakeries in France and Italy show lowest sensitivity when leasing stone mills through equipment-as-service models.
Supply Chain Analysis
Ocean freight cost differentials between Stuttgart-Zurich precision spindle corridors and emerging fabrication hubs in Turkey and India reshape total landed cost calculations for high-throughput installations. Grinding chamber alloys draw from German and Swiss bearing supply chains, with hardened roller faces sourcing from Japanese specialty steel producers. Single-source vulnerability clusters around Stuttgart and Zurich industrial corridors for precision spindle components. Distribution runs through OEM-direct channels for large integrated processors, while regional fabricators serve small-scale artisanal operators through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive component supply and validated regulatory compliance, as REACH and FSMA requalification costs force weaker players without ceramic coating capabilities toward exit.
For Market Incumbents: Anchor engineering leadership through backward integration into precision spindle production, eliminating single-source exposure from Stuttgart-Zurich supply corridors. Deepen optical sorting adjacencies via targeted capability acquisition, preempting Satake Corporation's convergence strategy. Defend against unbundled procurement pressure from Iowa and São Paulo feed manufacturers by embedding predictive maintenance sensors directly at grinding contact points, creating switching costs that separate vendors cannot replicate. For New Entrants and Emerging Players: Launch via equipment-as-service distribution models targeting independent bakeries in France and Italy, bypassing traditional distributor networks that Bühler Group dominates. Exploit specification gaps in pulse and alternative grain milling—lentil, quinoa, and sorghum shear profiles remain underdeveloped by wheat-centric incumbents. Target medium-scale capacity configurations for contract millers seeking adjustable gap settings, a segment where incumbent project delivery timelines create white-space opportunity. For Investors and Strategic Acquirers: FSSAI modernization deadlines in India are the leading indicator that stainless-steel contact surface compliance will concentrate procurement among qualified vendors over the medium-term horizon. Acquire turnkey project specialists with established FSSAI requalification track records and existing CIP-compatible design portfolios. Watch for optical sorting convergence M&A activity as the inflection signal that integrated technology platforms are securing permanent competitive separation from component vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Spindle Production | Eliminates single-source vulnerability from Stuttgart-Zurich supply corridors for high-throughput installations. |
| Thermal Spray Ceramic Coating Requalification | Secures EU REACH compliance for food-contact surfaces, unlocking premium-tier pricing in Netherlands and Denmark. |
| Optical Sorting Capability Acquisition | Converges precision defect detection with grinding lines, replicating Satake Corporation's adjacency strategy. |
| Equipment-as-Service Model Expansion | Bypasses traditional distributor networks to capture operational expenditure treatment preference among artisanal bakeries. |
| Predictive Maintenance Sensor Integration | Embeds response latency compression at grinding contact points, creating switching costs against unbundled procurement. |
Research Methodology
Multi-period observation of grinder procurement cycles, regulatory enforcement windows, and steel input price movements anchored the trend analysis, supplemented by interviews with plant engineers at commercial bakeries, aftermarket service heads at feed manufacturers, procurement teams at integrated protein processors, and maintenance directors at flour milling operations. Secondary validation drew from FDA FSMA enforcement documentation, EU REACH substance restriction updates, SAMR GB standards publications, and customs data on grinding equipment trade flows. Bottom-up capacity installation tracking and top-down end-use demand estimation were triangulated against manufacturer order backlogs.
Input-output matrices modeled grinder deployment across product type, end user sophistication tier, capacity scale, and application requirements throughout the forecast period. CAGRs were derived from segment-level demand elasticity functions calibrated to observed procurement patterns. Industry-specific forecast inputs included FSSAI inspection protocol escalation timelines and dual carbon goal pressure trajectories from China's MEE.
Steel alloy price volatility, REACH enforcement acceleration, and FSSAI compliance deadline shifts are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Powder Feed Center Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Vegetable Sorting Machines Market