
 Global Rice Transplanter Market | 2026-2036
Global Rice Transplanter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rice Transplanter Market Foresight
Market Context
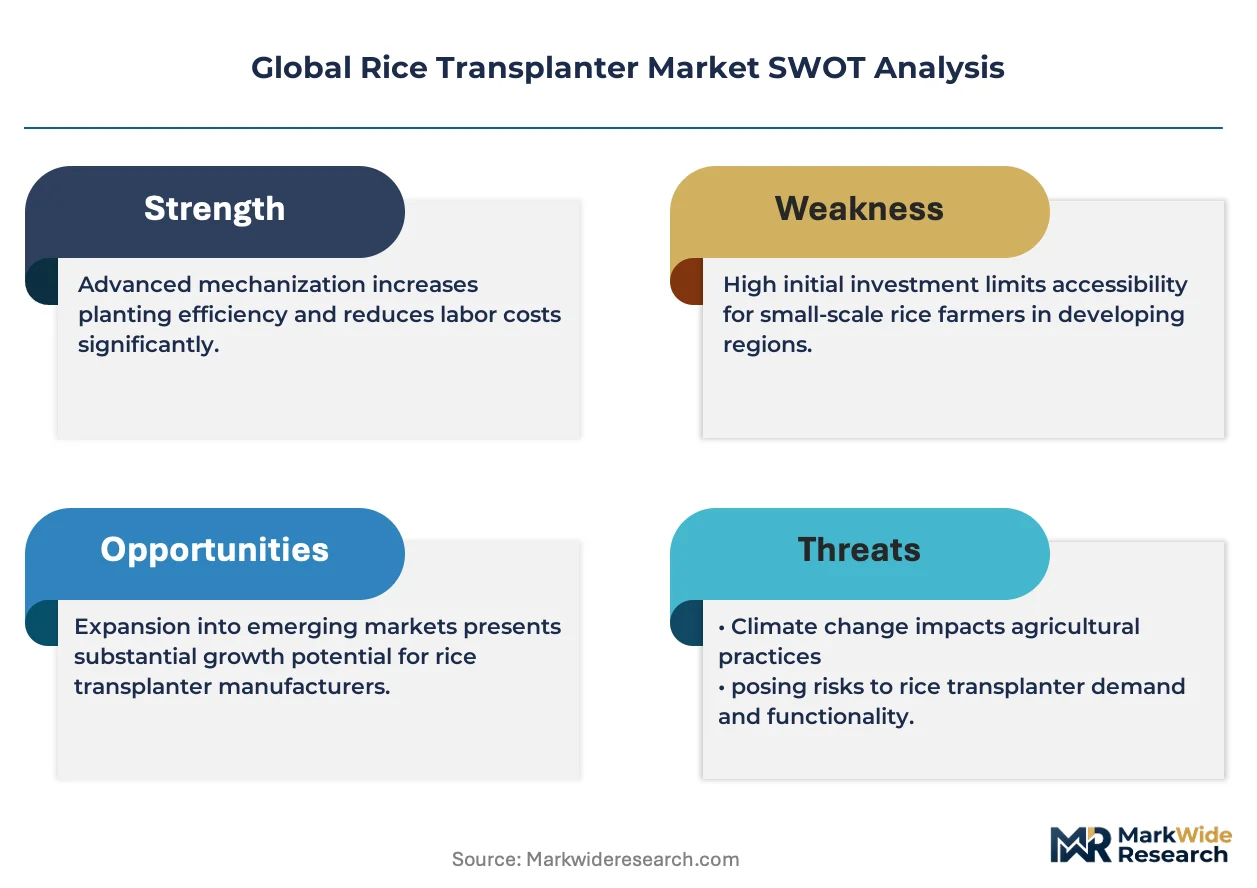
India's PLI scheme for farm machinery is rebalancing the cost-of-entry calculus for foreign manufacturers seeking local assembly partnerships. Kubota Corporation leverages its Thai manufacturing base to dominate Southeast Asian distribution channels for riding-type equipment. Yanmar Agritech Co., Ltd. sustains R&D intensity in compact walking-type platforms tailored to Japanese terraced field conditions. Mahindra & Mahindra Ltd. anchors its position through backward integration into diesel engine production and captive casting facilities.
Technical Definition and Segment Structure
A rice transplanter is a specialized agricultural implement that precisely inserts rice seedlings into puddled soil at controlled depth and spacing, typically operating at 30-80 cm row widths with transplanting speeds of 0.3-1.5 meters per second depending on machine class. The device automates what remains one of the most labor-intensive phases in cereal production, reducing per-hectare planting time from 25-30 person-days to under 2 machine-hours in irrigated flatland conditions. Riding-type platforms generate the dominant share of revenue due to higher unit values and attachment versatility, while fully automatic systems represent the fastest-expanding category as vision-guidance and GPS-RTK row-tracking mature. Hydraulic technology occupies the largest installed base, though electric actuation is displacing legacy systems in premium segments where battery-swapping infrastructure reaches critical density.
Regulatory Framework and Outlook
Japan's METI enforces stringent noise and emission standards under the Agricultural Machinery Safety Regulation, while China's MEE implements dual carbon goals that tighten diesel engine certification timelines for imported equipment. The EU F-Gas Regulation and REACH compliance requirements constrain hydraulic fluid formulations sold in European markets, pushing manufacturers toward biodegradable alternatives. Stakeholders must monitor how India's BIS localization mandates for critical components reshape sourcing economics for multinational assemblers operating within the country's tariff-protected farm equipment sector.
Market Dynamics
Labor scarcity across Southeast Asian rice belts is compressing planting windows and forcing mechanization decisions that previously faced cultural resistance. China's MIIT fuel-efficiency mandates and Japan's METI emission standards are accelerating electric drivetrain development while hydraulic platforms retain installed-base dominance.
Growth Catalysts
- PLI Scheme for Farm Machinery:India's production-linked incentive framework subsidizes local assembly, lowering effective cost-of-entry for foreign manufacturers establishing domestic partnerships. Smallholder cooperatives in Punjab and Haryana are consolidating procurement to access scheme benefits.
- Vision-Guidance Systems:GPS-RTK row-tracking and machine-vision seedling recognition reduce operator skill requirements. Vietnamese Mekong Delta collectives are retrofitting existing fleets with these modules ahead of full-platform replacement cycles.
- Agricultural Cooperatives:Labor shortages in Thailand's Central Plains and Indonesia's Java corridor are driving collective ownership models that spread capital burden across member farms. These entities negotiate volume discounts and shared maintenance pools.
Market Restraints
- Steel and Lithium Input Volatility:Battery-electric platform costs fluctuate with cathode material spot markets. Japanese manufacturers face margin compression when yen-denominated contracts confront dollar-denominated lithium carbonate pricing.
- Precision Component Supply Concentration:Hydraulic valve blocks and high-torque electric motors concentrate in German and Chinese supplier bases. Southeast Asian assemblers face extended lead times when these nodes experience capacity constraints.
- Biodegradable Hydraulic Fluid Mandates:EU F-Gas Regulation and REACH compliance constrain conventional fluid formulations. Equipment exported to European markets requires reformulated seals and pumps, adding SKU complexity without volume justification.
Strategic Opportunities
- Sub-Saharan Mechanization Gap:Nigeria's Niger Delta and Senegal's Senegal River Valley remain underpenetrated by riding-type equipment. Local distributors are piloting lease-to-own structures that match cash-flow profiles of rain-fed rice operations.
- Swappable Battery Infrastructure:Convergence of standardized battery form factors and fast-charging protocols enables field-side swapping stations. Chinese MIIT standardization efforts are creating interoperability expectations that reduce manufacturer lock-in.
- Retrofit Automation Kits:Walking-type platforms in Bangladesh's delta regions face replacement pressure. Aftermarket guidance and depth-control modules extend asset life while capturing upgrade spending that cannot support full-platform acquisition.
Industry Challenges
- Mechatronics Technician Scarcity:Electric actuator maintenance and CAN-bus diagnostics require skills absent from traditional diesel-mechanic labor pools. Vietnamese service networks report 90-day training gaps for complex fault isolation.
- Homologation Timeline Compression:China's GB standards and India's BIS localization mandates require parallel certification tracks. Multinational assemblers face resource allocation conflicts when multiple markets tighten approval windows simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rice Transplanter Market |
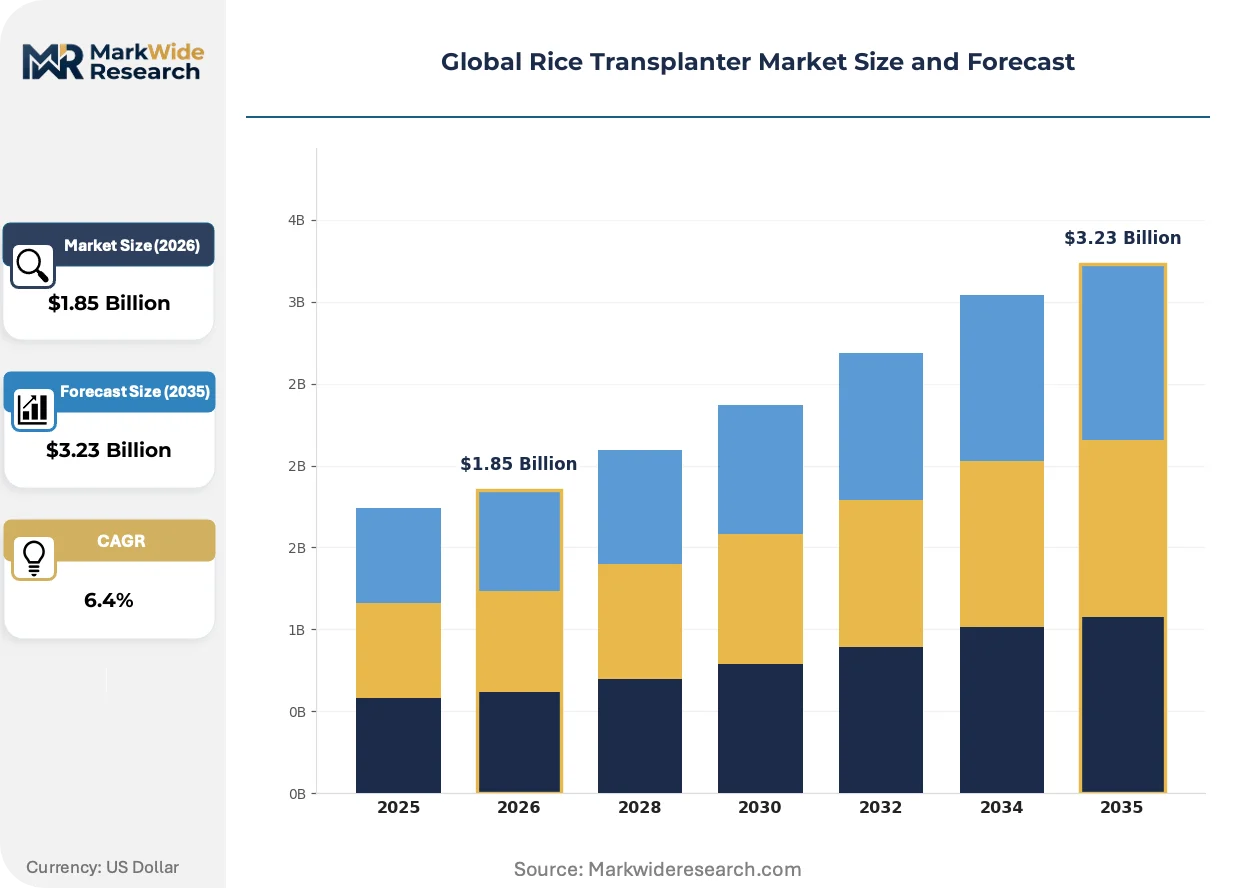
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walking Type, Riding Type, Semi-Automatic, Fully Automatic Technology: Hydraulic, Mechanical, Pneumatic, Electric Application: Irrigated Fields, Rainfed Fields, Upland Areas, Terraced Fields End User: Smallholder Farmers, Agricultural Cooperatives, Contract Farmers, Government Agencies |
| Companies Covered | Yanmar Agritech Co., Ltd., Kubota Corporation, ISEKI & CO., LTD., Mitsubishi Agricultural Machinery Co., Ltd., CNH Industrial, CLAAS KGaA mbH, Mahindra & Mahindra Ltd., AGCO Corporation, John Deere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rice Transplanter Market Shifts & Advancements
Electrification trajectories are diverging by machine class, with battery-swapping infrastructure enabling new ownership models while hydraulic platforms retain dominance in cost-sensitive segments. Regulatory pressure on emissions and noise is accelerating platform turnover in premium markets.
Electric drivetrain architectures with swappable battery packs are overtaking fixed-battery designs in Southeast Asian cooperative fleets. These systems eliminate charging downtime during critical planting windows. Vietnamese distributors report that swap-capable platforms command 15-20 percent lease premiums over equivalent fixed-battery units, compressing payback periods for capital-intensive electrification.
China's MEE dual carbon goals have tightened diesel engine certification timelines, forcing importers to pre-certify powertrains under accelerated GB standards. This regulatory compression affects riding-type platforms above 25 horsepower most severely. Japanese manufacturers are responding with parallel electric platform development to maintain market access without absorbing full recertification costs for legacy combustion architectures.
Collective procurement through agricultural cooperatives is displacing individual smallholder purchases across Vietnam's Mekong Delta. These entities aggregate demand to access government subsidy thresholds and negotiate service contracts that unbundle maintenance from equipment acquisition. The shift is most visible in An Giang and Dong Thap provinces, where cooperative membership has expanded coverage of precision transplanting equipment to farms below five hectares.
Global Rice Transplanter Market Segmentation
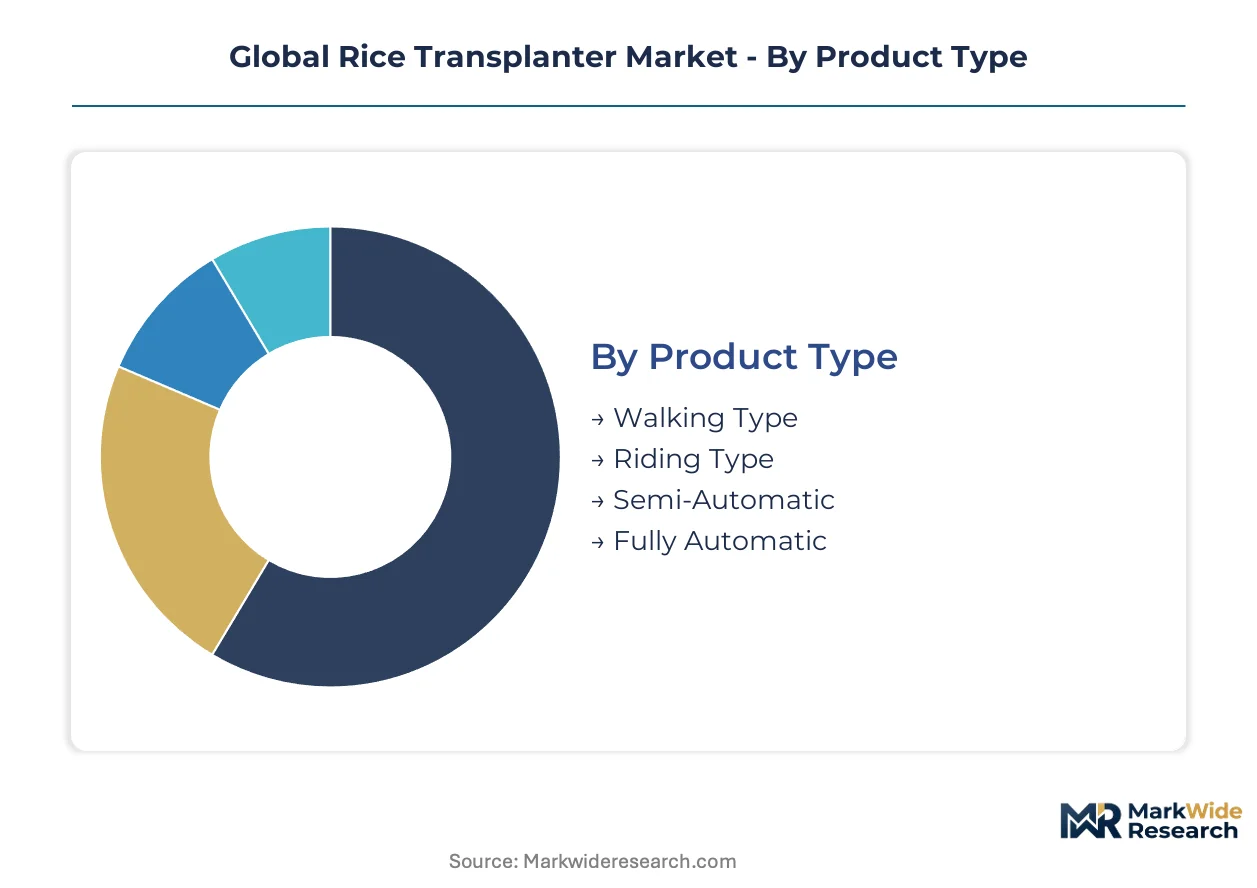
Rice transplanter procurement decisions hinge on field topology, capital access, and labor availability rather than crop economics alone. Equipment segmentation reveals how manufacturers align platform specifications with distinct operational constraints across Asian rice belts.
Product Type:
Capital intensity and field scale determine platform selection, with ownership models shifting from individual smallholders toward collective procurement.
- Riding Type:These platforms accommodate operators in seated positions while delivering transplanting widths of 30-80 cm and operating speeds up to 1.5 meters per second. Demand concentrates in Vietnam's Mekong Delta where agricultural cooperatives aggregate sufficient acreage to justify higher capital outlays. Government subsidy programs in An Giang and Dong Thap provinces accelerate fleet expansion among member collectives.
- Fully Automatic:Vision-guidance systems and GPS-RTK row-tracking eliminate manual steering corrections while machine-vision modules recognize seedling positioning in real time. Vietnamese distributors report retrofit demand from existing fleet operators seeking to defer full-platform replacement. The technology is gaining share fastest among precision-oriented cooperatives facing compressed planting windows.
- Walking Type:Compact platforms suit Japanese terraced field conditions where maneuverability constraints exclude larger equipment. Yanmar Agritech sustains dedicated R&D for this segment.
- Semi-Automatic:Intermediate automation reduces operator fatigue while preserving capital accessibility for individual smallholders in Bangladesh's delta regions.
Volume sits with Riding Type platforms; growth tilts toward Fully Automatic systems.
Technology:
Regulatory pressure on emissions and noise is fragmenting the installed base between proven hydraulic architectures and emerging electric alternatives.
- Hydraulic:Valve-block systems dominate current fleet composition with established service networks and parts availability. Southeast Asian assemblers face extended lead times when German and Chinese hydraulic component suppliers experience capacity constraints.
- Electric:Battery-swappable architectures eliminate charging downtime during critical planting windows. Chinese MIIT standardization efforts are creating interoperability expectations that reduce manufacturer lock-in across cooperative fleets.
- Mechanical:Linkage-driven systems persist in cost-sensitive segments where precision requirements remain modest.
- Pneumatic:Compressed-air actuation offers intermediate precision for specialized terraced applications.
Installed base concentration favors Hydraulic platforms; regulatory compression accelerates Electric substitution.
Application:
Water management infrastructure and topographical constraints dictate equipment specification more than varietal choice.
- Irrigated Fields:Flatland conditions with controlled water delivery enable highest operating speeds and widest transplanting configurations. Thailand's Central Plains represent the core demand geography for premium riding-type platforms.
- Terraced Fields:Stepped paddy configurations in Japan and upland Southeast Asia require compact turning radii and specialized flotation. Equipment here commands structural premiums due to low production volumes.
- Rainfed Fields:Unreliable water access in Sub-Saharan Africa and eastern India limits mechanization penetration to lease-to-own pilot structures.
- Upland Areas:Elevated terrain with slope constraints demands modified chassis geometry and enhanced stability systems.
Revenue concentrates in Irrigated Fields; equipment specialization is climbing fastest for Terraced Fields.
End User:
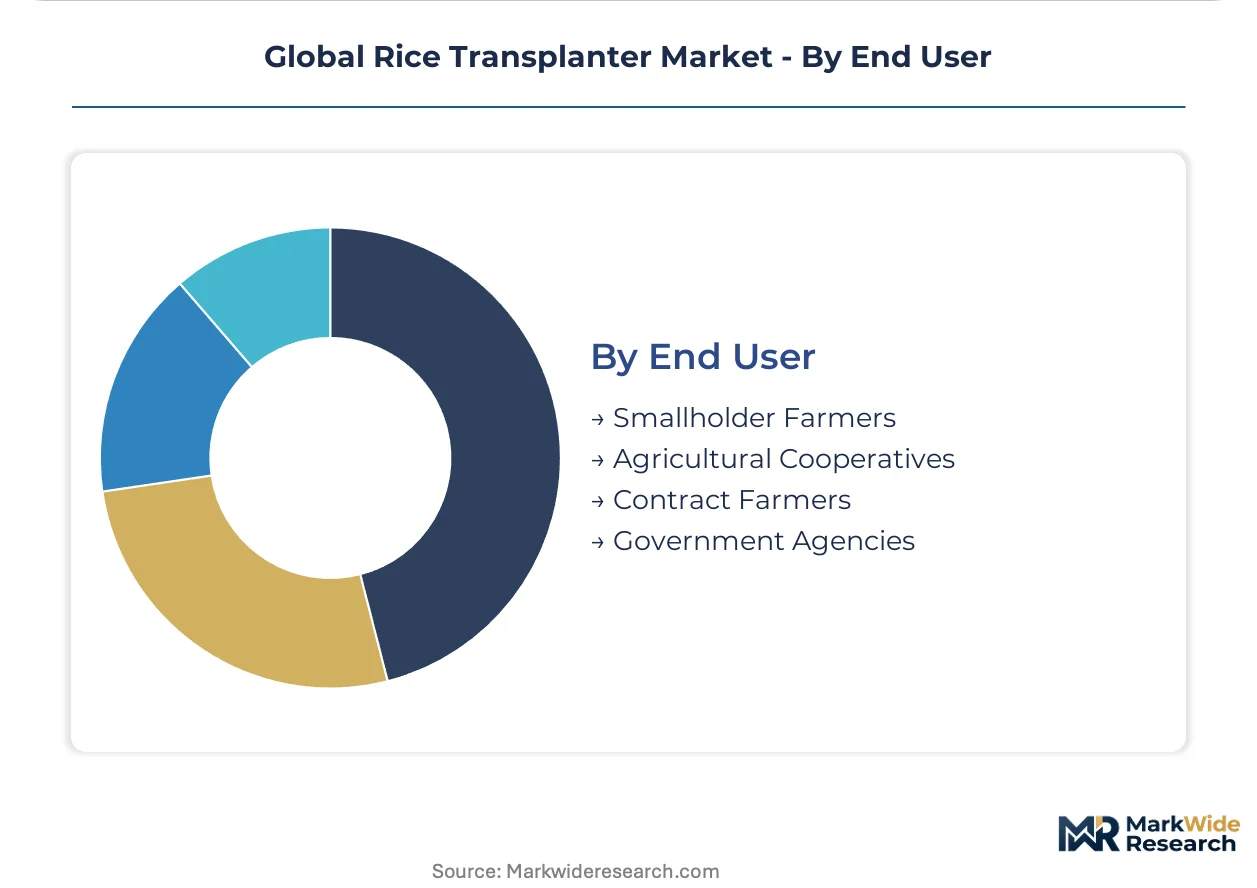
Procurement authority is migrating from individual operators toward collective entities with superior capital access and negotiating leverage.
- Agricultural Cooperatives:Member-owned entities aggregate demand across 50-200 hectare footprints to access government subsidy thresholds and negotiate unbundled service contracts. Vietnam's Mekong Delta has seen cooperative membership expand precision equipment coverage to farms below five hectares.
- Smallholder Farmers:Individual operators below five hectares face displacement from direct equipment ownership as subsidy structures favor collective procurement. Aftermarket retrofit modules capture upgrade spending that cannot support full-platform acquisition.
- Contract Farmers:Lease-based operators prioritize equipment access over ownership, driving rental fleet expansion.
- Government Agencies:Public extension services and demonstration farms anchor technology diffusion in emerging mechanization regions.
Transaction volume flows through Agricultural Cooperatives; Smallholder Farmers are shifting fastest toward service-based access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta special economic zones concentrate cooperative fleet procurement, while India's PLI scheme zones in Punjab and Haryana reconfigure foreign assembly economics. Japanese terraced regions and China's MIIT-compliant manufacturing corridors complete the demand geography.
China
MIIT fuel-efficiency mandates and MEE dual carbon goals compress diesel engine certification timelines for imported riding-type platforms. GB standards now require accelerated pre-certification that elevates electric platform development priorities. Yangtze River Delta manufacturing clusters around Shanghai host domestic and Japanese joint-venture assembly operations targeting Southeast Asian export markets.
Japan
METI enforces stringent noise and emission standards under Agricultural Machinery Safety Regulation that elevate R&D investment thresholds. Terraced field conditions in Chubu and Tohoku regions sustain demand for compact walking-type platforms with specialized maneuverability. Kanto manufacturing bases anchor precision component supply for vision-guidance and GPS-RTK systems.
India
BIS localization mandates for critical components reshape sourcing economics for multinational assemblers operating within tariff-protected farm equipment sectors. Punjab and Haryana agricultural cooperatives consolidate procurement to access PLI scheme subsidies for precision transplanting equipment. Western and northern state clusters drive riding-type platform adoption among smallholder collectives above five hectares.
Vietnam
Government subsidy programs for precision equipment reshape procurement patterns among smallholder collectives in An Giang and Dong Thap provinces. Mekong Delta cooperative membership has expanded coverage of riding-type and fully automatic systems to farms below five hectares. Vietnamese distributors report retrofit demand for vision-guidance modules ahead of full-platform replacement cycles.
Thailand
Central Plains labor shortages compress planting windows and force mechanization decisions through agricultural cooperative ownership models. Collective entities spread capital burden across member farms and negotiate volume discounts with Japanese manufacturers leveraging regional distribution channels. Bangkok-centered service networks report 90-day training gaps for electric actuator maintenance and CAN-bus diagnostics.
Global Rice Transplanter Market Competitive Landscape
Japanese producers anchor the premium tier with precision technology integration; Chinese and Indian fabricators hold cost-optimized segments through localized assembly partnerships. Market structure tilts toward consolidation among riding-type specialists while walking-type niches fragment across regional specialists. Three archetypes dominate: integrated engine manufacturers with captive casting capacity, precision automation specialists with vision-guidance portfolios, and cooperative-focused distributors with unbundled service contracts. Competitive intensity centers on electric drivetrain development speed and BIS localization compliance timelines.
Among Japanese specialists, Yanmar Agritech Co., Ltd. and Kubota Corporation exemplify the precision automation archetype with differentiated platform strategies. Mahindra & Mahindra Ltd. anchors the integrated engine-manufacturer tier through backward integration into diesel production and captive casting facilities. These three entities represent distinct competitive vectors: precision R&D intensity, Southeast Asian distribution dominance, and vertical manufacturing control respectively.
| Leading Market Players |
|---|
| Yanmar Agritech Co., Ltd. |
| Kubota Corporation |
| ISEKI & CO., LTD. |
| Mitsubishi Agricultural Machinery Co., Ltd. |
| CNH Industrial |
| CLAAS KGaA mbH |
| Mahindra & Mahindra Ltd. |
| AGCO Corporation |
| John Deere |
| Others |
Supply & Pricing Matrix
Mechatronics technician scarcity in Vietnam's Mekong Delta widens pricing-tier spreads between premium electric platforms and hydraulic alternatives, as labor-cost differentials for maintenance capability translate into 15-20 percent lease premiums for swap-capable battery systems over fixed-battery equivalents.
Pricing Analysis
Lead-time-driven pricing stratification rewards cooperative buyers securing advance slots with Japanese manufacturers, while spot-market availability commands premiums from operators facing compressed planting windows. Three-tier pricing structure across premium electric, standard hydraulic, and economy mechanical levels separates buyers by after-sales bundling intensity and certification grade. Cost compression in hydraulic tiers is intensifying because German and Chinese valve-block suppliers face capacity constraints. Smallholder farmers in Bangladesh's delta regions exhibit highest price sensitivity; Vietnamese agricultural cooperatives with consolidated procurement show least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cooperative demand in Vietnam and Thailand, while distributor networks serve fragmented smallholder markets. Component manufacturing concentrates in China, Japan, and Germany. Precision valve blocks and high-torque electric motors draw from German and Chinese supplier bases. Single-source vulnerability in hydraulic component nodes exposes Southeast Asian assemblers to extended lead times. Distribution runs through Bangkok-centered service networks with reported training gaps for electric actuator diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained precision component availability props pricing power for manufacturers with captive hydraulic and electric motor capacity, as German and Chinese supplier bottlenecks extend fulfillment timelines across Southeast Asian assembly operations.
For Market Incumbents: Anticipate margin compression from Chinese MIIT standardization efforts by accelerating parallel electric platform development to maintain market access without absorbing full diesel recertification costs. Prioritize backward integration into battery pack assembly and CAN-bus diagnostic training infrastructure to defend against emerging cooperative fleet operators demanding unbundled service contracts. For New Entrants and Emerging Players: India's PLI scheme for farm machinery opens a window for local assembly partnerships that lower effective cost-of-entry for foreign manufacturers. Target rain-fed rice operations in Nigeria's Niger Delta and Senegal's Senegal River Valley with lease-to-own structures matching cash-flow profiles. Pilot retrofit automation kits for walking-type platforms in Bangladesh as a beachhead before full-platform competition. For Investors and Strategic Acquirers: Re-rating potential sits with precision automation specialists given vision-guidance and GPS-RTK row-tracking maturation compressing operator skill requirements. Long-term viability favors manufacturers with demonstrated BIS localization compliance and electric drivetrain development speed. Monitor Chinese MIIT battery standardization progress as interoperability expectations reduce manufacturer lock-in and reshape competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Infrastructure Deployment | Chinese MIIT standardization creates interoperability reducing manufacturer lock-in across cooperative fleets. |
| Vision-Guidance Retrofit Module Development | Vietnamese distributors capture upgrade spending from operators deferring full-platform replacement cycles. |
| Local Assembly Partnership Formation | India's PLI scheme subsidies rebalance cost-of-entry calculus for multinational market entry. |
| Biodegradable Hydraulic Fluid Reformulation | EU F-Gas Regulation compliance requires reformulated seals adding SKU complexity for European exports. |
| Mechatronics Technician Training Program | Vietnamese service networks address 90-day training gaps for electric actuator maintenance and CAN-bus diagnostics. |
Research Methodology
Independent corroboration across primary interviews with OEM procurement teams, aftermarket service heads, and agricultural cooperative fleet managers, plus secondary validation through customs/trade data, MIIT certification filings, and SEC equipment manufacturer disclosures, underwrites the qualitative findings. Bottom-up demand modeling from cooperative procurement patterns and top-down supply assessment from manufacturing capacity announcements were triangulated.
Rate-of-change decomposition across product type, technology architecture, and end-user procurement authority segments drove volume and value outputs over the projection horizon. CAGRs derived from regression analysis against mechanization penetration rates and subsidy program enrollment trajectories. Forecast inputs incorporated diesel engine certification timeline compression under China's GB standards and battery-swapping infrastructure rollout curves.
The model assumes a particular technology adoption path; alternative pathways for electric drivetrain standardization would alter the outlook if interoperability expectations fail to materialize. Forecasts reflect assumptions on cooperative membership growth and government subsidy continuity. Practitioners should monitor Chinese MIIT battery form factor standardization and Vietnamese Mekong Delta cooperative procurement consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Battery Powered Sprayer Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Tree Trimmers Market