
 Soil Aerators Market | 2026-2036
Soil Aerators Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Aerators Market Outlook
Multi-source procurement for tine assemblies and drive systems is pivoting toward vertically integrated supply chains as OEMs seek tighter quality control over wear components. Deere & Company leverages its captive foundry network to produce hardened aerator tines in-house, reducing supplier dependency. The Toro Company anchors its position through dedicated turf innovation centers in Minnesota and Florida. Husqvarna Group competes via modular battery platforms that span multiple landscaping tools, creating ecosystem lock-in among municipal fleet buyers.
Soil aerators are mechanical devices designed to perforate soil with hollow or solid tines, typically operating at depths of two to four inches to alleviate compaction and improve gas exchange in root zones. Core aerators extract cylindrical soil plugs to reduce thatch buildup and enhance water infiltration, while spike aerators create holes without material removal for lighter maintenance applications. Puncture and core aerator types command the largest installed base among golf course managers due to proven agronomic outcomes. Battery-operated power sources represent the fastest-expanding category as lithium-ion pack energy density improves and EPA Phase 3 emissions rules tighten compliance costs for gas-powered units.
Federal EPA regulations on small-engine emissions shape product development timelines and manufacturing location decisions for equipment sold in the United States. OSHA noise exposure limits for grounds maintenance workers accelerate demand for quieter electric and battery-operated alternatives in municipal and commercial contracts. European REACH restrictions on chromium plating affect tine surface treatment options for exporters serving EU markets. Stakeholders must weigh capital allocation between gas-powered legacy platforms and electrified product lines as regulatory thresholds tighten across multiple jurisdictions without uniform phase-in schedules.
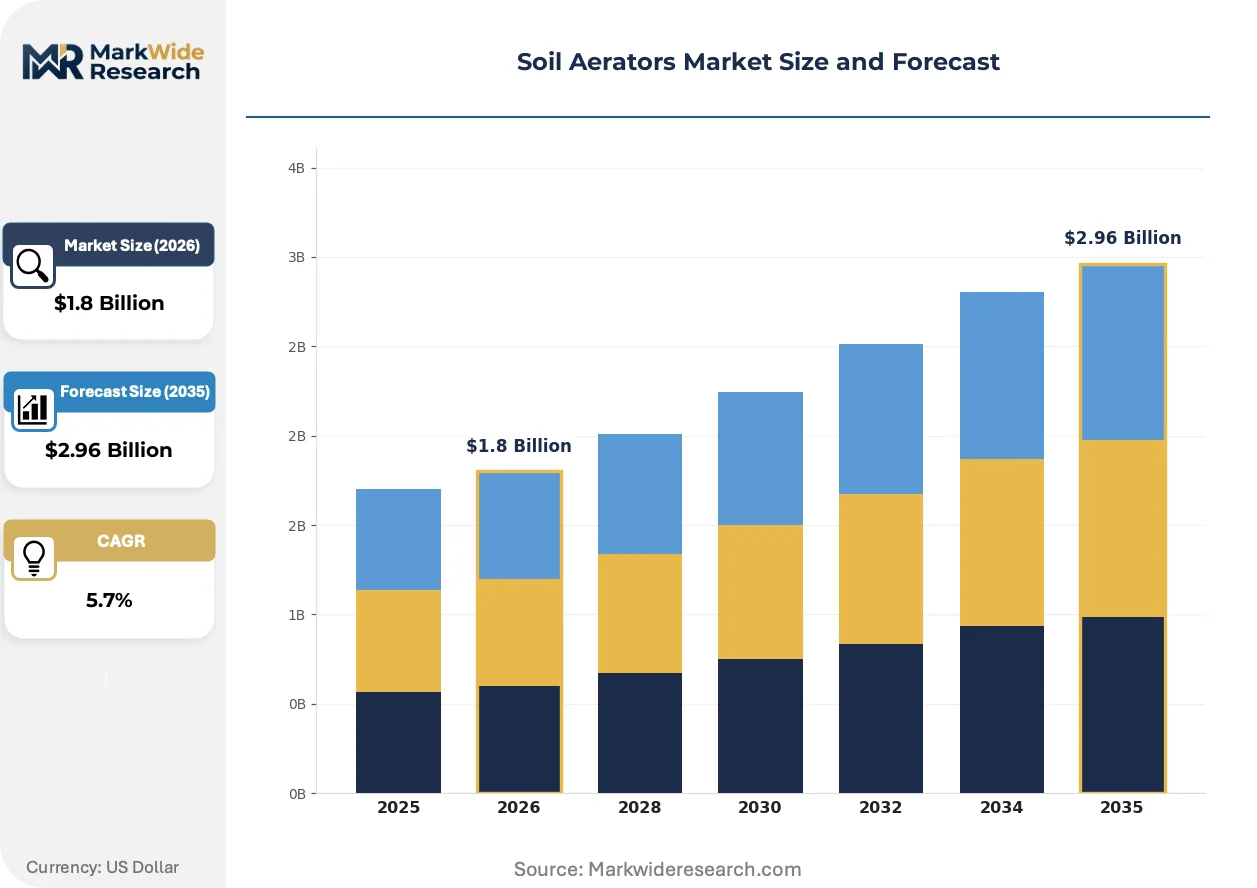
Market Dynamics
EPA Phase 3 emissions standards for small spark-ignition engines are forcing manufacturers to reallocate R&D budgets toward battery-electric platforms while maintaining gas-powered legacy lines for price-sensitive municipal buyers.
Growth Catalysts
- EPA Phase 3 Emissions Rules:Compliance deadlines for small-engine NOx and particulate limits accelerate fleet turnover among municipal parks departments, compressing replacement cycles for aging gas-powered aerator inventories.
- Lithium-Ion Energy Density Gains:Pack-level improvements above 250 Wh/kg enable commercial-grade runtime without the noise and vibration penalties that previously restricted electric units to residential applications.
- Golf Course Traffic Intensification:Heavier mowing and transport equipment compacts root zones faster, expanding aeration frequency requirements across North American course maintenance programs.
Market Restraints
- Steel Alloy Price Volatility:Hardened tine production depends on specialized wear-resistant alloys whose spot pricing fluctuates with construction and mining equipment demand cycles.
- Foundry Capacity Concentration:North American casting operations for precision tine components cluster in legacy manufacturing corridors, creating single-source vulnerability for mid-tier OEMs.
- Battery Thermal Limitations:Sustained high-torque aeration operations in ambient temperatures above 35°C trigger lithium-ion derating protocols that reduce effective runtime by 15-25%.
Strategic Opportunities
- India Turf Infrastructure Buildout:New golf course developments and cricket ground renovations in Maharashtra and Karnataka states create first-mover positioning for battery-electric equipment without legacy gas infrastructure.
- OSHA Noise Exposure Incentives:Municipal contracts in dense urban corridors increasingly specify sub-75 dB operation thresholds, disqualifying conventional gas units from bidding pools.
- Telematics-Enabled Usage Billing:Hour-meter data transmission allows equipment-as-a-service models that shift capital expenditure to operating budgets for cash-constrained landscaping contractors.
Industry Challenges
- Certification Timeline Compression:UL 2580 battery safety validation and EPA evaporative emissions certification must proceed in parallel, extending new product introduction schedules.
- Electrical Infrastructure Retrofit Costs:Municipal fleet depots require 480V three-phase installation and fire suppression system upgrades to support overnight charging of commercial battery packs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Aerators Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Puncture Aerators, Core Aerators, Spike Aerators, Tow-Behind Aerators Application: Residential Lawns, Commercial Turf, Sports Fields, Golf Courses Power Source: Manual, Gas-Powered, Electric, Battery-Operated End User: Landscapers, Homeowners, Municipalities, Golf Course Managers |
| Companies Covered | Deere & Company, The Toro Company, Husqvarna Group, Kubota Corporation, Briggs & Stratton, Alamo, AGCO Corporation, CNH Industrial, Mahindra & Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Aerators Market Strategic Shifts
Equipment electrification is absorbing engineering resources across the supply base while agronomic data integration creates new service revenue streams. Manufacturers now compete on ecosystem breadth rather than standalone machine specifications.
Brushless DC motor systems with integrated thermal management are absorbing the high-torque spikes characteristic of core aeration operations. Golf course superintendents in Florida and Arizona are adopting these platforms for noise-sensitive morning maintenance windows. The technology is absorbing price premiums that previously supported gas-engine service margins.
REACH restrictions on hexavalent chromium plating entered full enforcement for EU-bound equipment in 2024. Tine surface treatment processes must now substitute trivalent alternatives with reduced hardness retention. Exporters serving German and French municipal buyers face accelerated wear testing protocols to validate substitute coatings under abrasive soil conditions.
Municipal procurement offices are consolidating landscaping equipment purchases through cooperative purchasing agreements that span multiple agencies. State-level contracts in Texas and California now specify interoperable battery platforms across mowers, aerators, and utility vehicles. This concentration is displacing single-machine vendors who cannot demonstrate ecosystem compatibility.
Soil Aerators Market Segmentation
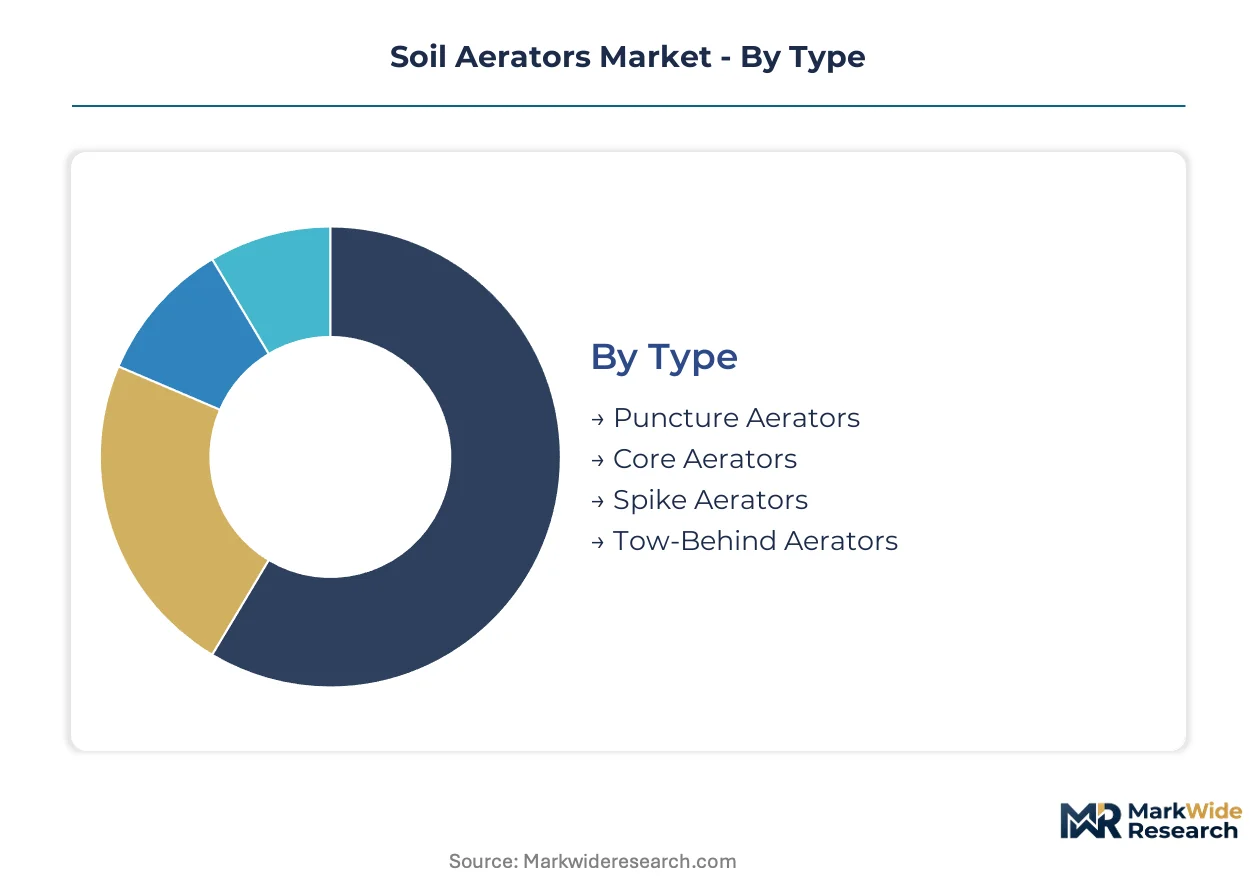
Equipment selection in soil aeration follows distinct procurement logics across buyer types, with golf course managers prioritizing agronomic precision while municipal fleets optimize for total cost of ownership and regulatory compliance. Segmentation reveals how power source transitions and application-specific durability requirements are reshaping manufacturer R&D allocation.
Type:
Purchase decisions here hinge on soil compaction severity and maintenance frequency rather than upfront equipment cost.
- Core Aerators:Hollow tines extract cylindrical soil plugs measuring 0.5 to 0.75 inches in diameter, creating channels that improve water infiltration and root gas exchange. Golf courses in Florida and Arizona specify these units for bi-weekly aeration programs combating sand-based root zone compaction. Equipment specifications emphasize tine penetration depth consistency across variable soil moisture conditions.
- Puncture Aerators:Solid tines perforate soil without material removal, suited for lighter maintenance on established turf with minimal thatch accumulation. Municipal parks departments in Texas deploy these for seasonal touch-ups between core aeration cycles. Operating speed and ground pressure distribution determine selection criteria.
- Spike Aerators:Narrow solid points create shallow holes for surface-level compaction relief on residential lawns and low-traffic commercial grounds.
- Tow-Behind Aerators:Hitch-mounted units leverage tractor power for large-area coverage across sports fields and expansive municipal properties.
Core Aerators leads on scale; Battery-Operated variants within each type lead on momentum.
Application:
Surface area and traffic intensity dictate equipment sizing, with sports fields requiring the highest durability specifications due to concentrated foot traffic.
- Golf Courses:Precision requirements span greens, tees, fairways, and roughs with distinct tine spacing and depth protocols for each zone. Superintendents in North Carolina and California maintain separate aerator inventories optimized for bentgrass versus bermudagrass root structures. Agronomic outcomes directly influence membership retention and tournament hosting eligibility.
- Sports Fields:Football and soccer grounds demand reinforced frame construction to withstand daily practice schedules and seasonal over-seeding operations. School districts in Ohio and Pennsylvania prioritize rapid recovery times between aeration and playable surface conditions.
- Commercial Turf:Corporate campuses and cemetery grounds balance aesthetic maintenance with operational efficiency across irregular terrain.
- Residential Lawns:Smaller footprint equipment dominates this price-sensitive segment where rental models compete with ownership.
Sports Fields command the steepest expansion trajectory as synthetic-to-natural turf conversions accelerate; Golf Courses retain the highest equipment specification density per acre.
Power Source:
Capital expenditure versus operating cost trade-offs are shifting as battery energy density improves and emissions compliance costs accumulate for gas-powered fleets.
- Battery-Operated:Lithium-ion packs above 250 Wh/kg now deliver commercial-grade runtime for core aeration operations without the noise and vibration penalties that restricted earlier electric units. Municipal contracts in dense urban corridors increasingly specify sub-75 dB operation thresholds that disqualify conventional gas alternatives. Brushless DC motor systems with integrated thermal management absorb high-torque spikes characteristic of tine penetration.
- Gas-Powered:Small spark-ignition engines retain installed base dominance among price-sensitive municipal buyers and landscaping contractors with established maintenance capabilities. EPA Phase 3 emissions standards are compressing replacement cycles as compliance costs erode total cost of ownership advantages.
- Manual:Foot-operated and handheld units serve residential spot treatments and professional edge work where equipment transport costs exceed mechanized deployment benefits.
- Electric:Corded platforms persist in fixed-location commercial maintenance facilities with reliable grid access and predictable daily route patterns.
Gas-Powered retains volume leadership; Battery-Operated is climbing the fastest as fleet electrification mandates propagate across municipal procurement.
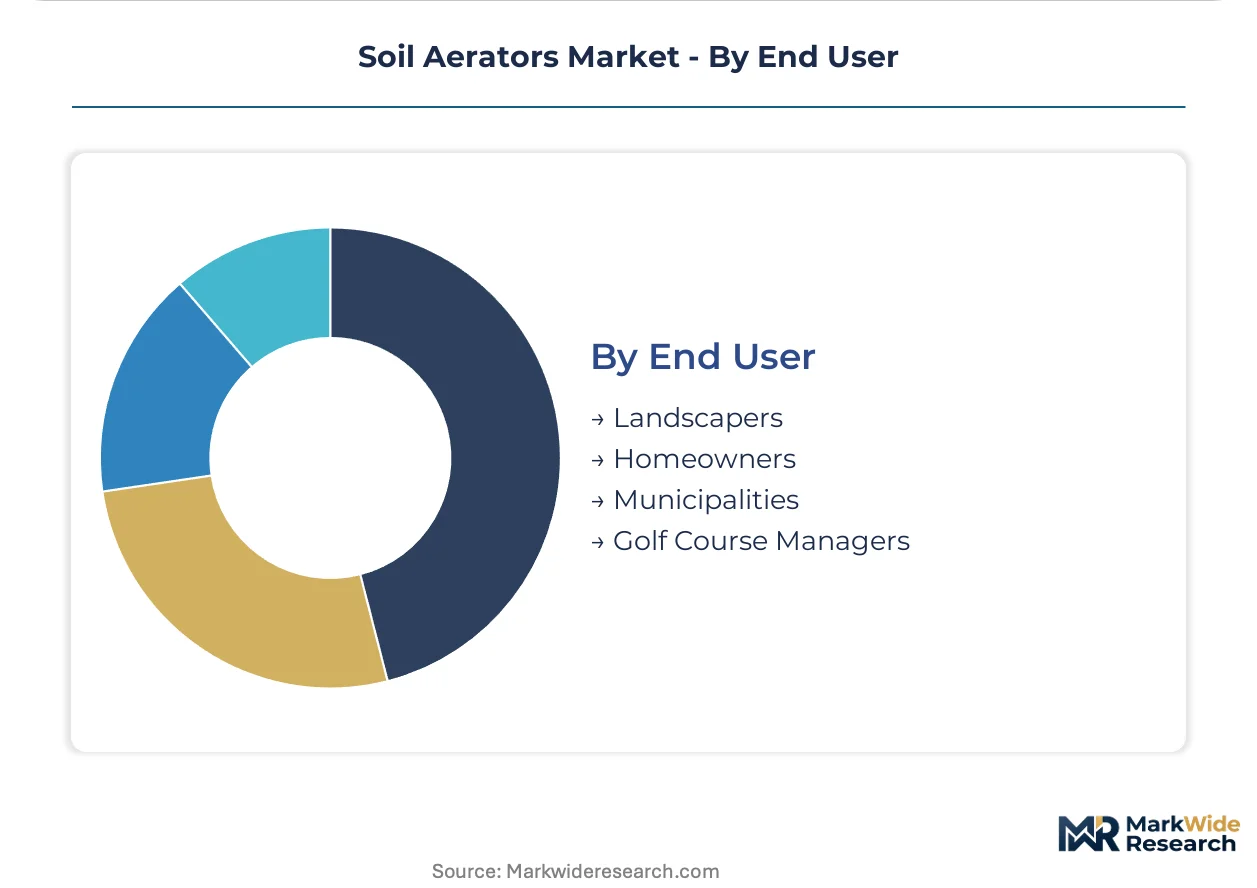
End User:
Procurement sophistication varies dramatically, with professional users demanding telematics integration and usage-based billing models.
- Municipalities:Cooperative purchasing agreements spanning multiple agencies consolidate volume and specify interoperable battery platforms across mowers, aerators, and utility vehicles. State-level contracts in California and Texas now disqualify single-machine vendors lacking ecosystem compatibility. Capital budgeting constraints favor equipment-as-a-service models with hour-meter data transmission.
- Landscapers:Independent contractors prioritize equipment versatility across customer types and rapid deployment capabilities for seasonal demand spikes. Fleet standardization reduces spare parts inventory and technician training overhead.
- Golf Course Managers:Agronomic expertise drives specification decisions with direct superintendent involvement in equipment trials and performance validation protocols.
- Homeowners:Retail channel purchases respond to seasonal promotion cycles and rental availability in home improvement centers.
Municipalities anchor procurement volume; Golf Course Managers set specification standards that diffuse to adjacent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-St. Paul metropolitan area anchors North American soil aerator engineering talent and captive foundry capacity for hardened tine production.
United States
Municipal parks departments in Texas and California consolidate landscaping equipment purchases through cooperative agreements spanning multiple agencies. EPA Phase 3 emissions standards for small spark-ignition engines compress replacement cycles for aging gas-powered aerator inventories. The Twin Cities corridor in Minnesota concentrates turf innovation centers where superintendents validate equipment performance protocols.
Germany
Golf course developments in Bavaria and Baden-Württemberg sustain demand for precision aeration equipment with distinct tine spacing protocols. REACH restrictions on hexavalent chromium plating entered full enforcement in 2024, forcing exporters to substitute trivalent surface treatments. The Stuttgart industrial cluster hosts precision casting operations for wear-resistant aerator components serving EU municipal buyers.
China
Dual carbon goals under MIIT direction accelerate battery-electric platform development for landscaping equipment without legacy gas infrastructure. Zhejiang and Jiangsu provinces concentrate foundry capacity for hardened steel tines serving domestic sports field construction. The Yangtze River Delta integrates lithium-ion pack assembly with commercial-grade motor controller production.
India
New golf course developments in Maharashtra and Karnataka states create first-mover positioning for battery-electric equipment. BIS certification requirements for agricultural and landscaping machinery shape product localization timelines. The Pune-Nashik manufacturing corridor attracts component suppliers for turf maintenance equipment targeting cricket ground renovations.
Australia
Sports field managers in New South Wales and Victoria prioritize rapid recovery aeration protocols for seasonal over-seeding operations. The country's national environmental regulator enforces noise exposure limits that accelerate demand for sub-75 dB electric alternatives. The Melbourne metropolitan area concentrates landscaping contractor fleets standardizing on interoperable battery platforms.
Soil Aerators Market Competitive Environment
Global majors compete with regional champions across battery platform ecosystems and foundry-integrated supply chains. The vendor base organizes around three tiers: diversified agricultural equipment conglomerates with captive component production, specialized turf maintenance manufacturers with dedicated innovation centers, and emerging battery-electric specialists leveraging modular powertrain architectures. Strategic moves concentrate on backward integration into hardened tine casting and ecosystem lock-in through interoperable battery platforms across municipal fleet contracts.
Within the diversified equipment tier, Deere & Company and The Toro Company exemplify contrasting approaches to vertical integration and geographic focus. Deere leverages its captive foundry network for in-house tine production, while Toro anchors position through dedicated turf innovation centers in Minnesota and Florida. Husqvarna Group occupies the modular ecosystem position, competing via battery platforms that span multiple landscaping tools and create fleet standardization incentives among municipal buyers.
| Leading Market Players |
|---|
| Deere & Company |
| The Toro Company |
| Husqvarna Group |
| Kubota Corporation |
| Briggs & Stratton |
| Alamo |
| AGCO Corporation |
| CNH Industrial |
| Mahindra & Mahindra |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EPA Phase 3-compliant battery platforms and legacy gas-powered units manifests in both pricing stratification and supply chain reconfiguration. Municipal buyers in California and Texas face 15-25% acquisition premiums for battery-operated aerators that satisfy sub-75 dB noise contracts, while hardened tine sourcing from captive foundries versus merchant suppliers creates parallel cost structures across equipment tiers.
Pricing Analysis
Specialized steel alloy pass-through from construction and mining demand cycles exerts immediate pressure on core aerator tine pricing. Three-tier pricing structure across premium, standard, and economy levels separates UL 2580-validated battery packs from gas-powered legacy units and unbranded manual alternatives. EPA compliance costs are compressing margins in the gas-powered tier as evaporative emissions certification extends development timelines. Municipal fleet buyers exhibit lowest price sensitivity due to cooperative purchasing leverage, while independent landscaping contractors face acute capital constraints driving rental model adoption.
Supply Chain Analysis
Reverse-logistics flows for lithium-ion pack refurbishment and tine remanufacturing are emerging as cost centers as battery-operated installed base expands. Foundry capacity clusters in the United States, Germany, and China, with hardened alloy production drawing from chromium and nickel supply chains subject to REACH and EPA surface treatment restrictions. Single-source vulnerability concentrates in legacy manufacturing corridors for precision casting operations. Distribution runs through municipal cooperative purchasing agreements and specialized turf equipment dealers serving golf course superintendents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EPA-regulated municipal replacement cycles in the United States and greenfield battery-electric adoption in India, where absence of legacy gas infrastructure eliminates stranded asset risk for new entrants.
For Market Incumbents: Extend captive foundry capacity into trivalent chromium plating substitutes to neutralize REACH enforcement risk on EU exports. Secure 480V three-phase charging infrastructure partnerships with municipal fleet depots to lock in battery platform ecosystems before interoperability standards consolidate.
For New Entrants and Emerging Players: Enter via Maharashtra and Karnataka golf course developments with battery-electric platforms that bypass gas infrastructure entirely. Cricket ground renovations offer lower specification barriers than established golf markets. Telematics-enabled usage billing addresses cash-constrained contractor segments.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier OEMs lack captive tine production and face simultaneous EPA and REACH compliance investments. Five-to-ten year viability favors foundry-integrated specialists with modular battery architectures. Monitor BIS certification timelines for India localization as inflection signal for geographic expansion returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Backward Integration | Captive tine production insulates margin from steel alloy spot volatility and REACH substitution costs. |
| Battery Platform Ecosystem Lock-in | Interoperable packs across mowers and aerators satisfy Texas and California cooperative procurement specifications. |
| Telematics-Enabled Service Models | Hour-meter data transmission converts capital expenditure to operating budgets for municipal budget cycles. |
| Trivalent Chromium Process Transition | EU-bound equipment requires surface treatment substitution as hexavalent plating restrictions enter full enforcement. |
| India Localization Partnership | BIS certification and Pune-Nashik corridor manufacturing address cricket ground and golf course buildout demand. |
Study Parameters
Direct dialogue with golf course superintendents, municipal fleet managers, turf equipment procurement officers, and aftermarket service directors grounded qualitative assessment in operational constraints. Secondary validation drew from EPA Phase 3 regulatory filings, OSHA noise exposure enforcement records, REACH restriction implementation notices, and customs data on hardened alloy trade flows. Bottom-up equipment shipment analysis and top-down turf maintenance expenditure triangulation reconciled volume estimates across the analysis window.
Segment-level projections incorporated power source transition curves, replacement cycle compression from emissions compliance, and battery energy density improvement trajectories. Modeled dimensions spanned aerator type, application intensity, power source architecture, and end-user procurement sophistication. CAGRs derived from equipment installed base turnover rates and municipal fleet electrification mandate propagation patterns.
Inputs from regulatory agency enforcement calendars and foundry capacity utilization surveys were available through the study window; gaps in battery thermal derating field performance data introduce uncertainty bands for high-temperature climate adoption forecasts. Practitioners should monitor EPA Phase 3 implementation timelines and lithium-ion pack cost curves for early signals of platform transition acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Global Yield Monitoring Devices Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market