
 Copper and Copper Alloy Busbars Market | 2026-2036
Copper and Copper Alloy Busbars Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Copper Alloy Busbars Market Insights
Aluminum is broadening its competitive challenge to copper busbars in weight-sensitive applications such as aerospace and select automotive platforms, yet copper retains decisive advantages in conductivity-critical segments. Aurubis anchors European supply through integrated smelting and refining operations. Luvata specializes in precision-engineered alloy formulations for high-performance electrical contacts. Schneider Electric SE leverages its global distribution network to bundle busbar systems with switchgear and power distribution units.
Copper and copper alloy busbars are rigid conductive bars, typically extruded or rolled to precise cross-sectional dimensions with purity grades exceeding 99.9% electrical conductivity, engineered to distribute high-current power across switchgear, transformers, and industrial control systems with minimal resistive loss. Pure copper busbars dominate installed base volumes across legacy power infrastructure due to established thermal performance benchmarks, while copper beryllium variants command premium positioning in aerospace and military applications where fatigue resistance and conductivity must coexist. Renewable energy systems represent the fastest-growing application segment as utility-scale solar and offshore wind projects require specialized laminated and insulated busbar configurations to manage intermittent load profiles.
The EU F-Gas Regulation and REACH compliance frameworks constrain alloy composition choices for manufacturers serving European electrical equipment manufacturers, while China's GB standards and dual carbon goals enforce progressively stricter efficiency thresholds for power distribution components. The US National Electrical Code and OSHA electrical safety standards dictate ampacity ratings and installation clearances that directly influence busbar sizing specifications across North American data center and industrial builds. Stakeholders must monitor how divergent regional efficiency mandates affect alloy selection tradeoffs between conductivity, cost, and regulatory compliance.
Market Dynamics
Hyperscale data center buildouts are compressing procurement cycles for high-ampacity busbar systems as operators race to energize AI training clusters before facility commissioning deadlines slip.
Growth Catalysts
- EU Green Deal mandates:National renewable energy targets across Germany, France, and Spain are forcing grid operators to replace aging aluminum busbar infrastructure with copper-intensive configurations that handle higher intermittent loads from solar and wind farms.
- China's dual carbon goals:Provincial efficiency benchmarks under the national carbon neutrality commitment are accelerating power distribution upgrades in manufacturing zones, concentrating demand for high-conductivity busbar assemblies.
- Data center liquid cooling convergence:Direct-to-chip thermal management systems require laminated busbar architectures that integrate power delivery with coolant routing, creating specialized demand from hyperscale operators in Northern Virginia and Frankfurt.
Market Restraints
- Copper price volatility:Concentration of mined supply in Chile and Peru exposes fabricators to exchange-driven input cost swings that compress margin predictability on fixed-price infrastructure contracts.
- Aluminum substitution in weight-critical platforms:Aerospace OEMs and select electric vehicle battery pack designers are specifying aluminum busbar solutions where conductivity requirements permit mass reduction tradeoffs.
- REACH alloy restrictions:ECHA compliance frameworks limit beryllium-copper formulations in European electrical equipment, constraining material options for high-fatigue applications without equivalent conductivity substitutes.
Strategic Opportunities
- India transmission expansion:Central Electricity Authority targets for renewable evacuation infrastructure create underpenetrated demand for 132kV and above busbar systems as state utilities modernize substations.
- Offshore wind cable marshalling:Turbine collector platforms require corrosion-resistant tin-plated busbar configurations that withstand North Sea salt exposure, opening specialized fabrication niches.
- US Inflation Reduction Act domestic content:Tax credit adders for domestically manufactured electrical components are incentivizing reshoring of busbar extrusion and finishing capacity to serve utility-scale solar developers.
Industry Challenges
- Skilled welder scarcity:Tungsten inert gas certification for thick-section copper joining remains concentrated among aging workforces in Ohio and Pennsylvania fabrication shops, constraining expansion timelines.
- Legacy switchgear integration:Retrofit projects require custom busbar bending and drilling patterns to mate with 1980s-era breaker compartments without full panel replacement, extending engineering cycles.
- IEC 61439-1 testing backlog:Certification queue lengths at accredited laboratories are stretching product validation timelines for manufacturers targeting European switchgear OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper and Copper Alloy Busbars Market |
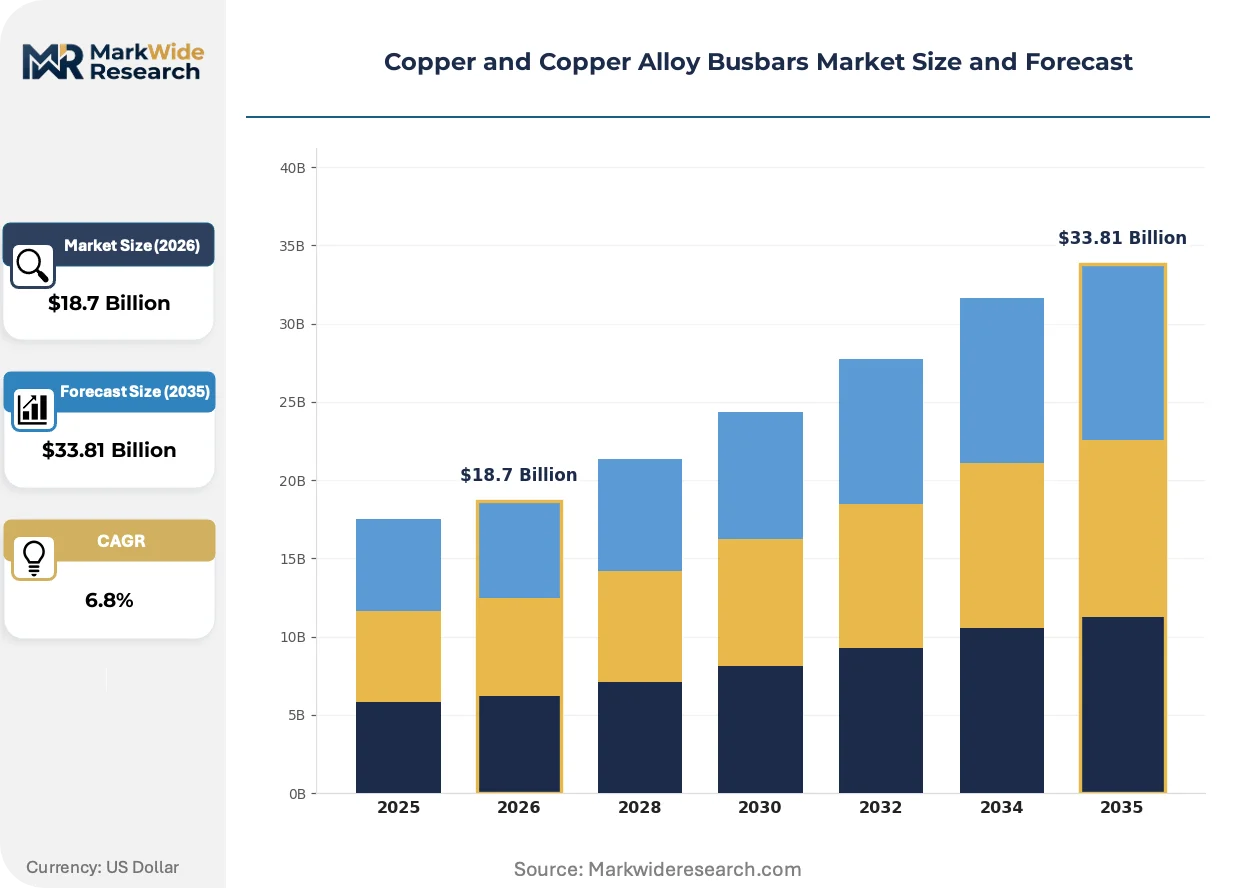
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Copper, Brass, Bronze, Nickel Silver, Copper Beryllium Application: Power Distribution Units, Switchgear, Transformers, Control Panels, Renewable Energy Systems End User: Electrical Equipment Manufacturers, Power Generation Companies, Data Centers, Telecommunication Providers Form: Flat, Rounded, Insulated, Perforated, Laminated |
| Companies Covered | Schneider Electric SE, ABB Ltd, Luvata, Oriental Copper, Gindre, Aurubis, ElvalHalcor, Southwire Company, Nexans S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Copper Alloy Busbars Market Trends and Innovations
Laminated and insulated busbar architectures are displacing traditional bolted-bus configurations as thermal management and space density requirements intensify across power-intensive applications.
Additive manufacturing of copper-chromium-zirconium alloys is overtaking conventional extrusion for prototype and low-volume aerospace busbar production. NASA Glenn Research Center and satellite prime contractors are qualifying electron-beam melted geometries that optimize current density in constrained payload envelopes. This technology is overtaking machined-from-solid approaches by eliminating material waste and compressing lead times for mission-specific electrical distribution systems.
China's GB/T 7251 series efficiency amendments are tightening permissible temperature rise limits in low-voltage switchgear assemblies. MIIT enforcement of these standards is compelling domestic busbar suppliers to upgrade from standard electrolytic copper to oxygen-free grades with superior conductivity retention at elevated operating temperatures. Industrial control panel builders in Jiangsu and Guangdong provinces are absorbing these material cost premiums to maintain market access.
Specification consolidation among EPC firms is compressing approved vendor lists for major infrastructure projects. Engineering-procurement-construction primes including Bechtel and Fluor are mandating pre-qualified busbar suppliers with integrated metallurgical testing and third-party witness inspection capabilities. This concentration is most visible in Middle Eastern desalination and petrochemical complexes where owner-operators demand single-source accountability for power distribution reliability.
Copper and Copper Alloy Busbars Market Segmentation
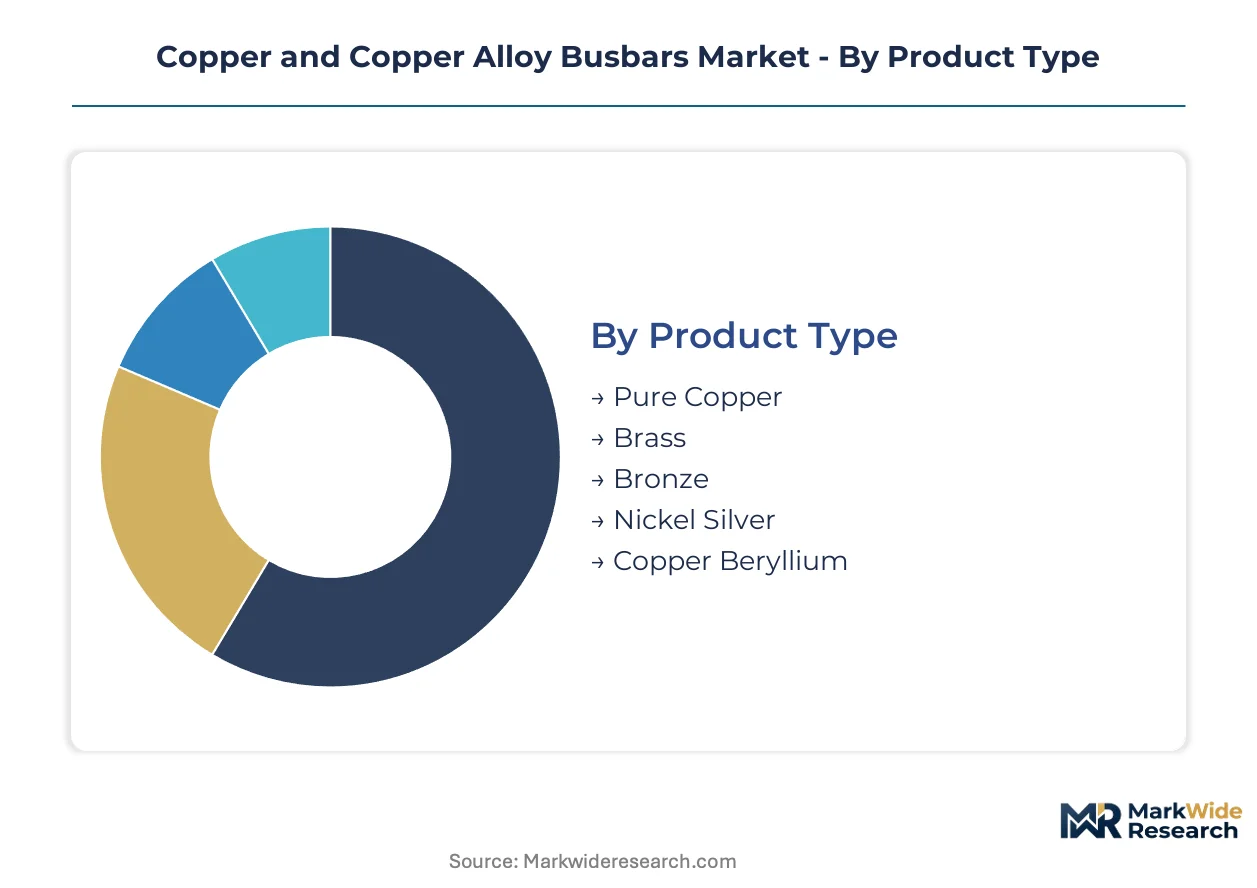
Copper and copper alloy busbars serve divergent performance requirements across conductivity-critical and cost-optimized applications. Segmentation reveals where material science investments concentrate versus where commoditized supply suffices.
Product Type:
Pure copper dominates tonnage while copper beryllium commands premium positioning in fatigue-critical aerospace and military electrical systems.
- Pure Copper:Electrolytic grades exceeding 99.9% IACS conductivity anchor legacy power infrastructure and standard switchgear installations. Demand concentrates in Chinese manufacturing zones where provincial efficiency mandates under dual carbon goals are forcing upgrades from aluminum to copper-intensive distribution systems.
- Copper Beryllium:Age-hardened alloys combining high conductivity with elastic modulus retention serve satellite payload distribution and aircraft flight control systems. Procurement from NASA Glenn Research Center and defense primes is accelerating as additive manufacturing enables topology-optimized geometries for mass-constrained applications.
- Brass:Zinc-alloyed variants trade conductivity for machinability in threaded busbar terminals and grounding applications.
- Bronze:Tin additions improve corrosion resistance for offshore wind turbine marshalling platforms exposed to North Sea salt.
- Nickel Silver:Copper-nickel-zinc compositions provide tarnish resistance for decorative and low-current architectural power distribution.
Today's leader: Pure Copper. Tomorrow's challenger: Copper Beryllium.
Application:
Application segmentation tracks where thermal management complexity and ampacity requirements are reshaping procurement specifications.
- Renewable Energy Systems:Utility-scale solar and offshore wind projects require laminated and insulated busbar configurations engineered for intermittent load cycling. Procurement from EPC firms including Bechtel and Fluor is compressing approved vendor lists as specification consolidation demands integrated metallurgical testing capabilities.
- Data Centers:Hyperscale facilities in Northern Virginia and Frankfurt are specifying direct-to-chip liquid cooling convergence architectures that integrate power delivery with coolant routing. AI training cluster commissioning deadlines are compressing procurement cycles for high-ampacity laminated systems.
- Power Distribution Units:Standardized switchboard assemblies for commercial buildings specify flat copper bars within IEC 61439-1 temperature rise limits.
- Switchgear:Retrofit projects require custom bending patterns to mate with 1980s-era breaker compartments without full panel replacement.
- Transformers:Winding terminations and tap changer connections use rounded-edge busbars to reduce eddy current losses.
- Control Panels:Industrial automation enclosures specify perforated busbars for component mounting flexibility.
Renewable Energy Systems and Data Centers together are climbing the fastest as electrification and digital infrastructure investments accelerate.
End User:
End user segmentation distinguishes between specification authority and procurement execution in complex supply chains.
- Electrical Equipment Manufacturers:Switchgear OEMs in Jiangsu and Guangdong provinces are absorbing oxygen-free copper cost premiums to maintain access under tightened GB/T 7251 efficiency amendments. These manufacturers hold specification authority that cascades through EPC and utility procurement.
- Data Centers:Hyperscale operators in Frankfurt and Northern Virginia are consolidating procurement for bundled power distribution and thermal management systems.
- Power Generation Companies:German, French, and Spanish grid operators are replacing aging aluminum infrastructure under EU Green Deal renewable integration mandates.
- Telecommunication Providers:5G edge computing facilities specify compact insulated busbar configurations for space-constrained equipment shelters.
Electrical Equipment Manufacturers set specifications. Data Centers are gaining direct procurement leverage.
Form:
Form factor selection reflects the tension between installation efficiency and thermal-electrical performance optimization.
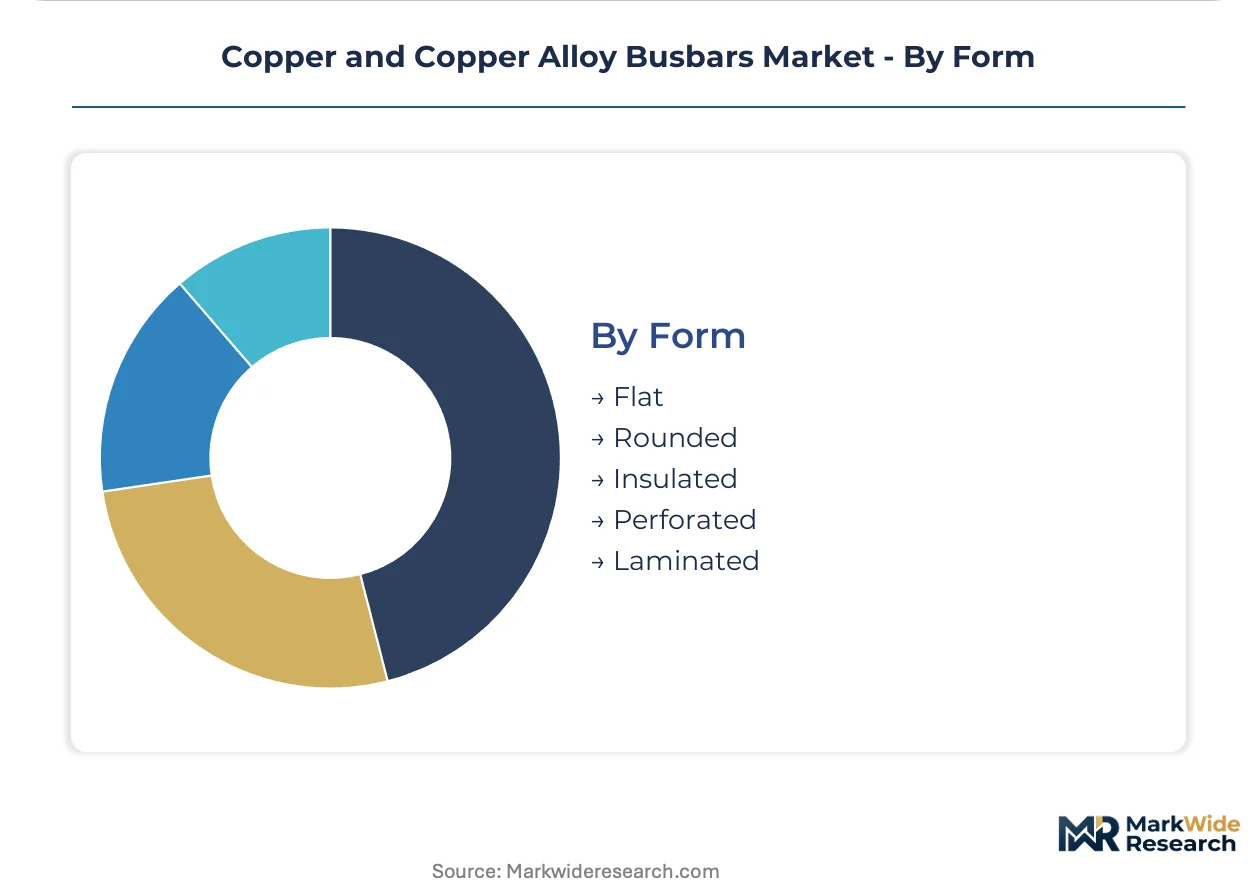
- Laminated:Multi-layer copper and insulation sandwiches enable high current density in confined enclosures. Demand from offshore wind turbine platforms requires corrosion-resistant tin-plated configurations that withstand salt exposure while maintaining ampacity.
- Insulated:Pre-coated busbars eliminate field wrapping and reduce installation clearance requirements for data center and marine applications.
- Flat:Standard extruded profiles dominate legacy infrastructure where bolted connections and established ampacity tables govern design.
- Rounded:Edge conditioning reduces corona discharge in medium-voltage switchgear above 15kV.
- Perforated:Pre-drilled mounting patterns accelerate panel assembly for industrial control builders.
Laminated forms are displacing traditional bolted configurations where space density and thermal management requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Guangdong provinces concentrate Chinese manufacturing capacity for high-conductivity busbar systems serving both domestic power distribution upgrades and export fabrication contracts. Provincial efficiency benchmarks under China's dual carbon goals are forcing industrial control panel builders to absorb oxygen-free copper cost premiums. MIIT enforcement of tightened GB/T 7251 temperature rise limits is accelerating material grade migrations across low-voltage switchgear assemblies.
China
Yangtze River Delta and Pearl River Delta clusters dominate global extrusion capacity for electrolytic copper busbars serving hyperscale data center procurement. MIIT's GB standards amendments are compelling domestic suppliers to upgrade from standard to oxygen-free copper grades. Fabricators in Jiangsu and Guangdong are absorbing material cost premiums to maintain market access under efficiency mandates.
United States
Northern Virginia data center corridors and Ohio-Pennsylvania fabrication shops anchor North American demand for high-ampacity laminated systems. OSHA electrical safety standards and the National Electrical Code dictate ampacity ratings and installation clearances across industrial builds. The Inflation Reduction Act's domestic content tax credit adders are incentivizing reshoring of extrusion capacity to serve utility-scale solar developers.
Germany
Ruhr industrial belt and Bavarian electrical equipment clusters drive European demand for switchgear-integrated busbar assemblies. The EU F-Gas Regulation and REACH compliance frameworks constrain alloy composition choices for manufacturers serving domestic OEMs. Grid operators are replacing aging aluminum infrastructure under EU Green Deal renewable integration mandates.
India
Maharashtra and Gujarat manufacturing zones are emerging as procurement destinations for 132kV and above busbar systems. Central Electricity Authority targets for renewable evacuation infrastructure are creating underpenetrated demand as state utilities modernize substations. Domestic fabrication capacity is scaling to serve transmission expansion projects across western and southern states.
France
Île-de-France electrical equipment manufacturers and Atlantic offshore wind ports require corrosion-resistant tin-plated configurations. ECHA compliance frameworks limit beryllium-copper formulations in European equipment, constraining material options for high-fatigue applications. Turbine collector platforms in the North Sea are specifying salt-resistant laminated architectures.
Copper and Copper Alloy Busbars Market Competitive Landscape
Global majors compete with regional champions across metallurgical capabilities and distribution reach. The vendor base stratifies between integrated miners with captive refining, precision alloy specialists, and electrical equipment bundlers. Three archetypes dominate: vertically integrated copper producers controlling smelting-to-fabrication chains; precision alloy formulators serving aerospace and satellite applications; and power distribution OEMs integrating busbars with switchgear portfolios. Competitive moves concentrate on specification consolidation through pre-qualified supplier lists and capacity expansion to capture Inflation Reduction Act domestic content incentives.
Within the integrated producer tier, Aurubis anchors European supply through smelting and refining operations spanning Hamburg and Pirdop. Luvata occupies a specialist position in precision-engineered alloy formulations for high-performance electrical contacts. Schneider Electric SE exemplifies the bundling archetype, leveraging global distribution networks to integrate busbar systems with switchgear and power distribution units.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Luvata |
| Oriental Copper |
| Gindre |
| Aurubis |
| ElvalHalcor |
| Southwire Company |
| Nexans S.A. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal renewable integration mandates gate qualified supply for high-conductivity busbar systems, restricting premium-tier pricing access to fabricators with oxygen-free copper metallurgy and third-party witness inspection capabilities. This regulatory filter concentrates pricing power among integrated producers while compressing margins for standard-grade competitors.
Pricing Analysis
Input-cost pass-through from Chilean and Peruvian mined copper concentrates dominates pricing dynamics for extruded busbar fabricators. Three-tier pricing structure across oxygen-free premium, standard electrolytic, and aluminum-substitute economy levels differentiates by conductivity retention and GB/T 7251 certification grade. Cost compression in standard-grade segments is intensifying because Chinese provincial efficiency mandates are forcing material upgrades without commensurate price recovery. Data center operators show least price sensitivity for laminated liquid-cooling configurations, while commercial building contractors resist premiums beyond legacy flat-bar specifications.
Supply Chain Analysis
Skilled TIG welder availability constrains expansion timelines in Ohio and Pennsylvania fabrication shops, anchoring North American laminated busbar capacity. Supply concentrates in China, Germany, and the United States, with Jiangsu and Guangdong provinces controlling global extrusion output. Raw material dependencies draw from Chilean copper concentrates, Peruvian blister copper, and domestic scrap recovery streams. Single-source vulnerability runs through accredited IEC 61439-1 testing laboratories stretching certification queues. Distribution runs through EPC pre-qualified vendor lists mandating integrated metallurgical testing for Middle Eastern and European infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's oxygen-free copper cost premiums under MIIT efficiency enforcement and India's underpenetrated 132kV transmission infrastructure with lower specification barriers.
For Market Incumbents: Anticipate aluminum substitution pressure in electric vehicle battery packs by deepening backward integration into Chilean copper concentrate offtake. Secure capacity expansion in Northern Virginia data center corridors before Inflation Reduction Act domestic content adders attract new entrants. Lock EPC specification authority through bundled switchgear-busbar integration with third-party witness inspection capabilities. For New Entrants and Emerging Players: Additive manufacturing of copper-chromium-zirconium alloys offers a technology-first wedge into satellite payload distribution and aerospace flight control systems where fatigue resistance commands premium positioning. Target India's renewable evacuation infrastructure as the most penetrable geography, where Central Electricity Authority targets outpace domestic fabrication capacity. Pursue qualification partnerships with NASA Glenn Research Center and defense primes as the go-to-market angle for topology-optimized geometries. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extrusion specialists lacking IEC 61439-1 certification and integrated metallurgical testing. Long-term viability over the next decade hinges on capturing Inflation Reduction Act reshoring incentives and EU Green Deal infrastructure replacement cycles. Watch queue lengths at accredited testing laboratories as the inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Concentrate Supply | Captive offtake from Chilean mining operations insulates margin volatility from exchange-driven input swings. |
| IEC 61439-1 Certification Investment | Pre-qualified status with EPC firms including Bechtel and Fluor unlocks Middle Eastern petrochemical complex procurement. |
| Additive Manufacturing Capability Buildout | Electron-beam melted geometries qualify with NASA Glenn Research Center for satellite payload mass-constrained applications. |
| India Manufacturing Footprint Establishment | Maharashtra and Gujarat positioning captures Central Electricity Authority renewable evacuation infrastructure demand. |
| Liquid Cooling Convergence Product Development | Laminated busbar-coolant integration meets hyperscale operator specifications in Northern Virginia and Frankfurt clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with switchgear OEM procurement directors, EPC contractor specification engineers, data center facility managers, and copper smelter commercial leads with secondary validation. Sources included customs trade data for copper semis, MIIT GB standards filings, SEC 10-K disclosures from integrated producers, and IEC certification database records. Bottom-up project pipeline aggregation and top-down macroeconomic elasticity modeling were cross-checked for triangulation.
Comparable-period anchoring established historical reference baselines across the projection horizon, with segmentation modeling across product type, application, end user, and form factor dimensions. CAGRs were derived from elasticity-adjusted volume projections incorporating copper price scenario bands and regional regulatory enforcement intensity. Industry-specific inputs included hyperscale data center commissioning schedules and offshore wind turbine installation forecasts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chilean mining supply disruptions, ECHA REACH alloy restriction amendments, and Chinese dual carbon goal acceleration. Forecasts reflect documented assumptions about MIIT enforcement consistency and Inflation Reduction Act domestic content interpretation. Material deviation in copper concentrate availability or IEC certification queue lengths warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Current Clamps Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Insulator Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Lighting Contactor Market