
 Global Electric Plugs and Sockets Market | 2026-2036
Global Electric Plugs and Sockets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Plugs and Sockets Market Foresight
Polycarbonate is restructuring cost-performance tradeoffs across mid-voltage socket housings, displacing legacy bakelite formulations in price-sensitive segments. Schneider Electric S.A. leverages captive resin compounding to stabilize input costs across European distribution channels. Legrand S.A. anchors premium positioning through in-house mold fabrication and accelerated cycle times. Mennekes Elektrotechnik GmbH & Co. KG specializes in IP67-rated industrial configurations that dominate German automotive plant specifications.
Electric plugs and sockets are electromechanical coupling devices rated typically between 110V and 480V, engineered from thermoset or thermoplastic insulators with brass or beryllium copper contacts, designed to establish safe, reversible power connections between supply infrastructure and end-use equipment. Industrial sockets command the widest margin pools due to certification burdens and customized amperage configurations, while smart connectors represent the fastest-expanding technology segment as Wi-Fi enabled units integrate with building management systems in data centers and hospitality venues. USB plugs and power strips remain volume leaders in residential wiring applications, though price compression limits profitability for undifferentiated producers.
FCC Part 15 governs electromagnetic emissions from Wi-Fi enabled and Bluetooth integrated units in the United States, while the EU AI Act and CE marking under the Low Voltage Directive shape product compliance burdens for European market access. China's SAMR enforces GB standard alignment that affects export-bound manufacturing from Shenzhen and Dongguan clusters. Stakeholders must monitor divergence between regional cybersecurity mandates for connected outlets and the pace at which IEC harmonization narrows testing redundancy across jurisdictions.
Market Dynamics
IEC 60884-1 harmonization is compressing regional product variation while simultaneously accelerating replacement cycles across residential wiring infrastructure in Germany and India.
Growth Catalysts
- Industrial socket demand:Southeast Asian manufacturing zones require IP67-rated configurations for automotive and electronics assembly lines, pulling specialized connector volumes.
- Smart building integration:Wi-Fi enabled units with building management system compatibility are penetrating North American data center builds and hospitality venues.
- GB standard convergence:China's SAMR alignment reduces export friction for Shenzhen and Dongguan manufacturing clusters serving cross-border markets.
Market Restraints
- Copper price volatility:Brass and beryllium copper contact materials expose producers to commodity swings that compress margin stability.
- Certification fragmentation:Divergence between FCC Part 15 electromagnetic requirements and EU AI Act cybersecurity mandates creates testing redundancy.
- Bakelite displacement costs:Legacy thermoset housing formulations face forced obsolescence as polycarbonate achieves equivalent dielectric performance at lower unit cost.
Strategic Opportunities
- USB-C power delivery convergence:Unified charging standards across consumer electronics are creating socket-integrated USB module demand in residential retrofit markets.
- CE marking acceleration:Low Voltage Directive streamlining offers European market access advantages for producers achieving harmonized safety certification.
- Modular industrial configurations:Customizable amperage ratings and locking mechanisms address German automotive plant specifications without full redesign cycles.
Industry Challenges
- Mold fabrication lead times:In-house tooling capacity constraints at mid-tier producers delay product variant launches for region-specific voltage standards.
- Cybersecurity compliance talent:Connected outlet development requires embedded systems expertise scarce among traditional electromechanical engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Plugs and Sockets Market |
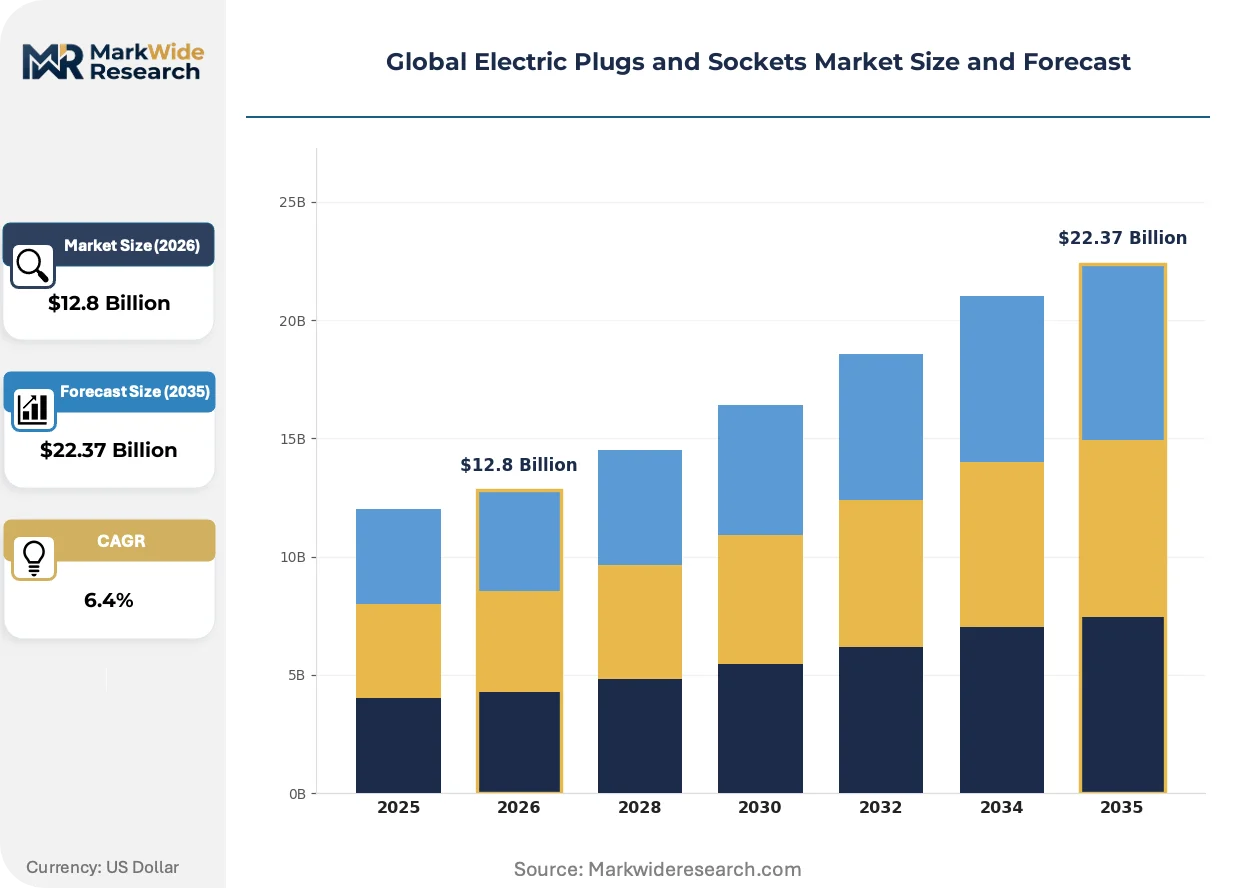
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Plugs, Travel Adapters, Industrial Sockets, Weatherproof Outlets, Smart Connectors, Power Strips Technology: Wi-Fi Enabled, Bluetooth Integrated, Smart Metered, Surge Protection, Modular Design, Energy Efficient Application: Residential Wiring, Commercial Electrical Setup, Data Centers, Transport Facilities, Hospitality Venues, Educational Institutions End User: Electrical Contractors, Facility Managers, Retailers, Institutional Buyers, Maintenance Teams, OEMs |
| Companies Covered | Legrand S.A., Emerson Electric Co., Schneider Electric S.A., TE Connectivity Ltd., Amphenol Corporation, ABB Ltd., Mennekes Elektrotechnik GmbH & Co. KG, Gewiss S.p.A., Eaton Corporation plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Plugs and Sockets Market Shifts & Advancements
Material substitution and connectivity integration are restructuring competitive advantage away from pure electromechanical reliability toward software-defined power management capabilities.
Polycarbonate resin compounding is electrifying mid-voltage socket housing production by matching bakelite's thermal resistance at 30% lower material cost. German automotive suppliers are specifying these formulations for plant-floor installations. The shift is compressing premium positioning windows for legacy thermoset specialists.
EU AI Act cybersecurity requirements for connected outlets are forcing firmware audit protocols that extend CE marking timelines by four to six months. Industrial socket producers with existing IP67 certification infrastructure are absorbing these burdens more efficiently than residential-focused competitors. German and French regulators are coordinating implementation guidance to reduce jurisdictional variance.
Specification consolidation among electrical contractors is displacing fragmented distributor relationships in North American data center construction. Engineering-procurement-construction firms now mandate pre-qualified smart connector vendors with integrated building management system APIs. This concentration is visible most acutely in Virginia and Texas hyperscale clusters.
Global Electric Plugs and Sockets Market Segmentation
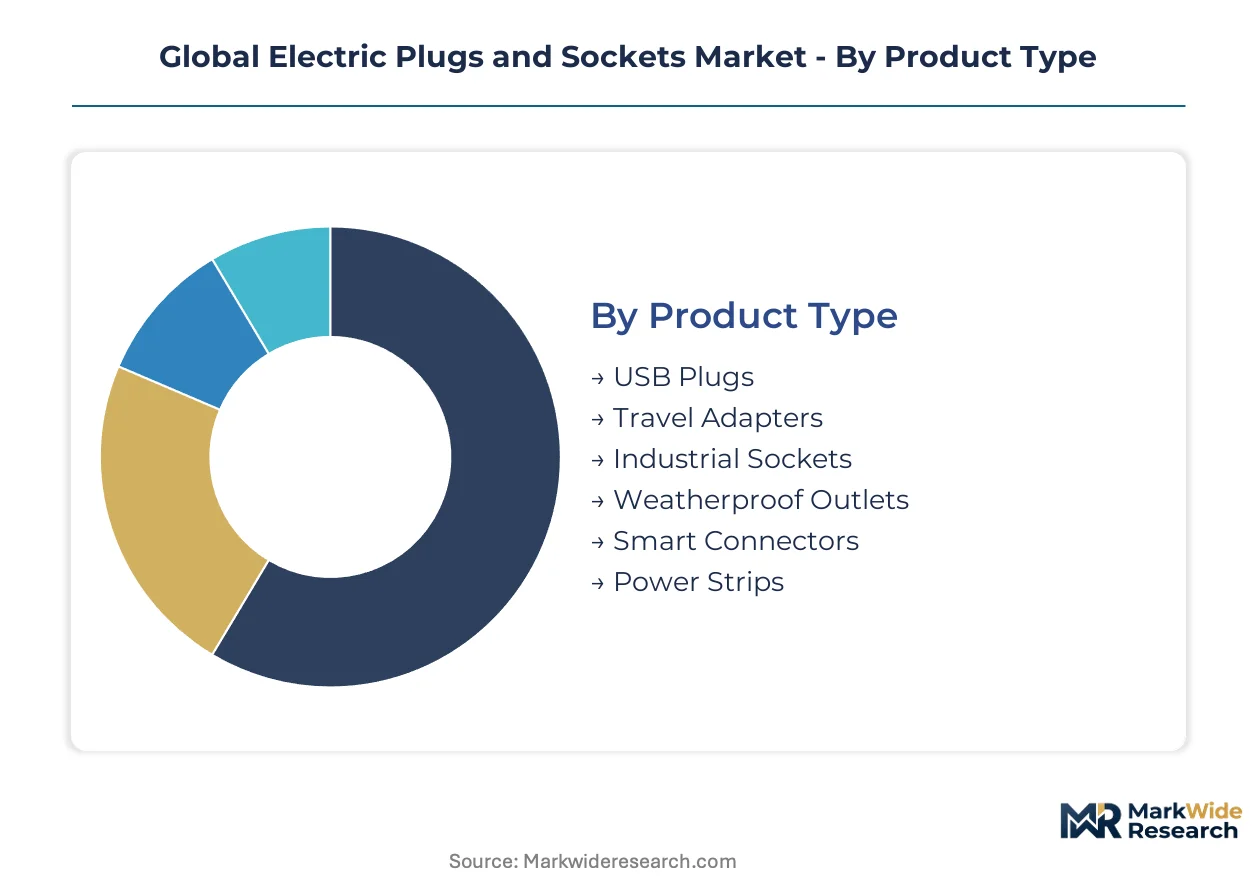
Segmentation in the electric plugs and sockets market reveals how certification burdens, connectivity integration, and end-use specialization fragment commercial opportunity. Understanding these divisions exposes where margin pools concentrate versus where volume commoditization dominates.
Product Type:
Certification requirements vary sharply across product categories, with industrial sockets demanding IP67 ratings and CE marking under the Low Voltage Directive while residential products face lighter compliance loads.
- USB Plugs:Socket-integrated USB modules deliver power delivery up to 240W under USB-C PD standards. Demand concentrates in German and Indian residential retrofit markets where wiring upgrades outpace new construction.
- Industrial Sockets:IP67-rated configurations with brass or beryllium copper contacts withstand automotive plant floor conditions. German automotive suppliers specify these for assembly line power distribution, commanding widest margin pools due to customized amperage ratings and locking mechanisms.
- Travel Adapters:Multi-standard compatibility devices serve cross-border consumer mobility with compact thermoplastic housings.
- Weatherproof Outlets:Exterior-rated polycarbonate housings resist moisture ingress for outdoor installations in coastal and industrial zones.
- Smart Connectors:Wi-Fi enabled units integrate with building management systems in North American data centers.
- Power Strips:Volume leaders in residential applications face price compression from undifferentiated producers despite surge protection integration.
Leading the category by volume: Power Strips. Growing fastest: Smart Connectors.
Technology:
Technology tiers separate connected products requiring FCC Part 15 electromagnetic compliance and EU AI Act cybersecurity audits from passive electromechanical alternatives with simpler certification paths.
- Wi-Fi Enabled:Embedded wireless modules enable remote power cycling and energy monitoring through cloud-connected firmware. FCC Part 15 governs electromagnetic emissions in the United States while EU AI Act mandates extend CE marking timelines by four to six months for European market access.
- Smart Metered:Real-time consumption tracking integrates with utility demand-response programs and corporate sustainability reporting. Data center builds in Virginia and Texas hyperscale clusters specify these for granular power allocation visibility.
- Bluetooth Integrated:Short-range connectivity supports localized control without internet dependency for hospitality venue installations.
- Surge Protection:Metal oxide varistor arrays clamp voltage transients for sensitive electronics protection.
- Modular Design:Field-configurable amperage ratings and locking mechanisms reduce inventory complexity for electrical contractors.
- Energy Efficient:Standby power minimization circuits address phantom load reduction in commercial electrical setups.
Widest certification burden: Wi-Fi Enabled. Steepest adoption climb: Smart Metered.
Application:
Application segments diverge by voltage standard, duty cycle, and integration complexity, with data centers and transport facilities imposing the most stringent performance specifications.
- Data Centers:Smart connectors with building management system APIs dominate hyperscale construction. Engineering-procurement-construction firms in Virginia and Texas mandate pre-qualified vendors with integrated power monitoring.
- Residential Wiring:USB-integrated outlets and power strips serve replacement cycles accelerated by German and Indian infrastructure upgrades. GB standard convergence in China reduces export friction for manufacturing clusters serving this volume segment.
- Commercial Electrical Setup:Modular industrial configurations address customizable power distribution for facility managers.
- Transport Facilities:Vibration-resistant locking mechanisms withstand railway and airport maintenance bay conditions.
- Hospitality Venues:Aesthetic housings with concealed mounting satisfy guest room and conference space requirements.
- Educational Institutions:Tamper-resistant shutters address safety codes for classroom and laboratory installations.
Highest specification intensity: Data Centers. Largest replacement volume: Residential Wiring.
End User:
End user categories reflect procurement authority concentration, with electrical contractors and facility managers controlling specification decisions that distributor relationships cannot easily influence.
- Electrical Contractors:Specification consolidation among EPC firms and independent contractors now mandates pre-qualified smart connector vendors. German automotive plant construction relies on these stakeholders to specify IP67-rated industrial sockets with customized locking mechanisms.
- Facility Managers:Building management system integration requirements drive connected outlet procurement for corporate and institutional portfolios. These buyers prioritize API compatibility over unit cost in North American data center and hospitality deployments.
- Retailers:Consumer-facing distribution channels move undifferentiated power strips and travel adapters with minimal technical support.
- Institutional Buyers:Public sector procurement frameworks emphasize safety certification and domestic content requirements.
- Maintenance Teams:Replacement part sourcing favors interchangeable modular designs with minimal tooling requirements.
- OEMs:Original equipment manufacturers integrate captive socket assemblies into machinery and appliance products.
Strongest specification control: Electrical Contractors. Fastest connectivity adoption: Facility Managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center construction in Virginia and Texas concentrates premium socket demand, while German automotive plants and Indian residential retrofits drive replacement cycles across distinct voltage standards.
United States
Hyperscale data center clusters in Virginia and Texas mandate pre-qualified smart connector vendors with building management system APIs. FCC Part 15 governs electromagnetic emissions for Wi-Fi enabled units. Engineering-procurement-construction firms in these states now control procurement through consolidated specification frameworks.
Germany
Automotive assembly lines in Bavaria and Baden-Württemberg specify IP67-rated industrial sockets with customized locking mechanisms. CE marking under the Low Voltage Directive shapes compliance timelines for connected outlet variants. Residential wiring upgrades in North Rhine-Westphalia accelerate replacement cycles for conventional outlets.
China
Shenzhen and Dongguan manufacturing clusters serve export markets as SAMR enforces GB standard alignment. Dual carbon goals drive energy-efficient socket specifications in commercial builds. The Yangtze River Delta concentrates polycarbonate resin compounding capacity for mid-voltage housing production.
India
Residential retrofit demand in Maharashtra and Karnataka outpaces new construction for USB-integrated outlets. BIS certification requirements compress product launch timelines for imported configurations. The Delhi-NCR corridor concentrates electrical contractor networks specifying modular industrial configurations.
Japan
Industrial automation in Aichi Prefecture pulls vibration-resistant socket configurations for robotics integration. METI efficiency standards shape standby power minimization requirements. The Osaka-Kobe manufacturing belt maintains specialized demand for high-amperage industrial connectors.
Global Electric Plugs and Sockets Market Competitive Landscape
Portfolio diversification dominates the current landscape as producers balance electromechanical reliability with software-defined power management capabilities. The vendor base separates into three tiers: integrated conglomerates with captive resin operations, specialized industrial socket fabricators, and undifferentiated residential volume producers. Strategic archetypes include certification-heavy industrial specialists, connectivity-first smart building vendors, and cost-optimized residential suppliers. M&A activity and backward integration into mold fabrication represent the dominant competitive moves.
Among European-based specialists, Mennekes Elektrotechnik GmbH & Co. KG exemplifies the industrial certification archetype, while Legrand S.A. and Schneider Electric S.A. anchor the integrated tier with diversified electromechanical portfolios. These three occupy positions spanning premium industrial specifications through mass-market residential configurations, representing distinct strategic postures toward material substitution and connectivity integration.
| Leading Market Players |
|---|
| Legrand S.A. |
| Emerson Electric Co. |
| Schneider Electric S.A. |
| TE Connectivity Ltd. |
| Amphenol Corporation |
| ABB Ltd. |
| Mennekes Elektrotechnik GmbH & Co. KG |
| Gewiss S.p.A. |
| Eaton Corporation plc |
| Others |
Supply & Pricing Matrix
Mold fabrication specialists concentrated in Dongguan and Shenzhen compress labor-cost differentials into pricing-tier spreads across industrial socket configurations. Chinese resin compounding clusters feed polycarbonate formulations that separate premium IP67-rated housings from economy-grade thermoplastic alternatives.
Pricing Analysis
The volume-mass split separates commodity power strips from industrial sockets with customized amperage ratings. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale. Price erosion runs through undifferentiated residential segments as polycarbonate achieves bakelite-equivalent dielectric performance at lower unit cost. Electrical contractors exhibit highest price sensitivity in power strip procurement, while data center EPC firms prioritize API compatibility over unit cost.
Supply Chain Analysis
Freight cost volatility from Asia-Europe lanes compresses margin stability for export-bound manufacturers serving German automotive specifications. Supply concentrates in China, Germany, and India for resin compounding, mold fabrication, and contact material finishing respectively. Raw material dependencies center on brass and beryllium copper for conductive elements, polycarbonate resin for housings, and metal oxide varistors for surge protection arrays. Single-source vulnerability in specialized IP67 certification infrastructure constrains industrial socket capacity expansion. Distribution runs through electrical contractor networks and EPC firm pre-qualification frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as IEC 60884-1 harmonization and cybersecurity compliance burdens force undifferentiated producers toward exit or acquisition.
For Market Incumbents: Acquire captive mold fabrication capacity to compress product variant launch timelines for region-specific voltage standards. Schneider Electric S.A. and Legrand S.A. anchor this posture through in-house tooling. Defend margin pools by deepening IP67 certification infrastructure against emerging connectivity-first entrants. Threat substitution from software-defined power management capabilities demands firmware audit protocol investment.
For New Entrants and Emerging Players: Enter via USB-C PD-integrated residential retrofit sockets in Maharashtra and Karnataka where Indian wiring upgrades outpace new construction. Target modular industrial configurations for German automotive plant specifications as Mennekes Elektrotechnik GmbH & Co. KG leaves white space below premium positioning. Go-to-market angle: BIS certification acceleration through Delhi-NCR electrical contractor networks.
For Investors and Strategic Acquirers: Re-rating potential sits with industrial socket specialists possessing IP67 infrastructure given EU AI Act cybersecurity timeline extensions. Long-term viability favors producers bridging electromechanical reliability with building management system API integration. Acquisition target archetype: mid-tier mold fabricators with CE marking acceleration capabilities. Signal to watch: EPC firm pre-qualification consolidation in Virginia and Texas hyperscale clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Schneider Electric S.A. stabilizes polycarbonate input costs across European distribution channels. |
| CE Marking Acceleration | Low Voltage Directive streamlining offers German automotive suppliers faster market access timelines. |
| Modular Industrial Configuration Development | Customizable amperage ratings address Bavarian plant specifications without full redesign cycles. |
| Building Management System API Integration | Wi-Fi enabled units penetrate Virginia and Texas data center construction mandates. |
| Cybersecurity Compliance Infrastructure Buildout | Firmware audit protocols absorb EU AI Act burdens more efficiently than residential-focused competitors. |
Research Methodology
SEC 10-K filings, customs and trade databases, and IEC technical committee documentation formed the secondary backbone for this analysis. Primary interviews with electrical contractor specification leads, EPC firm procurement officers, resin compounding plant managers, and industrial socket certification engineers validated demand assumptions. Bottom-up triangulation across product type volumes and top-down cross-check against regional construction activity anchored forecast integrity.
Historical trendline analysis of replacement cycle patterns and material substitution rates informed the projection framework. Segmentation dimensions modeled include product type, connectivity technology tier, application voltage standard, and end-user procurement authority. CAGRs derived from fitted growth curves adjusted for regulatory harmonization pace and copper price volatility assumptions. Industry-specific inputs encompassed German automotive plant construction pipelines and Indian residential retrofit permit data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper commodity spikes and cybersecurity mandate divergence scenarios. Forecasts reflect documented assumptions regarding IEC harmonization pace and GB standard convergence timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Waveguide Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Europe Circuit Breakers Market