
 Flexible Heating Element Market | 2026-2036
Flexible Heating Element Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Heating Element Market Analysis
OEM-direct supply contracts is rewriting procurement economics for flexible heating elements. Watlow leverages its vertical integration across sensor and heater manufacturing to sustain price competitiveness in North American industrial accounts. Chromalox dominates high-temperature alloy-based flexible heaters for chemical processing, while NIBE Element anchors European residential and commercial HVAC applications through specialized distribution partnerships.
Flexible heating elements are thin, conformable thermal devices constructed from etched metal foil, printed conductive inks, or woven carbon fiber matrices laminated between polymer substrates such as silicone, polyimide, or Kapton, engineered to deliver precise watt densities from 2.5 W/cm² to 50 W/cm² across irregular surfaces. These components serve critical functions in thermal management, freeze protection, and process heating where rigid heating solutions cannot conform to complex geometries. Silicone-based flexible heaters lead volume shipments due to their cost position and moisture resistance in industrial environments, while polyimide and Kapton variants command premium positioning in aerospace and medical devices where weight reduction and dielectric strength are paramount. Infrared technology competes aggressively in automotive interior comfort applications, whereas resistance heating sustains its installed base across food processing equipment where precise temperature uniformity remains essential.
FDA 21 CFR Part 820 quality system requirements govern medical device heating element validation, while EPA TSCA Section 6 restrictions on perfluoroalkyl substances are forcing substrate reformulation across US-sourced products. ECHA REACH Annex XVII substance restrictions and the EU MDR compliance timeline are elevating documentation burdens for European medical and industrial suppliers. Stakeholders must monitor evolving fluoropolymer substitution pathways and automotive electrification thermal architectures to align R&D portfolios with emerging specification requirements.
Market Dynamics
Automotive electrification is compressing thermal management specifications across OEM supply chains, forcing substrate suppliers to reconcile legacy silicone formulations with fluoropolymer-free alternatives mandated by EU F-Gas Regulation and REACH Annex XVII substance restrictions.
Growth Catalysts
- Battery Thermal Management:Electric vehicle OEMs in Germany, China, and the United States are embedding flexible heating elements into pack conditioning systems to maintain optimal operating temperatures across climate zones.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based substrates is redirecting R&D investment toward silicone and polyimide alternatives with equivalent dielectric performance.
- Medical Device Integration:Patient warming systems and diagnostic equipment manufacturers are specifying polyimide heaters for their weight reduction and precise watt density control in portable applications.
Market Restraints
- Raw Material Concentration:High-purity silicone rubber supply concentrates among specialty chemical producers in Germany and Japan, creating input cost volatility during energy price spikes.
- Technical Performance Ceiling:Silicone-based flexible heaters face maximum operating temperature limitations around 260°C that restrict deployment in aerospace engine proximity applications.
- Substitution by Infrared:Carbon fiber infrared panels are capturing automotive interior comfort applications where rapid surface heating outweighs conformability requirements.
Strategic Opportunities
- Indian Manufacturing Localization:BIS certification requirements and PLI scheme incentives for medical device production are creating captive demand for domestic flexible heater assembly capacity.
- Wearable Medical Devices:Flexible heating elements integrated into therapeutic garments and drug delivery patches represent underpenetrated application space with distinct form factor requirements.
- Printed Electronics Convergence:Screen-printed conductive ink heaters on biodegradable substrates are opening sustainability-positioned product lines for single-use medical applications.
Industry Challenges
- Fluoropolymer Substitution Chemistry:Reformulating polyimide and Kapton substrates to eliminate perfluoroalkyl substances while maintaining dielectric strength and thermal stability requires extended validation cycles with automotive and medical OEMs.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with FDA 21 CFR Part 820, EU MDR technical documentation requirements, and ECHA REACH substance notifications extends product launch timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Heating Element Market |
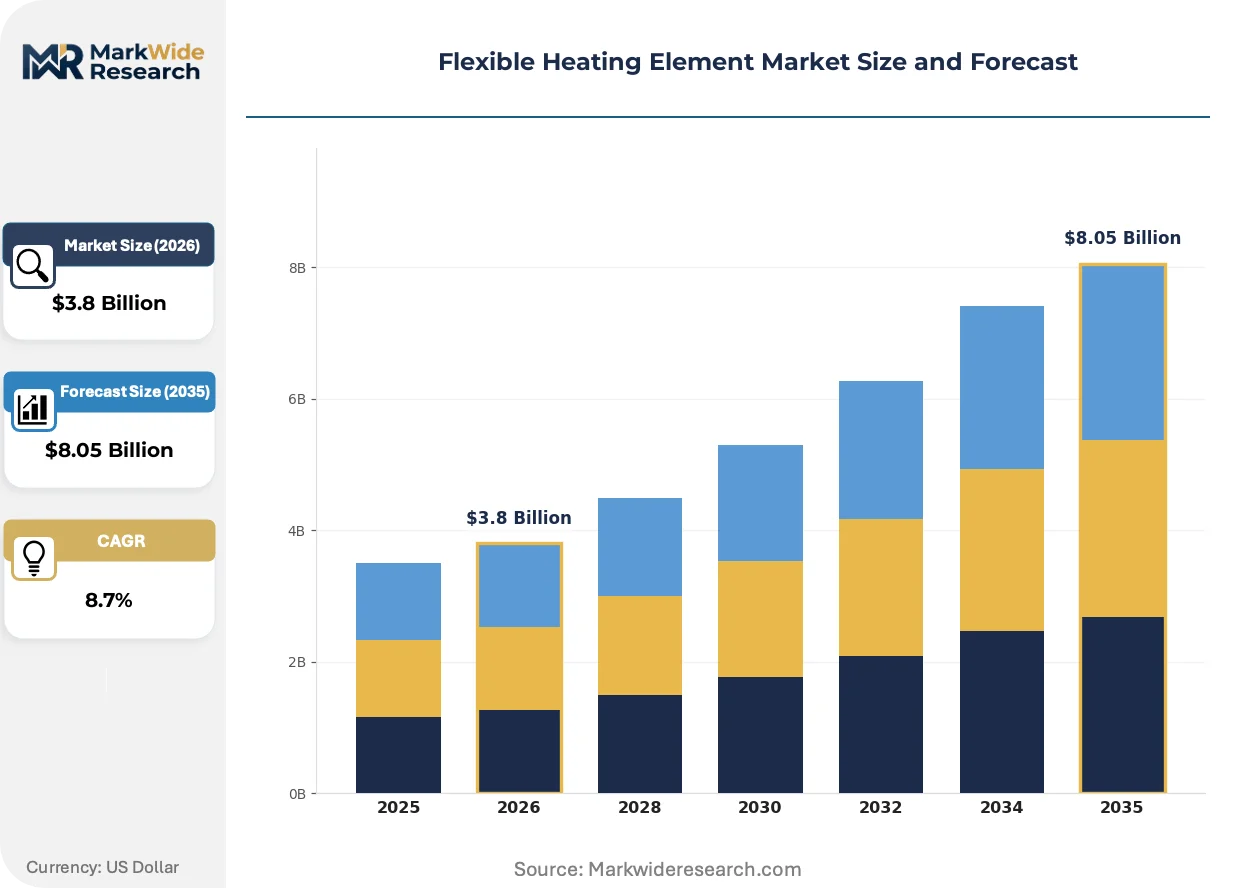
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyimide, Kapton, Carbon Fiber Technology: Infrared, Resistance, Induction, Microwave Application: Automotive, Aerospace, Medical Devices, Food Processing End User: Manufacturers, Contractors, Consumers, Retailers |
| Companies Covered | NIBE Element, Watlow, Honeywell, Chromalox, Minco, Winkler GmbH, OMEGA, Friedr. Freek GmbH, Durex Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Heating Element Market Emerging Trajectories
Digital twin integration is virtualizing heater design workflows, compressing prototype iterations while regulatory chemistry constraints are forcing material science breakthroughs in substrate formulation.
Printed conductive ink technology is virtualizing traditional etched-foil manufacturing for low-wattage applications. Medical device OEMs are adopting screen-printed silver and carbon formulations for disposable diagnostic cartridges. This shift is virtualizing capital equipment requirements for entry-level production while enabling rapid design iteration cycles.
EPA TSCA Section 6 restrictions on perfluoroalkyl substances are forcing substrate reformulation across US-sourced products. Industrial and medical suppliers must document alternative chemistries through extended validation protocols. The automotive segment is responding fastest, with Tier-1 suppliers accelerating silicone-dominant specifications ahead of enforcement timelines.
Direct OEM contracting is displacing distributor-mediated procurement in high-volume automotive and medical accounts. Buyers are consolidating supplier panels to capture volume pricing and co-development access. This pattern is most visible in Germany and the United States, where seat heating and battery thermal management procurement teams maintain dedicated commodity management functions.
Flexible Heating Element Market Segmentation
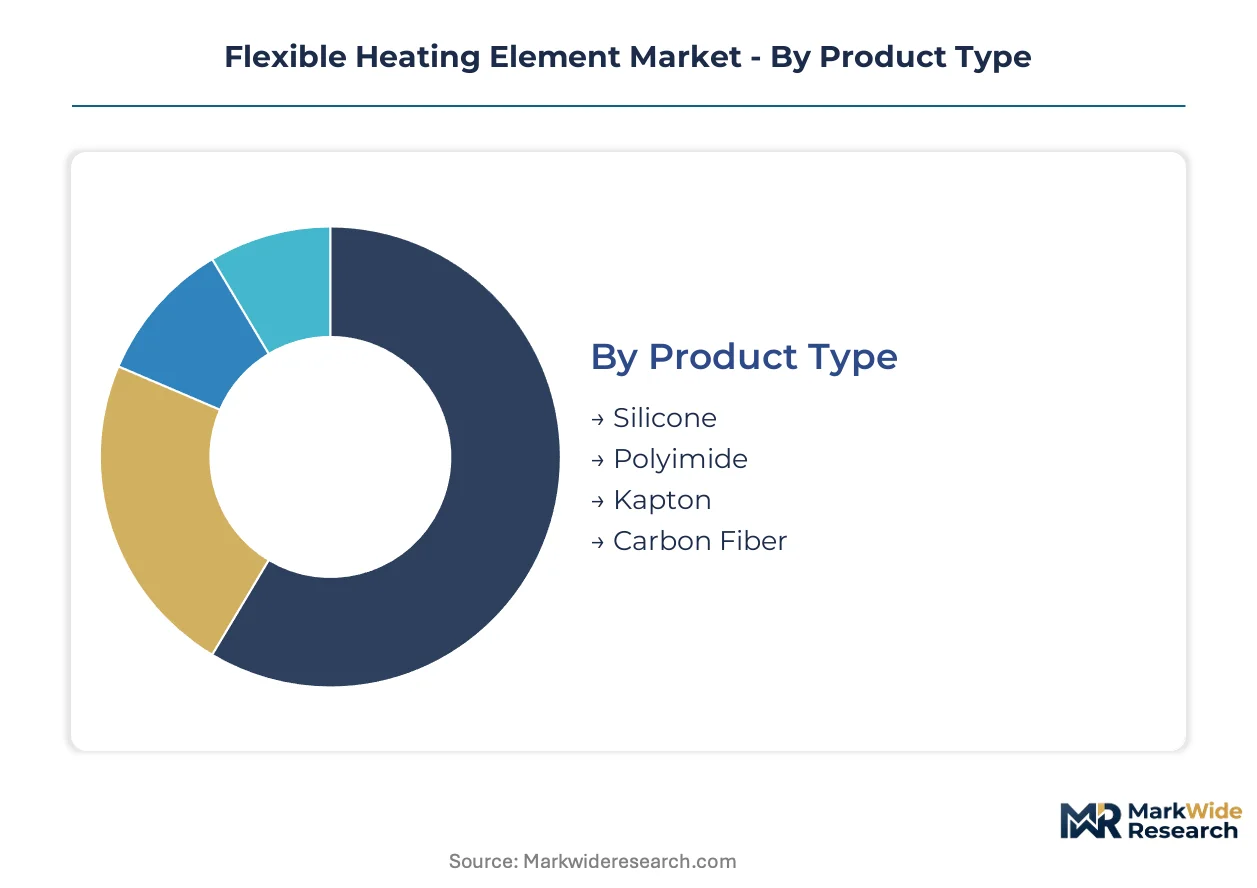
Flexible heating element procurement varies dramatically by segment cycle time, with automotive programs refreshing every 3-4 years while medical device platforms extend to 7-10 years. Understanding these velocity differentials enables suppliers to align inventory and R&D investment with segment-specific refresh patterns.
Product Type:
Silicone heaters turn inventory fastest due to broad industrial applicability, while Kapton variants move slowest given aerospace validation requirements.
- Silicone:Elastomer substrates laminated with etched nickel-chrome or copper-nickel foils deliver moisture resistance and flexibility across -60°C to 260°C operating ranges. Demand concentrates in German automotive OEM battery thermal management systems where EU F-Gas Regulation compliance is compressing substrate selection timelines.
- Polyimide:Thin-film constructions achieve dielectric strength above 3000 V/mil with thickness below 0.2mm, enabling precise watt density control in portable medical equipment. Chinese diagnostic device manufacturers specify polyimide for patient warming systems in climate-variable provinces.
- Kapton:DuPont-derived polyimide formulations serve aerospace engine proximity applications requiring radiation resistance and outgassing control per NASA specifications.
- Carbon Fiber:Woven conductive matrices enable rapid surface heating for automotive interior comfort systems competing against resistance-based alternatives.
Silicone anchors the volume base while carbon fiber gains share at the steepest rate.
Technology:
Cost tiers separate technologies sharply, with resistance heating occupying the economy position and induction commanding premium pricing for specialized industrial applications.
- Infrared:Carbon fiber and ceramic emitter panels deliver radiant heat without direct surface contact, capturing automotive seat comfort applications where rapid warm-up outweighs conformability needs. US-based Tier-1 suppliers are accelerating infrared specifications ahead of EPA TSCA Section 6 enforcement timelines for fluoropolymer-free substrates.
- Resistance:Etched metal foil and printed conductive ink configurations sustain installed base across food processing equipment where temperature uniformity within ±1°C remains critical for safety validation.
- Induction:Electromagnetic field coupling enables non-contact heating of metallic components in high-throughput manufacturing lines.
- Microwave:Dielectric heating mechanisms serve niche applications in laboratory and specialized industrial processing environments.
Resistance technology commands the widest installed base, though infrared applications are expanding most quickly in automotive comfort systems.
Application:
Customer concentration varies by application maturity, with automotive consolidating around fewer OEM-direct contracts while food processing retains fragmented procurement patterns.
- Automotive:Battery thermal management and seat heating systems embed flexible heaters directly into OEM platforms, with Germany, China, and the United States anchoring specification authority. ECHA REACH Annex XVII substance restrictions are forcing substrate reformulation across European supply chains.
- Aerospace:Weight-critical applications in satellite and aircraft systems specify polyimide and Kapton variants with radiation-hardened characteristics.
- Medical Devices:FDA 21 CFR Part 820 quality system requirements govern validation protocols for patient warming and diagnostic equipment heating elements.
- Food Processing:Stainless steel-sheathed resistance heaters maintain precise temperature control across conveyor ovens and holding equipment.
Automotive applications concentrate procurement volume while medical devices offer the steepest margin expansion trajectory.
End User:
Volume scale separates end user tiers, with manufacturers capturing multi-year supply agreements while retailers operate on spot purchasing terms.
- Manufacturers:Automotive OEMs and medical device producers negotiate multi-year supply agreements with technical co-development clauses, consolidating supplier panels to capture volume pricing.
- Contractors:Industrial installation and maintenance providers source flexible heaters for HVAC and process equipment retrofit applications.
- Consumers:Direct-to-user sales concentrate in heated apparel and therapeutic device segments through e-commerce channels.
- Retailers:Distributors and specialty equipment resellers maintain inventory for immediate replacement demand in industrial maintenance contexts.
Manufacturers anchor the revenue base while consumer channels are climbing the fastest as wearable therapeutic applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs extract pricing premiums through technical co-development clauses, while Chinese battery manufacturers compress supplier margins through volume consolidation tactics. This asymmetry shapes procurement economics across the flexible heating element supply base.
United States
Electric vehicle battery thermal management and medical device patient warming systems drive procurement volumes from Detroit automotive clusters and Minneapolis medical technology corridors. EPA TSCA Section 6 restrictions on perfluoroalkyl substances are forcing substrate reformulation timelines ahead of enforcement dates. Michigan-based Tier-1 suppliers are accelerating silicone-dominant specifications to preempt compliance costs.
Germany
Seat heating platforms and industrial process equipment anchor demand from Stuttgart automotive OEMs and Cologne chemical processing clusters. ECHA REACH Annex XVII substance restrictions and the EU F-Gas Regulation are compressing fluoropolymer-free substrate selection windows. Bavarian industrial heater fabricators are consolidating supplier panels to capture volume pricing through multi-year agreements.
China
Domestic electric vehicle production and diagnostic device manufacturing concentrate procurement in Shanghai battery pack facilities and Shenzhen medical electronics corridors. MIIT dual carbon goals and GB standards for automotive thermal management are elevating domestic content requirements. Yangtze River Delta heater assemblers are expanding capacity to serve local OEM qualification programs.
Japan
Precision industrial equipment and aerospace satellite systems sustain demand from Nagoya manufacturing clusters and Tokyo aerospace corridors. METI energy efficiency mandates and JIS standards for industrial heating equipment are tightening thermal performance specifications. Osaka-based specialty chemical producers control high-purity silicone rubber supply for regional heater manufacturers.
India
Medical device manufacturing incentives and automotive component localization are emerging demand centers from Maharashtra pharmaceutical clusters and Tamil Nadu automotive corridors. BIS certification requirements and PLI scheme incentives for medical device production are creating captive demand for domestic flexible heater assembly capacity. Gujarat chemical processing facilities are qualifying local substrate suppliers for industrial applications.
Flexible Heating Element Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and sensor supply. The vendor base organizes around three tiers: multinational thermal platform providers with automotive and medical OEM direct contracts; regional fabricators serving industrial maintenance and retrofit channels; and specialty chemical suppliers controlling high-purity silicone and polyimide substrate formulations. Competitive moves concentrate on backward integration into sensor manufacturing and geographic expansion through distribution partnerships in emerging manufacturing corridors.
Among European-based thermal platform providers, NIBE Element occupies a position within the residential and commercial HVAC tier through specialized distribution partnerships. Watlow represents the vertically integrated archetype spanning sensor and heater manufacturing for North American industrial accounts. Chromalox exemplifies the high-temperature alloy specialist segment serving chemical processing applications. These three anchors illustrate how procurement consolidation around OEM-direct contracts is reshaping competitive positioning across the supply base.
| Leading Market Players |
|---|
| NIBE Element |
| Watlow |
| Honeywell |
| Chromalox |
| Minco |
| Winkler GmbH |
| OMEGA |
| Friedr. Freek GmbH |
| Durex Industries |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII substance restrictions on fluoropolymers compress both substrate selection timelines and tier spreads, forcing buyers into premium silicone specifications while squeezing mid-market polyimide alternatives out of European automotive procurement.
Pricing Analysis
Configured-to-order pricing for medical-grade polyimide heaters commands spreads against standard silicone industrial variants. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical devices from industrial maintenance stock and consumer wearable imports. Cost compression in standard silicone grades intensifies as Chinese battery manufacturers consolidate procurement panels. Automotive OEMs exhibit lowest price sensitivity due to co-development clauses, while industrial contractors face acute margin pressure from spot purchasing terms.
Supply Chain Analysis
Export-control regimes on high-purity silicone rubber precursors limit flows from German and Japanese specialty chemical producers to regional heater fabricators. Supply concentrates in Germany for automotive-qualified substrates, China for battery pack assembly components, and Japan for aerospace-grade polyimide formulations. Raw material dependencies center on nickel-chrome resistance alloys, silver conductive inks, and fluoropolymer-free laminates. Single-source vulnerability runs through Osaka-based silicone rubber suppliers controlling regional chemical synthesis. Distribution runs through OEM-direct contracts for automotive and medical volumes, with industrial retrofit channels served by distributor inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery thermal management adoption in electric vehicles represents an early-cycle expansion tailwind, with OEM platform integration still penetrating below half of addressable pack architectures.
For Market Incumbents: Harden supply positions through backward integration into sensor manufacturing and captive silicone rubber compounding capacity in Germany or Japan. Chromalox and Watlow anchor defensive moats via high-temperature alloy specialization and North American vertical control. Carbon fiber infrared substitution in automotive comfort systems threatens resistance-based heater incumbents who delay fluoropolymer-free substrate qualification. For New Entrants and Emerging Players: Establish a beachhead in Indian medical device manufacturing corridors where BIS certification and PLI scheme incentives create captive demand for domestic flexible heater assembly. Printed conductive ink technology on biodegradable substrates offers the most penetrable white-space for single-use diagnostic applications. Target therapeutic garment OEMs through rapid prototyping partnerships with wearable device designers. For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown deadlines reshape the acquisition landscape toward suppliers with validated silicone-dominant portfolios and automotive OEM direct contracts. Long-term viability hinges on substrate chemistry transition completion within the next development cycle. Signal to watch: acceleration of fluoropolymer-free validation timelines at Tier-1 automotive suppliers as enforcement dates approach.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer-Free Substrate Qualification | REACH Annex XVII compliance enables continued European automotive OEM supply access. |
| Battery Thermal Management Partnership | Direct OEM contracts with German or Chinese electric vehicle manufacturers anchor volume. |
| Medical Device FDA Validation Investment | 21 CFR Part 820 quality system certification opens patient warming system procurement. |
| Indian Manufacturing Localization | BIS certification and PLI scheme incentives capture medical device assembly demand. |
| Printed Electronics Capability Buildout | Screen-printed conductive ink technology serves disposable diagnostic cartridge specifications. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with thermal platform engineering directors, automotive Tier-1 procurement managers, medical device regulatory affairs leads, and specialty chemical R&D directors; and secondary validation through ECHA REACH substance restriction filings, EPA TSCA Section 6 enforcement timelines, FDA 510(k) heating element clearances, and customs trade data on silicone rubber precursor flows. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Forecast inputs considered battery pack thermal management penetration rates, medical device platform refresh cycles, and fluoropolymer substitution chemistry validation timelines across the analysis window. Segmentation dimensions modeled include substrate material grade, heating technology type, application end-use, and regional regulatory cluster. CAGRs derived from weighted scenario analysis across OEM electrification roadmaps and compliance enforcement schedules.
Stress conditions across raw material cost volatility, REACH enforcement acceleration, and battery thermal management specification changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on OEM platform adoption curves and regulatory phasedown timelines. Material shifts in fluoropolymer substitution chemistry breakthroughs or sudden EPA enforcement acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
North America Electrical Bushing Market