
 Industrial Paint Booth Market | 2026-2036
Industrial Paint Booth Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Paint Booth Market Outlook
Automation integration with real-time airflow monitoring and robotic spray coordination is reshaping industrial paint booth architecture. Dürr AG leverages its robotics heritage to anchor premium automated finishing lines across European automotive plants. Eisenmann SE sustains engineering intensity in thermal process integration for heavy machinery applications. Global Finishing Solutions dominates the North American aftermarket through extensive distributor control and rapid field service deployment.
An industrial paint booth is an enclosed, ventilated chamber engineered to capture overspray, filter particulate emissions, and maintain controlled temperature and humidity for surface coating operations, typically achieving air velocities between 50 and 150 feet per minute depending on configuration. Downdraft designs command the highest capital allocation due to superior finish quality and worker safety profiles, while crossdraft systems retain volume leadership in budget-constrained refurbishment environments. Waterborne technology segments are capturing disproportionate investment as manufacturers phase out solvent-based systems under tightening environmental mandates.
The EPA enforces National Emission Standards for Hazardous Air Pollutants for surface coating operations, compelling booth operators to upgrade filtration and capture efficiency. OSHA ventilation requirements and the EU F-Gas Regulation jointly elevate capital costs for cross-border equipment suppliers while creating specification divergence between American and European procurement standards. Stakeholders must monitor regulatory calibration timelines to sequence R&D spending and inventory positioning ahead of compliance phase-ins.
Market Dynamics
Waterborne coating conversions are compressing replacement cycles across automotive and heavy machinery sectors, forcing booth operators to retool ventilation and filtration architectures ahead of compliance deadlines. This technology migration concentrates capital deployment in manufacturing hubs with the strictest emission enforcement timelines.
Growth Catalysts
- EPA NESHAP mandates:Surface coating operations face escalating capture efficiency requirements that accelerate booth refurbishment investments across US automotive OEM facilities.
- Robotic spray coordination:Automotive plants in Germany and China integrate real-time airflow monitoring with robotic arms to reduce material waste and improve finish consistency.
- Heavy machinery thermal processes:Eisenmann SE's engineering intensity in heat recovery systems pulls demand for integrated booth-oven configurations in agricultural and construction equipment manufacturing.
Market Restraints
- Steel and aluminum price volatility:Booth enclosure fabrication costs fluctuate with base metal commodity markets, compressing margin visibility for European fabricators.
- Filtration media supply concentration:High-efficiency particulate filters for VOC capture depend on a limited supplier base concentrated in Germany and Japan.
- Cross-border specification divergence:OSHA ventilation standards and EU F-Gas Regulation create incompatible technical requirements that fragment equipment design economies.
Strategic Opportunities
- India automotive manufacturing corridors:Tamil Nadu and Gujarat state industrial zones lack modern finishing infrastructure as passenger vehicle production scales.
- Aviation MRO aftermarket:Aircraft repaint cycles compress with rising fleet utilization, creating demand for portable booth configurations at regional maintenance hubs.
- EU Green Deal industrial renovation funding:Decarbonization grants for manufacturing SMEs subsidize solvent-to-waterborne conversion investments in Italian and Polish coating shops.
Industry Challenges
- Certified booth technician scarcity:HVAC-balancing and filtration-system commissioning require specialized skills that outpace vocational training program output in Midwestern US manufacturing regions.
- Legacy crossdraft retrofit complexity:Existing budget-constrained facilities face structural constraints when upgrading to downdraft airflow patterns without full reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Paint Booth Market |
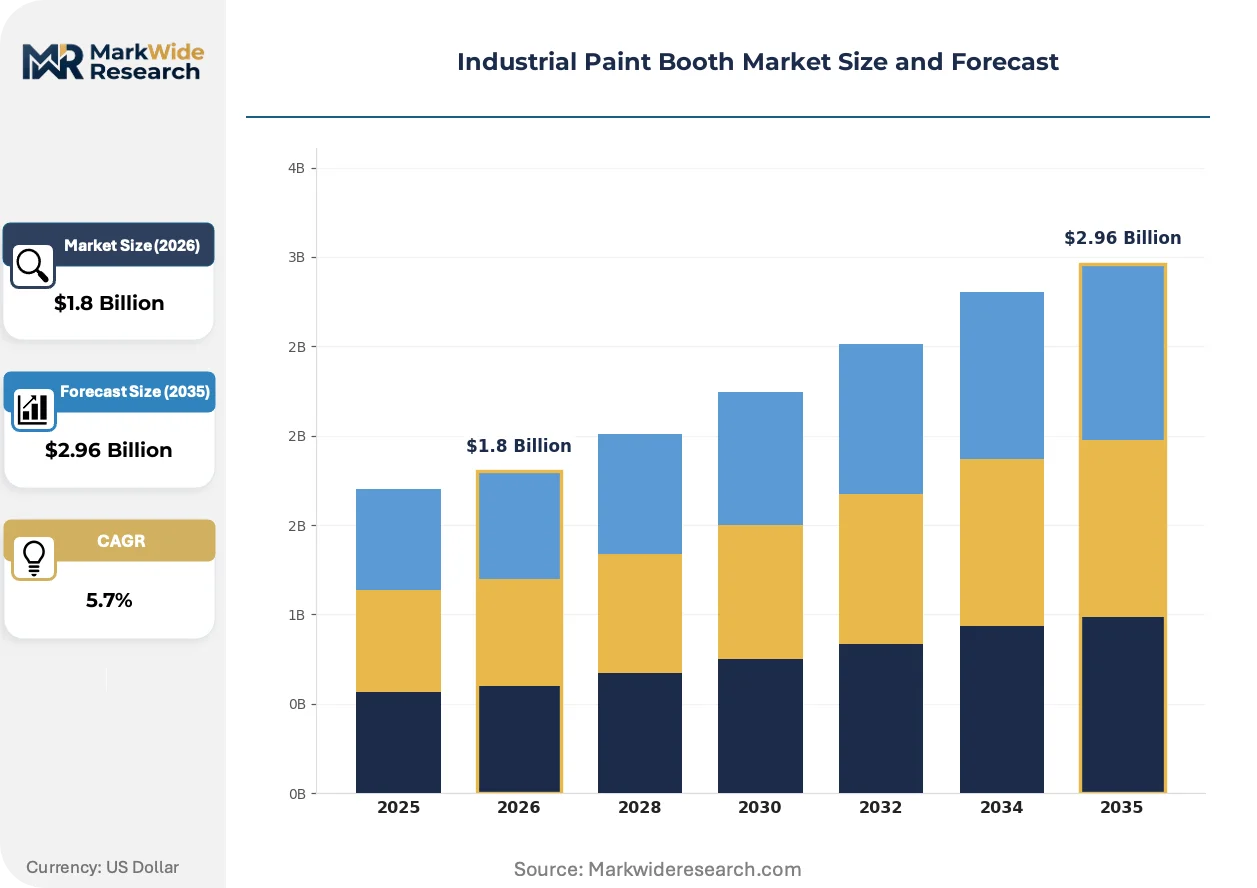
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crossdraft, Downdraft, Side Downdraft, Open Face Technology: Waterborne, Solvent-Based, UV-Cured, Powder Coating Application: Aerospace, Automotive OEMs, Furniture Manufacturing, Heavy Machinery End User: Manufacturers, Tier-1 Suppliers, Contract Assemblers, Refurbishing Centers |
| Companies Covered | Global Finishing Solutions, Accudraft, Eisenmann SE, Dürr AG, Blowtherm, Col-Met Engineered Finishing Solutions, Spray Systems Inc., Nova Verta International, Dalby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Paint Booth Market Strategic Shifts
Digital twin architectures are penetrating industrial finishing operations, enabling predictive maintenance and airflow optimization before physical commissioning. This convergence compresses design-validation cycles and reduces field rework for complex multi-zone booth installations.
Computational fluid dynamics software is virtualizing airflow pattern design for downdraft and crossdraft configurations, allowing engineers to model particulate capture efficiency and temperature uniformity before steel fabrication. Tier-one automotive OEMs in Germany and the United States deploy these simulations to de-risk custom booth specifications for multi-model paint lines. The technology is virtualizing traditional physical prototyping, cutting commissioning timelines and reducing costly field adjustments.
REACH authorization timelines for chromium-based corrosion inhibitors are forcing coating formulators toward alternative pretreatment chemistries that demand modified booth humidity controls and flash-off zone configurations. Automotive OEM supply chains in the EU face reformulation costs that cascade into booth specification changes for waterborne basecoat compatibility. Heavy machinery manufacturers serving EU export markets pre-emptively adopt these architectures to maintain single-platform production.
Aftermarket service unbundling is fragmenting traditional bundled maintenance contracts as fleet operators seek discrete filtration media replacement and airflow certification services. North American distributor networks respond with rapid-deployment field teams that bypass original equipment manufacturer service hierarchies. Independent body shops and regional MRO facilities drive this preference for transactional, response-time-guaranteed support over comprehensive multi-year agreements.
Industrial Paint Booth Market Segmentation
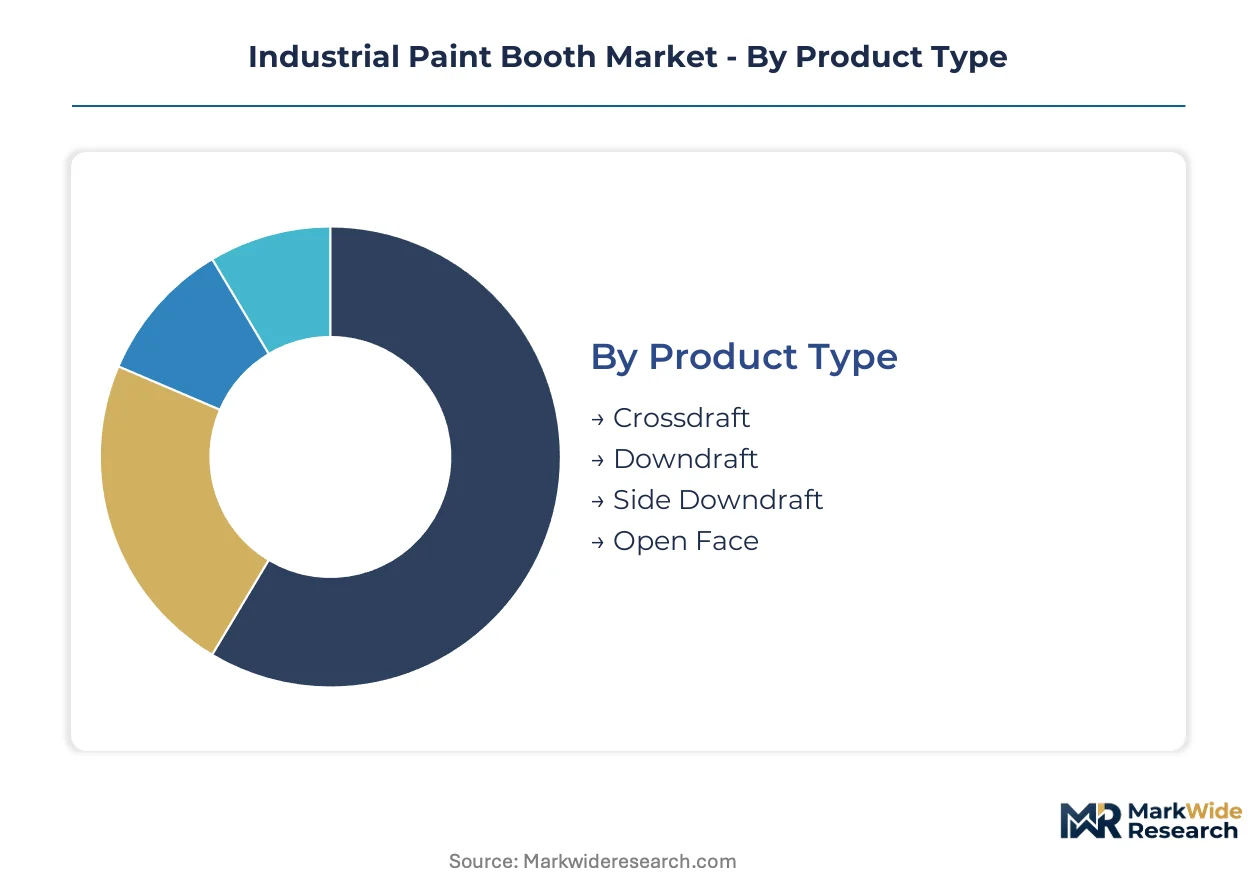
Paint booth segmentation reveals divergent capital cycles across equipment configurations and coating chemistries. Replacement timelines stretch from 15-20 years for structural enclosures to 3-5 years for filtration and control systems, creating layered revenue streams for suppliers.
Product Type:
Downdraft systems command the longest replacement cycles due to structural permanence, while open-face configurations turn over fastest as shops upgrade to enclosed, compliant architectures.
- Downdraft:Ceiling-mounted supply plenums drive airflow vertically through the work zone and into floor-level exhaust trenches, capturing overspray beneath the vehicle or component. German automotive OEMs specify these for multi-model paint lines where finish quality variance must stay below 5% across color changes. EPA NESHAP mandates on VOC capture efficiency are accelerating conversions from legacy configurations in Michigan and Ohio assembly plants.
- Crossdraft:Horizontal airflow patterns pull air across the booth width through filtered wall openings, requiring lower capital outlay but producing more turbulent overspray distribution. Budget-constrained refurbishing centers in Poland and Mexico retain these for single-color production runs where throughput speed outweighs finish perfection.
- Side Downdraft:Air enters through ceiling slots and exhausts through side-wall grilles, splitting the pressure differential to reduce floor trench construction costs. Furniture manufacturers in North Carolina deploy these for oversized cabinet and fixture finishing where floor pits would obstruct material handling.
- Open Face:Unenclosed or partially enclosed configurations rely on peripheral exhaust capture without controlled airflow patterns. Small-batch custom coaters in Italy use these for prototype and artisan work where regulatory enforcement remains uneven.
Downdraft dominates installed base value. Crossdraft is where expansion concentrates in emerging manufacturing corridors.
Technology:
Capital allocation splits between compliance-driven waterborne conversions and efficiency-seeking UV installations, with solvent-based systems entering managed decline.
- Waterborne:Basecoat and clearcoat formulations use water as the primary carrier solvent, requiring humidity-controlled flash-off zones and modified ventilation rates. China's MIIT emission standards and the EU F-Gas Regulation are forcing simultaneous booth architecture changes across Shanghai and Stuttgart automotive clusters.
- Solvent-Based:Traditional organic solvent carriers deliver faster drying and superior metallic flake orientation but face REACH authorization restrictions and EPA hazardous air pollutant limits. Heavy machinery exporters in India pre-emptively phase these out to maintain EU market access.
- UV-Cured:Photoinitiator-activated coatings polymerize instantly under ultraviolet lamps, eliminating thermal ovens and compressing line footprint. Flat-panel furniture producers in Vietnam adopt these for high-speed linear finishing where substrate geometry permits uniform lamp exposure.
- Powder Coating:Electrostatically charged thermoset particles fuse to grounded substrates in heated cure ovens, generating zero liquid waste. Agricultural equipment manufacturers in Iowa specify these for frame and implement finishing where chip resistance outweighs color complexity.
Solvent-based retains volume leadership in installed base. Waterborne is gaining share fastest as regulatory phase-ins synchronize across major manufacturing hubs.
Application:
Segment maturity varies sharply: automotive OEMs run continuous replacement programs while aerospace follows aircraft fleet cycles with decade-long intervals.
- Automotive OEMs:Original equipment manufacturers operate integrated paint shops with robotic spray zones, automated conveyor systems, and real-time quality monitoring. Tesla's Berlin and Austin facilities deploy Dürr AG finishing lines with digital twin commissioning to compress ramp-up timelines.
- Heavy Machinery:Agricultural and construction equipment requires oversized booths for frames, booms, and castings with thermal integration for post-paint baking. Eisenmann SE anchors this segment with heat recovery systems that cut energy intensity for Caterpillar and Komatsu suppliers.
- Aerospace:Aircraft repaint cycles follow MRO schedules with stringent FAA and EASA substrate preparation standards. Regional hubs in Singapore and Dubai lack sufficient booth capacity as fleet utilization rebounds.
- Furniture Manufacturing:Flat-panel and case goods producers prioritize throughput over finish complexity, favoring crossdraft and open-face configurations. North Carolina and Guangdong clusters drive replacement demand as labor costs shift automation priorities.
Automotive OEMs dominate capital deployment. Aerospace is where capacity expansion concentrates as MRO infrastructure lags fleet growth.
End User:
Procurement authority fragments across captive manufacturers and independent service providers with divergent specification sophistication.
- Manufacturers:Captive finishing operations at OEMs and large Tier-1s specify integrated lines with 15-20 year depreciation horizons. Volkswagen Group's Wolfsburg and Chattanooga plants standardize on Dürr AG architectures with unified control platforms.
- Tier-1 Suppliers:Component specialists like Magna and Faurecia operate satellite paint shops with OEM-mandated process conformity. These facilities face compressed upgrade cycles as platform specifications evolve.
- Contract Assemblers:Third-party finishers serve multiple OEMs with flexible batch configurations and rapid color change capability. Mexican border maquiladoras cluster these operations to serve US automotive demand.
- Refurbishing Centers:Collision repair and industrial recoating shops prioritize transactional equipment relationships and rapid field service response. Global Finishing Solutions' North American distributor network captures this preference with unbundled maintenance offerings.
Manufacturers dominate specification authority. Contract assemblers is where vendor switching concentrates as margin pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German paint booth exports supply automotive assembly plants across Central Europe and North America, with waterborne conversion mandates synchronizing replacement cycles across buyer geographies.
United States
EPA NESHAP mandates on VOC capture efficiency accelerate booth refurbishment investments across Michigan and Ohio automotive clusters. OSHA ventilation standards elevate capital costs for cross-border equipment suppliers. Tesla's Austin facility deploys integrated finishing lines with digital twin commissioning to compress ramp-up timelines.
Germany
EU F-Gas Regulation and REACH authorization timelines force coating formulators toward alternative pretreatment chemistries demanding modified booth humidity controls. Volkswagen Group's Wolfsburg plant standardizes on unified control platforms across captive finishing operations. Stuttgart automotive clusters synchronize waterborne basecoat compatibility specifications with supplier networks.
China
MIIT emission standards concentrate capital deployment in Shanghai and Guangdong manufacturing hubs. Domestic automotive OEMs expand booth installations to meet stricter volatile organic compound mandates. Zhengzhou-based fabricators supply crossdraft configurations for budget-constrained refurbishing centers in interior provinces.
India
Tamil Nadu and Gujarat state industrial zones lack modern finishing infrastructure as passenger vehicle production scales. The country's national automotive regulator pushes emission compliance timelines that concentrate replacement demand in manufacturing corridors. Heavy machinery exporters in Maharashtra pre-emptively phase out solvent-based systems to maintain EU market access.
Japan
METI industrial efficiency standards drive automation integration with real-time airflow monitoring in automotive plants. JIS certification requirements fragment equipment design economies for cross-border suppliers. Nagoya-area coating shops adopt computational fluid dynamics simulations to de-risk custom booth specifications.
Industrial Paint Booth Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base spans German engineering-intensive fabricators, North American distributor-anchored service networks, and Asian scale-driven manufacturers. Three archetypes dominate: robotics-heritage system integrators, thermal process engineering specialists, and aftermarket service unbundlers. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through distributor acquisition.
Among German-based fabricators, Dürr AG and Eisenmann SE exemplify divergent specialization vectors. Dürr AG occupies a position within the robotics-heritage tier, anchoring premium automated finishing lines through control platform standardization. Eisenmann SE sits within the thermal process engineering archetype, representing integrated booth-oven configurations for heavy machinery applications. Global Finishing Solutions anchors the North American aftermarket through extensive distributor control and rapid field service deployment.
| Leading Market Players |
|---|
| Global Finishing Solutions |
| Accudraft |
| Eisenmann SE |
| Dürr AG |
| Blowtherm |
| Col-Met Engineered Finishing Solutions |
| Spray Systems Inc. |
| Nova Verta International |
| Dalby |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese crossdraft booth fabrication is compressing margin structures for mid-tier European suppliers while simultaneously pressuring procurement teams at US automotive OEMs to renegotiate long-term maintenance contracts. This utilization asymmetry between manufacturing hubs and mature markets shapes supplier pricing power and forces equipment buyers to sequence purchases around regional capacity cycles.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate long-term agreements between automotive OEMs and German fabricators, insulating suppliers from commodity volatility while capping upside. Three-tier pricing structure across premium automated lines, standard enclosed configurations, and economy crossdraft units reflects certification grade and after-sales bundling intensity. Pricing pressure stems from Zhengzhou-based manufacturers exporting budget configurations to Southeast Asian markets. Tier-1 automotive suppliers exhibit lowest price sensitivity due to OEM-mandated specification conformity, while independent refurbishing centers in Poland and Mexico drive hardest bargain on upfront capital outlay.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for filtration media and control system components. High-efficiency particulate filter manufacturing concentrates in Germany and Japan, while steel enclosure fabrication draws from Chinese and Turkish rolling mills. Single-source vulnerability for HVAC-balancing instrumentation creates procurement bottlenecks during compliance-driven upgrade cycles. Distribution runs through captive OEM procurement channels for integrated lines and independent distributor networks for aftermarket service and replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne coating conversion mandates across Germany, China, and the United States signal early-cycle expansion as replacement demand concentrates in manufacturing hubs with the strictest emission enforcement timelines. This regulatory synchronization creates a multi-year equipment refresh window.
For Market Incumbents: Build switching-cost moats through control platform standardization across multi-model paint lines to lock in automotive OEM specification authority. Deepen captive service relationships with real-time airflow monitoring subscriptions that reduce field technician dispatch frequency. Counter Zhengzhou-based budget entrants by emphasizing EPA NESHAP pre-certification and digital twin commissioning capabilities that compress ramp-up timelines for US assembly plant expansions. For New Entrants and Emerging Players: Build out portable booth configurations for aviation MRO regional hubs in Singapore and Dubai where fleet utilization rebounds outpace infrastructure investment. Target India's Tamil Nadu and Gujarat automotive corridors with humidity-controlled flash-off zone packages tailored to waterborne basecoat compliance timelines. Pursue EU Green Deal industrial renovation funding channel partnerships to subsidize solvent-to-waterborne conversion sales in Italian and Polish coating shops. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket service unbundlers with rapid-deployment field teams and filtration media replacement programs. Five-to-ten year viability favors distributors with exclusive territory control and technician training infrastructure rather than pure-play fabricators exposed to steel price volatility. Monitor MIIT emission standard calibration announcements in China as the inflection signal for replacement cycle acceleration in Shanghai and Guangdong manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filtration Media | German fabricators secure supply continuity for EPA NESHAP-compliant VOC capture systems amid Japanese supplier concentration. |
| Digital Twin Commissioning Capability | Virtual airflow validation reduces field rework for Dürr AG multi-zone installations at Tesla Berlin and Austin facilities. |
| EU Green Deal Funding Partnership | Channel subsidies for waterborne conversion investments in Italian and Polish SME coating shops accelerate replacement sales. |
| Aviation MRO Portable Configuration Launch | Regional maintenance hubs in Singapore and Dubai address capacity gaps as aircraft repaint cycles compress with fleet utilization. |
| India State-Level Distribution Expansion | Tamil Nadu and Gujarat corridor presence captures passenger vehicle production scaling without modern finishing infrastructure. |
Study Parameters
Operator-level perspectives from plant engineers, OEM procurement managers, aftermarket service directors, and HVAC-balancing technicians anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against EPA NESHAP enforcement timelines, MIIT emission standard publications, EU F-Gas Regulation calibration schedules, and automotive OEM capital expenditure disclosures. Bottom-up triangulation across equipment configuration demand and top-down reconciliation with regional manufacturing output data ensured consistency.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across downdraft-crossdraft-side draft configurations, waterborne-solvent-UV-powder technology chemistries, and automotive OEM-heavy machinery-aerospace-furniture application verticals. CAGRs derived from replacement cycle compression analysis and regulatory phase-in synchronization across major manufacturing hubs. Forecast inputs incorporated REACH authorization timelines for chromium-based pretreatment alternatives and steel commodity price trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese crossdraft fabricators or accelerated EU Green Deal subsidy disbursement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Water Color Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market