
 Solar Paint Market | 2026-2036
Solar Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Paint Market Analytics
Commercial facade developers are unwinding legacy demand from standalone rooftop panel installers as building-integrated photovoltaics gains share. Sherwin-Williams leverages its architectural coatings distribution network to position energy-generating paints within existing specification channels. NIPPON PAINT anchors Asian project pipelines through deep ties with regional contractors. AkzoNobel differentiates via R&D intensity in conductive polymer formulations.
Solar paint comprises a thin-film photovoltaic coating containing semiconductor nanoparticles—typically titanium dioxide or perovskite derivatives—suspended in a polymer binder that converts incident light into electrical current when applied to exterior surfaces. The technology targets seamless energy harvesting on vertical building envelopes where traditional rigid panels prove impractical. Energy-generating paints currently command the steepest premium but transparent films are expanding fastest as smart window retrofits accelerate. Photovoltaic cell technology leads in conversion efficiency while hybrid systems capture emerging margin pools by combining thermal and electrical output.
The EU Green Deal and REACH framework shape product chemistry requirements across European construction markets, while the US EPA and state-level building codes govern VOC thresholds and net-zero mandates that determine solar paint eligibility for public projects. China's GB standards and MIIT directives set efficiency benchmarks and manufacturing compliance thresholds for imported coating technologies. Stakeholders must monitor how divergent efficiency certification regimes between jurisdictions affect cross-border product registration costs and timeline.
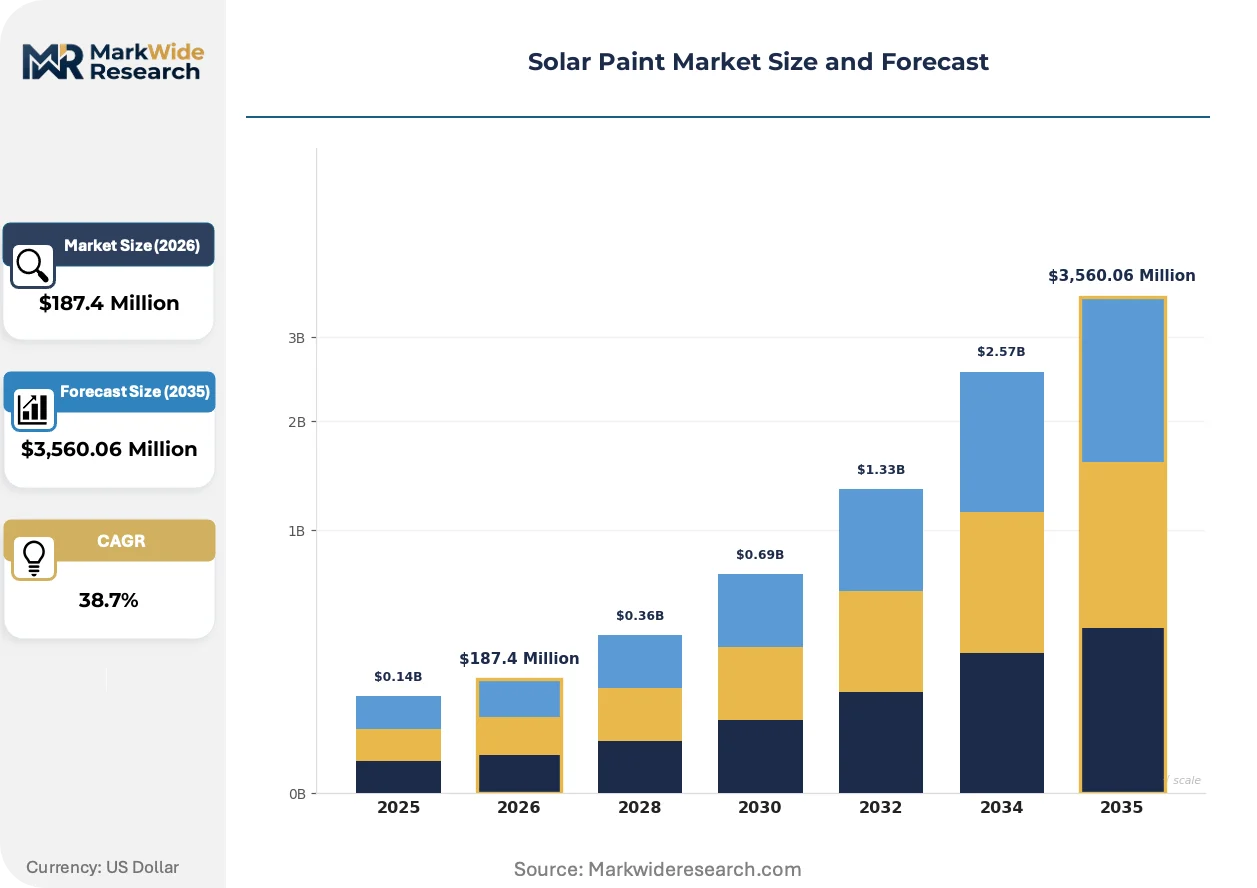
Market Dynamics
Building-integrated photovoltaics is compressing the addressable market for conventional rooftop solar hardware as facade developers prioritize seamless energy generation over bolt-on panel systems.
Growth Catalysts
- EU Green Deal embodied-carbon rules:Construction material specifications in Germany, France, and the Netherlands now favor low-carbon envelope solutions, pulling solar paint into public tender eligibility.
- Retrofit mandates in German building codes:The country's Energieeinsparverordnung requires efficiency upgrades on existing commercial stock, creating immediate specification pull for energy-generating coatings.
- Perovskite semiconductor efficiency gains:Laboratory conversion improvements for thin-film nanoparticle suspensions are narrowing the performance gap with rigid silicon panels.
Market Restraints
- Titanium dioxide supply concentration:Pigment production clusters in China create input cost volatility and geopolitical exposure for coating formulators.
- REACH chemical compliance friction:ECHA registration timelines for novel semiconductor binders extend product commercialization cycles by 18-36 months.
- Rigid panel substitution threat:Falling crystalline silicon prices from oversupplied Chinese manufacturing compress the premium window for novel coating technologies.
Strategic Opportunities
- Smart window retrofit channel:Transparent photovoltaic films for glazing refurbishment represent an underpenetrated application with faster installation cycles than full envelope replacement.
- India PLI scheme for solar manufacturing:Domestic production-linked incentives for photovoltaic components could localize coating supply chains for South Asian project pipelines.
- Hybrid thermal-electrical systems:Converging photovoltaic and building-thermal management functions capture margin pools from HVAC-integrated envelope specifications.
Industry Challenges
- Conductive polymer formulation expertise gap:The intersection of semiconductor physics and architectural coatings chemistry lacks trained technical personnel, constraining R&D throughput.
- Multi-jurisdiction certification timelines:Divergent efficiency testing protocols between EPA state-level programs, EU harmonized standards, and China's GB certification create registration cost stacking.
- Legacy facade contractor training:Application techniques for thin-film photovoltaic coatings differ substantially from conventional paint systems, requiring field workforce requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Paint Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,560.06 Million |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Coatings, Commercial Coatings, Transparent Films, Energy-Generating Paints Technology: Photovoltaic Cells, Conductive Polymers, Nanotechnology, Hybrid Systems Application: Building-integrated Photovoltaics, Renewable Energy Solutions, Smart Windows, Energy-efficient Homes End User: Architects, Contractors, Homeowners, Industrial Facility Managers |
| Companies Covered | Sherwin-Williams, NIPPON PAINT, AkzoNobel, SRI International, LuminX Coatings, Axalta Coating Systems Ltd., SPI Coatings, Onyx Solar Group LLC, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Paint Market Evolving Landscape
Active materials research and regulatory chemistry mandates are reconfiguring how photovoltaic coatings enter specification channels and compete with incumbent envelope technologies.
Perovskite-titania nanocomposite suspensions are displacing first-generation dye-sensitized formulations in laboratory and pilot-scale deployments. Commercial facade developers in Northern Europe specify these materials for vertical surface applications where silicon panel mounting proves structurally impractical. The technology is displacing rigid panel retrofit demand on heritage buildings and curtain-wall structures with weight-bearing constraints.
REACH framework amendments on persistent organic pollutants are tightening allowable solvent content in architectural coating binders. ECHA's evolving restricted substance lists force reformulation of polymer carriers used to suspend semiconductor nanoparticles. German and Dutch coating manufacturers are accelerating water-based binder development to maintain specification eligibility for public infrastructure tenders.
Specification decisions increasingly flow through integrated design-build contracts rather than fragmented architect-contractor handoffs. Large European construction consortia now bundle envelope performance guarantees with energy generation commitments, compressing the vendor selection window. This pattern concentrates most visibly in German commercial retrofit pipelines where single-source accountability reduces project risk allocation complexity.
Solar Paint Market Segmentation
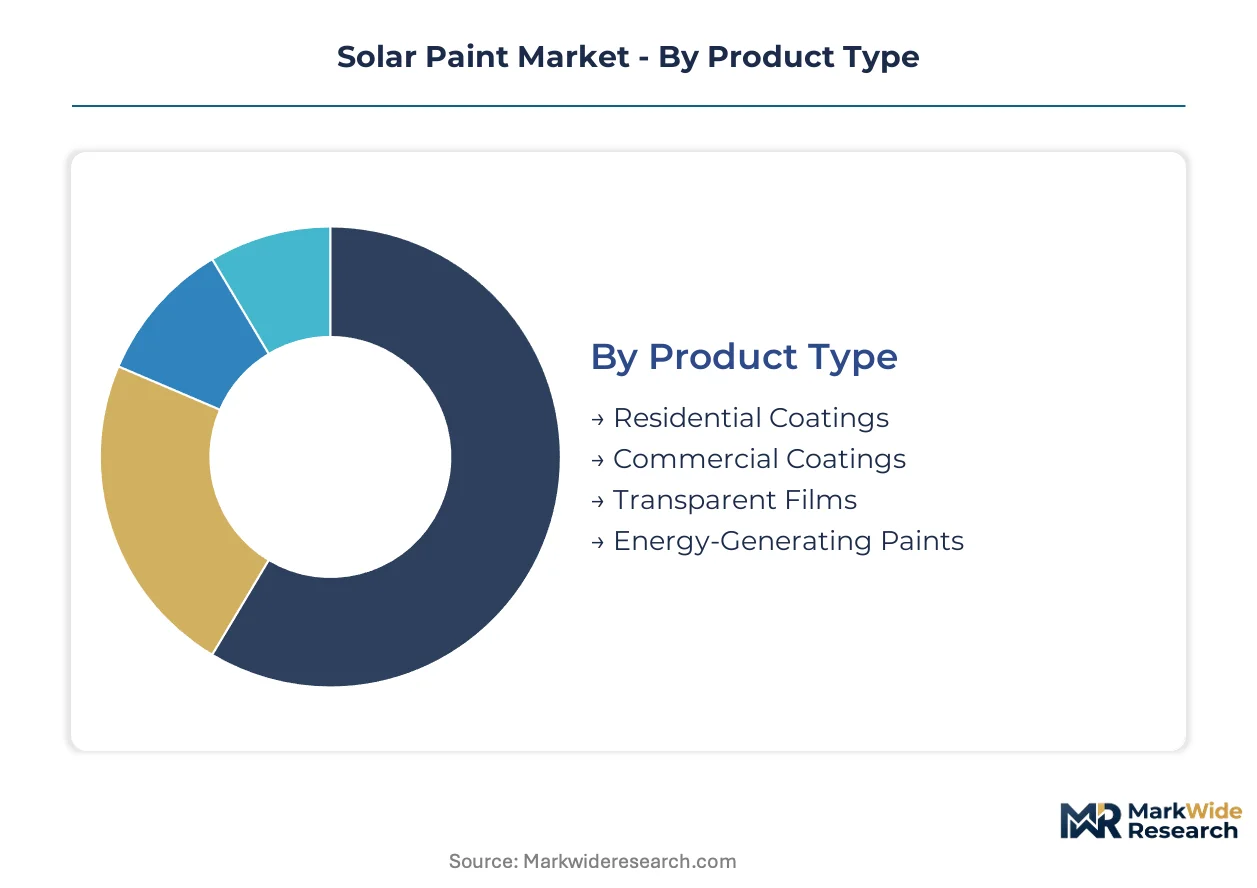
Solar paint segmentation reveals how value migrates across specification channels. Product chemistry, installation context, and buyer professionalization determine margin capture and pricing power for coating formulators.
Product Type:
Premium capture concentrates in specialized energy-generating formulations while volume scales through architectural retrofit channels.
- Energy-Generating Paints:These coatings embed perovskite or titanium dioxide nanoparticles in polymer binders to convert incident light into electrical current on vertical surfaces. German commercial facade developers specify these for heritage building retrofits where rigid panel mounting is structurally prohibited, though titanium dioxide supply concentration in China creates input cost volatility.
- Transparent Films:Thin photovoltaic layers applied to glazing enable smart window retrofits without full envelope replacement. Demand is accelerating in Dutch and French commercial buildings where EU Green Deal embodied-carbon rules favor low-carbon envelope solutions in public tenders.
- Commercial Coatings:High-durability formulations designed for curtain-wall and large-surface applications with extended weathering guarantees.
- Residential Coatings:Consumer-grade products targeting energy-efficient home retrofits with simplified application protocols for contractor networks.
Energy-generating paints hold installed capacity. Transparent films are rotating up the share rankings.
Technology:
Conversion efficiency and manufacturing scalability separate leaders from followers in semiconductor formulation.
- Photovoltaic Cells:First-generation thin-film architectures using dye-sensitized or silicon-integrated approaches achieve the highest laboratory conversion rates. Northern European facade specifications favor these for vertical surface deployment where mounting constraints eliminate rigid alternatives, though falling crystalline silicon prices from Chinese manufacturing compress the premium window.
- Hybrid Systems:Converged thermal-electrical output captures margin pools from HVAC-integrated envelope specifications. German Energieeinsparverordnung retrofit mandates create immediate specification pull for these dual-function coatings on existing commercial stock.
- Conductive Polymers:Polymer carriers suspending semiconductor nanoparticles, increasingly water-based to satisfy REACH solvent restrictions.
- Nanotechnology:Perovskite-titania nanocomposite suspensions displacing earlier formulations in pilot deployments.
Photovoltaic cells anchor current revenue. Hybrid systems are climbing the fastest as building-thermal integration specifications proliferate.
Application:
Specification complexity and project scale determine vendor selection criteria and contract structure.
- Building-integrated Photovoltaics:Seamless envelope integration where energy generation is specified as a performance guarantee rather than hardware procurement. Large European construction consortia now bundle these commitments in integrated design-build contracts, compressing vendor selection windows in German commercial retrofit pipelines.
- Smart Windows:Glazing refurbishment with transparent photovoltaic films offers faster installation cycles than full envelope replacement. Dutch and French public infrastructure tenders increasingly specify these for embodied-carbon compliance.
- Renewable Energy Solutions:Standalone generation projects treating solar paint as primary energy infrastructure rather than building component.
- Energy-efficient Homes:Residential retrofit programs linking coating specification to building code compliance and subsidy eligibility.
Building-integrated photovoltaics dominates contract value. Smart windows are gaining share fastest as retrofit acceleration outpaces new construction.
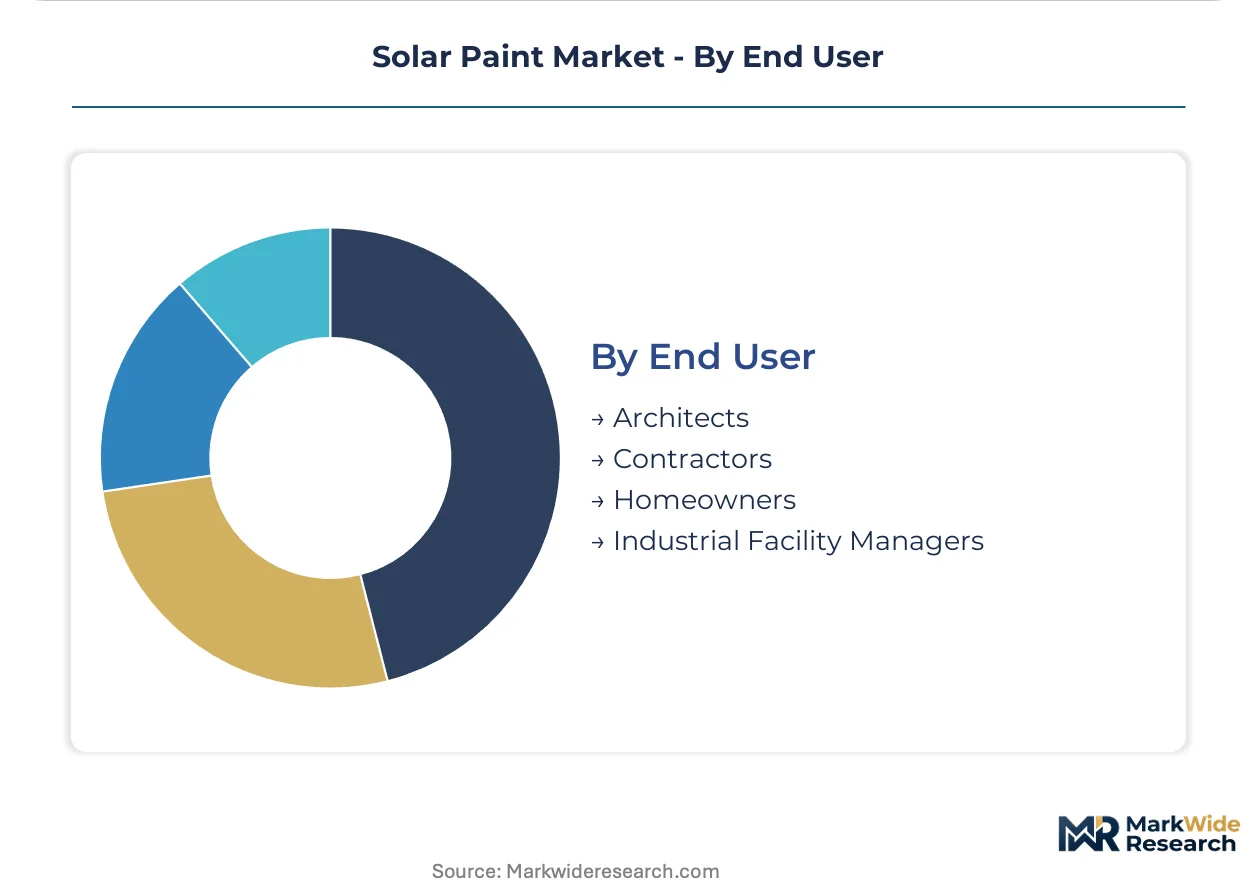
End User:
Professionalization level and procurement authority shape pricing tolerance and technical service requirements.
- Contractors:Field application specialists requiring workforce requalification for thin-film photovoltaic coating techniques that differ substantially from conventional paint systems. German regional contractors anchor Asian project pipelines through specification influence in integrated design-build structures.
- Architects:Design-phase specification holders who channel decisions through performance guarantees and envelope energy commitments. Their influence concentrates in Northern European commercial facade development where seamless energy generation is prioritized over bolt-on panel systems.
- Industrial Facility Managers:Operational decision-makers targeting HVAC-integrated envelope specifications for thermal-electrical hybrid systems.
- Homeowners:Price-sensitive retail buyers dependent on contractor recommendations and subsidy program navigation.
Contractors control installed volume. Architects are rotating up the influence rankings as performance-based specifications displace hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese titanium dioxide exports feed German coating formulators while Indian project developers source transparent films from Dutch distributors. Trade corridors concentrate input materials in East Asian manufacturing clusters and finished formulations in Northern European specification markets.
Germany
Energieeinsparverordnung retrofit mandates pull energy-generating coatings into commercial building upgrades. The EU Green Deal tightens embodied-carbon thresholds for public tenders. Berlin-Brandenburg contractors bundle envelope performance guarantees with energy generation commitments in integrated design-build contracts.
Netherlands
Smart window retrofits accelerate as facade developers seek faster installation cycles than full envelope replacement. REACH solvent restrictions force water-based binder reformulation. Eindhoven Region coating manufacturers concentrate R&D in conductive polymer architectures for glazing refurbishment pipelines.
China
MIIT efficiency benchmarks and GB standards govern manufacturing compliance for photovoltaic coating components. Domestic titanium dioxide supply clusters create input cost leverage for regional formulators. Yangtze River Delta production bases export semiconductor nanoparticle suspensions to European architectural coating blenders.
France
Public infrastructure tenders specify low-carbon envelope solutions under EU Green Deal implementation. Île-de-France commercial developers prioritize seamless energy generation on heritage curtain-wall structures. Paris-based construction consortia compress vendor selection windows through bundled performance guarantees.
India
PLI scheme incentives for solar manufacturing localize coating supply chains for South Asian project pipelines. Maharashtra and Gujarat contractors anchor regional specification influence through integrated design-build structures. BIS efficiency certification timelines determine product eligibility for government-backed retrofit programs.
Solar Paint Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D throughput dimensions. The vendor base stratifies between diversified coating conglomerates with architectural distribution networks and focused photovoltaic material developers with semiconductor physics capabilities. Three archetypes dominate: legacy paint manufacturers leveraging specification channels, dedicated solar coating startups, and diversified chemical conglomerates with conductive polymer expertise. Competitive moves concentrate on strategic partnerships with facade contractors and geographic licensing arrangements to bypass multi-jurisdiction certification bottlenecks.
Within the legacy coating manufacturer tier, Sherwin-Williams and NIPPON PAINT exemplify channel-anchored positions, while AkzoNobel occupies a position representing R&D-intensive formulation specialization. These three entities illustrate how diversified chemical portfolios and regional contractor relationships create divergent pathways to specification influence in commercial facade markets.
| Leading Market Players |
|---|
| Sherwin-Williams |
| NIPPON PAINT |
| AkzoNobel |
| SRI International |
| LuminX Coatings |
| Axalta Coating Systems Ltd. |
| SPI Coatings |
| Onyx Solar Group LLC |
| PPG Industries |
| Others |
Value Network & Pricing Analysis
Perovskite-titania nanocomposite suspensions displacing first-generation dye-sensitized formulations are redrawing procurement geography toward Chinese titanium dioxide clusters while compressing premium capture windows for European formulators facing REACH compliance costs.
Pricing Analysis
First-generation dye-sensitized photovoltaic coatings trade at substantial discounts to perovskite-titania nanocomposite formulations, with next-generation hybrid thermal-electrical systems commanding the widest premiums. Three-tier pricing structure across premium, standard, and economy levels reflects conversion efficiency gradations and certification tier under EU harmonized standards. Pricing pressure stems from falling crystalline silicon panel costs out of Chinese manufacturing, which narrows the viable premium for novel coating technologies. Commercial facade developers in Northern Europe show lowest price sensitivity due to performance-guarantee contract structures, while residential contractors in emerging markets resist premiums without subsidy program support.
Supply Chain Analysis
Inventory lead times for semiconductor nanoparticle suspensions extend substantially when sourced through Yangtze River Delta production bases serving European architectural coating blenders. Titanium dioxide pigment production clusters in China, perovskite precursor synthesis concentrates in South Korea, and polymer binder manufacturing localizes in Germany and the Netherlands. Raw material dependencies encompass titanium dioxide ore, perovskite methylammonium halide precursors, and conductive polymer carriers. Single-source vulnerability runs through Chinese titanium dioxide exports subject to geopolitical friction. Distribution runs through integrated design-build construction consortia rather than fragmented architect-contractor channels.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar paint sits in early-cycle expansion as building-integrated photovoltaics penetration accelerates faster than conventional rooftop panel retrofit rates across Northern European commercial stock.
For Market Incumbents: Secure specification lock-in through exclusive distribution arrangements with German regional contractors anchoring integrated design-build contracts. Deepen backward integration into perovskite precursor supply to offset titanium dioxide cost volatility from Chinese export concentration. Prioritize water-based binder R&D to maintain REACH eligibility as ECHA solvent restrictions tighten. For New Entrants and Emerging Players: ECHA fast-track registration for novel semiconductor binders offers the most penetrable pathway to European public tender eligibility. Target smart window retrofit channels in Dutch and French commercial buildings where installation cycle advantages outweigh full envelope replacement economics. Pursue licensing partnerships with established architectural coatings distributors to bypass multi-jurisdiction certification bottlenecks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed conductive polymer specialists possessing laboratory-scale perovskite formulation capabilities but lacking commercial specification channels. Five-to-ten year viability hinges on hybrid thermal-electrical system adoption rates in HVAC-integrated envelope markets. Watch German Energieeinsparverordnung retrofit mandate enforcement intensity as inflection indicator for coating specification pull.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Formulation Scale-Up | Laboratory conversion gains must transfer to manufacturing yield stability for cost competitiveness with silicon panels. |
| Water-Based Binder Development | REACH solvent restrictions force reformulation to maintain specification eligibility for German public infrastructure tenders. |
| Contractor Training Certification | Application technique differentiation from conventional paint systems requires workforce requalification for field deployment. |
| Hybrid System Integration | Converged thermal-electrical output captures HVAC-integrated envelope specifications under Energieeinsparverordnung mandates. |
| Regional Production Licensing | India PLI scheme localization bypasses import duty exposure and accelerates South Asian project pipeline access. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulator R&D directors, commercial facade developer procurement leads, German regional contractor operations managers, and ECHA regulatory affairs specialists, then refined against secondary validation from SEC 10-K filings of listed coating manufacturers, EU public tender databases, customs trade data on titanium dioxide flows, and IEA building energy efficiency reports. Bottom-up project pipeline enumeration triangulated against top-down addressable envelope surface estimates.
Variance decomposition across product chemistry, installation context, technology generation, and end-user professionalization dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by retrofit mandate enforcement schedules and subsidy program renewal probabilities. Forecast inputs incorporated perovskite efficiency improvement trajectories from laboratory disclosures and crystalline silicon price elasticity assumptions from Chinese manufacturing capacity utilization.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or perovskite manufacturing yield breakthroughs would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Radar Absorbing Paint Market