
 Global Paints and Coatings Fillers Market | 2026-2036
Global Paints and Coatings Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paints and Coatings Fillers Market Foresight
Calcium carbonate is hardening its position as the preferred extender pigment, displacing higher-cost titanium dioxide in mid-tier architectural formulations. Sibelco leverages its integrated quarry-to-distribution network across Europe to sustain cost advantages in ground calcium carbonate supply. Omya AG anchors its competitive stance through specialized particle-size engineering that meets OEM specifications for automotive primer systems.
Paints and coatings fillers are particulate mineral additives—typically calcium carbonate, kaolin, talc, or silica—graded to specific particle size distributions between 0.5 and 50 microns, incorporated to reduce raw material costs, improve rheology, enhance opacity, or reinforce mechanical film properties in liquid and powder coating systems. Titanium dioxide dominates value contribution due to its unmatched refractive index and hiding power, though calcium carbonate volumes lead across architectural applications where cost efficiency outweighs optical performance demands. Powder coatings represent the fastest-growing application vector, driven by VOC-free regulatory mandates and the shift toward electrostatic spray processes in metal fabrication.
REACH registration requirements in Europe, EPA TSCA oversight in the United States, and China's GB standards on hazardous substance limits in decorative coatings collectively elevate compliance costs and favor suppliers with certified, traceable mineral sourcing. ECHA's evolving restrictions on microplastic additives further redirect formulation strategies toward inorganic filler systems. Stakeholders must monitor regulatory divergence across jurisdictions to anticipate reformulation timelines and secure qualified raw material positions ahead of compliance deadlines.
Market Dynamics
Calcium carbonate's displacement of titanium dioxide in architectural coatings is compressing raw material costs while forcing reformulation investments across mid-tier decorative paint portfolios.
Growth Catalysts
- Automotive primer demand:OEM specifications for high-build automotive primer systems are pulling engineered calcium carbonate volumes as manufacturers seek cost-efficient hiding power in electrocoat layers.
- REACH microplastic restrictions:ECHA's evolving restrictions on microplastic additives are redirecting formulation strategies toward inorganic filler systems in European decorative coatings.
- Powder coating conversion:VOC-free regulatory mandates are accelerating electrostatic spray process adoption in metal fabrication, expanding precipitated calcium carbonate offtake for powder systems.
Market Restraints
- Titanium dioxide price volatility:Feedstock ilmenite and rutile cost swings transmit directly into coating raw material budgets, constraining mid-tier architectural margin recovery.
- Ground calcium carbonate supply concentration:European quarry ownership concentrates among integrated mineral processors, limiting spot market liquidity for regional coating compounders.
- Optical performance ceiling:Calcium carbonate's refractive index of 1.58 versus titanium dioxide's 2.7 creates an immutable hiding-power gap that blocks substitution in premium gloss segments.
Strategic Opportunities
- India construction acceleration:BIS-certified filler grades for decorative coatings remain undersupplied relative to residential and infrastructure coating demand expansion.
- Bio-based coating convergence:Formulators combining precipitated calcium carbonate with plant-derived binders are accessing EU Green Deal-aligned procurement channels.
- Direct-to-compounder distribution:Bypassing regional distributors through qualified-supplier portals is compressing working capital cycles for large architectural coating manufacturers.
Industry Challenges
- Particle-size engineering talent scarcity:Specialized mineral processing engineers capable of tuning sub-micron distributions for automotive OEM specifications command premium compensation.
- REACH registration timeline compression:Coating compounders face accelerated substance dossier deadlines that strain in-house regulatory affairs capacity.
- Legacy ERP integration friction:Mineral suppliers implementing batch-traceability systems encounter data architecture conflicts with coating customers' legacy manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paints and Coatings Fillers Market |
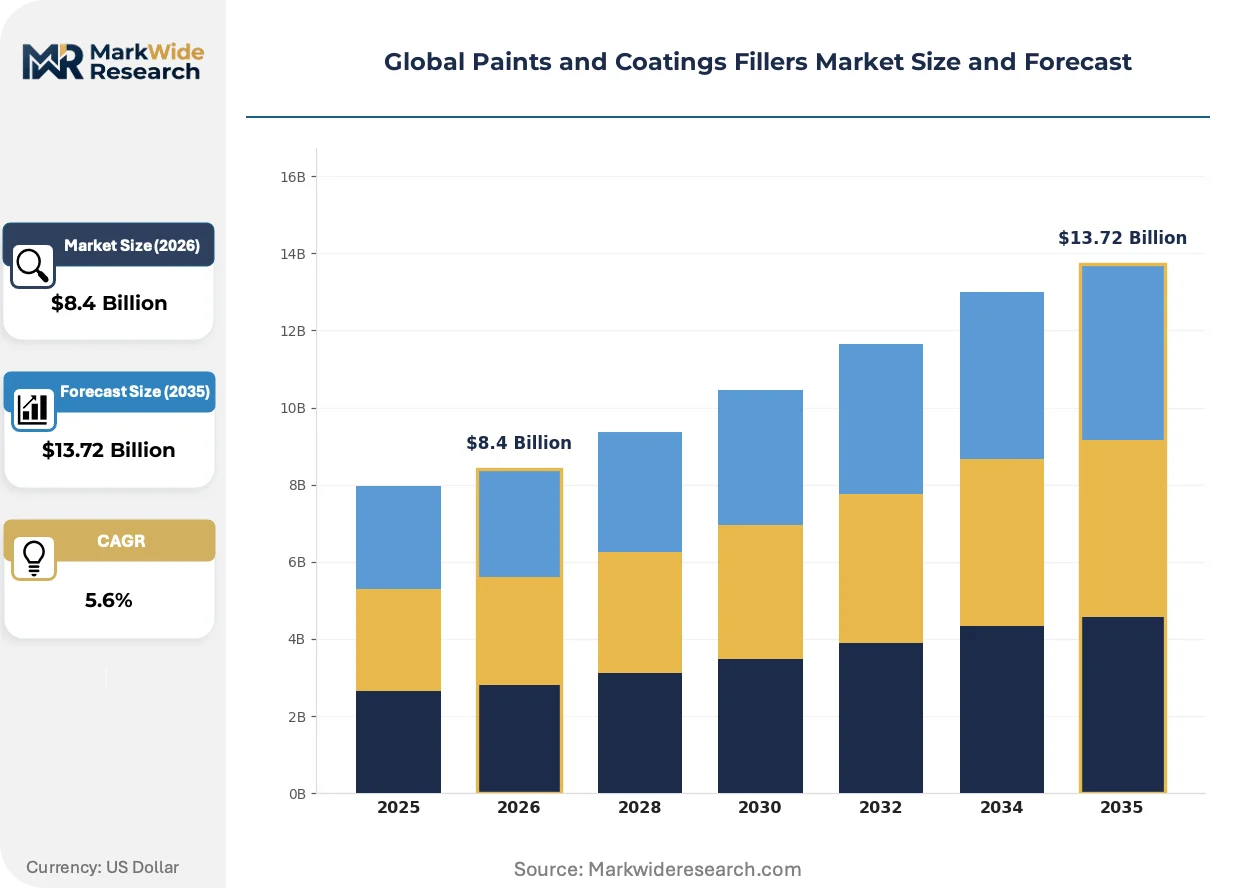
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Dioxide, Calcium Carbonate, Kaolin, Talc, Silica, Clay Application: Architectural Coatings, Industrial Coatings, Automotive Finishes, Marine Coatings, Wood Coatings, Powder Coatings End User: Manufacturers, Contractors, Shipbuilders, Furniture Producers, OEMs, Aftermarket Suppliers Packaging Type: Bulk Bags, Drums, Flexible Intermediate Bulk Containers, Paper Bags, Plastic Containers, Fiber Drums |
| Companies Covered | Sibelco, 3M, Minerals Technologies Inc., Mississippi Lime Company, Huber Engineered Materials, Omya AG, Gebrüder Dorfner GmbH & Co, IMCD N.V., Imerys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paints and Coatings Fillers Market Shifts & Advancements
Surface-engineered calcium carbonate is fragmenting traditional extender pigment hierarchies while regulatory microplastic bans and procurement digitization reshape supplier-buyer relationships.
Engineered surface-modified calcium carbonate is modularizing coating formulation architectures by decoupling rheology control from opacity functions in a single additive platform. Tier-two architectural manufacturers are adopting these multifunctional grades fastest, compressing their additive SKU portfolios by 30-40 percent while maintaining film performance. This consolidation is modularizing supplier relationships as compounders reduce qualified vendor lists.
EPA TSCA Section 5 pre-manufacture notification requirements for new chemical substances are lengthening innovation cycles for novel nano-structured fillers in the United States. Coating manufacturers are responding by prioritizing existing substance inventory over experimental mineral modifications, slowing premium product pipeline velocity. Automotive refinish segments face the tightest compliance timelines as OEM clearcoat specifications evolve faster than regulatory clearance windows.
Large architectural coating buyers are consolidating mineral filler procurement through centralized category management functions, displacing plant-level spot purchasing. This concentration is compressing negotiation leverage for regional ground calcium carbonate distributors across Germany and France. Direct supplier relationships now dominate volume planning for top-five European decorative paint manufacturers.
Global Paints and Coatings Fillers Market Segmentation
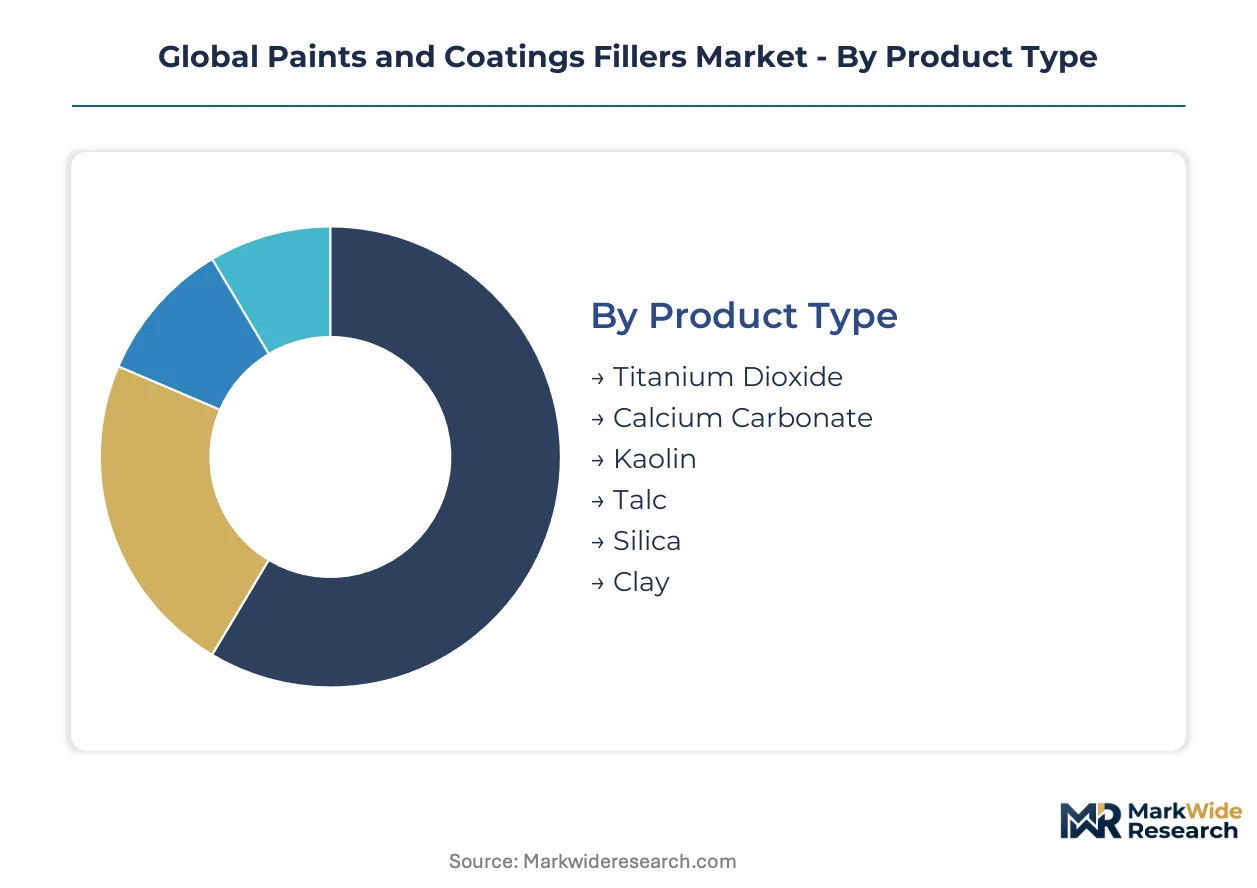
Segmentation in paints and coatings fillers reveals how regulatory compliance burdens, application performance thresholds, and supply chain configurations fragment procurement strategies across mineral grades and delivery formats. Distinct certification requirements for automotive OEMs versus architectural compounders create divergent sourcing patterns that reshape competitive positioning.
Product Type:
REACH registration dossiers and ECHA substance evaluations impose differentiated compliance timelines across mineral categories, with nano-grade materials facing extended toxicity testing protocols.
- Titanium Dioxide:Rutile and anatase crystal structures deliver refractive indices of 2.7, establishing unmatched hiding power in premium gloss formulations. Demand concentrates in automotive refinish segments where OEM clearcoat specifications mandate optical performance that calcium carbonate cannot replicate, though feedstock ilmenite price volatility constrains margin stability.
- Calcium Carbonate:Ground and precipitated grades span particle sizes from 0.5 to 50 microns, with surface-modified variants displacing titanium dioxide in mid-tier architectural systems. China’s construction surge and automotive primer production in Germany pull engineered calcium carbonate volumes as manufacturers seek cost-efficient hiding power in electrocoat layers.
- Kaolin:Hydrous and calcined aluminum silicate grades provide rheology control and barrier properties in marine protective coatings.
- Talc:Magnesium silicate lamellar structures enhance corrosion resistance and film reinforcement in industrial maintenance systems.
- Silica:Amorphous and crystalline forms deliver matting efficiency and scratch resistance in wood furniture finishes.
- Clay:Bentonite and attapulgite grades suspend pigments and control sag in thick-film applications.
Leading the category by volume: Calcium Carbonate. Growing fastest: Surface-engineered precipitated calcium carbonate grades.
Application:
VOC emission thresholds and curing process requirements segment formulation strategies, with powder and waterborne systems commanding distinct mineral specifications.
- Architectural Coatings:Interior and exterior decorative paints incorporate calcium carbonate extenders to reduce titanium dioxide loading while maintaining scrub resistance and tint retention. Residential construction in India and commercial building maintenance across France sustain substantial offtake, though BIS certification requirements for decorative coatings create entry barriers for uncertified suppliers.
- Industrial Coatings:Protective and functional finishes for metal substrates demand corrosion-resistant filler systems with engineered particle size distributions. Chemical processing facilities in Germany and offshore infrastructure in Norway specify talc and mica-reinforced formulations that withstand aggressive service environments.
- Automotive Finishes:Electrocoat primer, basecoat, and clearcoat layers require sub-micron calcium carbonate with controlled oil absorption for high-build systems.
- Marine Coatings:Ballast tank and hull protection systems utilize barrier-optimized kaolin and talc grades to prevent corrosion in saltwater immersion.
- Wood Coatings:Furniture and flooring finishes employ silica matting agents to achieve low-sheen aesthetics with mechanical durability.
- Powder Coatings:Electrostatic spray processes for metal fabrication rely on precipitated calcium carbonate with precise particle morphology for charge acceptance and flow control.
Architectural Coatings dominates volume contribution. Powder Coatings climbs fastest on VOC-free regulatory mandates.
End User:
Procurement sophistication and technical specification authority determine whether mineral sourcing occurs at corporate, plant, or project level.
- Manufacturers:Large decorative paint compounders consolidate mineral filler procurement through centralized category management functions, displacing plant-level spot purchasing across Germany and France.
- Contractors:Application crews and project managers source bagged filler products through distributor networks for on-site tinting and touch-up operations.
- Shipbuilders:Korean and Chinese shipyards specify certified marine coating systems with traceable mineral sourcing for classification society compliance.
- Furniture Producers:Italian and Polish manufacturers demand low-VOC wood coating formulations with silica matting agents for export markets.
- OEMs:Automotive original equipment manufacturers enforce qualified supplier lists with particle-size engineering validation for primer system approvals.
- Aftermarket Suppliers:Refinish paint distributors stock titanium dioxide-rich systems for collision repair shops requiring color-matching precision.
Manufacturers command the largest procurement volumes. OEMs impose the strictest qualification protocols.
Packaging Type:
Handling automation and inventory velocity determine format selection across direct-to-compounder and distributor-mediated channels.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume architectural coating plants with pneumatic conveying systems and silo storage.
- Drums:Steel and fiber drums protect moisture-sensitive precipitated calcium carbonate for specialty automotive primer shipments.
- Flexible Intermediate Bulk Containers:Four-loop and two-loop FIBC designs accommodate forklift handling in powder coating compounder warehouses.
- Paper Bags:Multiwall kraft constructions with polyethylene liners serve mid-tier decorative paint manufacturers with moderate throughput.
- Plastic Containers:Pails and jars package pre-dispersed filler pastes for tinting system compatibility in retail channels.
- Fiber Drums:Lightweight cylindrical packaging suits export shipments of kaolin and talc grades to furniture coating operations.
Bulk Bags moves the highest tonnage. Flexible Intermediate Bulk Containers gains fastest on powder coating logistics automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones concentrate precipitated calcium carbonate capacity to serve automotive primer production clusters. Germany's Rhine-Ruhr industrial corridor anchors European ground calcium carbonate processing for architectural coating compounders. India's western industrial corridor generates BIS-certified filler demand from residential construction acceleration.
China
Automotive production in Shanghai-Tianjin-Hebei corridor and construction activity in Yangtze River Delta sustain calcium carbonate offtake volumes. GB standards on hazardous substance limits in decorative coatings tighten permissible heavy-metal thresholds. Jiangsu province hosts precipitated calcium carbonate plants supplying powder coating compounders with VOC-compliant mineral grades.
Germany
OEM specifications for high-build automotive primer systems pull engineered calcium carbonate through qualified supplier channels. REACH registration requirements impose differentiated compliance timelines across nano-grade mineral categories. North Rhine-Westphalia's chemical processing belt concentrates ground calcium carbonate distribution networks serving mid-tier decorative paint manufacturers.
United States
EPA TSCA Section 5 pre-manufacture notification requirements lengthen innovation cycles for novel nano-structured fillers in automotive refinish segments. Metal fabrication conversion to electrostatic spray processes expands precipitated calcium carbonate demand. Ohio and Michigan automotive coating clusters enforce particle-size engineering validation for primer system approvals.
India
BIS-certified filler grades for decorative coatings remain undersupplied relative to residential construction acceleration in Maharashtra and Gujarat. CDSCO-aligned substance testing protocols create entry barriers for uncertified mineral suppliers. Tamil Nadu's industrial corridor attracts ground calcium carbonate distributors targeting architectural coating compounders with moderate throughput requirements.
France
ECHA's evolving restrictions on microplastic additives redirect formulation strategies toward inorganic filler systems in decorative coatings. Auvergne-Rhône-Alpes region hosts specialty mineral processors serving wood furniture finish manufacturers. Île-de-France's centralized procurement functions for large architectural coating buyers compress negotiation leverage for regional distributors.
Global Paints and Coatings Fillers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mineral processors commanding ground calcium carbonate supply and precipitated grade specialists serving automotive OEM channels. The vendor base concentrates among European quarry owners with captive distribution networks and Asian chemical processors with scale-driven precipitated carbonate output. Three archetypes dominate: integrated mineral processors with quarry-to-distribution control, specialty chemical engineers with particle-size tuning capabilities, and regional compounders with BIS or REACH-certified sourcing. Competitive moves center on backward integration into quarry assets and direct-to-compounder distribution portal deployment.
Among integrated mineral processors, Sibelco and Omya AG exemplify archetypes with European quarry network control and specialized particle-size engineering positioning respectively. Minerals Technologies Inc. occupies a position within the precipitated calcium carbonate specialization tier. These three anchors illustrate how geographic concentration of mineral reserves and technical specification authority segment competitive positioning across architectural and automotive end-uses.
| Leading Market Players |
|---|
| Sibelco |
| 3M |
| Minerals Technologies Inc. |
| Mississippi Lime Company |
| Huber Engineered Materials |
| Omya AG |
| Gebrüder Dorfner GmbH & Co |
| IMCD N.V. |
| Imerys |
| Others |
Supply & Pricing Matrix
ECHA's evolving REACH microplastic restrictions gate qualified supply access and premium-tier pricing power for surface-engineered calcium carbonate grades. Coating compounders lacking certified mineral sourcing face exclusion from EU procurement channels while compliant suppliers capture margin premiums on automotive OEM qualifications.
Pricing Analysis
Short lead-time premiums of 15-20 percent apply to precipitated calcium carbonate shipments for automotive primer compounders facing compressed production schedules. Pricing stratifies across REACH-certified, ISO-grade, and uncertified tiers with differentiation driven by particle-size engineering precision and batch-traceability documentation. Cost compression in mid-tier architectural segments intensifies as ground calcium carbonate distributors compete for consolidated category management contracts. Large decorative paint manufacturers exhibit lowest price sensitivity due to volume scale, while regional compounders in India face acute budget constraints on BIS-certified grades.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from automotive primer manufacturers in Germany and China with qualified supplier portal access. Raw material dependencies center on high-purity limestone deposits in Vietnam and Thailand, ilmenite/rutile feedstocks from Australia and South Africa, and surface-modification chemistries from South Korean specialty chemical processors. Distribution runs through integrated mineral processors with captive quarry networks rather than spot-market intermediaries. Single-source vulnerability concentrates in European ground calcium carbonate where Sibelco and Omya AG control quarry-to-distribution infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH registration dossiers create barrier-to-entry moats favoring incumbent mineral processors with established ECHA substance evaluations.
For Market Incumbents: Extend qualified supplier list dominance by deepening backward integration into Vietnamese limestone assets and accelerating particle-size engineering capacity in North Rhine-Westphalia. Surface-modified calcium carbonate substitution threats from engineered silicas demand defensive patent filings on sub-micron distribution tuning methods. For New Entrants and Emerging Players: Enter via BIS-certified ground calcium carbonate supply to Maharashtra and Gujarat architectural coating compounders facing certified-grade shortages. India's western industrial corridor offers the most penetrable geography with direct-to-compounder distribution portals as the viable go-to-market mechanism. For Investors and Strategic Acquirers: REACH registration timeline compression for nano-grade materials is the leading indicator that specialized mineral processing engineering capabilities will command scarcity premiums. Long-term viability favors integrated quarry-to-distribution assets with automotive OEM qualification track records. Acquisition targets should surface among precipitated calcium carbonate specialists with unutilized capacity in Jiangsu province.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive limestone supply from Vietnamese deposits secures cost position against ilmenite volatility. |
| REACH Registration Acceleration | ECHA dossier completion ahead of substance evaluation deadlines locks out uncertified competitors. |
| Direct-to-Compounder Portal Deployment | Bypassing regional distributors compresses working capital cycles for large architectural manufacturers. |
| Surface-Modification R&D Partnership | Collaboration with South Korean specialty chemical houses advances multifunctional additive platforms. |
| Automotive OEM Qualification Expansion | Primer system approvals from German and Chinese manufacturers anchor premium-tier pricing power. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this paints and coatings fillers analysis. Primary interviews with mineral processing plant managers, procurement leads at architectural coating compounders, distribution channel partners, and automotive OEM specification engineers combined with Cefic industry reports, ECHA substance databases, and SEC 10-K disclosures. Bottom-up volume modeling triangulated against top-down market sizing across mineral grades and application segments.
Data-stream reconciliation aligned production capacity surveys with import-export flow analysis and end-use consumption estimates across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user procurement tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical volume trends against construction and automotive production forecasts, with powder coating conversion rates and REACH compliance cost pass-through assumptions as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ilmenite price spike scenarios or accelerated ECHA microplastic restriction enforcement. Periodic stress-testing of base assumptions is recommended given regulatory divergence across jurisdictions and potential automotive production cycle downturns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Oman Paints and Coatings Market