
 Refinish Paint Market | 2026-2036
Refinish Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Refinish Paint Market Analysis
Modular tint-and-dispense systems are recalibrating buyer choice across the refinish paint value chain, shifting procurement from bulk color-matched gallons to on-demand basecoat packages. PPG Industries leverages its global color-matching software infrastructure to anchor high-margin recurring revenue in collision networks. BASF SE differentiates through captive resin production that sustains formulation consistency across climate zones. Axalta Coating Systems dominates the North American fleet refinish channel through direct distribution control.
Refinish paint comprises pigmented coating systems engineered for substrate repair and surface restoration, typically formulated with acrylic or urethane binders at solids contents of 30-55 percent to achieve specified gloss and durability on cured automotive body panels. Its primary commercial purpose is restoring OEM appearance standards on damaged vehicles, furniture, and industrial equipment after wear or collision events. Acrylic formulations now lead volume in waterborne conversions across regulated markets, while urethane segments capture premium margin pools in high-performance automotive clearcoat applications. Two-stage basecoat-clearcoat systems command the fastest growth in professional collision centers, displacing single-stage enamel in metallic and pearl finishes.
EPA VOC regulations and REACH substance restrictions are reshaping permissible solvent content, forcing reformulation investments that favor waterborne and high-solids technologies. FDA does not regulate refinish coatings, but OSHA workplace exposure standards govern spray booth operations and technician respiratory protection. The EU F-Gas Regulation and evolving MEE standards in China add compliance layers for drying and curing equipment. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certify cross-border product lines.
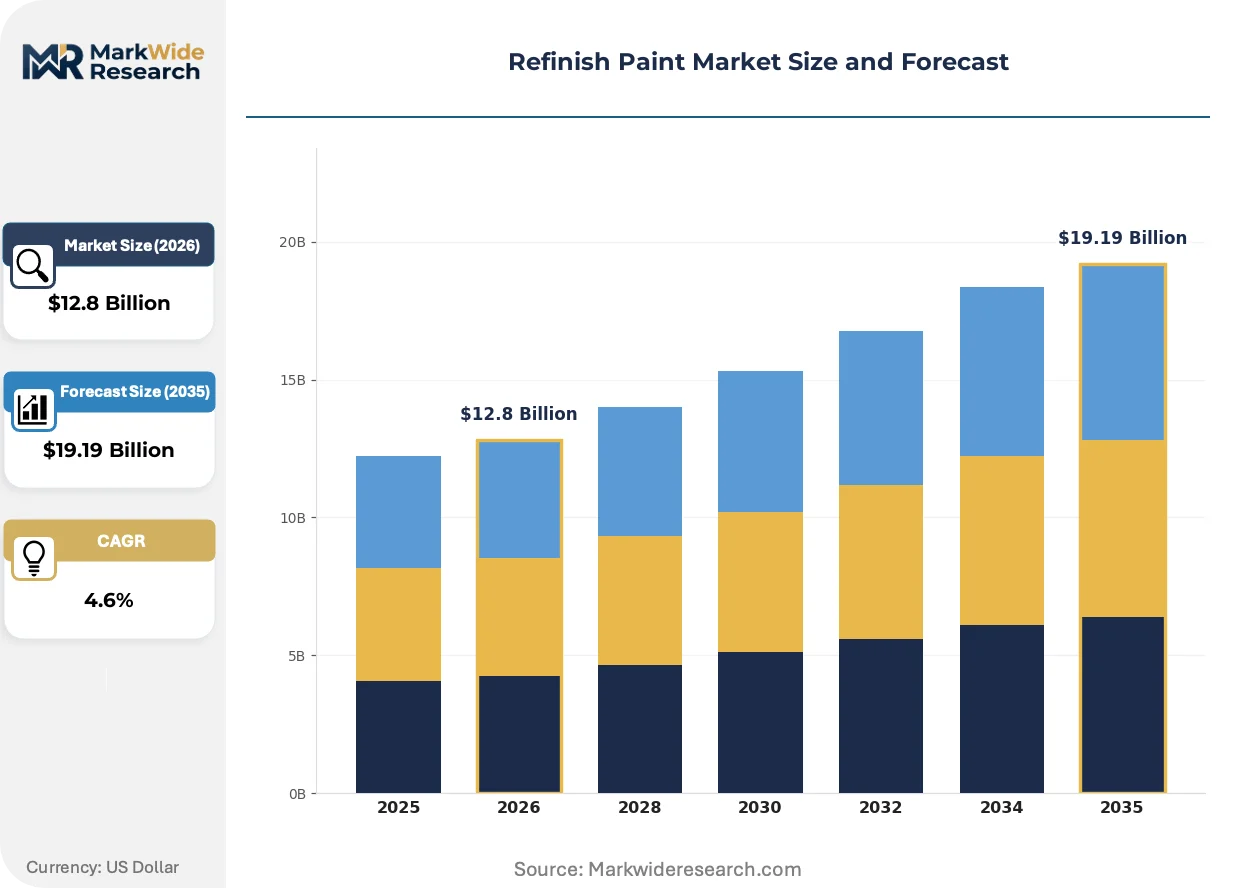
Market Dynamics
Waterborne formulation mandates under EPA and REACH protocols are compressing solvent-based volumes while forcing capital retooling across coating facilities. Collision centers now drive professional demand as vehicle age rises across major economies.
Growth Catalysts
- EPA VOC regulations:Compliance deadlines accelerate waterborne conversion investments in US collision networks, expanding addressable market for compliant formulations.
- Passenger vehicle parc expansion:China's sustained fleet growth generates refinish throughput at scale, anchoring regional volume for basecoat-clearcoat systems.
- Modular tint-and-dispense systems:On-demand color matching reduces inventory carrying costs for independent body shops, shifting procurement toward basecoat packages.
Market Restraints
- Petrochemical feedstock volatility:Acrylic resin and isocyanate hardener costs fluctuate with crude derivatives, squeezing formulation margins unpredictably.
- Supply concentration in titanium dioxide:Chinese producers dominate chloride-route TiO2, creating geographic single-source risk for white pigment supply.
- REACH substance restrictions:ECHA candidate list expansions threaten legacy crosslinkers, forcing reformulation cycles before amortization of prior R&D.
Strategic Opportunities
- India's underpenetrated collision network:Organized body shop chains remain below 15% of repair volume, creating first-mover whitespace for branded refinish systems.
- EU F-Gas Regulation:Infrared and UV-curing equipment upgrades qualify for green transition financing, opening equipment-paint bundled sales channels.
- Digital color-matching convergence:Spectrophotometer-to-cloud integration enables remote formula verification, reducing technician skill barriers in emerging markets.
Industry Challenges
- Certified spray booth technician shortage:OSHA respiratory protection compliance and EPA NESHAP training requirements outpace vocational pipeline output.
- Legacy solvent inventory stranding:State-level VOC rule acceleration in California and New York forces write-downs of non-compliant stock before regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refinish Paint Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Urethane, Enamel, Solvent-Based Application: Automotive, Furniture, Industrial, Marine Formulation: Single-Stage, Two-Stage, Waterborne, Powder End User: Professional, DIY, Workshops, Collision Centers |
| Companies Covered | Axalta Coating Systems, PPG Industries, BASF SE, AkzoNobel, The Sherwin-Williams Company, Nippon Paint Holdings, Kansai Paint, KCC Corporation, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refinish Paint Market Emerging Trajectories
Digital infrastructure and regulatory chemistry mandates are restructuring how refinish coatings are formulated, distributed, and applied across collision networks.
UV-curable clearcoat systems are rewriting throughput economics in high-volume collision centers. Tier-one automotive repair chains in Germany and Japan adopt these technologies to compress cycle times below four hours. The technology is rewriting labor allocation models by reducing booth occupancy and enabling same-day vehicle delivery.
REACH authorization requirements for chromium trioxide in corrosion primers are forcing conversion to trivalent and organic alternatives. ECHA sunset date pressures concentrate reformulation investment in 2024-2027. European commercial fleet refinish operations face the steepest compliance cost curves, accelerating supplier consolidation.
Collision centers now unbundle paint procurement from body labor, negotiating direct supply agreements with manufacturers rather than distributor intermediaries. Large multi-shop operators in Texas and Florida lead this disintermediation, extracting volume rebates and technical support commitments previously captured by jobbers. The shift compresses distributor margins while rewarding direct distribution infrastructure.
Refinish Paint Market Segmentation
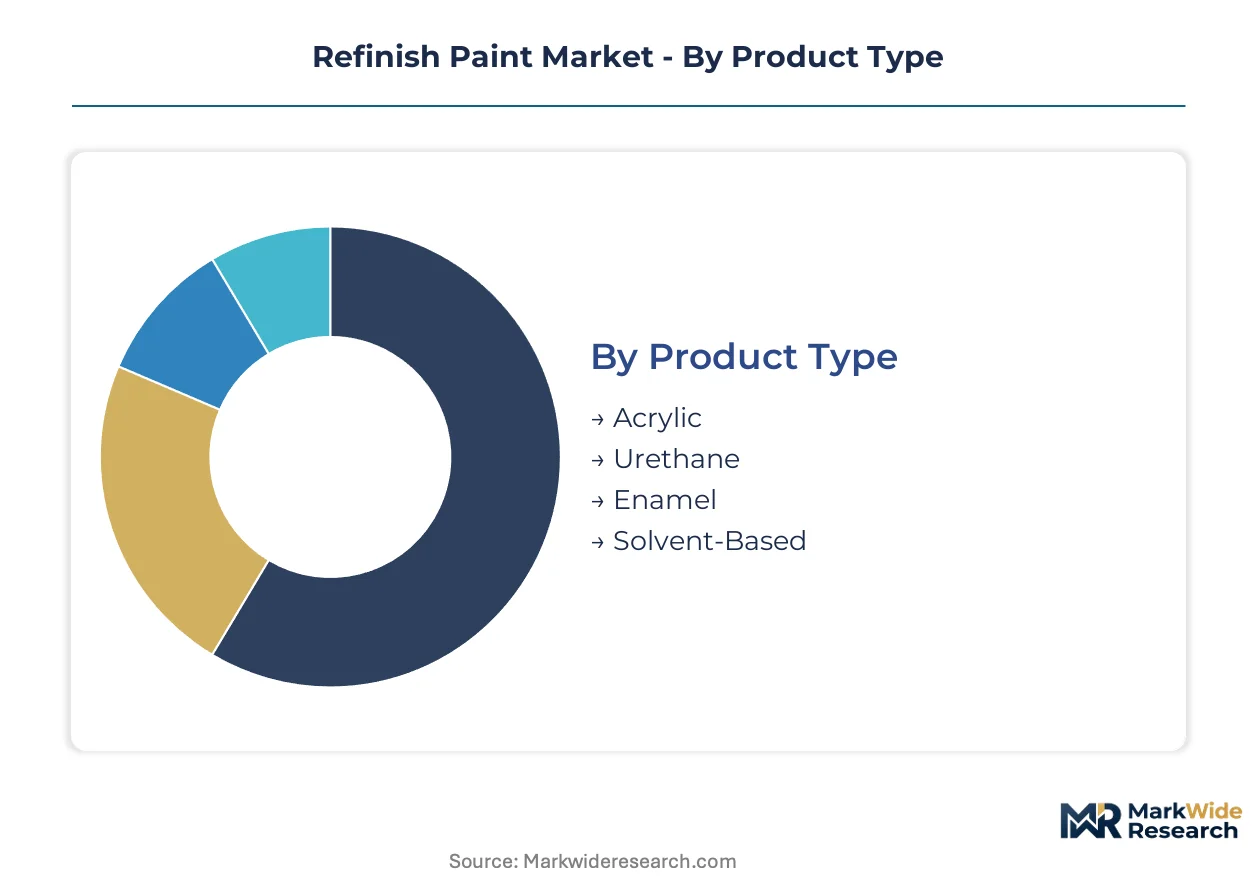
Refinish paint segmentation tracks how repair cycles, regulatory deadlines, and substrate requirements reshape procurement patterns across professional and consumer channels. Upgrade timelines for coating equipment and reformulation investments concentrate demand in specific product categories.
Product Type:
Replacement-cycle dynamics favor formulations that align with booth retooling schedules and VOC compliance deadlines.
- Acrylic:Waterborne acrylic systems now dominate basecoat formulations in regulated markets, with solids content optimized for EPA-compliant spray equipment. Collision centers in California and New York prioritize acrylic conversions to meet state-level VOC acceleration timelines.
- Urethane:Two-component urethane clearcoats deliver superior gloss retention and chemical resistance for premium automotive repair. Demand concentrates in high-throughput German and Japanese collision networks where cycle-time compression justifies material cost premiums.
- Enamel:Single-stage alkyd enamels retain share in furniture refinish and vintage automotive restoration where substrate compatibility outweighs durability requirements.
- Solvent-Based:Legacy solvent systems face volume compression under REACH and EPA mandates, surviving only in unregulated geographies and specialty restoration applications.
Acrylic sits at the top of the volume ranking, with urethane climbing the fastest.
Application:
Cost-tier stratification separates high-frequency automotive repair from episodic industrial and marine touch-up demand.
- Automotive:Passenger vehicle collision repair generates the highest throughput volume, with basecoat-clearcoat systems displacing single-stage finishes in metallic color matches. China's expanding vehicle parc sustains regional refinish demand at scale.
- Industrial:Epoxy-urethane hybrids protect heavy equipment and infrastructure assets against chemical exposure and abrasion. Maintenance schedules in manufacturing clusters drive recurring demand in Germany's Ruhr region and Japan's Chubu industrial corridor.
- Furniture:Nitrocellulose lacquers and catalyzed finishes serve antique restoration and high-end woodworking shops where hand-rubbed appearance commands price premiums.
- Marine:Isocyanate-cured polyurethane topside coatings resist UV degradation and saltwater immersion for yacht and commercial vessel maintenance in Mediterranean and Caribbean refit yards.
Automotive commands the largest revenue pool, while industrial applications gain share through preventive maintenance program expansion.
Formulation:
Application-method requirements and drying infrastructure determine procurement decisions across professional installer segments.
- Two-Stage:Basecoat-clearcoat separation enables precise color matching and repairability, now standard in OEM-certified collision networks. Waterborne two-stage systems capture volume in EPA-regulated US markets and REACH-governed EU territories.
- Waterborne:Low-VOC aqueous formulations require forced-air drying equipment, creating capital barriers for independent shops. Mandates in California, New York, and EU member states accelerate conversion timelines.
- Single-Stage:Combined color-and-gloss formulations persist in fleet refinish and commercial equipment where repair speed outweighs appearance matching.
- Powder:Thermoset powder coatings serve industrial component refinishing with zero VOC emissions, limited to bake-capable substrates and batch operations.
Two-stage formulations lead professional adoption, with waterborne systems expanding most quickly under regulatory pressure.
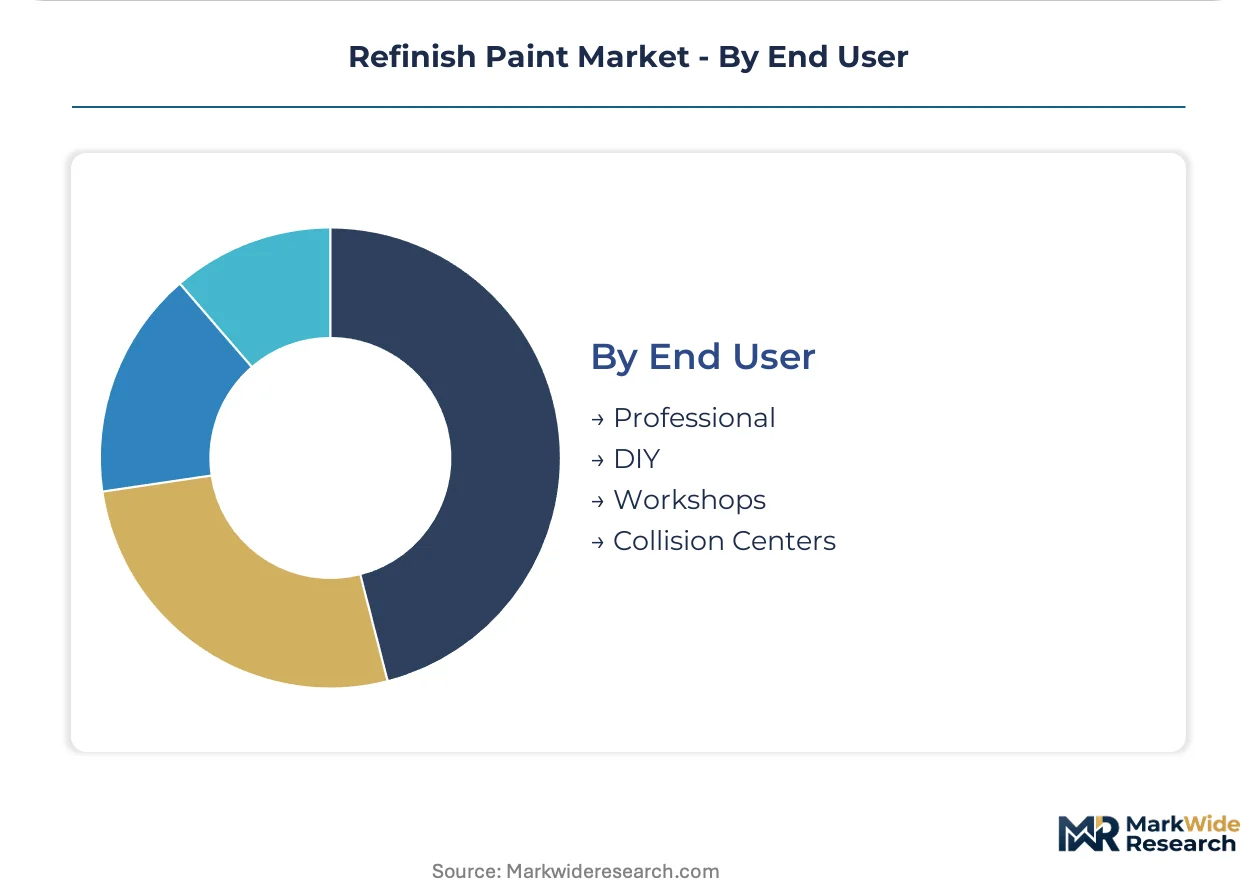
End User:
Customer-type segmentation reflects divergent technical capabilities, inventory carrying capacity, and compliance exposure.
- Collision Centers:Multi-shop operators and OEM-certified networks negotiate direct manufacturer agreements, bypassing traditional distributor channels. EPA NESHAP compliance and OSHA respiratory protection requirements concentrate procurement in certified professional channels.
- Professional:Independent body shops and refinish specialists balance inventory breadth against carrying costs, driving adoption of modular tint-and-dispense systems.
- Workshops:Fleet maintenance facilities and dealership service departments prioritize throughput over color complexity, favoring simplified mixing systems.
- DIY:Consumer aerosol and quart-size retail products serve scratch repair and small-project demand, with quality limitations excluding this channel from appearance-critical applications.
Collision centers anchor professional volume, with consolidated multi-shop operators gaining purchasing leverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive refinish coatings first achieved industrial scale in the United States during the post-war collision repair expansion of the 1950s. European and Asian markets subsequently developed distinct formulation traditions shaped by local environmental regulations and vehicle fleet characteristics.
United States
Collision centers in Texas and Florida now drive volume through direct manufacturer procurement agreements that bypass traditional distributor channels. EPA NESHAP compliance deadlines for spray booth operations accelerate capital investment cycles across multi-shop operators. The Gulf Coast petrochemical corridor near Houston anchors domestic resin supply for acrylic and urethane formulations serving North American collision networks.
Germany
Tier-one automotive repair chains adopt UV-curable clearcoat systems to compress cycle times below four hours in high-throughput operations. The EU F-Gas Regulation mandates infrared and UV-curing equipment upgrades that qualify for green transition financing. The Ruhr industrial corridor sustains demand for epoxy-urethane hybrids protecting heavy equipment against chemical exposure in manufacturing clusters.
China
Passenger vehicle parc expansion generates refinish throughput at scale, anchoring regional volume for basecoat-clearcoat systems. MEE standards add compliance layers for drying and curing equipment in collision networks across major metropolitan areas. The Yangtze River Delta concentration of automotive manufacturing sustains parallel demand for both OEM and aftermarket coating systems.
Japan
High-throughput collision networks in Kanto and Kansai regions justify material cost premiums for two-component urethane clearcoats delivering superior gloss retention. METI industrial standards govern formulation consistency across climate zones from Hokkaido to Kyushu. The Chubu industrial corridor around Nagoya maintains specialized demand for industrial equipment refinishing in precision manufacturing clusters.
India
Organized body shop chains remain below fifteen percent of repair volume, creating first-mover whitespace for branded refinish systems in Maharashtra and Gujarat. BIS certification requirements for automotive coatings create entry barriers that favor established formulation suppliers. The Delhi-NCR corridor concentrates fleet maintenance operations driving simplified mixing system adoption for throughput over color complexity.
Refinish Paint Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation technology and direct distribution control. The market structure concentrates around integrated coating suppliers with captive resin production and global color-matching infrastructure. Three archetypes dominate: multinational chemical conglomerates with backward integration into raw materials, specialized coating systems companies with regional distribution dominance, and diversified industrial materials suppliers with cross-selling capabilities. Competitive moves center on direct distribution bypass of traditional jobber networks and waterborne formulation conversion partnerships with collision center chains.
Among North American coating specialists, Axalta Coating Systems and PPG Industries exemplify the direct distribution archetype through manufacturer-to-collision-center supply relationships. BASF SE represents the integrated chemical conglomerate model with captive resin production sustaining formulation consistency. These three companies anchor the competitive structure through contrasting approaches to channel control and raw material integration.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| PPG Industries |
| BASF SE |
| AkzoNobel |
| The Sherwin-Williams Company |
| Nippon Paint Holdings |
| Kansai Paint |
| KCC Corporation |
| 3M |
| Others |
Supply Flow & Price Mechanics
Multi-shop collision center operators concentrate procurement leverage in North America, forcing a volume-rebate pricing model that rewards direct manufacturer relationships over distributor intermediaries. This buyer consolidation is compressing jobber margins while elevating formulation suppliers with captive technical support infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified collision networks from independent body shops and fleet maintenance facilities. Price differentiation hinges on certification grade and volume scale, with EPA NESHAP-compliant formulations commanding material premiums. Cost compression in the standard tier is intensifying because acrylic resin feedstock volatility squeezes formulation margins unpredictably. Fleet maintenance workshops exhibit highest price sensitivity, while German and Japanese tier-one collision networks prioritize throughput economics over unit cost.
Supply Chain Analysis
OEM certification requirements gate supplier access to premium collision center networks, creating qualification barriers that favor established formulation houses with technical validation infrastructure. Raw material supply concentrates in China for titanium dioxide chloride-route production, Germany for specialty isocyanate hardeners, and the US Gulf Coast for acrylic resin intermediates. Formulation consistency rests on captive resin production and spectrophotometer-to-cloud color infrastructure. Single-source vulnerability in Chinese TiO2 supply creates geographic concentration risk for white pigment. Distribution runs through direct manufacturer agreements with multi-shop operators, bypassing traditional jobber channels in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refinish paint market functions as a stable compounder anchored by collision repair demand from aging vehicle parcs across major economies. Regulatory-driven formulation conversions create recurring revenue streams for compliant suppliers.
For Market Incumbents: To counter distributor disintermediation by multi-shop operators, deepen direct technical service teams in high-volume collision corridors and secure captive resin production to insulate margin from petrochemical volatility. Prioritize waterborne conversion partnerships with EPA-regulated state networks to lock in compliance-driven switching costs. For New Entrants and Emerging Players: Digital color-matching convergence offers entry leverage into India's underpenetrated organized body shop segment, where BIS certification barriers favor technical partnerships over greenfield formulation investment. Target Maharashtra and Gujarat for first-mover whitespace, deploying spectrophotometer-to-cloud platforms that reduce technician skill barriers in emerging markets. For Investors and Strategic Acquirers: Chemical conglomerates with captive resin assets are the most active acquirer in this space, consolidating regional specialists to complete geographic coverage. The 5-10 year viability window favors targets with direct distribution infrastructure in high-growth collision corridors. Watch for MEE standard acceleration in China as inflection indicator for equipment-paint bundled sales expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation Conversion | EPA NESHAP compliance deadlines in California and New York accelerate capital investment cycles across collision networks. |
| Direct Distribution Bypass | Multi-shop operators in Texas and Florida extract volume rebates previously captured by traditional jobber intermediaries. |
| UV-Curing Equipment Bundling | EU F-Gas Regulation qualification for green transition financing opens integrated paint-equipment sales channels in Germany. |
| Digital Color-Matching Integration | Spectrophotometer-to-cloud platforms reduce technician skill barriers in India's emerging organized body shop segment. |
| Captive Resin Production Expansion | Backward integration into acrylic intermediates insulates margin from Gulf Coast petrochemical feedstock volatility. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with collision center procurement directors, formulation R&D leads, distributor channel partners, and EPA compliance officers with secondary validation. Trade data from customs records, ACC formulation reports, and SEC filings anchored volume estimates. Bottom-up segmentation triangulated against top-down macroeconomic drivers across the analysis window.
Segment-weighting applied product type, application method, end-user channel, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from regression against vehicle parc age curves and collision frequency data, with formulation conversion timelines modeled against EPA and REACH compliance deadlines. Waterborne adoption rates and tint-and-dispense system penetration served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines; deviation in VOC rule acceleration or feedstock cost spikes would shift conversion investment cycles. Forecasts reflect documented assumptions regarding collision center consolidation pace and equipment upgrade financing availability. A model refresh is warranted upon material change in MEE standard implementation or REACH authorization list expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market