
 Floor Paints Market | 2026-2036
Floor Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Paints Market Analysis
Aftermarket maintenance revenue is rewriting profit dynamics across the floor coatings value chain. PPG Industries leverages its service network to capture recurring refurbishment contracts in industrial facilities. Akzo Nobel N.V. anchors its position through specialized epoxy systems for chemical processing environments. Sika AG competes on construction-phase integration, bundling floor paints with waterproofing and sealing solutions.
Floor paints are polymer-based protective coatings formulated with binders, pigments, and functional additives, typically applied at dry film thicknesses of 100-500 microns to concrete, wood, or metal substrates for abrasion resistance and chemical protection. Epoxy formulations dominate industrial applications due to superior adhesion and solvent resistance, while polyurethane segments gain share in commercial settings requiring UV stability and aesthetic flexibility. Acrylic products occupy the residential tier, where ease of application and lower odor profiles align with consumer preferences for DIY renovation projects.
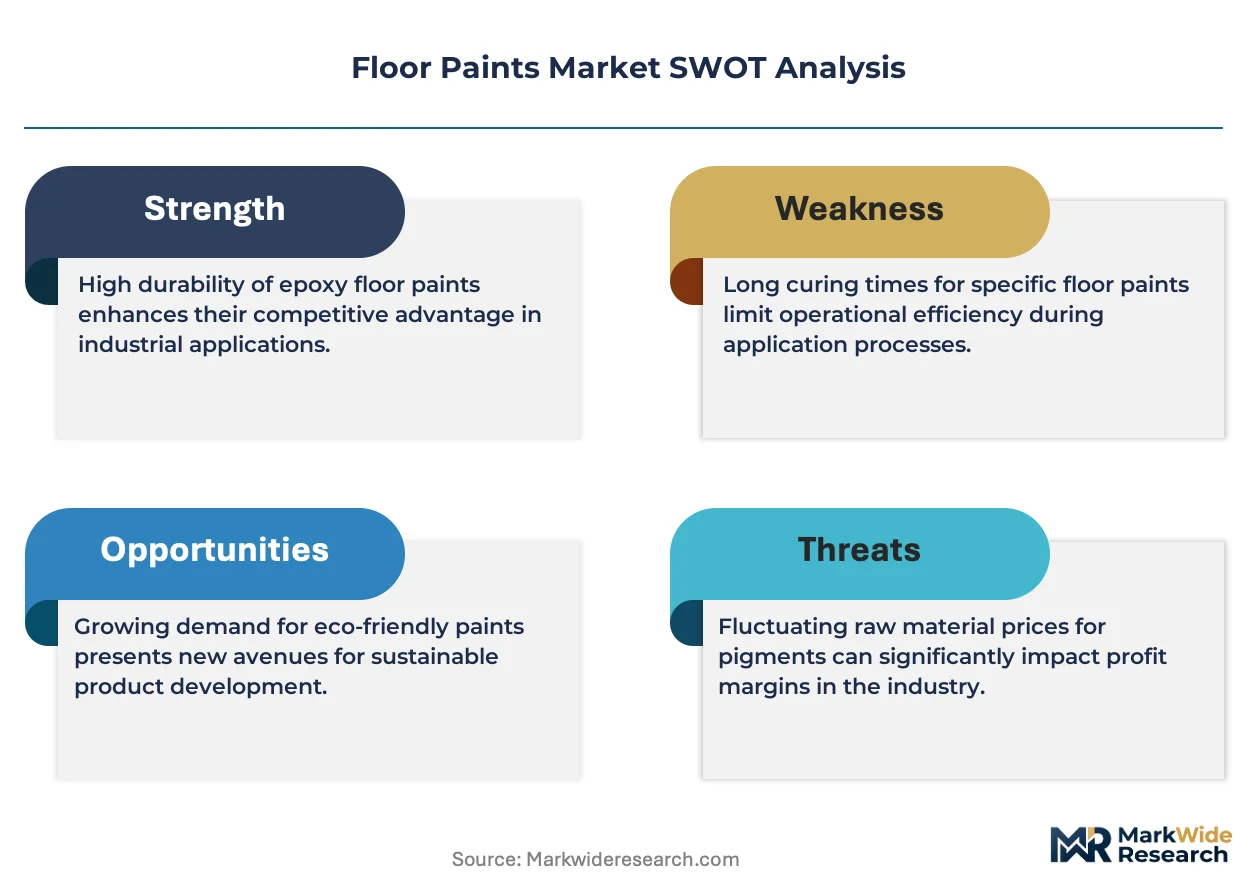
EPA regulations under the National Volatile Organic Compound Emission Standards for Architectural Coatings mandate VOC limits that push manufacturers toward water-borne technologies, while REACH restrictions on hazardous substances in Europe reshape raw material sourcing across the supply base. OSHA slip-resistance standards for workplace safety directly stimulate demand for anti-slip functionality segments in commercial and industrial applications. Stakeholders must weigh regulatory compliance investments against the margin compression from commodity acrylic competition in price-sensitive residential channels.
Market Dynamics
Water-borne epoxy technologies are compressing solvent-based margins as EPA VOC enforcement tightens and automotive OEMs mandate low-emission coating systems for new facility construction.
Growth Catalysts
- Automotive Assembly Plant Expansion:OEMs in China, Mexico, and Germany are specifying high-build epoxy systems for new paint shop floors, creating sustained specification pull for chemical-resistant formulations.
- REACH Article 57 Authorization:European restrictions on chromium VI in anti-corrosive primers are accelerating migration to alternative curing agents, expanding addressable market for compliant epoxy hardener suppliers.
- OSHA Walking-Working Surfaces Rule:US workplace safety mandates for slip-resistant flooring are driving specification of textured polyurethane and epoxy systems in food processing and pharmaceutical manufacturing facilities.
Market Restraints
- Bisphenol A Feedstock Concentration:Asian petrochemical complexes supply over 70% of global epoxy resin precursors, exposing Western formulators to freight cost volatility and tariff exposure.
- Cement Substrate Variability:Moisture vapor transmission rates in existing concrete slabs frequently exceed 3 lb/1000 sq ft/24 hr, causing adhesion failures that limit warranty coverage and repeat specification.
- Polyaspartic Substitution Threat:Fast-cure polyaspartic coatings are capturing commercial garage and retail floor maintenance contracts with 4-hour return-to-service performance that epoxy cannot match.
Strategic Opportunities
- India Industrial Corridor Buildout:Dedicated freight corridors and electronics manufacturing clusters under PLI scheme incentives are generating greenfield demand for heavy-duty industrial flooring systems.
- EU Green Deal Public Procurement:Mandatory environmental criteria in government construction tenders are creating specification advantage for water-borne and bio-based formulations with Environmental Product Declarations.
- Digital Color Matching + Direct-to-Applicator E-commerce:Pigment dispensing systems integrated with contractor mobile platforms are disintermediating traditional distributor color-mixing services and capturing specification data.
Industry Challenges
- Certified Applicator Shortage:ICRI and SSPC surface preparation and coating application credentials remain scarce in secondary US markets, constraining project throughput and warranty issuance.
- Multi-Layer System Integration Complexity:Specifiers must reconcile incompatible cure chemistries between moisture barrier primers, epoxy build coats, and polyurethane topcoats, increasing field failure risk and callback costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Paints Market |
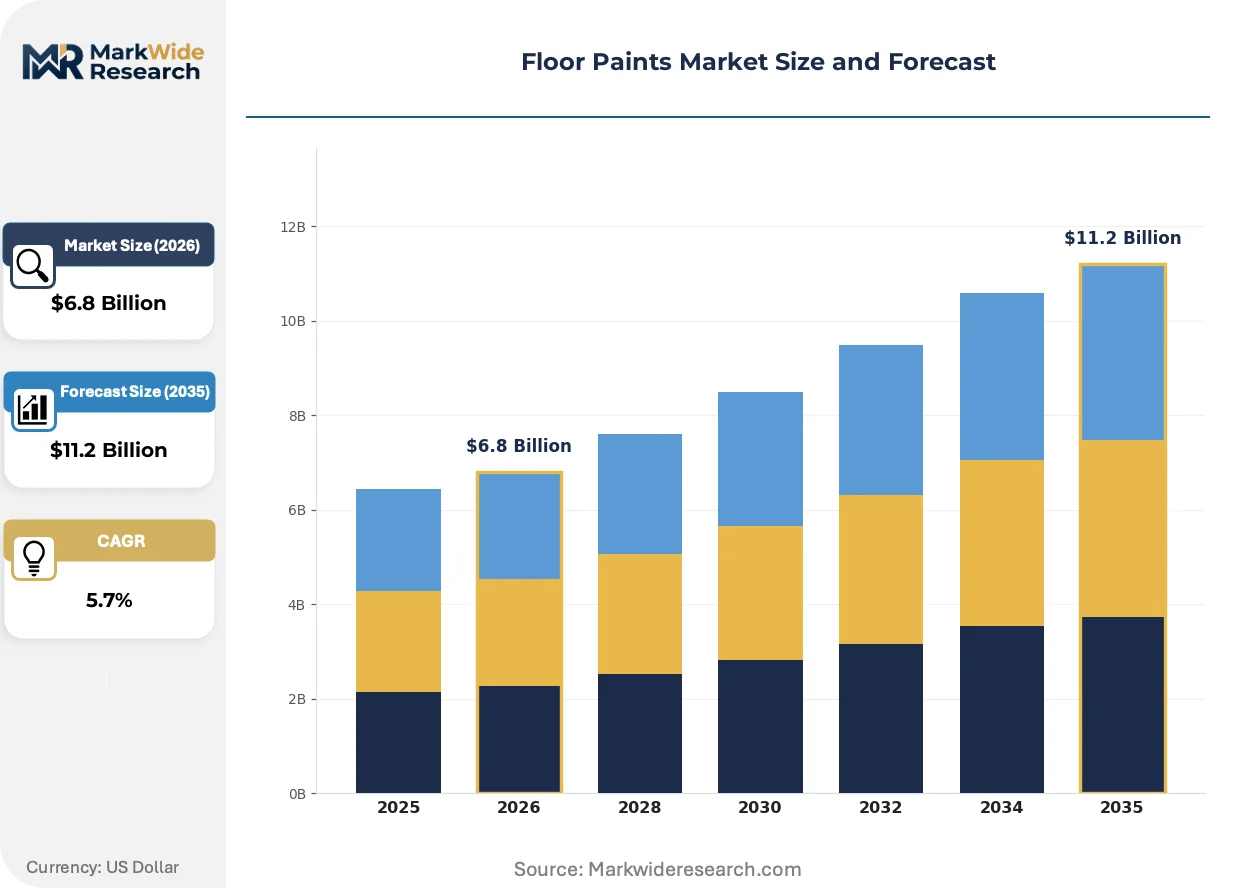
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Enamel Application: Residential, Commercial, Industrial, Automotive Functionality: Anti-slip, Waterproof, Chemical Resistant, UV Resistant Finish Type: Matte, Gloss, Satin, Semi-gloss |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, RPM International, BASF SE, Akzo Nobel N.V., Sika AG, Jotun, Asian Paints, Nippon Paint Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Paints Market Emerging Trajectories
Formulation chemistry and application methodology are converging to compress project timelines and eliminate solvent exposure. Three developments are restructuring competitive advantage.
Bio-based epoxy resins derived from lignin and plant oil feedstocks are achieving 40-60% renewable content while maintaining solvent resistance metrics. European automotive OEMs are qualifying these systems for new facility construction in Germany and Spain. Conventional petroleum-derived bisphenol A epoxies are rendering obsolete for premium sustainability-specified projects.
EPA National Volatile Organic Compound Emission Standards for Architectural Coatings are tightening subcategory limits for industrial maintenance coatings in 2025-2027 rulemaking cycles. Manufacturers are reformulating high-solids and water-borne alternatives to maintain compliance without sacrificing film build. The industrial maintenance segment is absorbing reformulation costs through specification premiums rather than volume sacrifice.
Facility maintenance managers are consolidating coating procurement under single-source performance contracts that bundle surface preparation, application, and warranty coverage. Traditional material-only supply relationships are losing share to turnkey service providers in US commercial real estate and German manufacturing sectors. This model shift is most advanced in multi-site retail and logistics portfolios where standardization reduces total cost of ownership calculations.
Floor Paints Market Segmentation
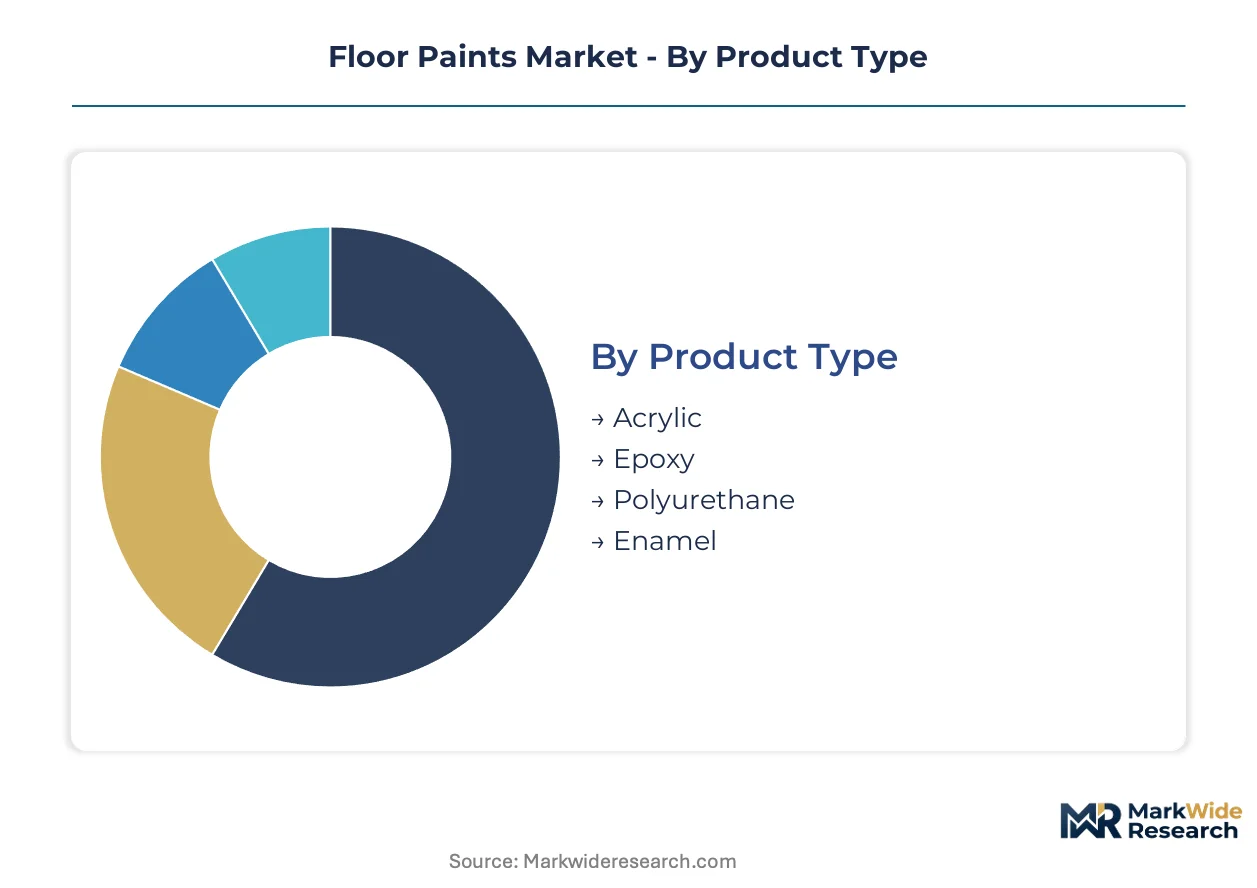
Floor paints segmentation reflects divergent performance requirements across substrate conditions, exposure severity, and aesthetic priorities. Formulators must align resin chemistry, film build, and cure speed to specific end-use duty cycles rather than pursuing universal solutions.
Product Type:
Epoxy formulations anchor industrial duty cycles where chemical exposure and mechanical abrasion dominate specification criteria.
- Epoxy:Two-component thermosetting systems built from bisphenol A or bisphenol F resins with polyamine hardeners deliver 100-500 micron dry film thickness and superior solvent resistance. Automotive assembly plants in Germany and China specify high-build epoxy for paint shop floors where brake fluid and solvent exposure are routine, though moisture vapor transmission limits in older concrete substrates constrain warranty terms.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems provide UV stability and color retention for commercial environments where aesthetic durability matters. Retail chains in US shopping malls favor polyurethane topcoats over epoxy primers for showroom floors requiring gloss maintenance under fluorescent and LED lighting cycles.
- Acrylic:Water-borne emulsion polymers serve residential renovation with low-odor application and soap-water cleanup, sacrificing chemical resistance for convenience.
- Enamel:Solvent-borne alkyd and modified acrylic systems retain share in light industrial maintenance where rapid recoat and equipment touch-up dominate over heavy-duty performance.
The dominant share belongs to epoxy, while polyurethane is closing the gap fastest.
Application:
End-use concentration tracks manufacturing investment cycles and commercial real estate development velocity.
- Industrial:Chemical processing, food manufacturing, and electronics assembly facilities specify high-performance systems with thermal shock resistance and cleanroom compatibility. India's PLI scheme incentives for semiconductor and pharmaceutical manufacturing are generating greenfield demand for heavy-duty flooring across Gujarat and Tamil Nadu industrial corridors.
- Automotive:OEM paint shops and assembly lines require conductive and chemical-resistant coatings integrated with ESD protection and spill containment. Mexico's automotive manufacturing expansion near Monterrey and Silao is pulling specification of specialized epoxy formulations from US and European suppliers.
- Commercial:Office buildings, retail spaces, and healthcare facilities balance durability with design flexibility, driving demand for decorative flake and metallic finish systems.
- Residential:Garage floor coatings and basement waterproofing represent the price-sensitive tier where DIY application and big-box retail distribution dominate procurement.
Industrial applications command premium pricing, with automotive expanding most quickly on facility buildouts.
Functionality:
Regulatory mandates and liability exposure are elevating functional performance from optional upgrade to baseline specification.
- Chemical Resistant:Formulations with enhanced crosslink density and fluoropolymer modification withstand acids, alkalis, and solvents in battery manufacturing and pharmaceutical processing. REACH restrictions on chromium VI are accelerating migration to compliant epoxy hardener systems across European chemical processing facilities.
- Anti-slip:Textured aggregates and aluminum oxide additives embedded in urethane and epoxy matrices satisfy OSHA Walking-Working Surfaces Rule requirements for slip-resistant flooring in food processing and pharmaceutical manufacturing.
- Waterproof:Moisture-tolerant primers and vapor barrier systems address concrete substrates with elevated moisture vapor emission rates, extending warranty coverage in below-grade applications.
- UV Resistant:Aliphatic polyurethane and acrylic topcoats prevent chalking and color shift in atrium, showroom, and outdoor pedestrian bridge applications.
Chemical resistance leads specification value, though anti-slip is gaining share fastest on regulatory enforcement.
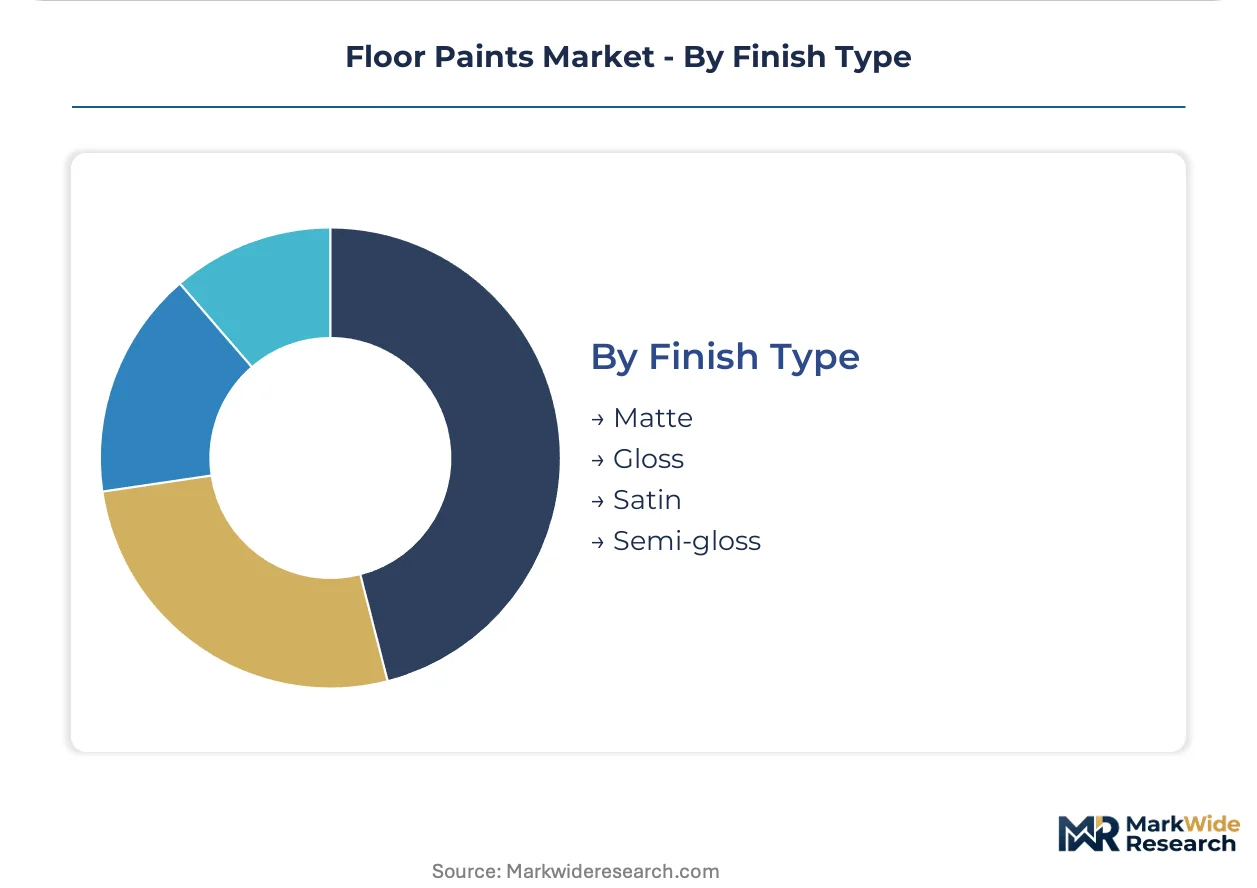
Finish Type:
Aesthetic preference and maintenance protocol determine gloss level selection across exposure environments.
- Gloss:High-reflectance finishes maximize light distribution in warehouses and manufacturing floors while facilitating spill detection and cleaning verification.
- Semi-gloss:Balanced sheen hides substrate imperfections better than full gloss while retaining cleanability, dominating healthcare and educational facility specifications.
- Satin:Low-sheen surfaces minimize glare in commercial office environments and residential basements where visual comfort competes with durability.
- Matte:Flat finishes conceal wear patterns and substrate irregularities in high-traffic retail and hospitality settings where frequent recoating is impractical.
Gloss finishes retain the dominant position, with semi-gloss climbing fastest on healthcare sector expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes floor paints primarily for industrial greenfield construction, while the United States emphasizes aftermarket refurbishment and regulatory compliance upgrades. Germany anchors European specification standards for chemical-resistant systems. Mexico and India represent the fastest-expanding installation bases on manufacturing relocation trends.
China
Automotive assembly plant construction in Shanghai and Guangdong provinces drives specification of high-build epoxy systems for paint shop floors. MEE enforcement of dual carbon goals accelerates water-borne formulation adoption across state-owned industrial facilities. The Yangtze River Delta concentration of electronics manufacturing clusters sustains demand for cleanroom-compatible polyurethane coatings in semiconductor fabrication plants.
United States
OSHA Walking-Working Surfaces Rule enforcement stimulates anti-slip coating retrofits in food processing facilities across the Midwest and Southeast. EPA VOC regulations under the National Emission Standards compel reformulation of industrial maintenance coatings toward compliant water-borne alternatives. The Houston petrochemical corridor and Detroit automotive belt represent concentrated demand zones for chemical-resistant flooring systems.
Germany
REACH Article 57 Authorization restrictions on chromium VI in anti-corrosive primers force migration to compliant epoxy hardener systems. EU Green Deal public procurement mandates create specification preference for bio-based formulations with Environmental Product Declarations. Bavarian automotive OEMs and Baden-Württemberg machinery manufacturers qualify sustainable coating systems for new facility construction.
Mexico
OEM paint shop construction near Monterrey and Silao pulls specialized epoxy formulations for brake fluid and solvent exposure environments. Nearshoring incentives under the IMMEX program accelerate industrial facility buildouts across Nuevo León and Guanajuato. The Bajío Region electronics manufacturing clusters generate parallel demand for ESD-protected conductive flooring systems.
India
PLI scheme incentives for semiconductor and pharmaceutical manufacturing generate greenfield demand across Gujarat and Tamil Nadu industrial corridors. BIS certification requirements for construction chemicals create compliance barriers for imported formulations. Dedicated freight corridor development sustains heavy-duty flooring consumption in warehousing and logistics facilities near Delhi-Mumbai Industrial Corridor nodes.
Floor Paints Market Vendor Landscape
Capability concentration sits with specialty chemical formulators possessing resin synthesis expertise; scale advantage sits with diversified coatings conglomerates commanding raw material procurement leverage. The market structures around three tiers: multinational integrated suppliers, regional formulation specialists, and construction-chemical bundlers. Dominant competitive moves include backward integration into epoxy resin production and strategic partnerships with certified applicator networks to capture specification data and warranty relationships.
Within the multinational integrated tier, PPG Industries, Akzo Nobel N.V., and Sika AG occupy positions that exemplify divergent strategic vectors. PPG Industries represents the service-network archetype, leveraging aftermarket maintenance contracts to secure recurring revenue streams. Akzo Nobel N.V. anchors the specialty-formulation position, emphasizing compliant systems for regulated chemical processing environments. Sika AG exemplifies construction-phase integration, bundling floor coatings with adjacent waterproofing and sealing solutions to capture specification during initial buildout rather than refurbishment cycles.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries |
| RPM International |
| BASF SE |
| Akzo Nobel N.V. |
| Sika AG |
| Jotun |
| Asian Paints |
| Nippon Paint Holdings |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight differentials amplify cost asymmetries between Asian epoxy resin suppliers and Western formulators, compressing margins on water-borne formulations while rewarding backward-integrated producers with captive bisphenol A supply. This logistics chokepoint concentrates pricing power among petrochemical complexes in Jiangsu and Zhejiang provinces, forcing independent coaters to absorb tariff volatility or cede specification share to construction-chemical bundlers.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and specialty formulators, insulating volume commitments from spot resin volatility while project-based pricing governs commercial refurbishment cycles. Price differentiation hinges on certification tier (ICRI surface preparation credentials, SSPC applicator status) and after-sales warranty bundling. Cost compression in residential acrylic tiers intensifies as big-box retailers consolidate private-label sourcing. Industrial buyers exhibit lowest price sensitivity due to total cost of ownership calculations, while DIY residential segments demand economy-grade alternatives.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for Western formulators dependent on Asian epoxy resin precursors. Raw material sourcing concentrates on bisphenol A feedstock from Jiangsu province petrochemical complexes, polyamine hardeners from German specialty chemical producers, and titanium dioxide pigments from Chinese sulfate-process plants. Distribution runs through construction-chemical distributors and direct-to-applicator digital platforms, with certified applicator networks increasingly controlling specification gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified applicator scarcity constrains market expansion more than formulation capacity, creating asymmetric returns for stakeholders who control surface preparation credentials and warranty issuance capabilities.
For Market Incumbents: Harden specification lock-in through captive applicator certification programs that bundle ICRI credentials with proprietary coating systems. Deepen upstream control over epoxy resin production in Jiangsu corridor facilities to neutralize freight cost volatility. Polyaspartic substitution threats in commercial garage segments demand accelerated R&D in fast-cure epoxy alternatives. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-driven pharmaceutical manufacturing corridor where BIS certification barriers filter out established multinational competition. Target Gujarat and Tamil Nadu industrial zones with moisture-tolerant primer systems addressing local concrete substrate variability. Go-to-market traction requires partnership with domestic construction-chemical distributors possessing existing government tender relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected flooring divisions lacking service-network integration. Long-term viability centers on recurring refurbishment revenue streams rather than construction-phase material supply. Monitor EPA VOC rulemaking enforcement intensity as inflection signal for water-borne technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Network Certification | ICRI-credentialed contractor partnerships secure specification data and warranty relationships in industrial refurbishment. |
| Backward Integration into Epoxy Resin | Captive bisphenol A production neutralizes Shanghai-Ningbo freight volatility and tariff exposure. |
| Water-Borne Formulation Transition | EPA VOC compliance investments capture automotive OEM mandates for low-emission facility construction. |
| Digital Direct-to-Applicator Platform | Pigment dispensing systems disintermediate traditional distributor color-mixing services and capture project data. |
| Moisture-Tolerant Primer Development | Extended warranty coverage addresses concrete substrates with elevated vapor transmission rates in existing facilities. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, EPA enforcement disclosures, and REACH authorization filings. Primary inputs drew from coating formulator R&D directors, certified applicator network managers, automotive OEM facility engineering leads, and construction-chemical procurement officers at industrial distributors. Secondary validation incorporated SEC 10-K segment disclosures, BIS certification registries, and PLI scheme implementation reports. Bottom-up project pipeline assessment triangulated against top-down resin consumption estimates.
Forecast inputs considered resin chemistry segmentation, substrate condition severity, and end-use duty cycle requirements across the projection horizon. Modeled dimensions spanned product type, application vertical, functional performance tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating automotive buildout cycles and refurbishment replacement rates. Specific inputs included MEE dual carbon enforcement trajectory and OSHA Walking-Working Surfaces Rule adoption velocity.
Sensitivities concentrate around REACH Article 57 authorization scope expansion and polyaspartic cure technology advancement timelines. Forecasts reflect assumptions on certified applicator pipeline development and moisture barrier primer efficacy improvements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
India Paints and Coatings Market