
 Global Thinners and Paint Strippers Market | 2026-2036
Global Thinners and Paint Strippers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thinners and Paint Strippers Market Foresight
Asset-light toll manufacturing and third-party solvent recovery leasing is reconfiguring capital requirements for new entrants in the thinners and paint strippers sector. BASF leverages its integrated petrochemical feedstock network to secure cost-advantaged raw material positions across European production hubs. Sherwin-Williams Company anchors North American distribution through its captive retail and professional contractor channels. Akzo Nobel navigates regulatory complexity by maintaining dedicated formulation labs in multiple jurisdictions.
Thinners and paint strippers comprise formulated solvent blends—typically incorporating acetates, glycol ethers, aromatic hydrocarbons, or caustic alkalis—engineered to reduce coating viscosity for application or chemically degrade cured paint films for substrate restoration. Solvent-based thinners sustain dominant volume share in automotive refinishing and marine coating applications where evaporation rate control and substrate compatibility remain critical performance parameters. Water-based thinners are gaining formulation share in wood finishing as VOC regulations tighten across industrialized economies. Bio-based thinners occupy emerging niche positions where aerospace maintenance facilities and premium shipyards seek exempt-status products for enclosed-space applications.
EPA NESHAP standards, EU REACH restrictions on methylene chloride, and China's GB standards on volatile organic compound content collectively determine permissible chemistries and compliance costs across major demand centers. Product registration burdens favor incumbents with established toxicology dossiers and reformulation pipelines. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate stranded inventory risks and prioritize multi-standard certification investments.
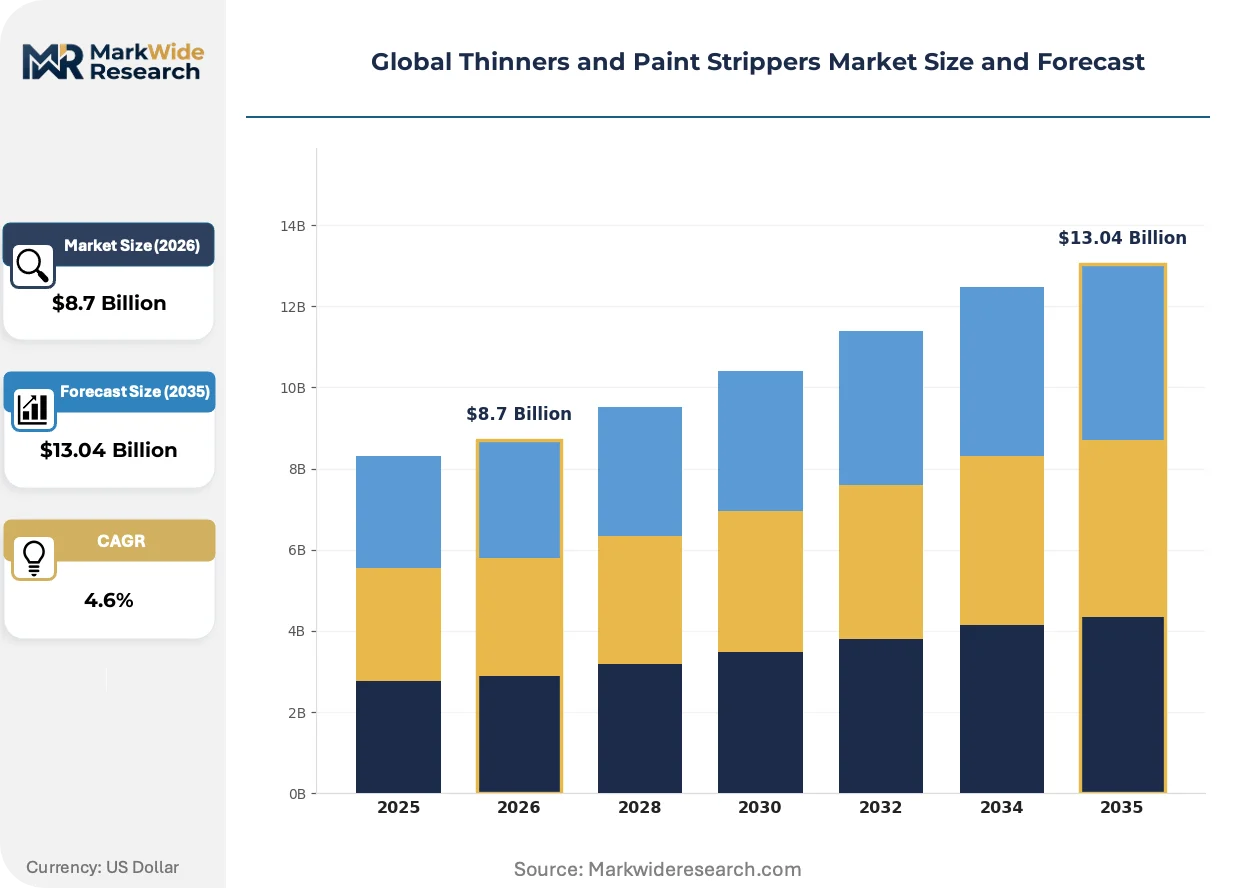
Market Dynamics
Regulatory divergence across major economies is fragmenting formulation standards and forcing manufacturers to maintain parallel product portfolios, with the EPA's NESHAP revisions, EU REACH methylene chloride restrictions, and China's GB VOC standards creating incompatible compliance zones that reshape competitive economics.
Growth Catalysts
- Shipyard maintenance volumes:China's domestic maritime repair sector is expanding solvent consumption as local paint manufacturers upgrade formulation capabilities and replace imported thinners with certified domestic alternatives.
- Automotive solvent recycling:EPA NESHAP compliance pressures are pushing refinishing shops toward closed-loop solvent recovery systems that reduce disposal costs and extend chemical lifecycles.
- Bio-based exemption status:Aerospace maintenance facilities in enclosed-space applications are sourcing exempt-status bio-thinners to bypass VOC permitting requirements while maintaining substrate compatibility.
Market Restraints
- Feedstock cost volatility:Aromatic hydrocarbon and acetate feedstocks track crude oil and natural gas derivatives, compressing margin stability for formulated product manufacturers.
- Registration dossier burdens:EU REACH toxicology requirements and EPA new chemical notifications favor incumbents with established data packages, raising barriers for novel solvent introductions.
- Water-based performance gaps:Evaporation rate control and substrate adhesion limitations restrict water-based thinners to wood finishing and light industrial applications, preserving solvent dominance in marine and automotive sectors.
Strategic Opportunities
- Toll manufacturing penetration:Asset-light toll manufacturing and third-party solvent recovery leasing reduce capital requirements for new entrants seeking regional formulation presence without captive production assets.
- Multi-standard certification:Regulatory divergence between EPA, ECHA, and SAMR jurisdictions creates premium positioning for products certified across all three compliance zones, commanding price premiums from multinational coating manufacturers.
- Professional contractor channels:Captive distribution through dedicated professional channels bypasses commoditized retail thinners, capturing higher-margin specification-driven demand in refinishing and restoration segments.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in solvent blend optimization for regulatory compliance across multiple jurisdictions concentrates within incumbent technical teams, constraining new entrant R&D velocity.
- Reformulation pipeline timelines:Multi-year toxicology testing and registration dossier compilation for replacement chemistries strand existing inventories when bans take effect, requiring parallel production runs during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thinners and Paint Strippers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based Thinners, Water-Based Thinners, Paint Removers, Caustic Strippers, Bio-Based Thinners Application: Wood Finishing, Metal Coatings, Automotive Refinishing, Marine Coating, Aerospace Maintenance End User: Paint Manufacturers, Industrial Coaters, Vehicle Maintenance Centers, Shipyards, Aerospace Facilities Packaging Type: Drums, Cans, Bottles, Aerosol Containers, Bulk Containers |
| Companies Covered | Akzo Nobel, PPG Industries, Sherwin-Williams Company, 3M, BASF, Henkel AG & Co. KGaA, Jotun, Nippon Paint, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thinners and Paint Strippers Market Shifts & Advancements
Formulation chemistry is diverging along regulatory fault lines while digital tools compress specification-to-procurement cycles, creating parallel tracks of compliance-first innovation and operational efficiency gains.
Supercritical CO2 stripping technology is migrating from aerospace maintenance facilities into premium marine and heritage restoration applications where substrate preservation and zero-VOC operation justify capital intensity. German shipyards and Dutch heritage contractors are piloting mobile units for enclosed-space paint removal. The technology is compressing demand for traditional methylene chloride and NMP-based strippers in high-value segments while remaining cost-prohibitive for volume industrial markets.
EU REACH restrictions on methylene chloride and N-methyl-2-pyrrolidone are forcing reformulation across decorative paint stripping and industrial coating removal segments. The industrial consequence is accelerated substitution toward benzyl alcohol, dimethyl glutarate, and bio-derived ester blends with inferior stripping kinetics but favorable toxicology profiles. Professional restoration contractors in France and Italy are absorbing higher per-unit chemical costs while residential DIY segments shift toward mechanical methods, bifurcating the stripper category by application value.
Specification-driven procurement through digital coating platforms is consolidating buyer power among large fleet operators and industrial maintenance contractors. BASF and Akzo Nobel direct-to-contractor portals are disintermediating traditional distributor inventory positions, compressing working capital requirements for buyers while exposing smaller regional blenders to price transparency pressure. This channel shift is most visible in North American automotive refinishing and German industrial coating maintenance, where fleet-scale buyers negotiate annual solvent supply agreements indexed to feedstock benchmarks.
Global Thinners and Paint Strippers Market Segmentation
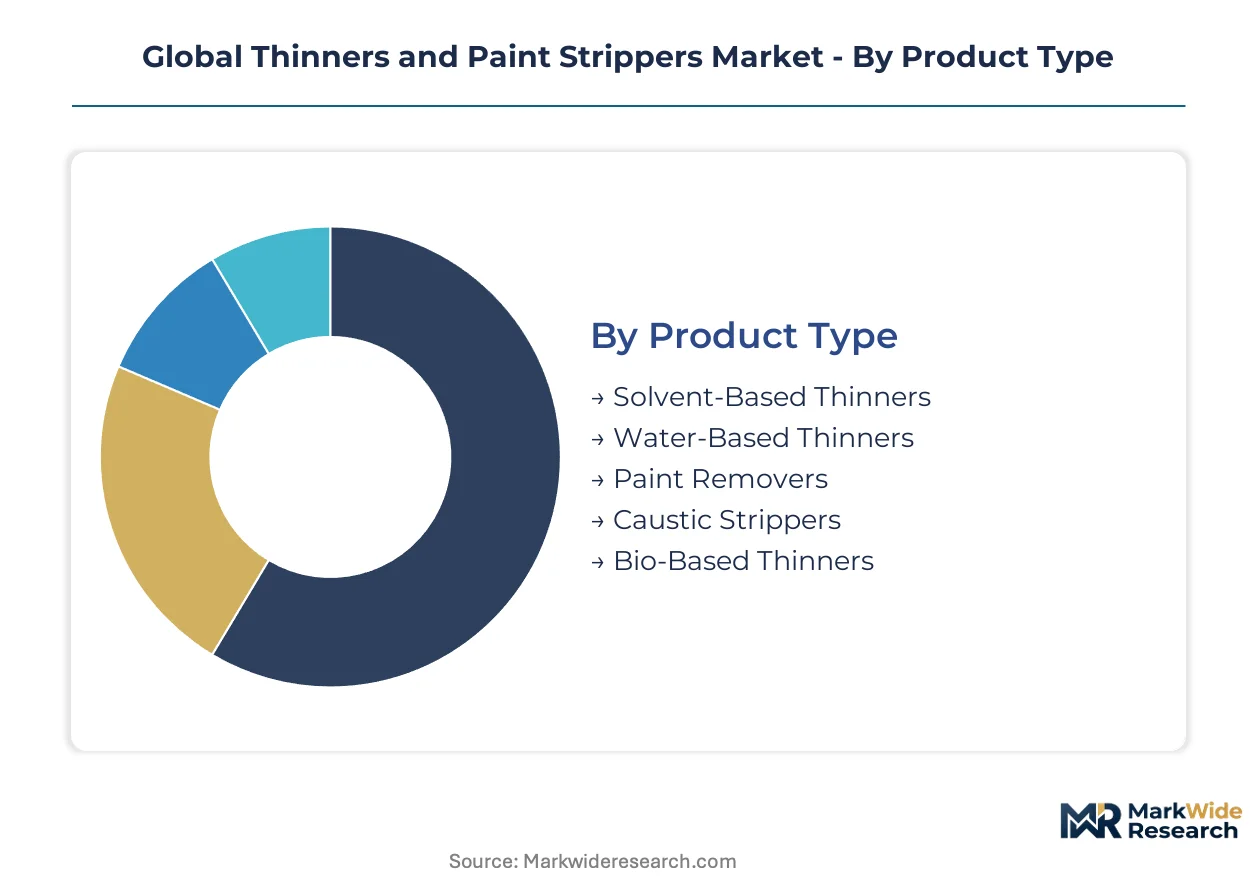
Formulation chemistry diverges sharply across use cases in the thinners and paint strippers sector. Regulatory compliance zones and substrate compatibility requirements fragment demand into distinct technical specifications. Understanding these segment boundaries reveals where capital deployment and R&D investment concentrate.
Product Type:
Use cases span from high-performance industrial coating removal to low-VOC residential applications, with formulation chemistry calibrated to evaporation rates, substrate sensitivity, and enclosed-space safety requirements.
- Solvent-Based Thinners:Blends of aromatic hydrocarbons, acetates, and glycol ethers deliver controlled evaporation rates essential for automotive refinishing and marine coating applications. Demand concentrates in German automotive refinishing clusters and Chinese shipyards where substrate compatibility and film formation speed outweigh VOC regulatory pressure.
- Paint Removers:Methylene chloride, N-methyl-2-pyrrolidone, and benzyl alcohol formulations chemically degrade cured paint films for substrate restoration. Professional restoration contractors in France and Italy absorb higher per-unit chemical costs as EU REACH restrictions force substitution toward dimethyl glutarate and bio-derived ester alternatives.
- Water-Based Thinners:Acrylic and polyurethane dispersion carriers reduce VOC content for wood finishing applications in regulated jurisdictions.
- Caustic Strippers:Sodium hydroxide formulations target heavy industrial coatings on metal substrates where substrate etching is acceptable.
- Bio-Based Thinners:Agricultural ester and terpene-derived solvents qualify for exempt status under EPA and EU VOC regulations.
Established volume favors solvent-based formulations; emerging adoption favors bio-based alternatives gaining exempt-status positioning.
Application:
Substrate material and coating chemistry dictate thinner selection, with performance requirements varying across porous wood, reactive metal, and thermally sensitive aerospace composites.
- Automotive Refinishing:Clearcoat and basecoat compatibility demands precise solvent blend ratios to prevent marring or solvent popping. EPA NESHAP compliance pressures in the United States push refinishing shops toward closed-loop solvent recovery systems that extend chemical lifecycles and reduce disposal costs.
- Aerospace Maintenance:Enclosed-space applications and substrate preservation requirements favor low-toxicity, slow-evaporating formulations. Supercritical CO2 stripping technology is migrating from United States maintenance facilities into German and Dutch heritage restoration applications where zero-VOC operation justifies capital intensity.
- Wood Finishing:Lacquer and varnish thinning for furniture and cabinetry applications drives water-based formulation adoption.
- Metal Coatings:Industrial maintenance and protective coating applications require aggressive solvent power for epoxy and polyurethane systems.
- Marine Coating:Antifouling and protective coating removal in shipyard environments demands high-flash-point formulations for safety compliance.
Volume gravity centers on automotive refinishing; steepest expansion trajectory appears in aerospace maintenance as exempt-status bio-formulations penetrate enclosed-space protocols.
End User:
Procurement scale and specification authority separate captive formulation users from merchant market buyers, reshaping channel economics and technical service requirements.
- Industrial Coaters:Continuous coating lines and batch operations consume formulated thinners at scale, with specification authority concentrated among maintenance engineers. Digital procurement platforms are consolidating buyer power among large fleet operators in North America and Germany, compressing working capital requirements while exposing smaller regional blenders to price transparency pressure.
- Shipyards:China's domestic maritime repair sector is expanding solvent consumption as local paint manufacturers upgrade formulation capabilities and replace imported thinners with certified domestic alternatives.
- Paint Manufacturers:In-house formulation teams source commodity solvents for viscosity adjustment in coating production.
- Vehicle Maintenance Centers:Automotive body shops and collision repair facilities purchase packaged thinners through professional distribution channels.
- Aerospace Facilities:Maintenance, repair, and overhaul operations specify exotic solvent blends for sensitive substrate compatibility.
Specification authority concentrates with industrial coaters; emerging volume concentrates with Chinese shipyards upgrading domestic supply chains.
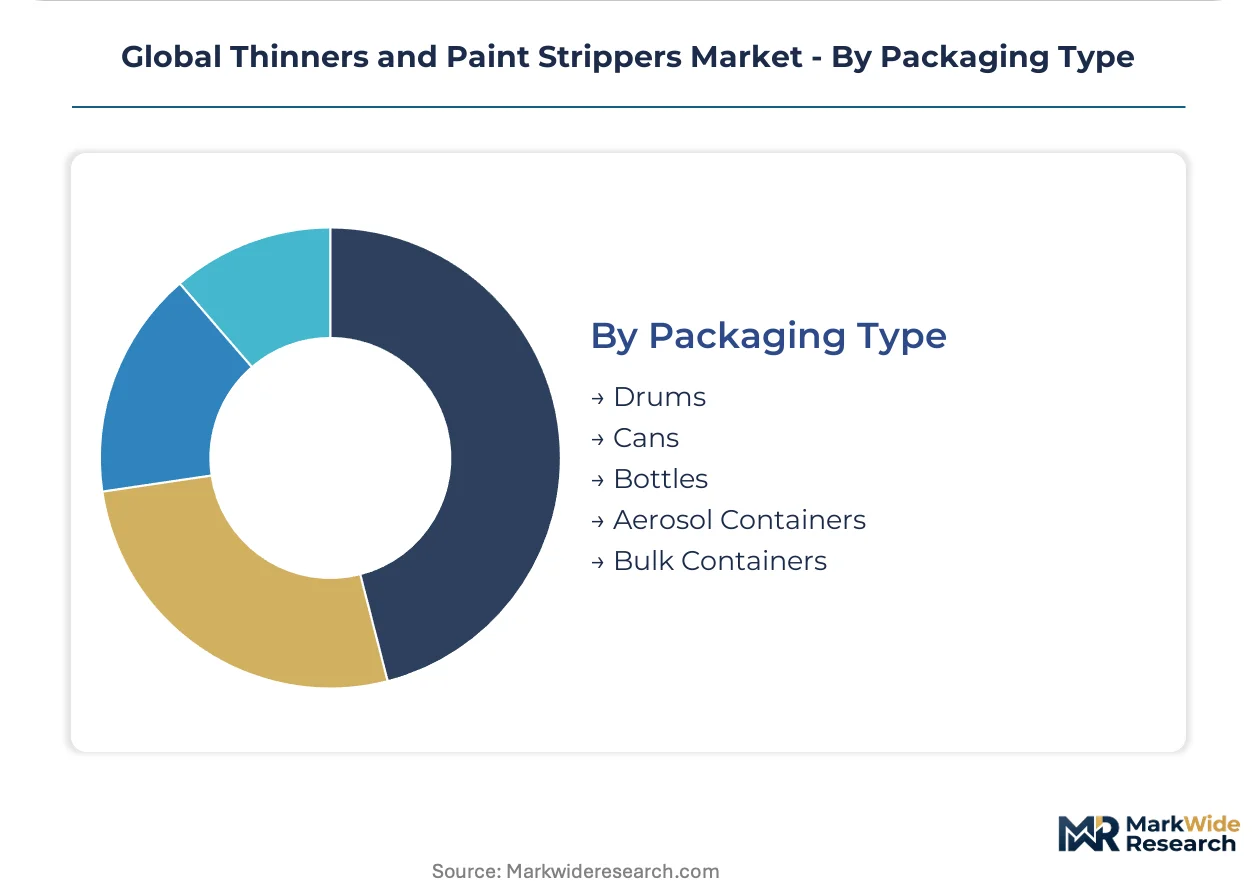
Packaging Type:
Container format aligns with use volume, regulatory transport classification, and point-of-application constraints across professional and retail channels.
- Drums:55-gallon steel drums serve high-volume industrial users with bulk handling infrastructure and hazmat storage compliance.
- Bulk Containers:Intermediate bulk containers and tanker deliveries supply continuous coating operations with direct-to-process feed.
- Cans:Gallon and quart metal cans target professional contractors with moderate consumption rates.
- Bottles:Pint and quart plastic bottles serve retail DIY segments and small-scale touch-up applications.
- Aerosol Containers:Spray-dispensed thinners and strippers enable controlled application in confined spaces and spot repair scenarios.
Industrial volume flows through drums and bulk containers; professional contractor channels sustain can and bottle formats with higher per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial coaters and automotive refinishing shops concentrate purchasing power across four major demand centers, with regulatory divergence fragmenting formulation standards and procurement patterns.
United States
Automotive refinishing clusters in Detroit and Los Angeles drive solvent consumption as EPA NESHAP compliance pressures shops toward closed-loop recovery systems. The agency's volatile organic compound limits for surface coating operations are tightening permissible chemistries. BASF and Sherwin-Williams anchor supply relationships through direct-to-contractor digital portals in these metropolitan markets.
Germany
Industrial coating maintenance in the Ruhr region and automotive refinishing in Bavaria sustain demand for high-performance solvent blends. ECHA REACH restrictions on methylene chloride are forcing reformulation toward benzyl alcohol and dimethyl glutarate alternatives. German shipyards in Hamburg and Bremen are piloting supercritical CO2 stripping technology for enclosed-space applications.
China
Domestic shipyard maintenance volumes in Shanghai and Guangzhou are expanding as local paint manufacturers upgrade formulation capabilities. SAMR GB standards on volatile organic compound content are reshaping permissible chemistries. Chinese producers are replacing imported thinners with certified domestic alternatives in these coastal manufacturing zones.
France
Professional restoration contractors in Paris and Lyon absorb higher per-unit chemical costs as EU REACH restrictions eliminate methylene chloride from decorative paint stripping. The country's national chemical regulator enforces toxicology dossier requirements that favor established suppliers. Heritage restoration specialists in Provence are shifting toward bio-derived ester blends with favorable safety profiles.
Japan
Aerospace maintenance facilities in Nagoya and Osaka specify exotic solvent blends for sensitive substrate compatibility. METI industrial standards govern chemical handling in enclosed-space applications. Japanese coating manufacturers are sourcing exempt-status bio-thinners to bypass VOC permitting requirements while maintaining performance specifications.
Global Thinners and Paint Strippers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented regional markets. The vendor base separates into three tiers: integrated petrochemical suppliers with captive feedstock positions, formulation specialists with jurisdiction-specific compliance expertise, and toll manufacturers offering asset-light regional presence. Scale advantages concentrate with players controlling professional distribution networks. Competitive moves center on multi-standard certification investments and toll manufacturing partnerships to bypass capital-intensive production assets.
Among integrated chemical conglomerates, BASF leverages its Ludwigshafen feedstock network to secure cost-advantaged raw material positions across European production hubs. Sherwin-Williams Company exemplifies channel-controlling strategy through its captive retail and professional contractor networks in North America. Akzo Nobel occupies a position navigating regulatory complexity through dedicated formulation laboratories in multiple jurisdictions.
| Leading Market Players |
|---|
| Akzo Nobel |
| PPG Industries |
| Sherwin-Williams Company |
| 3M |
| BASF |
| Henkel AG & Co. KGaA |
| Jotun |
| Nippon Paint |
| RPM International |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp petrochemical corridor's freight cost dynamics amplify supply concentration effects across European thinners markets, compressing margin structures for non-integrated blenders while enabling feedstock-advantaged producers to sustain three-tier pricing stratification across premium certified, standard industrial, and economy solvent tiers.
Pricing Analysis
Cost-plus contracts indexed to aromatic hydrocarbon and acetate feedstock benchmarks dominate procurement between integrated suppliers and large industrial coaters. Price differentiation separates multi-jurisdiction certified formulations from single-standard products and unregistered commodity blends. Pricing pressure stems from digital platform transparency exposing regional blender margins to fleet-scale buyers. Small vehicle maintenance centers exhibit highest price sensitivity, while aerospace facilities prioritize specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with German chemical services firms and Chinese toll blenders serving domestic shipyard demand. Feedstock supply draws from Saudi aromatics complexes, U.S. Gulf Coast acetate producers, and European naphtha crackers. Single-source vulnerability runs through methylene chloride substitution supply chains as REACH restrictions strand legacy inventory. Distribution runs through captive professional channels for specification products and open distribution for commodity thinners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among fleet-scale automotive refinishing groups and Chinese state-owned shipyards, fragmenting pricing leverage for mid-size regional blenders unable to match direct-to-contractor digital platforms.
For Market Incumbents: Build toxicology dossier moats by accelerating multi-jurisdiction registration pipelines ahead of methylene chloride phase-outs. BASF and Sherwin-Williams demonstrate channel control leverage through captive professional networks that lock in specification-driven demand. Backward integration into acetate feedstock production anchors margin stability against crude derivative volatility. For New Entrants and Emerging Players: Pursue toll manufacturing partnerships with Rotterdam-Antwerp corridor service providers to bypass capital-intensive solvent recovery assets. Chinese domestic shipyard supply chains present the most penetrable white-space as SAMR certification requirements displace imported thinners. Lead with exempt-status bio-formulation positioning for aerospace maintenance facilities seeking VOC permitting relief. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with jurisdiction-specific compliance expertise over commodity solvent traders. Five-to-ten year viability hinges on successful methylene chloride replacement chemistry commercialization. Watch ECHA restriction timelines and EPA NESHAP revision schedules as inflection signals for stranded asset risk and reformulation capex requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | REACH, NESHAP, and SAMR compliance unlocks premium pricing from multinational coating manufacturers. |
| Toll Manufacturing Partnership | Asset-light regional presence reduces capital barriers for entrants targeting Chinese shipyard demand. |
| Closed-Loop Solvent Recovery Deployment | EPA compliance pressure drives refinishing shop adoption, extending chemical lifecycles and service revenue. |
| Bio-Based Formulation Pipeline | Exempt-status positioning captures aerospace maintenance demand for enclosed-space applications. |
| Direct-to-Contractor Digital Platform | BASF and Sherwin-Williams portals disintermediate distributors, compressing buyer working capital requirements. |
Research Methodology
Operator-level perspectives from plant managers at European toll manufacturers, procurement leads at German automotive refinishing clusters, technical R&D directors at integrated chemical conglomerates, and distribution channel partners in Chinese coastal manufacturing zones anchored the qualitative base. Secondary validation drew from customs and trade data, Cefic solvent consumption reports, SEC 10-K disclosures from listed coating manufacturers, and SAMR product registration databases. Bottom-up segment sizing triangulated against top-down feedstock demand models.
Scenario-bracketing around regulatory phase-out timelines and feedstock price volatility bands structured the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, end-use application, packaging format, and regional regulatory cluster. CAGRs derived from solvent consumption intensity ratios by application and substitution elasticity estimates for water-based and bio-based alternatives. Industry-specific inputs incorporated shipyard maintenance scheduling patterns and automotive refinishing shop technology adoption curves.
Sensitivities concentrate around ECHA restriction enforcement timing, SAMR domestic substitution acceleration, and crude derivative price volatility. Forecasts reflect assumptions on reformulation pipeline completion rates and toll manufacturing capacity expansion. Quarterly review of regulatory filing volumes, feedstock benchmark movements, and digital platform transaction data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Water Color Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market