
 Connected Lighting Platform Market | 2026-2036
Connected Lighting Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Lighting Platform Market Outlook
EU Green Deal building renovation targets is rebalancing the cost-of-entry calculus for platform vendors serving European commercial real estate. Signify Holding leverages its Interact portfolio to anchor retrofit contracts across Nordic municipal networks. Acuity Brands sustains technology leadership in tunable-white systems through deep R&D partnerships with US architectural specifiers. ams-OSRAM competes on component density, supplying high-efficacy LED engines that reduce node costs for control system integrators.
A connected lighting platform integrates luminaires, sensors, and network gateways into a unified management architecture operating over protocols such as DALI-2, Zigbee 3.0, or Bluetooth Mesh, with typical system latency below 100 milliseconds for real-time occupancy response. These platforms serve primarily to reduce commercial building energy consumption by 30-50% while enabling spatial analytics and automated environmental tuning. Control Systems currently command the largest margin pools because software licensing and recurring SaaS fees outstrip hardware commoditization curves. Wi-Fi and Zigbee technology segments split the installed base, with Zigbee dominating large-footprint deployments where mesh resilience matters and Wi-Fi capturing residential and small-office retrofits that prioritize smartphone-native setup. Energy Management applications are expanding fastest as utility demand-response programs and time-of-use tariffs make load-shifting financially material for facility operators.
The US Department of Energy's SSL program and ENERGY STAR certification shape product efficiency baselines, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-based thermal management in outdoor node enclosures. China's GB standards for smart city interoperability and MIIT's IoT security certification create dual compliance requirements for vendors targeting state-backed infrastructure tenders. Stakeholders must monitor whether regional cybersecurity mandates fragment protocol standardization or consolidate procurement around a narrower set of certified platform stacks.
Market Dynamics
Protocol fragmentation between DALI-2, Zigbee 3.0, and Bluetooth Mesh is forcing vendors to engineer multi-stack gateways, raising R&D burn rates while compressing hardware margins across the installed base.
Growth Catalysts
- EU Green Deal building renovation mandates:The directive tightens energy performance standards across member states, compelling commercial real estate operators to retrofit legacy luminaires with networked control systems.
- MIIT IoT deployment directives:China's ministry mandates large-scale commercial retrofits, creating procurement pull for integrated sensor-luminaire nodes in state-backed infrastructure tenders.
- Utility demand-response program expansion:Time-of-use tariffs and load-shifting incentives make energy management applications financially material for facility operators managing multi-site portfolios.
Market Restraints
- LED engine supply concentration:High-efficacy chip fabrication concentrates in East Asian foundries, exposing control system integrators to input cost volatility and allocation risk during capacity crunches.
- Cybersecurity certification fragmentation:Divergent national mandates for IoT device security create compliance friction, lengthening product launch timelines and inflating regional variant engineering costs.
- Legacy analog infrastructure persistence:Deep installed bases of 0-10V dimming in North American commercial buildings slow digital retrofit cycles, constraining near-term addressable market expansion.
Strategic Opportunities
- Spatial analytics monetization:Occupancy pattern data streams from sensor networks enable new SaaS revenue pools as building operators seek workplace utilization intelligence beyond illumination control.
- German smart city infrastructure tenders:Municipal procurement of networked streetlight systems accelerates as federal funding programs underwrite district-scale deployments.
- Bluetooth Mesh-Wi-Fi convergence:Hybrid protocol stacks that bridge smartphone-native setup with enterprise-grade mesh resilience capture small-office retrofits previously lost to single-protocol solutions.
Industry Challenges
- DALI-2 commissioning expertise scarcity:Certified system integrators capable of complex address programming and fault diagnostics remain concentrated in Western European markets, constraining deployment velocity elsewhere.
- Multi-protocol firmware maintenance burden:Vendors supporting three or more wireless stacks face escalating QA complexity and security patch propagation costs across divergent certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Lighting Platform Market |
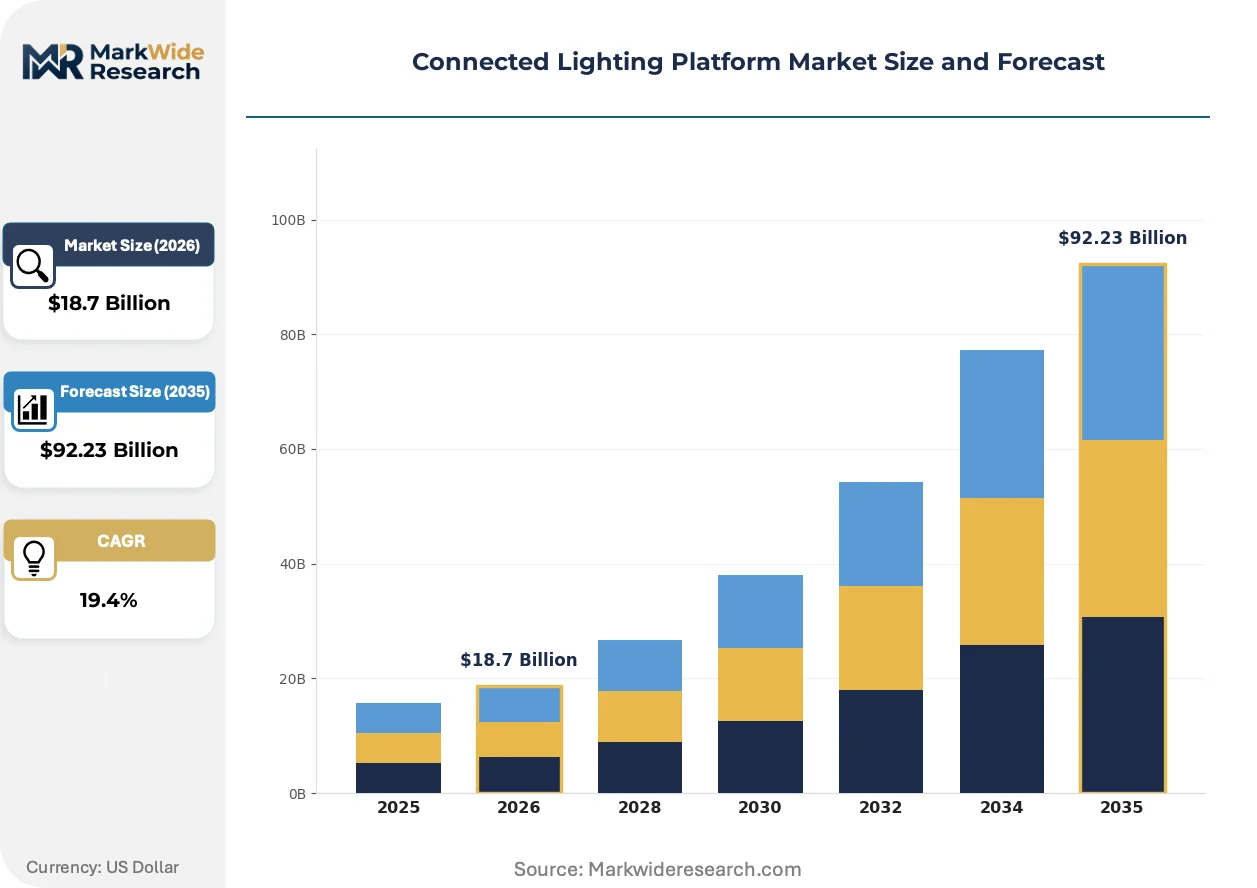
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bulbs, LED Fixtures, Control Systems, Sensors Technology: Wi-Fi, Zigbee, Bluetooth, LoRaWAN End User: Commercial Buildings, Residential Spaces, Industrial Facilities, Outdoor Areas Application: Lighting Control, Energy Management, Security, Automation |
| Companies Covered | Signify Holding, Acuity Brands, Itron, Legrand, Lutron Electronics, Panasonic Holdings Corporation, ams-OSRAM, Zumtobel Group, Schréder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Lighting Platform Market Strategic Shifts
Edge computing migration and AI-driven predictive maintenance are compressing the latency-performance tradeoff, enabling lighting networks to host non-illumination workloads that were previously cloud-dependent.
Tunable-white luminaires with circadian rhythm programming are automating spectral tuning across healthcare and education verticals. Hospital systems in the US and Nordic countries deploy these systems to support patient recovery protocols and staff alertness cycles. The technology is automating environmental conditioning decisions that previously required manual scene setting, reducing facilities management labor allocation.
The EU F-Gas Regulation constrains refrigerant-based thermal management in outdoor node enclosures, pushing manufacturers toward passive cooling architectures and phase-change materials. This regulatory pressure accelerates redesign cycles for streetlight and parking structure luminaires. Vendors targeting European municipal tenders now engineer sealed, fanless housings as standard specifications rather than premium options.
Facility management procurement teams increasingly bundle lighting retrofits with broader building automation upgrades, consolidating vendor relationships and compressing standalone lighting specification cycles. Mechanical-electrical contractors capture this bundled demand, displacing traditional lighting specifier influence in mid-market commercial projects. This pattern concentrates most visibly in US Class-B office and retail retrofit segments where capital planning integrates HVAC, access control, and illumination under single master system integrators.
Connected Lighting Platform Market Segmentation
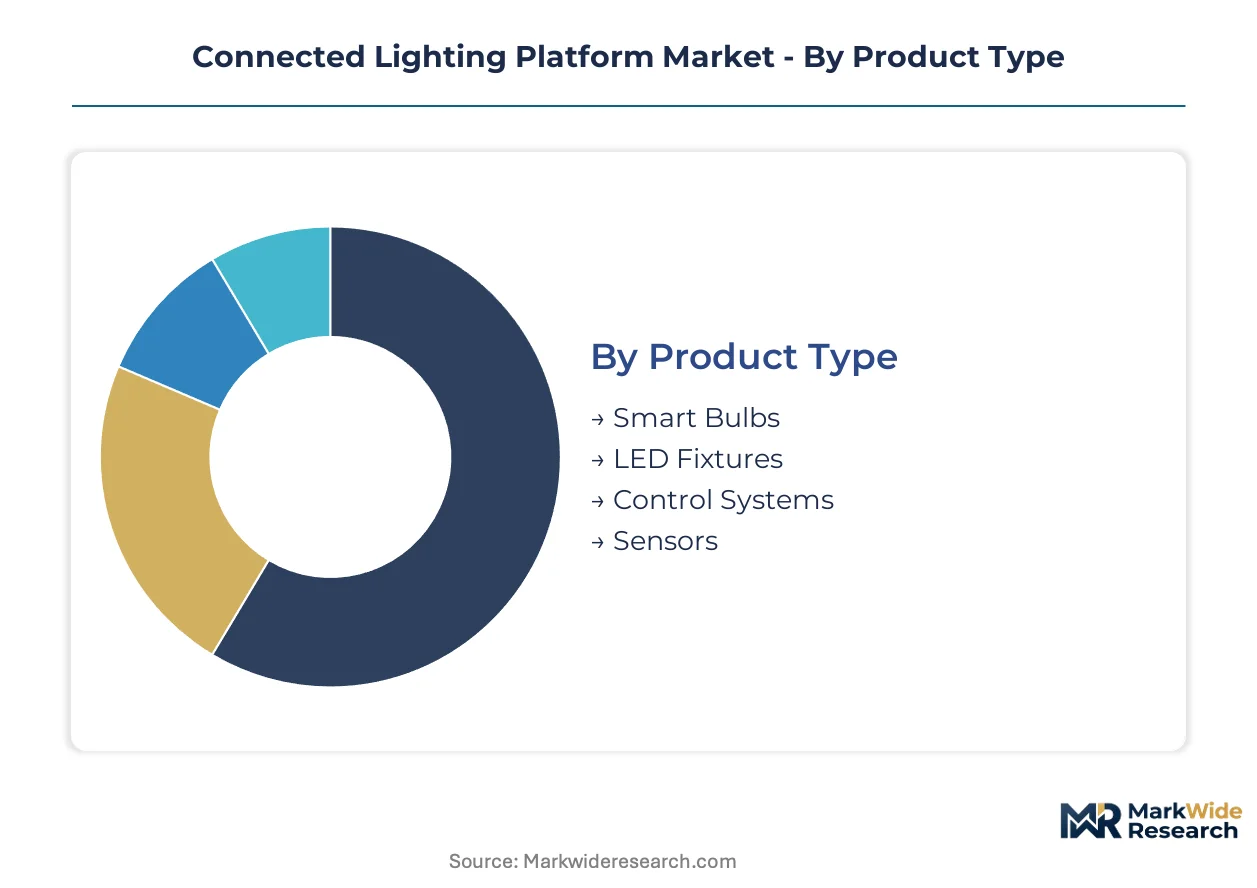
Segmentation in connected lighting platforms reveals how procurement priorities diverge across customer archetypes. Control system vendors, LED fixture manufacturers, and network technology providers each address distinct buyer workflows and compliance environments.
Product Type:
Buyers in this category separate by technical sophistication and integration burden tolerance.
- Control Systems:Software-defined management architectures unify luminaire addressing, sensor data ingestion, and gateway orchestration. Facility operators in Germany and the Netherlands prioritize these for EU Green Deal compliance and utility demand-response enrollment. Recurring SaaS licensing outstrips hardware commoditization curves, concentrating margin pools here.
- LED Fixtures:Network-ready luminaires embed DALI-2 or wireless control modules at the factory, reducing field commissioning complexity. China's MIIT-mandated commercial retrofits drive volume procurement of sensor-integrated nodes for state-backed infrastructure tenders.
- Sensors:Occupancy, daylight harvesting, and environmental sensing nodes extend platform functionality beyond illumination.
- Smart Bulbs:Consumer-grade retrofit lamps with embedded radios serve residential and small-office segments prioritizing smartphone-native setup.
LED Fixtures lead volumes today; Control Systems is gaining share fastest.
Technology:
Protocol selection hinges on deployment scale, mesh resilience requirements, and IT infrastructure maturity.
- Zigbee:Mesh-native protocol dominates large-footprint commercial deployments where node density and network self-healing matter. Nordic municipal streetlight networks and US campus retrofits specify Zigbee 3.0 for its sub-100ms latency and certified interoperability stacks.
- Wi-Fi:Leverages existing enterprise infrastructure for rapid deployment in Class-B office and retail spaces. Small-office buyers favor smartphone-native commissioning without dedicated gateways, though power consumption constrains battery-operated sensor applications.
- Bluetooth:Bluetooth Mesh bridges consumer setup simplicity with enterprise-grade density, capturing mid-market retrofits previously lost to single-protocol solutions.
- LoRaWAN:Wide-area, low-power protocol serves outdoor and campus-scale deployments requiring kilometer-range backhaul without mesh density.
Zigbee anchors the installed base; Bluetooth Mesh is climbing the fastest as hybrid stacks proliferate.
End User:
Capital allocation cycles and regulatory exposure differentiate buyer segments sharply.
- Commercial Buildings:Office, retail, and hospitality operators pursue 30-50% energy reduction through networked controls. EU Ecodesign Directive compliance and ENERGY STAR certification requirements shape specification criteria in Europe and the US respectively.
- Outdoor Areas:Municipal streetlight and parking structure deployments accelerate under German federal funding programs and Chinese smart city infrastructure tenders. F-Gas Regulation constraints push vendors toward passive cooling architectures in European procurement.
- Industrial Facilities:Manufacturing and warehousing operators demand ruggedized nodes with high ingress protection and vibration tolerance.
- Residential Spaces:Single-family and multi-unit dwellings prioritize cost minimization and consumer-app ecosystem compatibility over enterprise-grade management.
Commercial Buildings lead volumes today; Outdoor Areas is expanding most quickly on smart city investment waves.
Application:
Return-on-investment horizons and data monetization potential separate use case priorities.
- Energy Management:Load-shifting, demand-response, and time-of-use tariff optimization deliver quantifiable utility bill reductions. US utility program expansion and EU building renovation mandates make this the primary retrofit justification for multi-site facility operators.
- Lighting Control:Core platform functionality encompassing dimming, scene setting, and circadian rhythm programming. Healthcare systems in the US and Nordic countries deploy tunable-white systems for patient recovery protocols and staff alertness cycles.
- Automation:Integration with HVAC, access control, and broader building management systems consolidates vendor relationships.
- Security:Sensor networks enable occupancy verification and perimeter monitoring beyond illumination functions.
Lighting Control anchors current deployments; Energy Management shows the steepest expansion trajectory as tariffs restructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Systems integrators with DALI-2 commissioning expertise cluster in Western European markets, while IoT security certification specialists concentrate in Chinese technology hubs.
United States
Commercial building operators pursue ENERGY STAR-certified retrofits to capture utility demand-response incentives. The Department of Energy's SSL program shapes baseline efficiency requirements for networked luminaire procurement. Hospital systems in the Northeast deploy tunable-white platforms for circadian rhythm programming in patient recovery protocols.
Germany
Municipal procurement of networked streetlight systems accelerates under federal funding programs underwriting district-scale deployments. The EU Green Deal's building renovation mandates tighten energy performance standards across commercial real estate portfolios. Industrial facilities in Baden-Württemberg specify ruggedized nodes with high ingress protection for manufacturing floor integration.
China
MIIT-mandated commercial retrofits create procurement pull for integrated sensor-luminaire nodes in state-backed infrastructure tenders. GB standards for smart city interoperability impose dual compliance requirements on platform vendors. Technology clusters in Shenzhen and Shanghai engineer multi-protocol gateways for domestic and export markets.
Japan
Healthcare and education verticals automate spectral tuning through tunable-white systems supporting staff alertness cycles. METI efficiency programs shape specification criteria for commercial building retrofits. Manufacturing facilities in the Chubu region demand vibration-tolerant nodes for warehouse automation integration.
Netherlands
Facility operators prioritize EU Ecodesign Directive compliance through software-defined management architectures with recurring SaaS licensing. Utility time-of-use tariffs make energy management applications financially material for multi-site portfolio managers. Amsterdam's municipal networks specify Zigbee 3.0 for sub-100ms latency in large-footprint deployments.
Connected Lighting Platform Market Competitive Environment
The competitive structure tilts toward diversified lighting conglomerates with captive control system portfolios. Three tiers have formed: integrated platform vendors spanning hardware and software, component specialists supplying high-efficacy LED engines, and regional fixture manufacturers with localized commissioning capabilities. Consolidation pressure intensifies as multi-protocol firmware maintenance burdens escalate and hardware margins compress. Strategic moves concentrate on vertical integration into sensor manufacturing and geographic expansion through municipal tender capture.
Among diversified lighting conglomerates, Signify Holding and Acuity Brands occupy positions anchoring retrofit contract flows across municipal and commercial segments. The component specialist tier includes ams-OSRAM, which exemplifies the high-efficacy LED engine supply archetype serving control system integrators. These three entities represent distinct competitive vectors: platform integration depth, specification influence with architectural decision-makers, and input cost reduction for downstream assemblers.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Itron |
| Legrand |
| Lutron Electronics |
| Panasonic Holdings Corporation |
| ams-OSRAM |
| Zumtobel Group |
| Schréder |
| Others |
Value Chain & Pricing Dynamics
Certified DALI-2 commissioning engineers concentrated in Western European labor markets widen pricing-tier spreads between premium turnkey installations and economy self-service deployments, compressing margins for vendors lacking regional integration partnerships.
Pricing Analysis
The bundled-vs-unbundled service split separates SaaS-recurring control platforms from transactional hardware-only sales. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service intensity. Cost compression in economy LED fixture tiers intensifies because hardware commoditization outpaces software margin expansion. Small-office retrofit buyers exhibit highest price sensitivity; municipal smart city procurement teams prioritize total-cost-of-ownership over upfront unit economics.
Supply Chain Analysis
Reverse-logistics flows for failed gateway modules and end-of-life luminaire recovery remain underdeveloped, exposing vendors to circular-economy compliance costs as EU Ecodesign Directive requirements tighten. High-efficacy LED chip fabrication concentrates in China, Taiwan, and South Korea, drawing from gallium nitride wafers and rare-earth phosphor formulations. Single-source vulnerability in wireless radio module supply creates allocation risk during semiconductor capacity crunches. Distribution runs through mechanical-electrical contractors consolidating bundled building automation procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Connected Lighting Platform Market functions as a stable compounder, with regulatory-mandated building renovation cycles providing predictable procurement pull across decade-long infrastructure refresh timelines.
For Market Incumbents: Deploy multi-protocol firmware consolidation as the primary lever. Reduce QA complexity by retiring legacy Zigbee 1.2 stacks and standardizing on certified Bluetooth Mesh-Zigbee 3.0 hybrid architectures. Acquire regional system integration capabilities in German municipal markets to capture district-scale streetlight tender flows before emerging platform vendors establish local commissioning expertise.
For New Entrants and Emerging Players: Mechanical-electrical contractors represent the most accessible channel partner type for bypassing incumbent lighting specifier relationships. Target US Class-B office retrofits where bundled HVAC-access control-lighting procurement concentrates specification influence with contractors rather than traditional architectural channels. White-space exists in spatial analytics SaaS layers above commodity control hardware.
For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists with captive LED engine supply and limited downstream platform integration. Long-term viability hinges on software recurring revenue attachment rates rather than hardware shipment volumes. Monitor utility demand-response program enrollment velocity as the critical inflection signal for energy management application monetization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Gateway Consolidation | Reduces firmware maintenance burden and security patch propagation costs across divergent certification cycles. |
| Spatial Analytics SaaS Layer Development | Captures workplace utilization intelligence revenue pools beyond illumination control in commercial building portfolios. |
| Municipal Tender Capture in Germany | Federal funding programs underwrite district-scale networked streetlight deployments with multi-year maintenance contracts. |
| Passive Cooling Architecture Migration | EU F-Gas Regulation compliance requires sealed, fanless outdoor node enclosures for European procurement eligibility. |
| Bluetooth Mesh-Wi-Fi Hybrid Stack Launch | Bridges smartphone-native setup simplicity with enterprise-grade mesh resilience for small-office retrofit capture. |
Study Parameters
Direct dialogue with control system vendors, municipal procurement officers, facility management executives, and mechanical-electrical contractors grounded qualitative findings in operational reality. Secondary validation drew from EU Ecodesign Directive filings, MIIT IoT security certification databases, ENERGY STAR product listings, and utility demand-response program disclosures. Bottom-up shipment modeling and top-down construction spending allocation triangulated market sizing across product type, technology protocol, and end-user vertical dimensions.
Segment-level value outputs across the analysis window reflect installed base projections, replacement cycle assumptions, and attach-rate modeling for software licensing revenue. Product type, technology protocol, end-user vertical, and application use case structured the forecast framework. CAGRs derived from logistic diffusion curves fitted to historical retrofit penetration patterns and regulatory mandate implementation timelines. Smart city infrastructure investment flows and time-of-use tariff restructuring served as primary demand elasticity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to protocol standardization consolidation versus fragmentation, cybersecurity certification harmonization or divergence, and LED engine supply concentration shifts. Practitioners should monitor utility rate structure reforms, MIIT IoT deployment directive revisions, and EU Green Deal enforcement intensity for early signals of demand trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Smart Street Lighting Systems Market
Lighting
Global Work Lights Market
Lighting
Smart Lamp Market
Lighting
GCC Smart Lighting Market
Lighting
Explosion Proof Lighting Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Residential Lighting Fixtures Market
Lighting
Graphene Lighting Market
Lighting
Lighting Control Components Market
Lighting
Lighting Fixture Market
Lighting
Fluorescent Lighting Market
Lighting
Programmable Stage Lighting Market
Lighting
OLED Lightening Panels Market
Lighting
Cleanroom Lighting Market