
 Gesture Control Light Market | 2026-2036
Gesture Control Light Market Size, Share, and Industry Trends Forecast 2026-2036
Gesture Control Light Market Foresight
Modular fixture designs that separate gesture-sensing modules from luminaire housings is recalibrating buyer choice across residential and commercial channels. Nimbus Group GmbH leverages its German engineering base to dominate premium architectural installations. Elmos Semiconductor SE anchors the supply chain through dedicated gesture-recognition chipsets that reduce peripheral component counts. Blebox Sp. z o.o. competes on open-protocol compatibility, allowing its modules to integrate with third-party automation platforms.
Gesture control light systems combine non-contact motion sensors with solid-state illumination to enable hands-free dimming, color temperature adjustment, and on-off toggling through predefined hand movements, typically operating via infrared or radar detection at ranges of 5–30 centimeters. These systems serve smart homes, hospitality venues, and commercial offices where hygiene consciousness and accessibility requirements elevate demand for touchless interfaces. Smart ceiling lights lead volume deployment in new residential construction across Europe, while portable desk lamps represent the fastest-growing category as hybrid work patterns sustain home-office retrofit cycles. Radar sensor technology captures expanding share from infrared alternatives where false-trigger sensitivity undermines user experience in high-traffic environments.
The EU Green Deal and F-Gas Regulation impose escalating efficiency standards on connected lighting products sold within Europe, compelling manufacturers to certify gesture modules alongside luminaire assemblies. Germany's KBA and France's ANSM do not directly regulate this category, but CE marking requirements under the EU AI Act increasingly scrutinize sensor data processing in gesture-recognition algorithms. Stakeholders must monitor whether emerging product safety frameworks reclassify gesture-sensing cameras as biometric data collectors, triggering GDPR compliance obligations that reshape hardware architecture and firmware design decisions.
Market Dynamics
Radar sensor modules are displacing infrared alternatives across European smart home installations, compressing design cycles for fixture manufacturers while elevating hygiene-driven specification requirements in hospitality and healthcare channels.
Growth Catalysts
- EU Green Deal efficiency mandates:Escalating certification requirements for connected lighting products accelerate replacement cycles in commercial real estate portfolios across Germany and France.
- Hybrid work normalization:Sustained home-office retrofit demand concentrates in portable desk lamp categories, expanding addressable household penetration beyond traditional ceiling fixture markets.
- GDPR-compliant sensor architectures:Edge-processing gesture modules that eliminate cloud data transmission unlock specification in privacy-sensitive German institutional procurement.
Market Restraints
- Semiconductor supply concentration:Dedicated gesture-recognition chipsets depend on concentrated foundry capacity in East Asian manufacturing nodes, exposing lead time volatility.
- False-trigger sensitivity in infrared systems:Legacy proximity detection technologies suffer ambient light interference, degrading user experience in high-traffic commercial environments and delaying specification.
- F-Gas Regulation compliance costs:Thermal management component certification for integrated sensor-luminaire assemblies elevates per-unit production economics for mid-tier manufacturers.
Strategic Opportunities
- Open-protocol module integration:Third-party automation platform compatibility enables specification in retrofit-heavy French residential channels where proprietary ecosystems face replacement friction.
- Radar-to-visible-light convergence:Combined occupancy-sensing and illumination control reduces peripheral component counts, compressing bill-of-materials for architectural fixture producers.
- ANSM-adjacent healthcare specification:Touchless control interfaces align with French medical facility hygiene protocols, opening dedicated procurement verticals outside traditional building automation.
Industry Challenges
- CE marking timeline compression:EU AI Act sensor data processing scrutiny extends certification cycles for gesture-recognition firmware updates, delaying product launch windows.
- Legacy building management integration:BACnet and KNX protocol translation requirements elevate engineering overhead for commercial retrofit projects, constraining margin recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gesture Control Light Market |
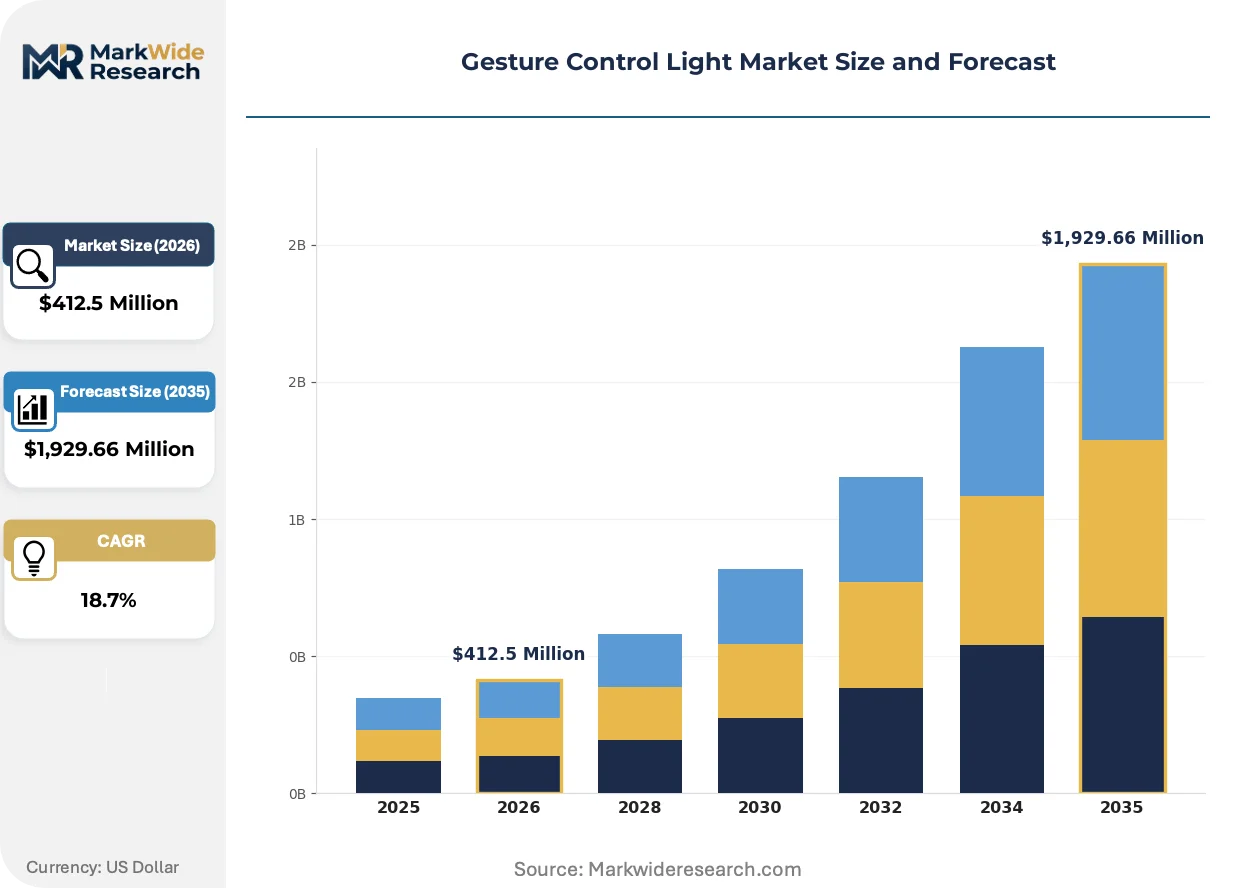
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ceiling Lights, Portable Desk Lamps, LED Wall Lights, Outdoor Spotlights, Motion Sensor Lamps Technology: Infrared Sensors, Ultrasonic Sensors, Radar Sensors, Capacitive Sensors, Optical Sensors Application: Smart Homes, Hospitality Venues, Commercial Offices, Public Spaces, Entertainment Facilities End User: Homeowners, Facility Managers, Office Administrators, Event Organizers, Retail Establishments |
| Companies Covered | Nimbus Group GmbH, Blebox Sp. z o.o., Allocacoc, Banvil 2000, Elmos Semiconductor SE, Hillmax, iGear, ROOME, Sensinova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gesture Control Light Market Shifts & Advancements
Technology convergence between radar sensing and solid-state illumination is compressing hardware footprints while regulatory pressure on data privacy reshapes firmware architectures across European supply chains.
Millimeter-wave radar sensors are integrating proximity detection, occupancy sensing, and gesture recognition into single-chip modules. German architectural lighting manufacturers specify these consolidated components for ceiling installations where multiple discrete sensors previously occupied separate mounting positions. The technology is integrating dimming, color-temperature adjustment, and daylight harvesting into unified control planes, eliminating redundant wiring infrastructure.
F-Gas Regulation phase-down schedules impose escalating thermal efficiency requirements on connected luminaire assemblies sold within Europe. Manufacturers must certify integrated gesture modules alongside complete fixture assemblies, extending testing protocols and elevating documentation burdens. German KBA vehicle lighting standards indirectly influence residential sensor durability expectations, compressing acceptable failure-rate thresholds across adjacent product categories.
Specification behavior among French hospitality procurement teams now prioritizes touchless interface compatibility as a standalone evaluation criterion, displacing traditional aesthetic-first selection protocols. Channel partners in the Paris-Ile-de-France corridor report compressed decision cycles for retrofit projects where hygiene certification carries equal weight to energy performance ratings. This pattern concentrates in boutique hotel segments where guest-facing technology differentiation commands rate premiums.
Gesture Control Light Market Segmentation
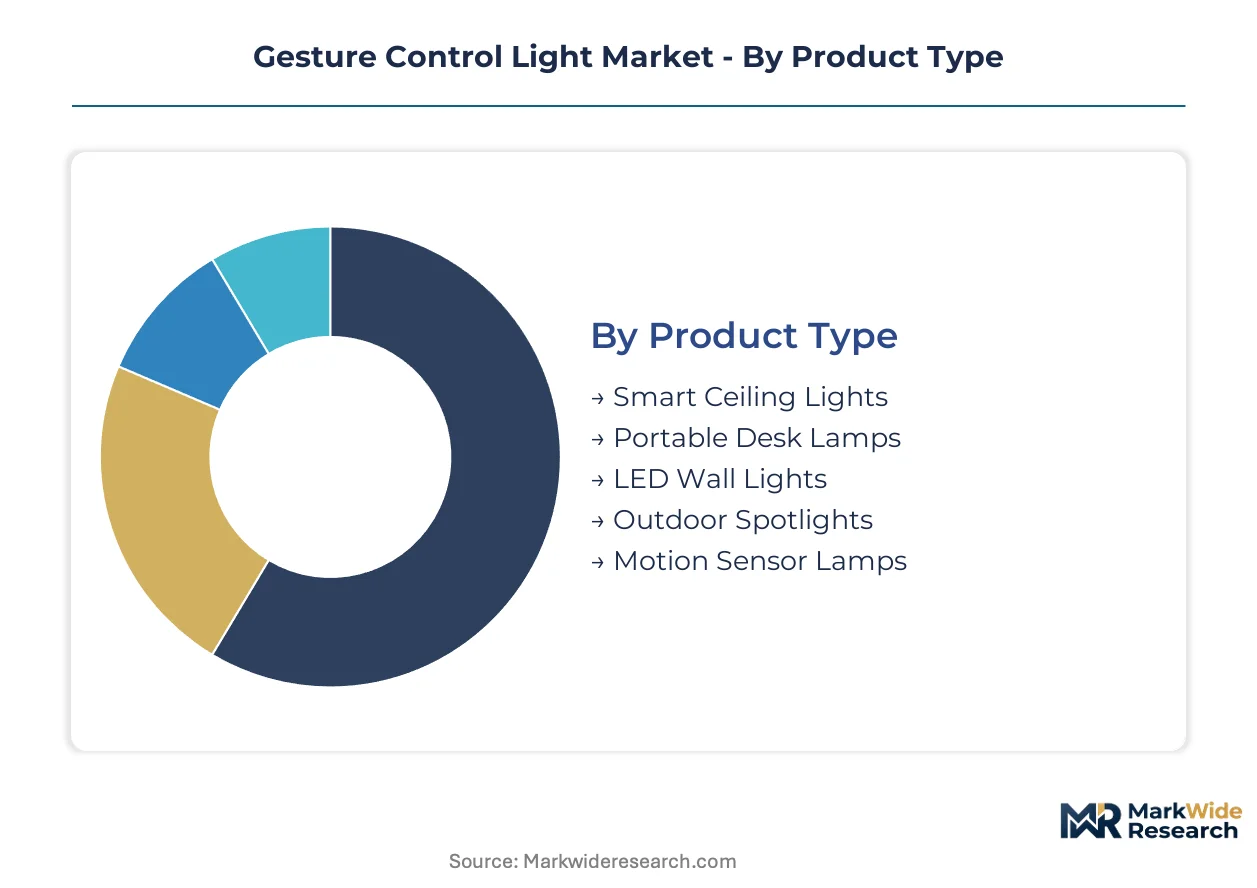
Segmentation in gesture control lighting reveals divergent integration strategies across residential and commercial channels. Standalone portable units compete with embedded architectural systems for specification priority. Understanding where each segment sits on the integration spectrum illuminates procurement behavior and margin architecture.
Product Type:
Integration depth varies sharply across fixture categories, with ceiling-mounted systems embedding sensors permanently while portable units maintain modular separation.
- Smart Ceiling Lights:Permanent architectural installations integrate radar or infrared modules directly into luminaire housings. Demand concentrates in German new residential construction where EU Green Deal efficiency mandates accelerate connected fixture specification. These systems serve as primary lighting infrastructure with gesture control as embedded functionality rather than add-on feature.
- Portable Desk Lamps:Self-contained units with detachable gesture modules dominate hybrid work retrofit cycles. French home-office procurement channels show fastest uptake as facility managers extend enterprise wellness budgets to remote employee equipment. The category benefits from plug-and-play deployment without electrical contractor involvement.
- LED Wall Lights:Sconce and panel formats embed proximity sensors for corridor and accent illumination.
- Outdoor Spotlights:Weather-hardened housings incorporate motion-activated gesture overrides for security lighting applications.
- Motion Sensor Lamps:Entry-level units combine basic proximity detection with limited gesture vocabulary for utility spaces.
Smart Ceiling Lights lead volumes today; Portable Desk Lamps are gaining share fastest.
Technology:
Cost tier stratification separates premium radar implementations from commodity infrared alternatives, with mid-tier ultrasonic and capacitive options filling specification gaps.
- Radar Sensors:Millimeter-wave modules consolidate proximity, occupancy, and gesture recognition into single-chip architectures. German architectural manufacturers specify these for high-traffic hospitality environments where false-trigger immunity justifies premium positioning. The technology eliminates redundant sensor clusters in ceiling installations.
- Infrared Sensors:Legacy proximity detection dominates entry-level residential retrofit through established supply chains and minimal calibration requirements. French mass-market retail channels maintain volume concentration despite ambient light interference limitations in commercial settings.
- Ultrasonic Sensors:Time-of-flight ranging supports basic gesture vocabulary in cost-constrained commercial retrofits.
- Capacitive Sensors:Near-field detection enables touchless control in medical and food-service hygiene-critical applications.
- Optical Sensors:Camera-based systems face GDPR scrutiny under EU AI Act sensor data processing rules, constraining deployment.
Infrared Sensors retain volume leadership; Radar Sensors are expanding most quickly.
Application:
Customer type differentiation separates consumer-directed smart home procurement from institutional specification processes with divergent compliance burdens.
- Smart Homes:Residential automation platforms drive integration demand across new construction and retrofit channels. German homeowners prioritize open-protocol compatibility to avoid ecosystem lock-in, while French buyers emphasize aesthetic integration with interior design schemes. Gesture control serves as differentiator in premium smart home packages.
- Hospitality Venues:Boutique hotels and business-class properties specify touchless interfaces as standalone evaluation criteria. Paris-Ile-de-France procurement teams compress decision cycles where hygiene certification carries equal weight to energy performance ratings.
- Commercial Offices:Facility managers balance retrofit economics against employee wellness positioning.
- Public Spaces:Municipal procurement emphasizes vandal resistance and minimal maintenance in transit and civic buildings.
- Entertainment Facilities:Themed environments deploy gesture control for immersive interaction and operational efficiency.
Smart Homes dominate current volumes; Hospitality Venues show steepest expansion trajectory.
End User:
Volume concentration sits with individual purchasers while margin expansion follows institutional procurement sophistication.
- Homeowners:Direct-to-consumer channels capture volume through retail and e-commerce platforms. German buyers demonstrate highest willingness-to-pay for premium architectural fixtures with embedded gesture modules. Purchase decisions integrate with broader smart home ecosystem investments.
- Facility Managers:Enterprise and commercial real estate portfolios drive specification for standardized deployments across multiple properties. French facility management firms increasingly require GDPR-compliant edge-processing architectures to satisfy institutional privacy policies.
- Office Administrators:Department-level procurement supports team-specific workspace customization.
- Event Organizers:Temporary installation demand favors rental and lease models over capital acquisition.
- Retail Establishments:Customer-facing gesture interfaces support brand differentiation in experiential merchandising.
Homeowners lead volumes today; Facility Managers are gaining specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered gesture-recognition lighting integration through its precision-engineering heritage, establishing the technical standards that shaped European smart home adoption patterns.
Germany
EU Green Deal efficiency mandates accelerate connected fixture replacement in commercial real estate portfolios. The KBA's durability standards for vehicle lighting indirectly elevate sensor reliability expectations across adjacent consumer categories. Nimbus Group GmbH anchors production in Stuttgart engineering clusters, supplying premium architectural installations across Central Europe.
France
ANSM-adjacent healthcare procurement protocols prioritize touchless interfaces in medical facility retrofits. The CNIL enforces GDPR-compliant edge-processing requirements for sensor data handling in institutional deployments. Paris-Ile-de-France hospitality procurement teams now weight hygiene certification equally with energy performance ratings.
United Kingdom
Post-pandemic hybrid work patterns sustain home-office equipment demand through facility management wellness budgets. CE marking alignment with EU AI Act sensor processing rules extends certification timelines for firmware updates. London-Southeast channel partners report compressed decision cycles for boutique hotel retrofit projects.
Poland
Blebox Sp. z o.o. leverages Warsaw-based engineering capacity to compete on open-protocol compatibility. The country's manufacturing cost structure supports mid-tier module production for third-party automation platform integration. Kraków-TriCity corridor clusters specialize in firmware development for privacy-sensitive European institutional procurement.
Netherlands
Randstad metropolitan demand concentrates in smart ceiling installations for high-density residential construction. The country's building automation heritage accelerates KNX protocol integration requirements for gesture modules. Eindhoven-region semiconductor expertise feeds radar sensor component sourcing for architectural fixture manufacturers.
Gesture Control Light Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with architectural fixture specialists commanding specification priority over portable unit assemblers. The vendor base stratifies into three tiers: German-engineered premium architectural systems, Polish-led open-protocol module suppliers, and Asian-origin volume producers of consumer desk lamps. Consolidation pressure concentrates among mid-tier infrared-dependent manufacturers as radar sensor costs decline. Dominant competitive moves include backward integration into dedicated gesture-recognition chipsets and strategic partnerships with building automation platform providers.
Within the premium architectural tier, Nimbus Group GmbH exemplifies German engineering positioning through its Stuttgart-based GmbH structure. Elmos Semiconductor SE anchors the component supply layer with its SE designation indicating public corporate form. Blebox Sp. z o.o. occupies the open-protocol integration position, with its Polish Sp. z o.o. structure reflecting limited liability incorporation suited to agile module development cycles.
| Leading Market Players |
|---|
| Nimbus Group GmbH |
| Blebox Sp. z o.o. |
| Allocacoc |
| Banvil 2000 |
| Elmos Semiconductor SE |
| Hillmax |
| iGear |
| ROOME |
| Sensinova |
| Others |
Supply & Pricing Matrix
Radar sensor engineering talent pools in the Netherlands and Germany compress labor-cost differentials into pricing-tier spreads across gesture control lighting markets. Warsaw-based firmware developers and Stuttgart industrial designers anchor distinct cost structures that separate premium architectural fixtures from mass-market portable units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs gesture control lighting procurement. CE certification grade and radar-versus-infrared technology tier drive price differentiation between German-engineered architectural systems and Asian-origin desk lamps. Pricing pressure stems from declining radar module costs that compress mid-tier margins. Home-office facility managers show highest price sensitivity, while German boutique hotel procurement teams prioritize hygiene certification over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg operate hub-and-spoke patterns for European gesture module fulfillment. Taiwan and South Korea anchor millimeter-wave radar chip fabrication, while China dominates infrared sensor die production. German luminaire assemblers draw from Polish firmware development clusters for GDPR-compliant edge-processing architectures. Single-source vulnerability concentrates in East Asian foundry capacity for dedicated gesture-recognition semiconductors. Distribution runs through building automation integrators and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gesture control light market compounds steadily as EU Green Deal efficiency mandates force replacement cycles across European commercial real estate portfolios.
For Market Incumbents: Lock in specification priority through captive supply of radar sensor chipsets and exclusive KNX protocol certification partnerships. Nimbus Group GmbH's Stuttgart engineering base demonstrates how backward integration into gesture-recognition semiconductors defends margin architecture against Polish open-protocol competitors. CE marking timeline compression under EU AI Act sensor data rules threatens firmware update velocity; incumbents should pre-certify modular architectures to compress launch windows. For New Entrants and Emerging Players: French healthcare facility procurement teams represent an underserved buyer archetype where ANSM-adjacent hygiene protocols create specification entry points outside traditional building automation channels. Portable desk lamp retrofit demand in hybrid work environments offers faster penetration than permanent ceiling fixture markets. Open-protocol module compatibility with third-party automation platforms unlocks specification in ecosystem-agnostic French residential channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier infrared-dependent manufacturers facing radar sensor cost compression. Long-term viability centers on edge-processing architectures that eliminate cloud data transmission and satisfy GDPR compliance burdens. The inflection signal to watch is EU AI Act enforcement patterns that reclassify camera-based gesture systems as biometric data collectors, triggering hardware architecture shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Radar Sensor Backward Integration | Captive millimeter-wave chipset supply secures margin architecture against foundry volatility. |
| GDPR-Compliant Edge Processing | On-device gesture recognition unlocks French institutional procurement blocked by cloud transmission restrictions. |
| KNX Protocol Certification | German building automation heritage demands interoperability for ceiling fixture specification. |
| Open-Protocol Module Development | Third-party platform compatibility captures retrofit-heavy French residential channels. |
| Healthcare Channel Partnership | ANSM hygiene protocol alignment opens dedicated procurement verticals in medical facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged architectural lighting designers, facility management procurement leads, semiconductor component specialists, and smart home platform engineers. Secondary validation drew from EU Green Deal implementation documents, CE marking databases, F-Gas Regulation compliance filings, and customs trade records for gesture sensor modules. Bottom-up fixture shipment tallies and top-down smart home penetration rates were triangulated against manufacturer production disclosures.
Historical reference periods anchored volume and value trajectories across the projection horizon. Segmentation dimensions modeled include fixture integration depth, sensor technology tier, application channel, and end-user procurement sophistication. CAGRs were derived from replacement cycle analysis under EU efficiency mandates and hybrid work equipment refresh patterns. Radar sensor cost decline curves and GDPR compliance timeline assumptions shaped forward estimates.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time production data from private semiconductor foundries introduce uncertainty bands around sensor supply assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Commercial Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
Display Light Control Film Market
Lighting
Human Centric Lighting Market
Lighting
Ring Lights Market
Lighting
OLED Lightening Panels Market
Lighting
Battery Operated Lights Market
Lighting
North America Street Lighting Market
Lighting
Bacteriological Light Market
Lighting
Xenon Flashlamps Market
Lighting
Dimmers Market
Lighting
Tritium Light Source Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Programmable Stage Lighting Market