
 US Indoor LED Lighting Market | 2026-2036
US Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
US Indoor LED Lighting Market Insights
Modular fixture-and-control bundling is consolidating buyer choice across the US Indoor LED Lighting Market, as specifiers increasingly demand pre-integrated luminaire-and-sensor packages rather than discrete components. Acuity Brands, Inc. leverages its Atrius IoT platform to anchor intelligent building contracts in the commercial vertical. Signify (Philips) competes through Interact software ecosystems that extend its luminaire footprint into data-driven facility management. Cree LED (SMART Global Holdings, Inc.) specializes in high-efficacy chip-on-board architectures that dominate premium downlight specifications.
US Indoor LED Lighting comprises solid-state electroluminescent fixtures utilizing gallium nitride semiconductor emitters mounted on aluminum or ceramic substrates, typically operating at correlated color temperatures between 2700K and 5000K with system efficacies exceeding 130 lumens per watt for commercial-grade products. Panel lights and troffers occupy the largest installed base in office and education retrofits, though margin pools increasingly shift toward smart lighting configurations that integrate occupancy sensing and daylight harvesting. Downlight demand accelerates in residential and hospitality segments where compact aperture designs and warm-dim functionality command specification premiums.
The DOE maintains minimum efficacy requirements through federal appliance standards, while California's Title 24 Building Energy Efficiency Standards mandate automatic daylight dimming and vacancy sensing in new commercial construction. OSHA workplace illumination guidelines and state-level utility rebate programs administered by entities such as the California Energy Commission further shape product specification pathways. Stakeholders must monitor the convergence of building electrification mandates with emerging grid-interactive efficient building standards that will redefine control architecture requirements.
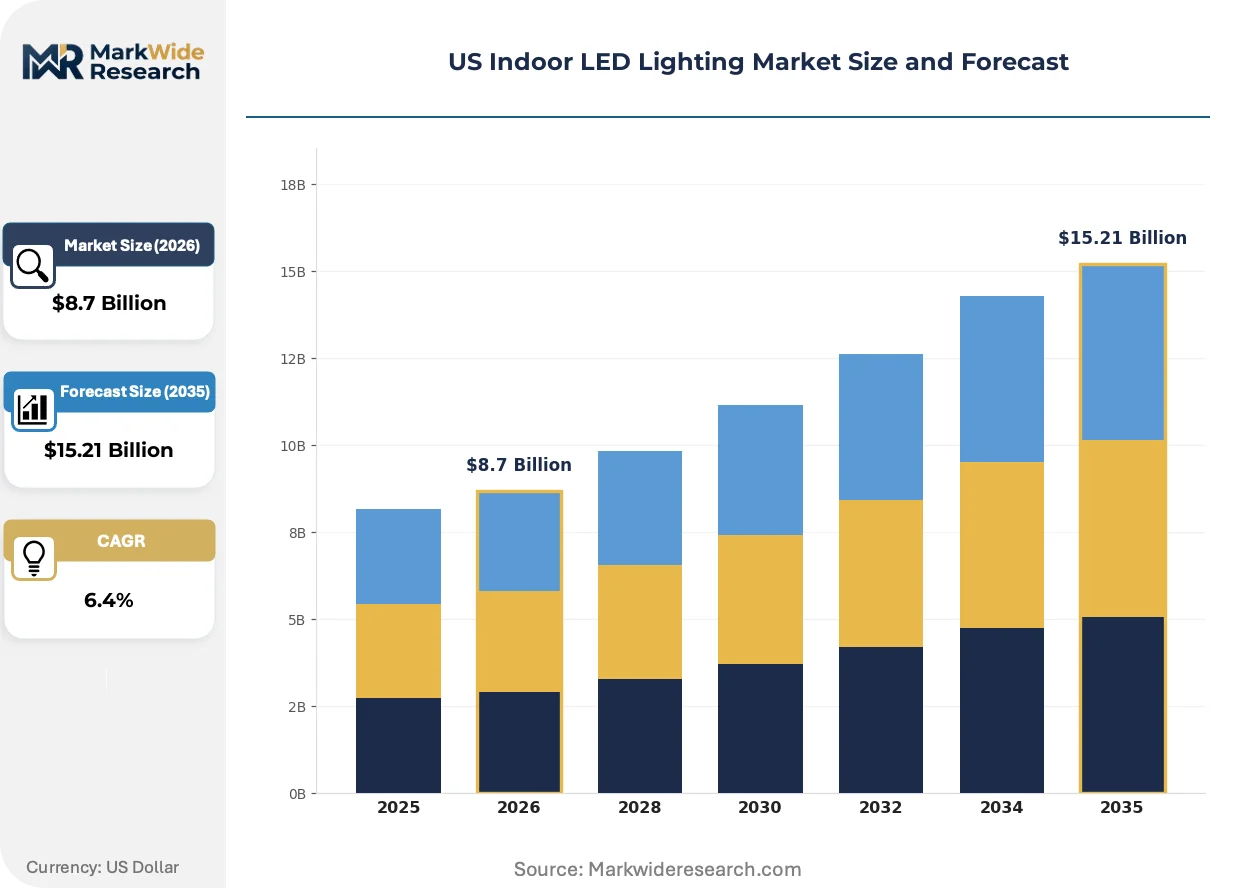
Market Dynamics
California's Title 24 Building Energy Efficiency Standards are compressing fixture replacement cycles and forcing control-integrated specifications across commercial construction, rewiring procurement workflows nationwide.
Growth Catalysts
- Utility Rebate Programs:California Energy Commission and Texas utility administrators accelerate payback periods for LED retrofits in commercial offices and education facilities.
- DOE Efficiency Standards:Federal minimum efficacy requirements phase out legacy fluorescent systems and mandate high-lumen-per-watt performance in new federal buildings.
- Smart Building Integration:IoT-enabled luminaire-and-sensor packages capture facility management budgets as enterprises consolidate vendor relationships.
Market Restraints
- Chip Supply Concentration:Gallium nitride substrate production concentrates in Asian foundries, exposing US fixture manufacturers to input volatility and extended lead times.
- Retrofit Capex Burden:Full-building LED conversions require simultaneous control infrastructure upgrades, stretching municipal and school district capital planning horizons.
- Technical Ceiling:System efficacy gains above 150 lumens per watt encounter thermal management constraints that demand costly ceramic substrate materials.
Strategic Opportunities
- Grid-Interactive Buildings:FERC Order 2222 and emerging state-level demand response mandates position tunable white systems for frequency regulation revenue streams.
- Healthcare Circadian Lighting:Tunable CCT systems penetrate hospital and senior living specifications as Joint Commission guidelines emphasize patient sleep-cycle management.
- Residential Smart Retrofit:Big-box retail and direct-to-consumer channels bypass traditional electrical distributor networks for downlight and retrofit kit sales.
Industry Challenges
- Controls Integration Complexity:Facility managers face fragmented commissioning protocols when merging LED fixtures with existing BACnet and proprietary building automation systems.
- Lighting Designer Skill Shortages:Specifier fluency in photometric modeling and circadian metrics lags behind product capability, compressing value capture for advanced systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Indoor LED Lighting Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Lights, Downlights, Troffers, Ceiling Lights Application: Residential, Commercial, Industrial, Hospitality Technology: Smart Lighting, Dimmable LED, RGB LED, Direct Lighting Distribution Channel: Online Stores, Wholesalers, Retail Outlets, Direct Sales |
| Companies Covered | Acuity Brands, Inc., Cree LED (SMART Global Holdings, Inc.), Current Lighting Solutions, LLC., Signify (Philips), ams-OSRAM AG, Feit Electric Company, Inc., Hubbell Incorporated, Dialight, Eaton Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Indoor LED Lighting Market Trends and Innovations
Human-centric lighting specifications and embedded sensor architectures are displacing commodity lumen-for-dollar procurement in commercial verticals, elevating software and control content in fixture valuations.
Tunable white LED systems with independently addressable warm and cool diode channels are rewriting specification criteria in healthcare and education verticals. Hospital administrators and school facility directors adopt circadian-optimized installations to support patient recovery and student alertness metrics. This technology is compressing the premium gap between standard fixed-CCT fixtures and intelligent lighting configurations, forcing mid-tier manufacturers to accelerate control partnerships or cede specification share.
OSHA workplace illumination guidelines are tightening minimum maintained illuminance requirements in manufacturing and warehouse environments. Industrial facility operators face compliance-driven relamping schedules that favor LED high-bay systems with integrated motion sensing. The warehousing and logistics segment responds with rapid-payback retrofit programs that bundle fixture replacement with utility incentive capture.
Electrical contractors and facility managers now demand pre-commissioned luminaire-and-control packages rather than discrete component sourcing. Traditional distributor-led specification is fragmenting as direct manufacturer relationships and software-subscription models capture ongoing service revenue. This channel compression is most visible in Texas and Florida commercial construction markets where design-build contracts consolidate procurement authority with general contractors.
US Indoor LED Lighting Market Segmentation
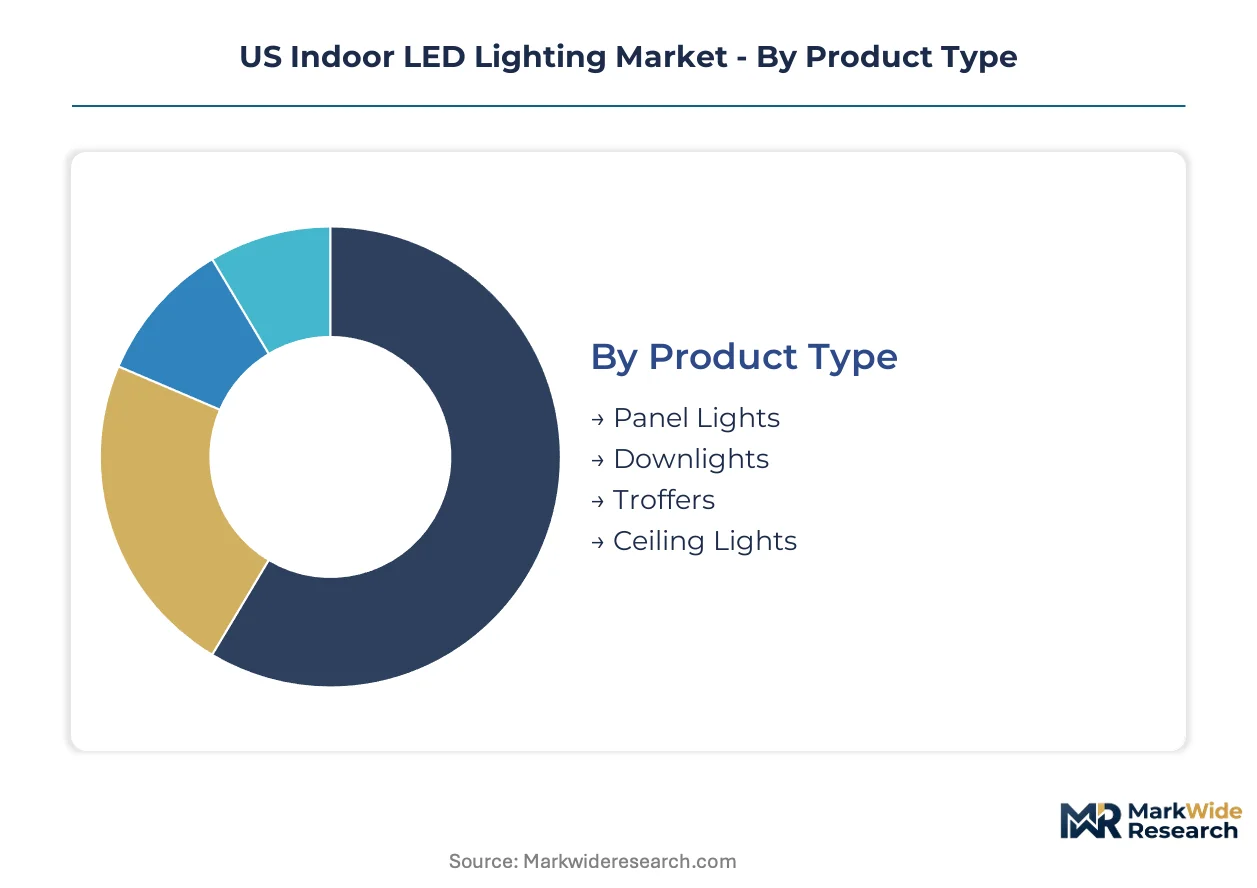
Segmentation in the US Indoor LED Lighting Market reveals how procurement authority, specification complexity, and channel economics diverge across fixture categories. Understanding these splits illuminates where margin pools concentrate and where commoditization pressures intensify.
Product Type:
Panel lights and troffers dominate commercial volume, while downlights capture residential premium pricing. Ceiling lights serve as the economy tier across retrofit applications.
- Panel Lights:Flat-profile luminaires utilizing edge-lit or direct-backlit LED arrays with aluminum frame construction, typically specified in 2x2 and 2x4 foot configurations for suspended ceiling grids. California office retrofits and Texas education facilities drive specification volume as Title 24 mandates accelerate replacement cycles.
- Downlights:Recessed aperture fixtures employing COB or SMD LED engines with integral thermal management, available in 4-inch to 8-inch trim diameters with warm-dim or tunable white options. Residential new construction in Florida and hospitality renovations in Nevada concentrate demand where compact form factors and aesthetic flexibility command specification premiums.
- Troffers:Lay-in fixtures designed for T-bar ceiling systems, offering the lowest installed cost per lumen in commercial retrofits.
- Ceiling Lights:Surface-mounted or semi-flush fixtures serving residential and light commercial applications where budget constraints override performance specifications.
Today's leader: Panel lights. Tomorrow's challenger: Downlights.
Application:
Commercial verticals generate the majority of fixture volume, though residential channels show the steepest expansion trajectory as smart home integration accelerates.
- Commercial:Office, retail, and institutional installations requiring high-efficacy systems with integrated controls for daylight harvesting and occupancy sensing. California and Texas utility rebate programs compress payback periods for full-building retrofits in this vertical.
- Residential:Single-family and multifamily installations where aesthetic integration and smart home compatibility drive specification. Direct-to-consumer channels and big-box retail bypass traditional electrical distribution in this segment.
- Industrial:Warehouse and manufacturing facilities requiring high-bay and linear high-bay configurations with motion sensing for OSHA compliance.
- Hospitality:Hotels, restaurants, and entertainment venues prioritizing dimming performance, color quality, and fixture design over raw efficacy metrics.
Commercial commands current procurement budgets. Residential is climbing the fastest.
Technology:
Smart lighting configurations capture expanding specification share as building automation convergence elevates software content in fixture valuations.
- Smart Lighting:Networked luminaires with embedded sensors, wireless connectivity, and API-accessible control platforms enabling occupancy analytics and grid-interactive demand response. Healthcare and education verticals in California adopt circadian-optimized tunable systems for patient recovery and student performance metrics.
- Dimmable LED:Phase-cut or 0-10V dimming capable fixtures serving hospitality and residential applications where ambiance control is essential.
- RGB LED:Color-mixing systems for architectural accent, entertainment, and branded environment applications.
- Direct Lighting:Basic on/off fixtures without control integration, remaining relevant in cost-constrained municipal and school district retrofits.
Smart lighting owns the premium tier. Dimmable LED defends the mainstream.
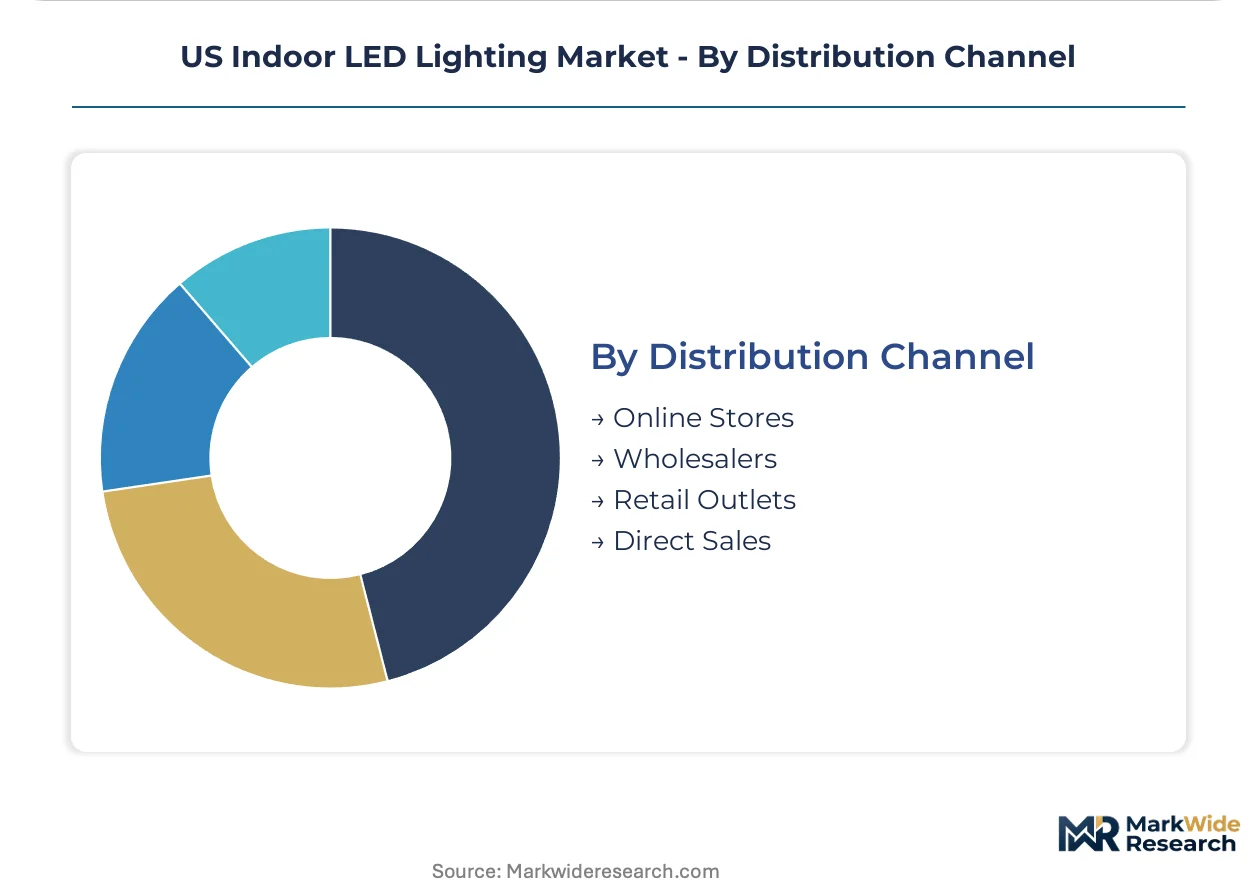
Distribution Channel:
Channel compression is fragmenting traditional electrical distributor dominance as manufacturers build direct relationships and digital platforms capture residential volume.
- Wholesalers:Traditional electrical distributors serving commercial contractors with specification support, credit terms, and project logistics. Texas and Florida design-build contracts are consolidating procurement authority with general contractors, eroding distributor influence.
- Direct Sales:Manufacturer-to-end-user relationships for large commercial and industrial accounts, often bundled with software subscriptions and ongoing service agreements.
- Online Stores:E-commerce platforms capturing residential downlight and retrofit kit volume through search-optimized product listings and consumer reviews.
- Retail Outlets:Big-box home improvement chains serving the DIY residential segment with limited SKUs and immediate availability.
Wholesalers retain commercial control. Direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Indoor LED Lighting industry traces its commercial scaling to California's early energy efficiency mandates in the 2000s, which established the regulatory template that other states subsequently adopted. This west-coast origin shaped a market where code compliance and utility incentives now drive procurement patterns across diverse state economies.
California
Title 24 Building Energy Efficiency Standards mandate automatic daylight dimming and vacancy sensing in new commercial construction, compressing fixture replacement cycles. The California Energy Commission administers utility rebate programs that accelerate payback periods for LED retrofits in office and education facilities. The Los Angeles Basin and Bay Area concentrate specification activity where design-build contracts consolidate procurement authority.
Texas
Commercial office construction and warehouse expansion in Dallas-Fort Worth and Houston generate substantial troffer and high-bay demand. State utility administrators operate rebate programs that mirror California's incentive structures without equivalent mandatory controls. The Austin metro area anchors emerging smart building integration projects tied to technology sector facility investments.
Florida
Residential new construction and hospitality renovations concentrate demand for downlights with warm-dim functionality. The state's building code adopts IECC standards with amendments that favor high-efficacy fixtures in commercial applications. Miami and Orlando metropolitan areas drive specification volume where hurricane-resistant construction practices intersect with energy efficiency requirements.
New York Metro
Local Law 97 carbon emission limits and the state's Clean Energy Standard pressure commercial building owners toward comprehensive lighting retrofits. The New York State Energy Research and Development Authority finances LED conversion programs for municipal and educational facilities. The five-borough area and adjacent northern New Jersey counties concentrate installation activity in aging commercial stock.
Pacific Northwest
Seattle and Portland municipal codes emphasize dark-sky compliance and circadian lighting in public buildings. Bonneville Power Administration and regional utilities maintain incentive programs for commercial and industrial LED adoption. The region's technology sector drives early adoption of tunable white and human-centric lighting specifications in workplace environments.
US Indoor LED Lighting Market Competitive Landscape
Premium-margin players sit above commodity-margin players across control integration and software content, with the former capturing facility management budgets and the latter competing on lumen-per-dollar metrics. The vendor base organizes into three tiers: full-stack providers bundling luminaires with IoT platforms, component specialists supplying chip-on-board engines and optical systems, and private-label assemblers serving price-sensitive residential channels. Dominant competitive moves include strategic partnerships between fixture manufacturers and building automation vendors, plus portfolio diversification into circadian and tunable white product lines.
Within the full-stack tier, Acuity Brands, Inc. and Signify (Philips) occupy positions defined by software ecosystem integration, while Cree LED (SMART Global Holdings, Inc.) exemplifies the component-specialist archetype with concentrated expertise in semiconductor emitter architectures. These three entities represent distinct strategic postures: one emphasizing intelligent building contracts, another leveraging global brand recognition in facility management software, and the third anchoring premium downlight specifications through thermal management innovation.
| Leading Market Players |
|---|
| Acuity Brands, Inc. |
| Cree LED (SMART Global Holdings, Inc.) |
| Current Lighting Solutions, LLC. |
| Signify (Philips) |
| ams-OSRAM AG |
| Feit Electric Company, Inc. |
| Hubbell Incorporated |
| Dialight |
| Eaton Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up fixture specialists now dominate mid-market luminaire production, compressing procurement timelines while enforcing three-tier pricing discipline across premium smart configurations, standard dimmable SKUs, and economy-grade direct lighting. This ownership concentration channels working capital toward control-integration R&D rather than component cost reduction, insulating premium tiers from commodity price erosion while squeezing margin pools in undifferentiated troffer and panel categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs fixture transactions, with certification grade and volume scale as the primary differentiation drivers. Price differentiation separates UL-certified smart luminaires with embedded sensors from basic DLC-qualified troffers and uncertified residential retrofit kits. Pricing pressure stems from utility rebate arbitrage compressing visible payback premiums for mid-tier products. Municipal and school district buyers exhibit highest price sensitivity, while healthcare facility directors prioritize circadian performance over unit cost.
Supply Chain Analysis
Ocean freight rates from Asian semiconductor foundries to US West Coast ports directly impact landed costs for gallium nitride substrates and packaged LED emitters. Supply concentrates in Taiwan, South Korea, and China for GaN-on-sapphire wafer production, with aluminum substrate fabrication and optical diffuser materials drawing from domestic US and Mexican metalworking capacity. Single-source vulnerability in epitaxial wafer supply exposes fixture manufacturers to allocation risk during foundry capacity constraints. Distribution runs through electrical wholesalers in commercial verticals, direct manufacturer relationships for large accounts, and e-commerce platforms for residential retrofit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's Title 24 Building Energy Efficiency Standards function as a regulatory compounder, mandating control-integrated specifications that accelerate fixture replacement cycles and reshape procurement authority toward general contractors and facility managers.
For Market Incumbents: Deploy software ecosystem lock-in to defend specification share against emerging IoT platform entrants. Deepen partnerships with building automation vendors to secure BACnet integration certification, while accelerating tunable white product line diversification to capture healthcare circadian lighting budgets before mid-tier competitors achieve Joint Commission guideline compliance. For New Entrants and Emerging Players: Enter via residential smart retrofit channels where big-box retail and direct-to-consumer platforms bypass entrenched electrical distributor networks. Target Florida and Texas single-family construction markets with warm-dim downlight SKUs optimized for design-build contractor procurement workflows, leveraging Amazon and Home Depot marketplace visibility to establish brand recognition before commercial specification penetration. For Investors and Strategic Acquirers: Valuations sit cheapest among component-specialist chip-on-board engine manufacturers lacking downstream fixture integration, relative to full-stack providers with recurring software revenue. Long-term viability hinges on grid-interactive building standard adoption creating demand response revenue streams for tunable white systems. Watch FERC Order 2222 implementation timelines across ISO/RTO territories as the signal for control-integrated fixture demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Control Platform Integration | Acuity's Atrius and Signify's Interact ecosystems capture facility management budgets through API-accessible lighting analytics. |
| Circadian Product Line Expansion | Tunable CCT systems penetrate hospital specifications as Joint Commission guidelines emphasize patient sleep-cycle management protocols. |
| Direct-to-Consumer Channel Buildout | Feit Electric and residential-focused brands bypass electrical distributors via Amazon and Home Depot marketplace optimization. |
| GaN-on-Ceramic Thermal Architecture Investment | Cree LED's high-efficacy chip-on-board designs command specification premiums in premium downlight and hospitality applications. |
| Utility Rebate Program Partnership | California Energy Commission and Texas administrator relationships compress customer payback periods and accelerate retrofit conversion velocity. |
Research Methodology
Direct dialogue with electrical contractors, facility managers at commercial office portfolios, lighting specification engineers, and utility program administrators anchored qualitative grounding, cross-referenced against California Energy Commission rebate databases, DOE appliance standard filings, OSHA workplace illumination guidelines, and SEC 10-K disclosures from publicly traded fixture manufacturers. Secondary validation drew from Title 24 compliance documentation, utility incentive program impact evaluations, and architectural specification trend reports. Bottom-up fixture shipment estimates by product category and application vertical triangulated against top-down construction spending and energy efficiency investment flows.
Market size and growth trajectory outputs across the analysis window reflect segmentation by product type, application vertical, technology tier, and distribution channel, with CAGRs derived from regression against historical replacement cycle data and regulatory mandate implementation schedules. Forecast inputs incorporated utility rebate program budget allocations, commercial construction permit trends in California and Texas, and smart building automation penetration rates in healthcare and education facilities.
Inputs from utility administrators and lighting specification professionals were available through the study window; gaps in real-time foundry capacity utilization and gallium nitride substrate pricing introduce uncertainty bands around component cost assumptions. Forecasts reflect documented assumptions regarding Title 24 adoption timelines and FERC demand response rulemaking. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Portable Lamps Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Battery Operated Lights Market
Lighting
Residential Lighting Fixtures Market
Lighting
Tritium Light Source Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
LED Eye Protection Lamp Market
Lighting
Illuminating Signs Market
Lighting
Photography Light Box Market
Lighting
Global Plasma Lamp Market
Lighting
Smart Lights Market
Lighting
Gesture Control Light Market
Lighting
Ambient Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
Solar Lights Market
Lighting
Digital Light Processing Technology Market