
 Industrial Oil Filter Machine Market | 2026-2036
Industrial Oil Filter Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Oil Filter Machine Market Insights
EPA effluent limitation guidelines is consolidating compliance burdens for metalworking and petrochemical facilities, forcing smaller operators toward automated filtration upgrades. Donaldson Company leverages its vertically integrated media manufacturing to sustain pricing power across North American power generation accounts. Mann+Hummel Group anchors its position through R&D intensity in centrifugal separation technology for heavy equipment operators. Parker-Hannifin Corporation competes on hydraulic system integration, bundling filter machines with condition monitoring services.
An industrial oil filter machine removes particulate contaminants, water, and oxidation byproducts from lubricating and hydraulic oils through mechanical, centrifugal, or magnetic separation processes, typically achieving ISO 4406 cleanliness codes of 18/16/13 or finer. These systems extend fluid service life from months to years, cutting disposal costs and preventing catastrophic wear in precision machinery. Automatic oil filter systems command the widest installed base across continuous-process industries, while vacuum oil filter technology captures the fastest growth trajectory in transformer oil regeneration and high-voltage power applications. Centrifugal filtration dominates margin pools in marine and heavy-duty sectors where water ingress demands robust separation performance.
OSHA permissible exposure limits for oil mist and EPA hazardous waste rules for spent lubricants directly shape machine design specifications and aftermarket service contracts. ISO 4406 cleanliness standards and EU REACH chemical registration requirements further constrain material choices and filter media formulations for exporters. Stakeholders must monitor evolving state-level PFAS restrictions and carbon border adjustments, as these mechanisms will redefine total cost of ownership calculations and supplier qualification timelines.
Market Dynamics
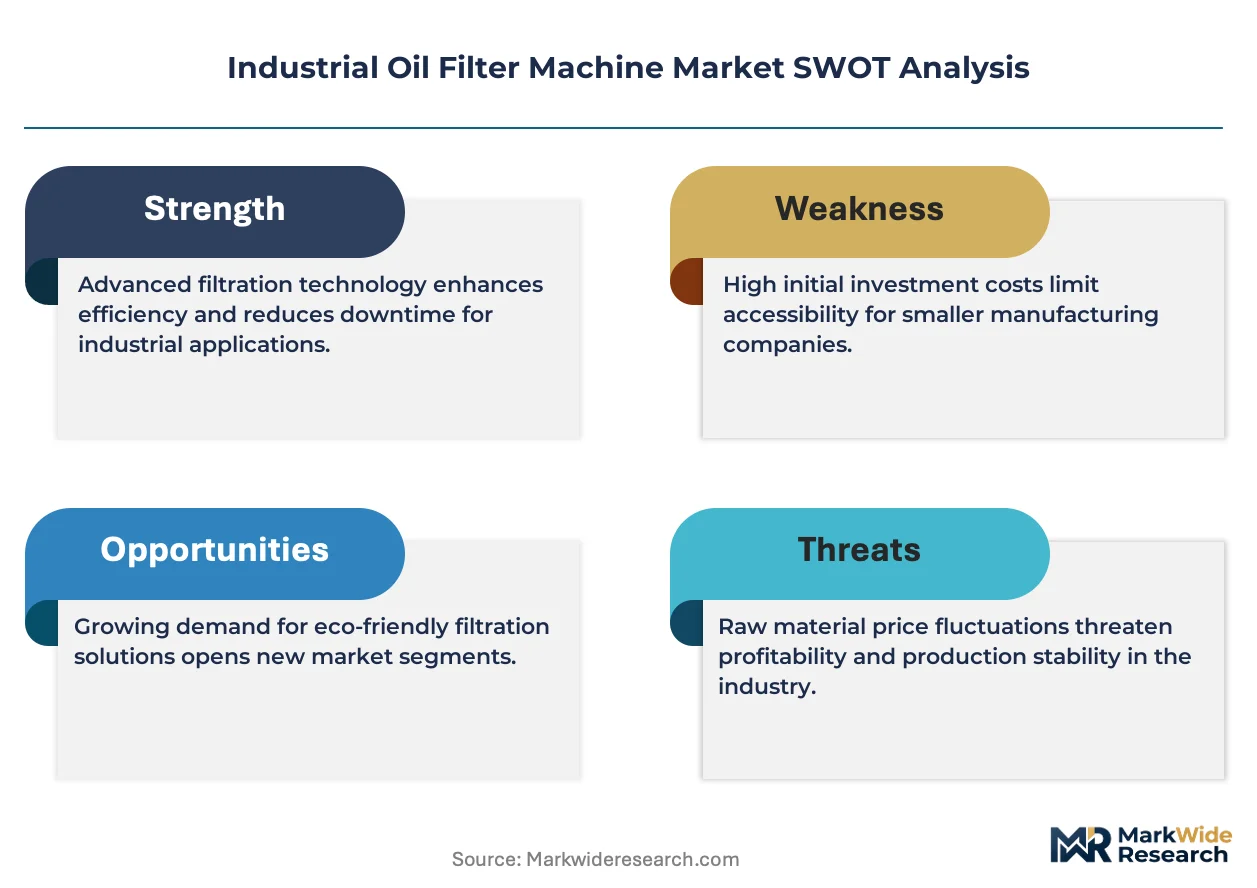
EPA effluent limitation guidelines are consolidating compliance burdens across metalworking and petrochemical facilities, forcing smaller operators toward automated filtration upgrades and compressing vendor selection timelines.
Growth Catalysts
- Power generation asset protection:Turbine and generator operators in the United States are expanding adoption of advanced filtration systems to extend equipment lifecycles and reduce unplanned outages.
- REACH chemical registration:EU exporters are reformulating filter media to meet contamination control specifications, creating pull for premium purification equipment across German precision manufacturing networks.
- Centrifugal separation R&D:Heavy equipment operators are demanding robust water separation performance, driving investment in next-generation centrifugal technology for marine and mining applications.
Market Restraints
- Specialized alloy input costs:Stainless steel and corrosion-resistant housing materials face price volatility from concentrated mining supply, squeezing margins on custom-engineered systems.
- Filter media supply concentration:Synthetic fiber and cellulose media production clusters in select Asian manufacturing hubs, exposing buyers to single-source risk during logistics disruptions.
- Technical limitation in high-viscosity fluids:Conventional mechanical filtration struggles with heavy gear oils above ISO VG 680, restricting addressable market in certain industrial lubrication applications.
Strategic Opportunities
- Transformer oil regeneration:Vacuum oil filter technology captures expanding demand from high-voltage power applications as grid infrastructure ages across North American utilities.
- PFAS restriction tailwinds:Evolving state-level chemical bans in the United States will redefine total cost of ownership calculations, favoring suppliers with advanced material qualification capabilities.
- Condition monitoring convergence:Integration of IoT sensors with filtration systems enables predictive maintenance contracts, creating recurring revenue streams beyond equipment sales.
Industry Challenges
- ISO 4406 certification timelines:Third-party cleanliness verification for export markets extends product launch cycles and strains engineering resources at mid-scale manufacturers.
- Legacy hydraulic system integration:Retrofitting automated filtration into existing plant infrastructure requires custom plumbing and control interface development, complicating project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Oil Filter Machine Market |
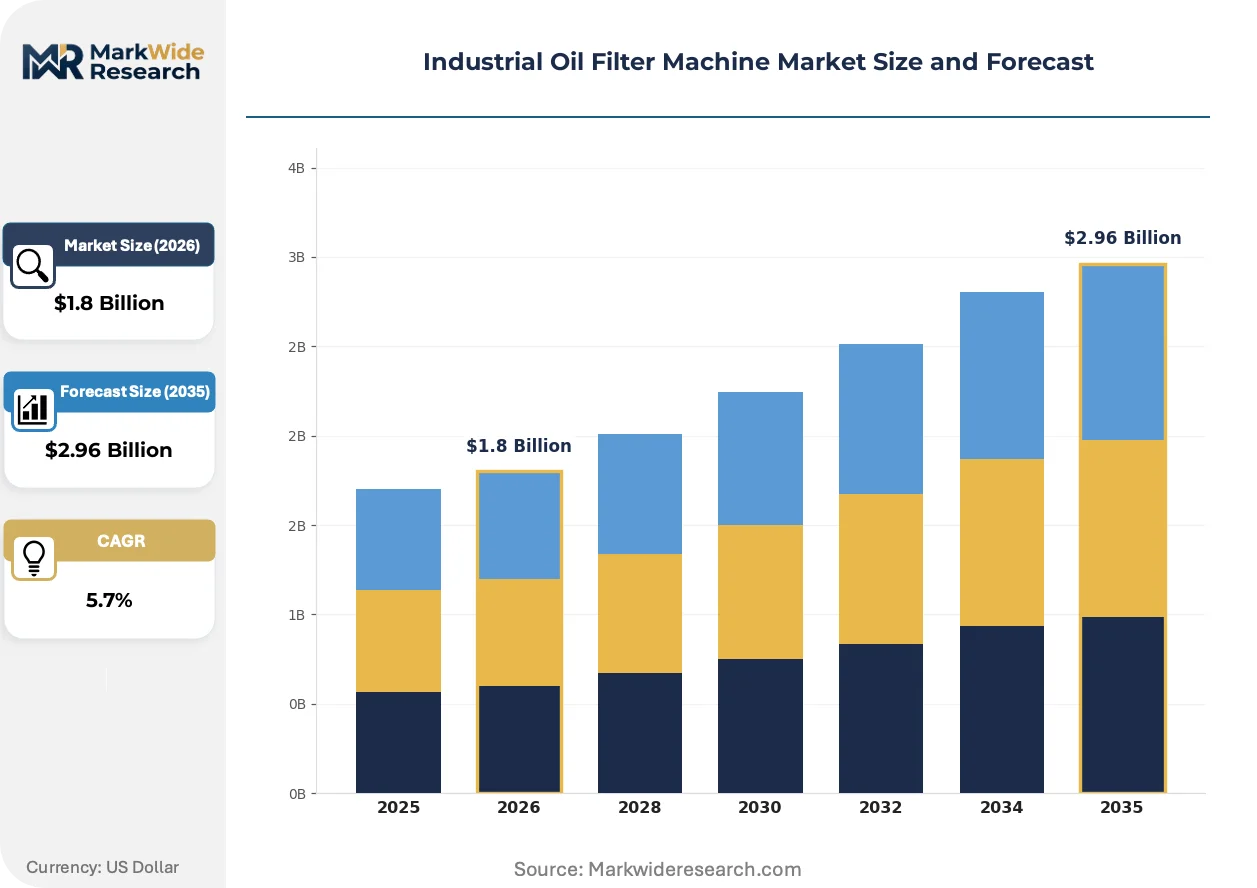
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Oil Filter, Manual Oil Filter, Portable Oil Filter, Stationary Oil Filter, Vacuum Oil Filter Technology: Mechanical Filtration, Centrifugal Filtration, Pressure Filtration, Magnetic Filtration, Absorption Filtration Application: Metalworking Facilities, Power Generation Plants, Chemical Processing Units, Food Processing Plants, Textile Manufacturing End User: Machinery Manufacturers, Equipment Repair Shops, Lubricant Suppliers, Petrochemical Facilities, Heavy Equipment Operators |
| Companies Covered | Donaldson Company, Inc., Mann+Hummel Group, MAHLE GmbH, Parker-Hannifin Corporation, Eaton, Cummins Inc., 3M, Danaher, Minimac Systems Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Oil Filter Machine Market Trends and Innovations
Vacuum dehydration technology is actively reshaping competitive positioning in high-voltage electrical applications, while regulatory pressure on hazardous waste disposal accelerates equipment refresh cycles across heavy industry.
Coalescing filter elements with synthetic glass media are overtaking conventional cellulose configurations in transformer oil regeneration applications. North American utilities facing aging grid infrastructure are adopting these systems at accelerated pace to maintain dielectric strength in high-voltage equipment. This technology shift is compressing replacement intervals for traditional vacuum purifiers and elevating performance benchmarks across the power generation segment.
EPA hazardous waste rules for spent lubricants are tightening manifesting and disposal documentation requirements for metalworking facilities. These regulations force smaller machine shops to upgrade from passive settling tanks to active purification equipment or face escalating compliance penalties. The automotive supplier tier in the Midwestern United States is responding fastest, bundling filtration upgrades with broader shop modernization programs.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance bundles into componentized offerings. Independent fluid analysis laboratories and mobile filtration service providers are capturing aftermarket value previously retained by original equipment manufacturers. This channel disintermediation is most visible in German automotive supplier networks, where precision manufacturers prefer specialized contamination monitoring over bundled service packages.
Industrial Oil Filter Machine Market Segmentation
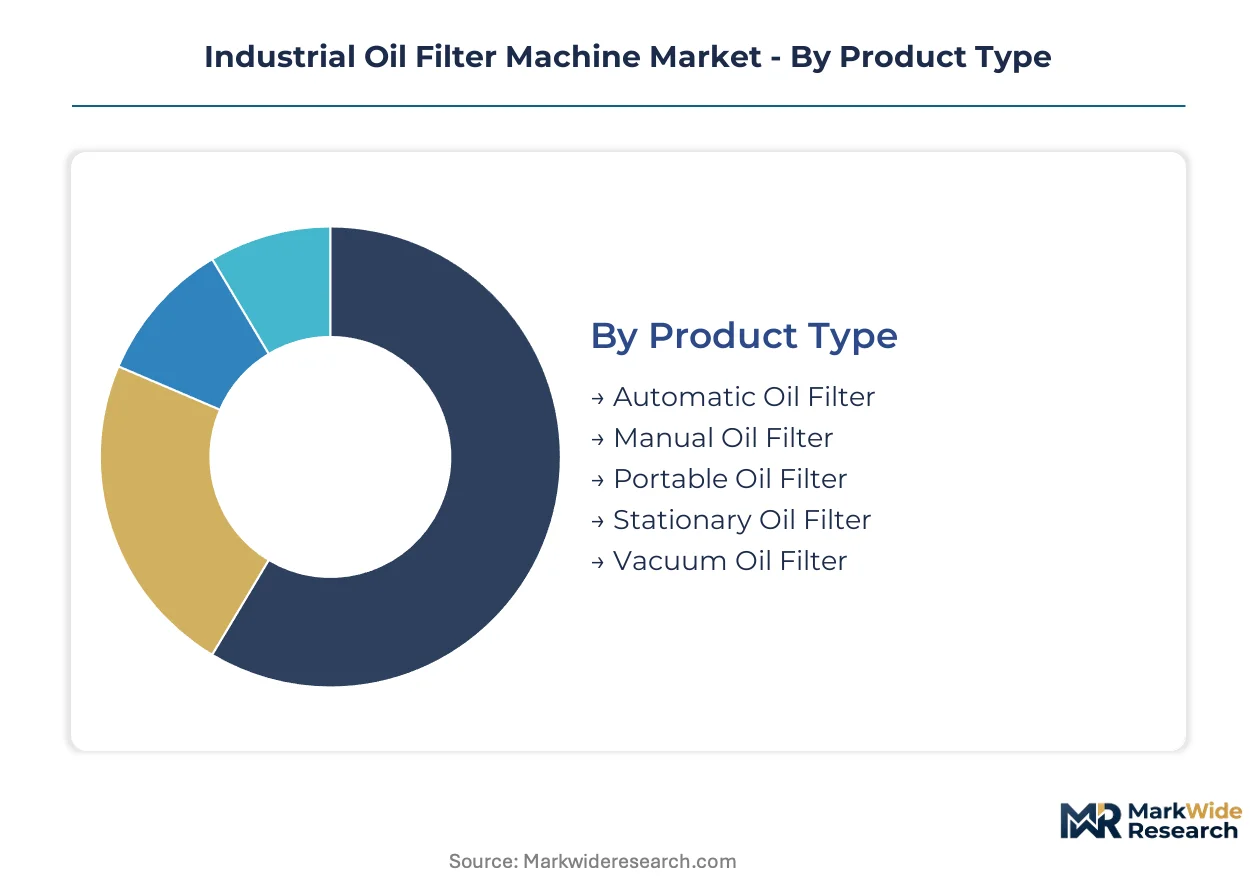
Industrial oil filter machine segmentation reflects divergent capital intensity and operational requirements across end-use environments. Equipment specifications vary sharply between continuous-process installations and intermittent maintenance applications, with technology selection directly tied to fluid viscosity, contamination load, and regulatory exposure.
Product Type:
Volume concentration sits with automatic systems, while vacuum technology commands premium positioning in specialized electrical applications.
- Automatic Oil Filter:Continuous-operation systems integrate pump-driven circulation with self-cleaning backflush mechanisms, achieving unattended runtime exceeding 8,000 hours. Power generation plants in the United States specify these configurations for turbine lube oil circuits, driven by FERC reliability standards and outage cost minimization.
- Vacuum Oil Filter:Dehydration and degasification units operate at absolute pressures below 5 mbar, removing dissolved moisture to below 10 ppm in transformer oils. North American utilities facing aging grid infrastructure are accelerating replacement of conventional purifiers, with dielectric strength restoration requirements tightening acceptance criteria.
- Manual Oil Filter:Hand-operated systems with batch processing capacity suit low-volume maintenance operations in equipment repair shops.
- Portable Oil Filter:Mobile cart-mounted units with integrated power supplies enable on-site fluid conditioning for mining and construction fleets.
- Stationary Oil Filter:Fixed-installation systems with permanent plumbing dominate metalworking facility central coolant systems.
Today's leader: Automatic Oil Filter. Tomorrow's challenger: Vacuum Oil Filter.
Technology:
Mechanical methods anchor installed base economics, whereas centrifugal separation captures margin pools in water-ingress applications.
- Mechanical Filtration:Depth and surface media configurations using cellulose, synthetic fiber, or wire mesh achieve ISO 4406 codes down to 15/13/10 for hydraulic circuits. German automotive supplier networks specify multi-stage mechanical systems for precision machining centers, with REACH-compliant media formulations now mandatory for EU market access.
- Centrifugal Filtration:High-speed bowl separators generate gravitational forces exceeding 5,000 G, separating water and dense particulate without consumable media replacement. Marine propulsion systems and mining haul trucks specify these units for severe water contamination environments, where ingress tolerance determines equipment lifecycle.
- Pressure Filtration:Positive-discharge systems with plate-and-frame or cartridge configurations handle high-viscosity gear oils above ISO VG 680.
- Magnetic Filtration:Rare-earth drum or rod assemblies extract ferrous wear debris without flow restriction, extending primary filter service intervals.
- Absorption Filtration:Activated clay or fuller's earth media remove oxidation byproducts and acidic contaminants in lubricant regeneration applications.
Centrifugal Filtration holds the steepest expansion trajectory in heavy-duty sectors, while Mechanical Filtration defends volume leadership through lower capital thresholds.
Application:
Power generation commands specification intensity, while metalworking drives unit volume through distributed machine shop populations.
- Power Generation Plants:Combined-cycle turbine installations require continuous oil purification maintaining cleanliness codes of 16/14/11 or finer to protect bearing surfaces and control systems. EPA discharge regulations for wastewater streams are compelling upgrades from passive settling to active filtration, particularly at facilities with cooling tower blowdown integration.
- Metalworking Facilities:Central coolant systems and individual machine sumps generate high particulate loads from chip generation and tool wear. Midwestern United States automotive supplier tiers are bundling filtration modernization with broader shop automation investments, responding to tightened hazardous waste documentation requirements.
- Chemical Processing Units:Corrosive fluid handling demands exotic alloy construction and specialized seal materials for reactor pump lubrication.
- Food Processing Plants:NSF H1-registered lubricant filtration requires stainless steel construction and sanitary design protocols for incidental contact applications.
- Textile Manufacturing:Synthetic fiber production lines utilize oil mist collectors and hydraulic fluid maintenance systems for loom and knitting machinery.
Power Generation Plants set performance benchmarks; Metalworking Facilities provide volume foundation.
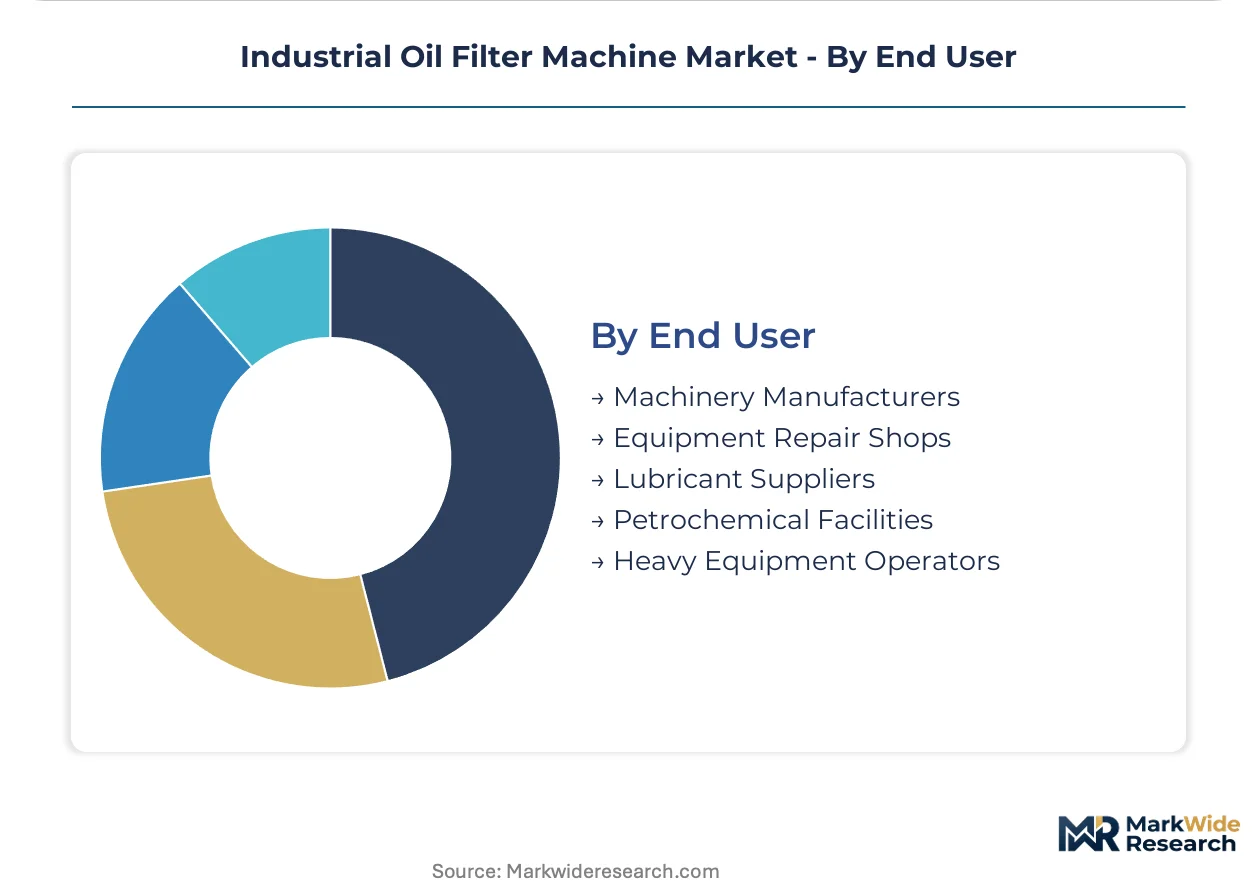
End User:
Machinery manufacturers specify at point of design, while lubricant suppliers build aftermarket service integration.
- Machinery Manufacturers:OEM integration of filtration systems at production enables extended warranty terms and predictive maintenance platform bundling. German precision machine tool builders are specifying IoT-enabled condition monitoring as standard, creating captive demand for compatible purification equipment.
- Heavy Equipment Operators:Fleet maintenance departments prioritize total fluid management programs combining filtration with analysis and reclamation services. Mining operations in water-ingress environments specify centrifugal separation for final drive and transmission circuits, where contamination tolerance directly correlates with component replacement intervals.
- Equipment Repair Shops:Independent service providers utilize portable and manual systems for contract fluid conditioning.
- Lubricant Suppliers:Distributors bundle filtration equipment with fluid sales to secure volume commitments and recurring filter element revenue.
- Petrochemical Facilities:Refinery maintenance departments specify high-pressure systems for compressor lube oil circuits in process-critical applications.
Machinery Manufacturers control specification gates; Heavy Equipment Operators are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial oil filter machine industry traces its modern scaling to German precision engineering clusters in the 1960s, where automotive supplier networks demanded contamination control systems capable of supporting automated machining centers. That heritage continues to shape specification standards and export demand patterns across industrialized economies.
United States
Power generation utilities and Midwestern automotive suppliers drive equipment procurement, with turbine operators requiring continuous oil purification to meet FERC reliability standards. EPA effluent limitation guidelines for metalworking facilities are accelerating upgrades from passive settling tanks to active filtration systems. Michigan and Ohio machine shop clusters are bundling filtration modernization with broader automation investments to satisfy tightened hazardous waste documentation rules.
Germany
Precision manufacturing networks and automotive supplier tiers anchor demand for REACH-compliant media formulations and multi-stage mechanical systems. The country's national chemical regulator enforces strict contamination control specifications that filter media producers must satisfy for EU market access. Stuttgart and Munich industrial corridors specify IoT-enabled condition monitoring as standard equipment, creating specification pull for compatible purification systems.
China
Heavy equipment manufacturing and expanding power generation capacity support centrifugal and automatic system deployment across industrial provinces. The Ministry of Ecology and Environment enforces dual carbon goals that pressure facilities to extend fluid service life and reduce hazardous waste generation. Yangtze River Delta manufacturing clusters are adopting vacuum dehydration technology for transformer oil regeneration as grid infrastructure expands.
India
Mining operations and construction equipment fleets generate demand for portable and centrifugal filtration systems capable of handling severe water contamination environments. The Central Electricity Authority mandates dielectric strength standards for transformer oils that drive vacuum purifier adoption across state utilities. Maharashtra and Gujarat industrial zones are specifying automatic backflush systems for continuous-process lubrication circuits in cement and steel plants.
Japan
Precision machine tool builders and semiconductor manufacturing equipment suppliers specify ultra-clean hydraulic and lubricant systems for automated production lines. METI industrial efficiency programs incentivize fluid life extension technologies that reduce disposal costs and environmental compliance burdens. Osaka and Nagoya manufacturing clusters are integrating filtration systems with predictive maintenance platforms at the OEM specification stage.
Industrial Oil Filter Machine Market Competitive Landscape
The competitive structure tilts toward diversified filtration conglomerates with captive media manufacturing capabilities. Vendor positioning concentrates across three tiers: integrated system suppliers bundling equipment with condition monitoring services, specialized centrifugal technology developers serving marine and mining applications, and regional fabricators competing on custom-engineered solutions for specific viscosity or alloy requirements. Dominant competitive moves include backward integration into synthetic fiber and cellulose media production, and technology licensing arrangements that accelerate geographic expansion without capital-intensive manufacturing footprints.
Within the diversified conglomerate tier, Donaldson Company, Inc. and Parker-Hannifin Corporation exemplify positioning through hydraulic system integration and vertically controlled supply chains. Mann+Hummel Group occupies a position among European-based specialists with R&D intensity in separation technologies. These three anchors represent distinct strategic postures: North American system integration, German precision engineering heritage, and global scale through multi-technology portfolios.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Mann+Hummel Group |
| MAHLE GmbH |
| Parker-Hannifin Corporation |
| Eaton |
| Cummins Inc. |
| 3M |
| Danaher |
| Minimac Systems Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
Midwestern United States automotive supplier tiers concentrate procurement authority through consolidated shop modernization programs, anchoring a three-tier pricing structure across premium, standard, and economy levels that bundles filtration equipment with broader automation investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 4406-certified systems with predictive maintenance integration from basic mechanical configurations. Price differentiation hinges on REACH-compliant media formulations and IoT-enabled condition monitoring bundling. Cost compression in the economy tier is intensifying because Asian filter media producers are expanding synthetic fiber capacity. Heavy equipment operators in mining applications exhibit lowest price sensitivity due to downtime cost exposure, while independent equipment repair shops face acute margin pressure.
Supply Chain Analysis
Domestic-content mandates in Indian power generation procurement are reshaping sourcing patterns for stainless steel housings and rare-earth magnetic assemblies. Manufacturing gravity draws from Germany, China, and the United States for precision-engineered components and specialized alloys. Raw material dependencies center on cellulose and synthetic fiber media, corrosion-resistant steel alloys, and activated clay absorption media. Single-source vulnerability concentrates in Asian synthetic fiber production clusters. Distribution runs through OEM-integrated specification channels and independent fluid service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as power generation utilities shift specification requirements toward vacuum dehydration systems with dielectric strength restoration capabilities.
For Market Incumbents: Cement pricing power through captive synthetic fiber media manufacturing and predictive maintenance platform bundling. Defend against independent fluid analysis laboratories by integrating IoT sensors at the OEM specification stage. Prioritize certification investment for evolving state-level PFAS restrictions. For New Entrants and Emerging Players: Begin with portable centrifugal systems for Indian mining operations and construction fleets where water-ingress tolerance commands premium positioning. Target equipment repair shops in underpenetrated secondary cities with mobile filtration service models. Pursue lubricant supplier partnership channels for recurring filter element revenue. For Investors and Strategic Acquirers: Diversified filtration conglomerates with backward integration into media manufacturing are the most active acquirer in this space. Long-term viability favors targets with REACH-compliant formulation capabilities and transformer oil regeneration technology portfolios. Monitor EPA effluent limitation guideline enforcement intensity as the signal for equipment refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Media Manufacturing | Captive supply of cellulose and synthetic fiber reduces exposure to Asian production cluster disruptions. |
| IoT-Enabled Condition Monitoring Platform Launch | Predictive maintenance contracts with FERC-regulated utilities create recurring revenue beyond equipment sales. |
| Vacuum Dehydration Technology Licensing | North American grid infrastructure aging accelerates dielectric strength restoration equipment demand. |
| REACH-Compliant Media Formulation Investment | EU chemical registration requirements constrain material choices for German automotive supplier network access. |
| Mobile Filtration Service Expansion | Independent service providers capture aftermarket value from OEM bundles in precision manufacturing corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at power generation facilities, plant engineers in metalworking operations, OEM procurement teams at German machine tool builders, and aftermarket service heads at heavy equipment distributors with secondary validation against EPA discharge filings, FERC reliability reports, EU REACH registration databases, and customs trade data for filtration equipment imports. Bottom-up equipment unit estimates and top-down market sizing triangulated across the analysis window.
Segment-weighting approaches modeled product type, technology, application, and end-user dimensions across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking regulatory enforcement intensity. Industry-specific forecast inputs incorporated transformer oil regeneration demand from aging North American grid infrastructure and centrifugal separation adoption in water-ingress mining environments.
Caveats apply where EPA effluent guideline enforcement delays or PFAS restriction implementation timelines could materially shift the outlook for metalworking facility upgrade cycles. Forecasts reflect assumptions regarding REACH compliance cost pass-through and stainless steel alloy price volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Automatic Tube Cleaning System Market