
 Dewatering Pumps Market | 2026-2036
Dewatering Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Dewatering Pumps Market Intelligence
Skilled pump technician shortages across North American mining corridors is unwinding maintenance backlogs and forcing rental-over-purchase shifts. Xylem Inc. leverages its digital monitoring platforms to anchor long-term service contracts in Appalachian coal basins. Sulzer Ltd. specializes in abrasion-resistant submersible designs that dominate Chilean copper pit dewatering. The Gorman-Rupp Company sustains its position in municipal lift stations through extensive distributor networks across the Great Lakes states.
Dewatering pumps are electromechanical devices engineered to evacuate groundwater or process slurry from excavations, tunnels, and sumps, typically achieving flow rates from 50 to 5,000 gallons per minute and operating against total dynamic heads exceeding 300 feet. Their primary industrial purpose is to maintain dry working conditions that prevent structural collapse, equipment corrosion, and regulatory non-compliance in below-grade construction and resource extraction. Submersible pumps capture the dominant share of product type revenue due to their flood-tolerant motor encapsulation and reduced suction lift constraints in deep-shaft mining. Electric powered solutions are displacing diesel alternatives fastest in European construction sites where CE-marked noise ordinances and urban emissions zones restrict combustion equipment. Municipal end users represent the most defensible margin pool because procurement cycles prioritize lifecycle cost over upfront capital, favoring OEMs with predictive maintenance capabilities.
EPA stormwater regulations and EU F-Gas restrictions on sealed motor cooling systems are elevating product compliance costs while opening preference windows for solar-hybrid and permanent installation configurations. BIS efficiency labeling in India and China's GB motor standards are fragmenting certification requirements, complicating cross-border manufacturing strategies. Stakeholders must weigh whether to regionalize production around divergent efficiency mandates or absorb tariff exposure from centralized assembly.
Market Dynamics
Electric-powered submersible configurations are displacing diesel alternatives across European construction corridors, driven by CE-marked noise ordinances and urban emissions zones that restrict combustion equipment. This technology pivot is compressing rental fleet economics and rewiring procurement priorities toward lifecycle cost optimization.
Growth Catalysts
- EPA Effluent Guidelines:Tightening discharge standards across US municipal wastewater infrastructure are forcing asset owners toward higher-efficiency pump configurations with advanced monitoring capabilities.
- Solar-Hybrid Electrification:Government-subsidized solar dewatering schemes in India's drought-prone agricultural belts are accelerating displacement of diesel-powered irrigation sets.
- EU Green Deal Water Reuse Targets:Circular economy mandates are elevating procurement priority for permanent installation pumps with predictive maintenance integration in Spanish and Italian treatment facilities.
Market Restraints
- Copper and Rare Earth Price Volatility:Motor winding materials and permanent magnet supply concentration in Chinese processing facilities are elevating production cost unpredictability for OEMs.
- F-Gas Cooling Restrictions:EU regulations on sealed motor cooling systems are fragmenting product architectures and elevating compliance engineering overhead.
- Submersible Seal Degradation:Abrasive slurry environments in Chilean copper pits compress mean-time-between-failures, elevating total cost of ownership calculations.
Strategic Opportunities
- Indonesian Infrastructure Upgrades:Municipal wastewater modernization programs across Jakarta and Surabaya corridors are opening procurement windows for electric submersible fleets.
- Digital Service Contract Unbundling:Predictive maintenance platforms are creating recurring revenue pools separate from hardware sales in Appalachian mining basins.
- BIS Efficiency Labeling Tailwinds:India's mandatory motor performance standards are advantaging certified OEMs over unlabeled imports in agricultural procurement tenders.
Industry Challenges
- Pump Technician Scarcity:Skilled maintenance labor shortages across North American mining corridors are unwinding service backlogs and compressing equipment utilization rates.
- Certification Timeline Fragmentation:Divergent efficiency mandates between India's BIS labeling and China's GB motor standards are complicating cross-border manufacturing strategies.
- Legacy Control System Integration:Retrofitting digital monitoring platforms into existing municipal lift station architectures requires specialized protocol bridging expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dewatering Pumps Market |
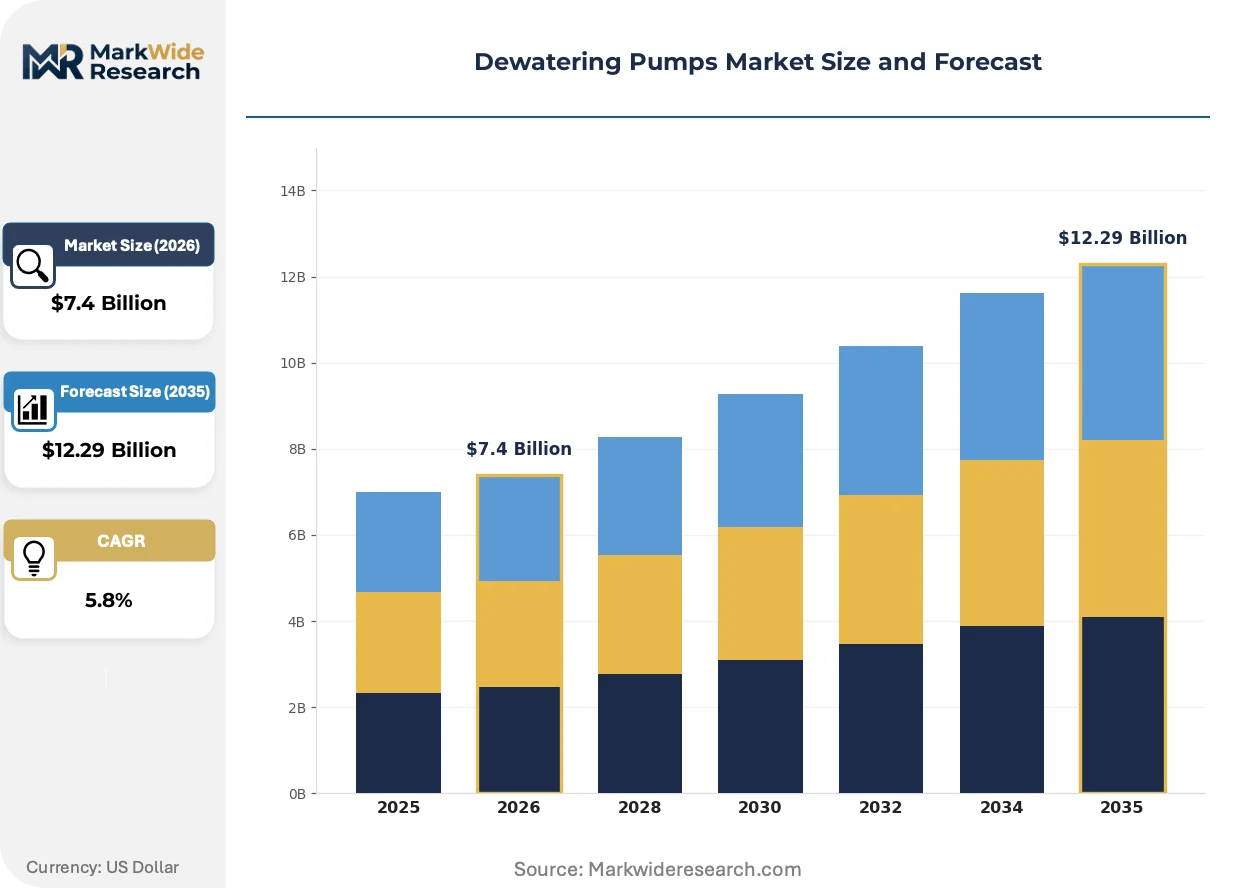
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Utility Pumps, Peristaltic Pumps, Diaphragm Pumps End User: Construction, Mining, Agriculture, Municipalities Solution: Electric Powered, Diesel Powered, Solar Powered, Hybrid Systems Deployment: Temporary Installations, Permanent Installations, Mobile Units, Fixed Units |
| Companies Covered | KSB SE & Co. KGaA, Ebara Corporation, Flowserve Corporation, The Gorman-Rupp Company, Sulzer Ltd., Grundfos Holding A/S, Atlas Copco AB, Wacker Neuson SE, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dewatering Pumps Market Strategic Shifts & Innovations
Digital monitoring convergence with electromechanical hardware is rewiring competitive positioning across the dewatering pump value chain. Three interconnected developments are compressing traditional equipment-margin structures while opening service-based revenue pools.
Permanent magnet synchronous motor technology is fragmenting efficiency benchmarks across the submersible pump category. These motors achieve higher power density with reduced thermal losses. European construction contractors are specifying PM-equipped units for deep-shaft dewatering where energy recovery justifies capital premiums. The technology is fragmenting supplier tiers between premium PM-integrated OEMs and conventional induction motor assemblers.
EU F-Gas Regulation restrictions on hydrofluorocarbon-based motor cooling are elevating air-cooled and liquid-cooled alternative designs. Manufacturers must reengineer thermal management architectures to maintain IP68 encapsulation ratings. German and Austrian mining equipment purchasers are prioritizing F-Gas-compliant configurations to preempt operational permitting delays in Alpine tunneling projects.
Lifecycle cost modeling is displacing upfront capital evaluation in municipal procurement cycles. Brazilian and Nigerian water authorities are embedding 10-year total cost of ownership calculations into tender specifications. Equipment vendors with predictive maintenance platforms and regional parts distribution are capturing preference premiums over low-bid alternatives in São Paulo and Lagos infrastructure awards.
Dewatering Pumps Market Segmentation
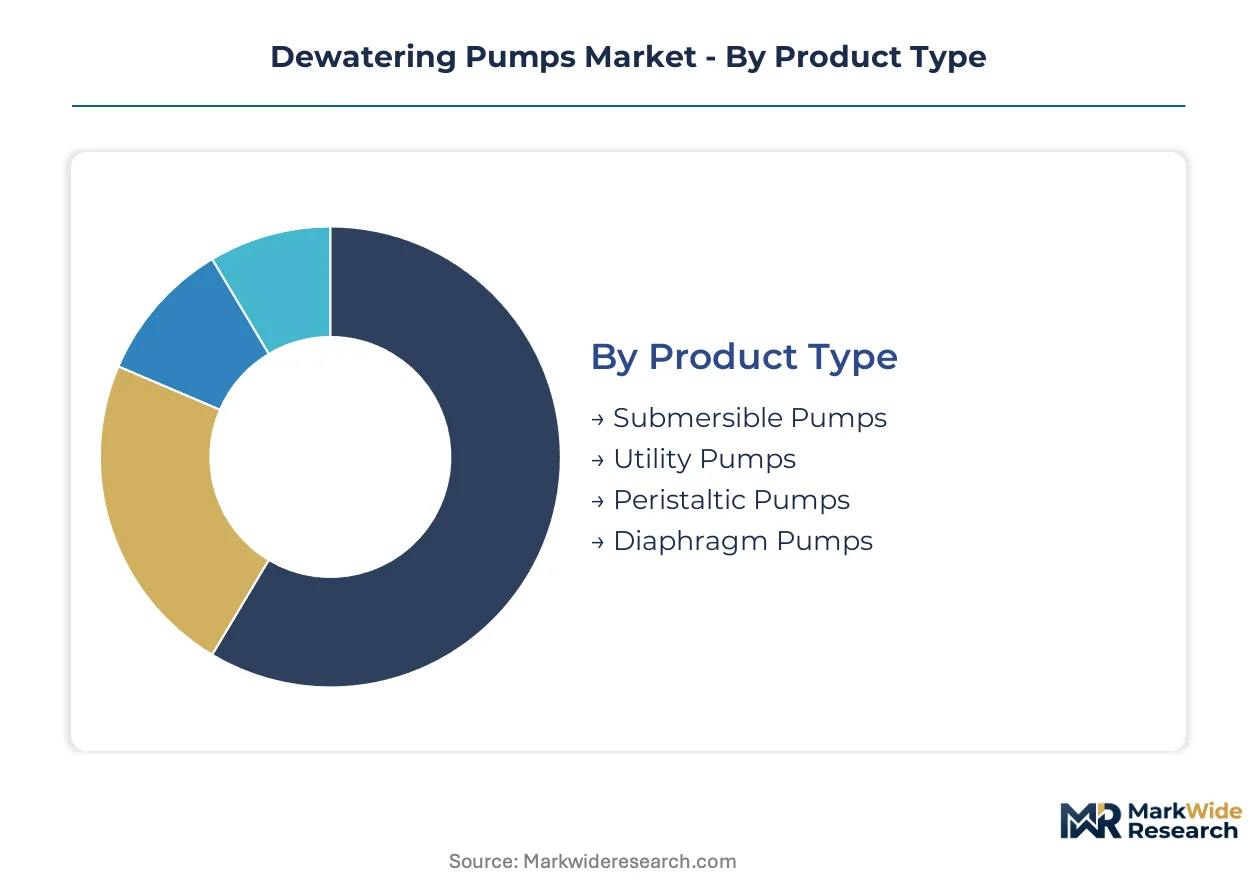
Dewatering pump procurement diverges sharply across application contexts, with motor technology and installation permanence driving margin fragmentation. Understanding segment-level profitability requires mapping efficiency mandates against operational duty cycles in specific geographies.
Product Type:
Margin pools concentrate in flood-tolerant motor encapsulation technologies that reduce suction lift constraints and extend mean-time-between-failures in abrasive environments.
- Submersible Pumps:These units integrate sealed motor housings that operate directly within pumped media, eliminating suction lift limitations entirely. Chilean copper pit operators specify abrasion-resistant variants for deep-shaft dewatering where thermal management and seal integrity determine lifecycle economics. EU F-Gas Regulation compliance is elevating engineering overhead for IP68-rated thermal architectures.
- Utility Pumps:Portable surface-mounted designs serve intermittent dewatering needs across residential and light commercial construction. Indonesian municipal contractors deploy these for temporary stormwater management during Jakarta infrastructure upgrades where capital constraints limit submersible procurement.
- Peristaltic Pumps:Positive displacement mechanisms handle high-viscosity slurries without seal contact.
- Diaphragm Pumps:Air-operated configurations excel in explosive atmosphere zones where electrical ignition risks are prohibitive.
The dominant share belongs to Submersible Pumps, while Utility Pumps is closing the gap fastest through rental fleet expansion in emerging market construction corridors.
End User:
Customer procurement sophistication varies dramatically, with lifecycle cost modeling penetration deepest where regulatory discharge standards are most stringent.
- Construction:Project-based demand cycles dominate this segment, with European urban emissions zones and CE-marked noise ordinances compressing diesel equipment economics. Contractors in Alpine tunneling corridors are specifying electric submersible fleets to preempt permitting delays.
- Municipalities:This end user applies 10-year total cost of ownership calculations in procurement tenders, embedding predictive maintenance requirements into contract specifications. Brazilian and Nigerian water authorities in São Paulo and Lagos corridors favor vendors with regional parts distribution networks.
- Mining:Abrasive slurry environments in Chilean copper pits and Appalachian coal basins elevate seal degradation concerns and maintenance labor scarcity.
- Agriculture:India's drought-prone belts are displacing diesel sets through government-subsidized solar dewatering schemes.
Municipalities commands the highest margin pool due to lifecycle procurement frameworks, though Agriculture is expanding most quickly through solar-hybrid electrification programs.
Solution:
Technology displacement patterns reflect divergent energy access and emissions enforcement across operating geographies.
- Electric Powered:Grid-connected and battery-backed configurations achieve highest efficiency in continuous-duty applications. European construction sites prioritize these for urban emissions zone compliance, while Indian agricultural procurement tenders increasingly specify BIS-certified motor performance standards.
- Solar Powered:Photovoltaic-driven systems eliminate fuel logistics in remote deployment contexts. Government-subsidized schemes across India's drought-prone agricultural belts are accelerating technology adoption where grid extension is uneconomical.
- Diesel Powered:Combustion engines retain relevance in off-grid mining and emergency response scenarios.
- Hybrid Systems:Dual-mode architectures combine solar generation with diesel backup for duty-cycle flexibility.
Electric Powered holds the dominant position, while Solar Powered is gaining share fastest through agricultural subsidy programs in water-stressed regions.
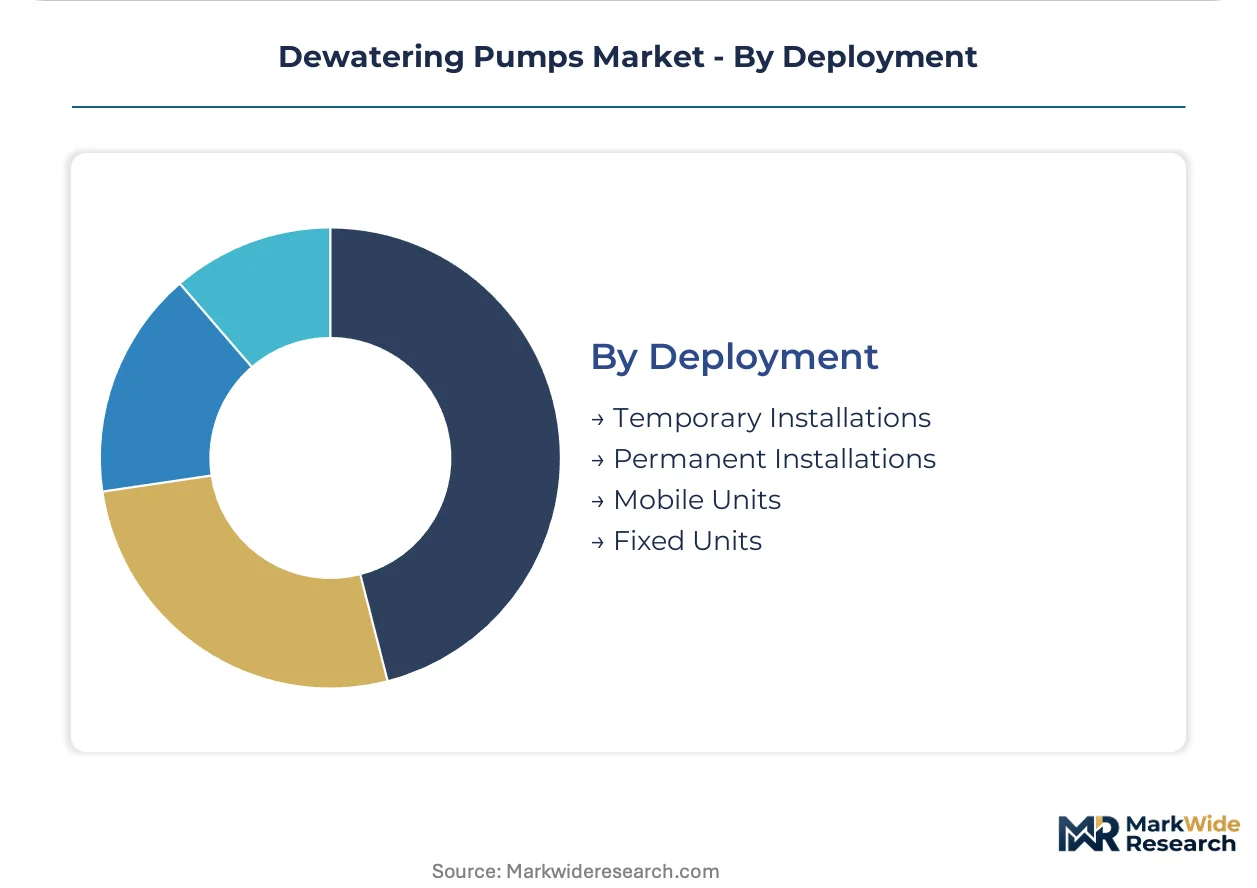
Deployment:
Installation permanence determines service contract attach rates and recurring revenue potential for OEM aftermarket strategies.
- Permanent Installations:Fixed infrastructure in municipal lift stations and treatment facilities enables predictive maintenance platform integration. Spanish and Italian water authorities under EU Green Deal circular economy mandates prioritize these configurations for water reuse target compliance.
- Mobile Units:Trailer-mounted and skid-based systems serve construction and emergency response applications requiring rapid repositioning. Rental fleet operators across North American mining corridors are expanding these assets to address technician scarcity through centralized maintenance depots.
- Temporary Installations:Project-specific deployments dominate construction dewatering cycles.
- Fixed Units:Stationary non-embedded configurations serve semi-permanent industrial sump applications.
Permanent Installations captures the dominant share, while Mobile Units is climbing the fastest through rental-over-purchase shifts in skilled labor-constrained markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European contractors prioritize electric submersible fleets for emissions compliance, while Indian agricultural procurement concentrates on solar-hybrid displacement of diesel sets. Mining corridors in Chile and Indonesia drive demand for abrasion-resistant configurations.
United States
Appalachian coal basins and municipal lift stations across the Great Lakes states anchor equipment demand. EPA effluent guidelines tighten discharge standards, forcing asset owners toward higher-efficiency pump configurations with advanced monitoring capabilities. Xylem Inc. leverages digital monitoring platforms to anchor long-term service contracts in these mining corridors.
Germany
Alpine tunneling projects and urban construction sites in Bavaria and North Rhine-Westphalia specify electric-powered units. EU F-Gas Regulation restrictions on hydrofluorocarbon-based motor cooling elevate air-cooled and liquid-cooled alternative designs. German mining equipment purchasers prioritize F-Gas-compliant configurations to preempt operational permitting delays.
India
Drought-prone agricultural belts in Maharashtra and Gujarat displace diesel-powered irrigation sets through government-subsidized solar dewatering schemes. BIS efficiency labeling mandates advantage certified OEMs over unlabeled imports in agricultural procurement tenders. Grid extension remains uneconomical in remote deployment contexts, accelerating photovoltaic-driven adoption.
Chile
Copper pit operations in the Atacama Desert and central mining districts specify abrasion-resistant submersible designs. Abrasive slurry environments compress mean-time-between-failures, elevating total cost of ownership calculations. Sulzer Ltd. specializes in configurations that dominate this deep-shaft dewatering segment.
Indonesia
Municipal wastewater modernization programs across Jakarta and Surabaya corridors open procurement windows for electric submersible fleets. Infrastructure upgrades accelerate procurement of electric-powered submersible units. Capital constraints in temporary stormwater management applications sustain parallel demand for portable utility pump configurations.
Dewatering Pumps Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding predictive maintenance platform integration and long-term service contract attach rates. The middle tier fragments across regional fabricators with distributor-dependent geographic coverage. Three archetypes dominate: full-system integrators with digital service unbundling, abrasion-resistant specialists for mining applications, and rental fleet operators addressing technician scarcity. Competitive moves concentrate on M&A for regional distribution networks and backward integration into permanent magnet motor supply.
Within the full-system integrator tier, Xylem Inc. and Grundfos Holding A/S exemplify positioning around digital monitoring convergence and lifecycle cost optimization. Sulzer Ltd. occupies a distinct specialization niche for abrasive environment configurations. Among European-based fabricators, KSB SE & Co. KGaA and Ebara Corporation represent archetypes of regional production scale and cross-border certification management. The Gorman-Rupp Company anchors distributor-network-dependent positioning in municipal lift station applications. These named entities illustrate how competitive advantage fragments across technology integration, application specialization, and channel control vectors rather than concentrating in any single capability domain.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| Ebara Corporation |
| Flowserve Corporation |
| The Gorman-Rupp Company |
| Sulzer Ltd. |
| Grundfos Holding A/S |
| Atlas Copco AB |
| Wacker Neuson SE |
| Xylem Inc. |
| Others |
Cost & Logistics Intelligence
Scale economies in permanent magnet synchronous motor manufacturing concentrate production cost advantages among integrated OEMs, compressing price floors for conventional induction motor assemblers while elevating procurement premiums for EU F-Gas-compliant thermal architectures. This concentration dynamics reshapes competitive positioning across electric submersible configurations where motor efficiency certification determines tender eligibility in Indian agricultural procurement and European urban construction corridors.
Pricing Analysis
Long-term service contracts with predictive maintenance bundling dominate municipal procurement cycles, displacing spot-market transactions in Brazilian and Nigerian water authority tenders. Price differentiation rests on BIS efficiency labeling in India and CE-marked noise compliance in Europe, with certification tiers separating premium OEMs from unlabeled imports. Cost compression in standard-efficiency induction motor segments intensifies due to copper price volatility and Chinese rare earth processing concentration. Municipal end users exhibit lowest price sensitivity through lifecycle cost modeling, while Indonesian temporary stormwater contractors prioritize capital-constrained utility pump configurations.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for motor winding materials and IP68-rated seal components sourced from Chinese and South Korean manufacturing hubs. Permanent magnet supply concentrates in Chinese processing facilities, while copper cathode draws from Chilean and Indonesian mining corridors. Single-source vulnerability in rare earth element refining creates tariff exposure for OEMs with centralized assembly strategies. Distribution runs through authorized distributor networks in North American Great Lakes states and direct municipal contracting in São Paulo and Lagos infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dewatering pumps market sits in early-cycle expansion as solar-hybrid electrification penetrates India's drought-prone agricultural belts and EU Green Deal water reuse mandates elevate permanent installation demand across Spanish and Italian treatment facilities.
For Market Incumbents: Consolidate predictive maintenance platform integration with regional parts distribution networks to defend municipal service contract attach rates against emerging digital-native entrants. Prioritize backward integration into permanent magnet motor supply to preempt copper and rare earth price volatility exposure. Anchor long-term offtake agreements with Brazilian and Indonesian water authorities before efficiency certification mandates fully phase in. For New Entrants and Emerging Players: BIS efficiency certification fast-track through Indian testing laboratories opens agricultural procurement tender access currently blocked to unlabeled imports. White-space concentration in solar-powered submersible configurations for Maharashtra and Gujarat drought belts offers lowest competitive density. Target mobile rental fleet positioning across North American mining corridors where technician scarcity compresses utilization rates for incumbent owned-equipment models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-system integrators with unbundled digital service revenue streams over pure hardware assemblers. Five-to-ten year viability concentrates in OEMs with predictive maintenance platform deployment and F-Gas-compliant thermal architecture portfolios. Monitor Indian solar subsidy program expansion rates as inflection indicator for diesel displacement velocity in agricultural segments.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Recurring revenue unbundling from hardware sales anchors municipal contract retention in São Paulo and Lagos corridors. |
| Permanent Magnet Motor Backward Integration | Upstream control over rare earth supply chains mitigates Chinese processing concentration risk for EU F-Gas-compliant product lines. |
| Regional Certification Fast-Track Investment | BIS and CE marking pathway acceleration unlocks tender eligibility in Indian agricultural and European urban emissions zones. |
| Solar-Hybrid Product Line Expansion | Photovoltaic-driven configurations capture subsidy tailwinds across Maharashtra and Gujarat drought-prone belts displacing diesel sets. |
| Rental Fleet Asset Buildout | Mobile unit positioning addresses North American mining technician scarcity through centralized maintenance depot economics. |
Research Approach
Desk research of customs trade databases, EPA effluent guideline filings, and EU F-Gas regulatory precedents preceded structured interviews with municipal water authority procurement directors, mining maintenance supervisors, and agricultural cooperative equipment managers. Primary fieldwork across Appalachian coal basins, Chilean Atacama copper pits, and Indian Maharashtra irrigation districts combined with secondary validation through OEM technical documentation and BIS certification registries. Bottom-up equipment shipment analysis triangulated against top-down infrastructure spending projections.
Variance decomposition across product type, end user, power source, and deployment permanence dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level adoption curves weighted by regulatory enforcement timelines and subsidy program budgets. Industry-specific forecast inputs incorporated copper price volatility indices and solar panel cost learning curves for hybrid system penetration modeling.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and Indian PLI scheme continuity assumptions; material deviation in subsidy allocation or emissions enforcement stringency would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Latin America Pumps Market