
 Dry Vacuum Pumps Market | 2026-2036
Dry Vacuum Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Vacuum Pumps Market Analysis
China is fragmenting dry vacuum pump supply chains as domestic foundries expand 300mm wafer capacity. Atlas Copco leverages its compressor heritage to cross-sell integrated vacuum solutions into semiconductor fabs. Pfeiffer Vacuum anchors European demand through its turbopump-dry pump hybrid architectures. Edwards Vacuum dominates Asia-Pacific service networks with localized refurbishment centers.
Dry vacuum pumps are positive-displacement or momentum-transfer devices that operate without sealing fluid, achieving ultimate pressures below 0.01 mbar through claw, screw, or scroll mechanisms; they prevent process contamination in sensitive manufacturing environments. Scroll pumps lead the product type category due to their oil-free compression and minimal particulate generation during semiconductor wafer processing. Dry lubrication technology captures expanding margin pools as fabs prioritize hydrocarbon-free pump architectures to eliminate backstreaming risks during atomic layer deposition cycles.
EPA emissions guidelines in the United States restrict fluorinated greenhouse gas releases from wet pump exhaust streams, accelerating dry pump retrofits in chemical processing plants. The EU F-Gas Regulation and REACH chemical restrictions collectively mandate oil-free vacuum architectures for pharmaceutical lyophilization and semiconductor etch applications. China's GB standards for industrial emissions and MIIT energy-efficiency directives push domestic manufacturers toward high-performance dry pump platforms. Stakeholders must weigh captive service network investments against third-party refurbishment partnerships as equipment utilization rates climb across Asian fabrication corridors.
Market Dynamics
Semiconductor fabs are consolidating vacuum pump procurement around oil-free architectures as atomic layer deposition and extreme ultraviolet lithography processes impose sub-ppb contamination thresholds that legacy wet pumps cannot satisfy.
Growth Catalysts
- EU F-Gas Regulation phase-out:The mandated elimination of fluorinated refrigerants in wet pump exhaust systems redirects capital expenditure toward dry pump retrofits across pharmaceutical lyophilization and chemical processing facilities in Germany, France, and the Netherlands.
- 300mm wafer capacity expansion:Taiwan and South Korean foundries are scaling dry pump procurement to support 3nm and 2nm node production, with each advanced fab requiring 500-800 units for etch, deposition, and lithography modules.
- Claw mechanism refinement:Improved rotor coatings and variable pitch screw designs now deliver ultimate pressures below 0.001 mbar without lubrication, opening dry pump applicability to previously excluded high-vacuum process steps.
Market Restraints
- Specialized ceramic and coating input costs:Rotor manufacturing depends on silicon carbide and diamond-like carbon deposition chambers concentrated in Japanese and German supply bases, creating margin pressure when capacity tightens.
- Technical ceiling at ultra-high vacuum:Dry pumps cannot displace cryogenic or turbomolecular pumps below 10^-6 mbar, limiting addressable market in electron microscopy and certain space simulation applications.
- Service network concentration risk:Refurbishment expertise and spare rotor inventories cluster in East Asian logistics hubs, extending mean time to repair for European and North American fabs during supply disruptions.
Strategic Opportunities
- India's semiconductor subsidy pipeline:The country's PLI scheme and designated fabrication zones in Gujarat and Tamil Nadu create first-mover advantage for dry pump vendors establishing local assembly and service infrastructure.
- Battery dry room applications:Lithium-ion cell manufacturing requires dew points below -40°C in electrode drying and electrolyte filling bays, a specification that oil-free scroll and screw pumps now satisfy at scale.
- Predictive maintenance convergence:Integration of vibration sensors and machine learning diagnostics with dry pump controllers enables unplanned downtime reduction, shifting revenue models toward performance-guaranteed service contracts.
Industry Challenges
- Vacuum engineering talent scarcity:The specialized knowledge required for rotor dynamics, gas load calculations, and process-specific pump sizing concentrates in aging workforces at Japanese and European OEMs, constraining expansion of independent service providers.
- Legacy wet pump infrastructure lock-in:Chemical plants and pharmaceutical facilities face 18-36 month validation cycles when replacing oil-sealed systems, delaying dry pump adoption despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Vacuum Pumps Market |
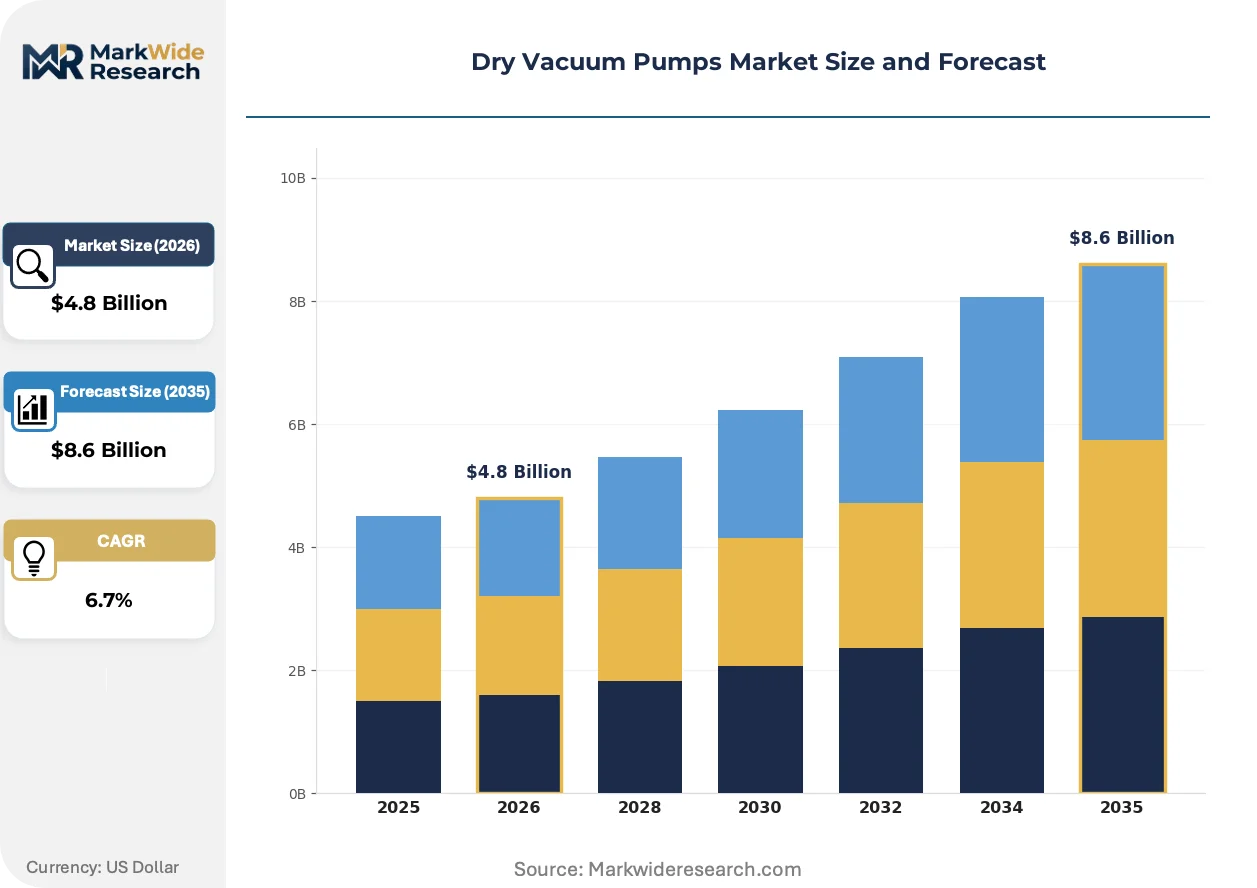
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Vane, Scroll, Piston, Diaphragm Application: Semiconductor, Pharmaceutical, Chemical Processing, Food Packaging End User: Manufacturing, Research Laboratories, Electronics, Healthcare Technology: Dry Lubrication, Oil-Free, Low-Temperature, High-Performance |
| Companies Covered | Atlas Copco, Pfeiffer Vacuum, Edwards Vacuum, Busch Vacuum Solutions, Ebara Corporation, ULVAC, Gardner Denver, Agilent Technologies, Leybold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Vacuum Pumps Market Emerging Trajectories
Digital instrumentation is embedding intelligence at the pump level, transforming maintenance economics and enabling fab-wide vacuum system optimization through real-time pressure telemetry and predictive algorithms.
Smart sensor arrays are digitizing condition monitoring across screw and claw pump architectures. Leading memory foundries in South Korea now deploy edge-computing modules on every dry pump, transmitting bearing temperature, motor current signature, and exhaust pressure data to central manufacturing execution systems. This connectivity is digitizing failure prediction, compressing unplanned downtime from days to hours and reducing emergency spare parts inventory by enabling condition-based rather than calendar-based replacement.
The EU F-Gas Regulation and REACH chemical restrictions are tightening permissible emissions from vacuum pump exhaust streams. Pharmaceutical manufacturers operating lyophilization equipment must now demonstrate fluorinated compound capture or elimination, accelerating adoption of fully dry, refrigerant-free architectures. Semiconductor etch applications in Ireland and the Netherlands face parallel scrutiny, with national environmental agencies requiring continuous emissions monitoring data as a condition of operating permits.
Consolidated procurement through equipment OEMs is displacing direct pump vendor relationships. Applied Materials, Lam Research, and Tokyo Electron now specify and source dry pumps as integrated subsystems rather than standalone capital equipment, compressing vendor count and shifting negotiation leverage toward volume-scale foundry operators. This pattern concentrates most visibly in Taiwan, where the three dominant pure-play foundries account for the majority of annual dry pump procurement volume.
Dry Vacuum Pumps Market Segmentation
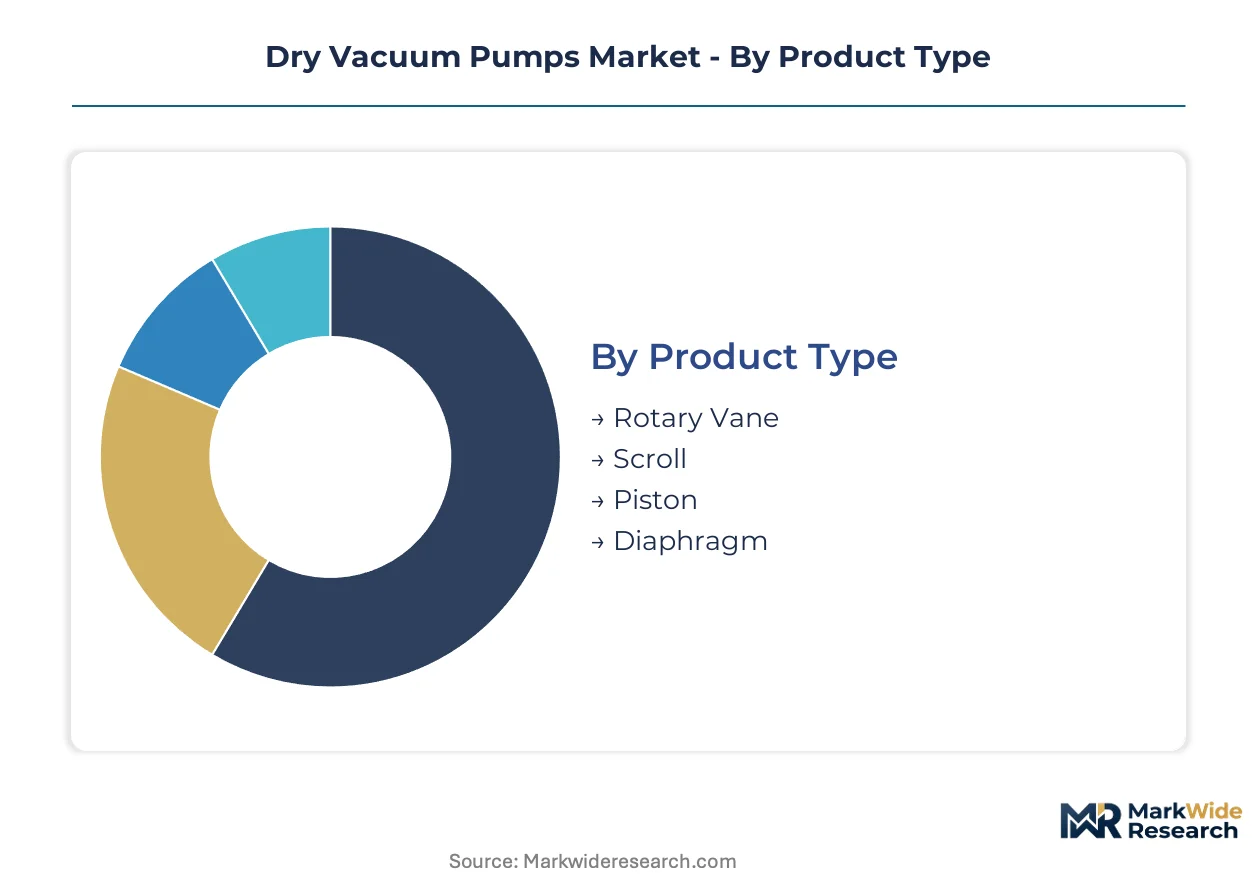
Dry vacuum pump procurement patterns diverge sharply across technical specifications and end-use environments. Semiconductor fabs prioritize contamination-free architectures while chemical processors balance emission compliance against capital constraints. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where commoditization pressures dominate.
Product Type:
Replacement cycles stretch from eighteen months in high-duty semiconductor etch applications to seven years in light industrial packaging, creating divergent aftermarket revenue profiles across pump architectures.
- Scroll:Orbiting spiral scrolls compress gas through crescent-shaped pockets without contacting surfaces, eliminating particulate generation. Taiwanese foundries specify scroll pumps for atomic layer deposition modules where sub-ppb hydrocarbon limits apply. The EU F-Gas Regulation accelerates scroll retrofits in pharmaceutical freeze-drying equipment across Germany and the Netherlands.
- Rotary Vane:Eccentric rotors with sliding vanes deliver high pumping speeds at moderate ultimate pressures. South Korean memory fabs deploy rotary vane pumps in bulk etch processes where cost-per-unit throughput outweighs contamination sensitivity. Carbon vane wear rates in aggressive fluorocarbon chemistries shorten service intervals below twelve months.
- Piston:Reciprocating piston mechanisms handle high gas loads and particulate contamination in harsh chemical processing environments.
- Diaphragm:Flexible membrane displacement suits laboratory and analytical instrument applications requiring complete oil isolation.
Scroll pumps anchor the volume base while rotary vane configurations gain share at the steepest rate in cost-sensitive process steps.
Application:
Process contamination thresholds stratify demand tiers, with atomic-scale manufacturing imposing specifications that exclude half the available pump technologies.
- Semiconductor:Etch, deposition, and lithography modules require ultimate pressures below 0.001 mbar with zero backstreaming risk. Taiwan and South Korean foundries consume the dominant procurement volume for 3nm and 2nm node production. Each advanced fab installation demands 500-800 dry pump units across process modules.
- Pharmaceutical:Lyophilization and freeze-drying applications mandate oil-free architectures under EU F-Gas Regulation and REACH chemical restrictions. Irish and Dutch facilities face continuous emissions monitoring requirements as permit conditions. Validation cycles for new pump installations extend 18-36 months, delaying retrofit timelines.
- Chemical Processing:Corrosive gas handling and solvent recovery operations prioritize chemical-resistant coatings and high gas throughput capacity.
- Food Packaging:Modified atmosphere packaging lines utilize dry pumps for vacuum sealing at less stringent ultimate pressure specifications.
Semiconductor applications command the highest unit margins while pharmaceutical retrofits expand most quickly under regulatory compulsion.
End User:
Capital deployment patterns separate high-volume contract manufacturers from specification-driven research facilities with fragmented procurement authority.
- Manufacturing:High-volume production lines in electronics and automotive battery dry rooms specify oil-free scroll and screw pumps for dew point control below -40°C. Gujarat and Tamil Nadu fabrication zones under India's PLI scheme create concentrated demand clusters for localized service infrastructure.
- Electronics:Contract assembly and testing operations prioritize reliability metrics and rapid spare parts availability over ultimate performance specifications.
- Research Laboratories:Academic and government facilities balance capital constraints against specialized vacuum requirements for materials science and physics applications.
- Healthcare:Medical device sterilization and diagnostic equipment manufacturers face FDA and EPA emissions guidelines restricting fluorinated compound releases.
Manufacturing end users generate the dominant procurement volume while electronics sector demand climbs fastest on battery dry room expansion.
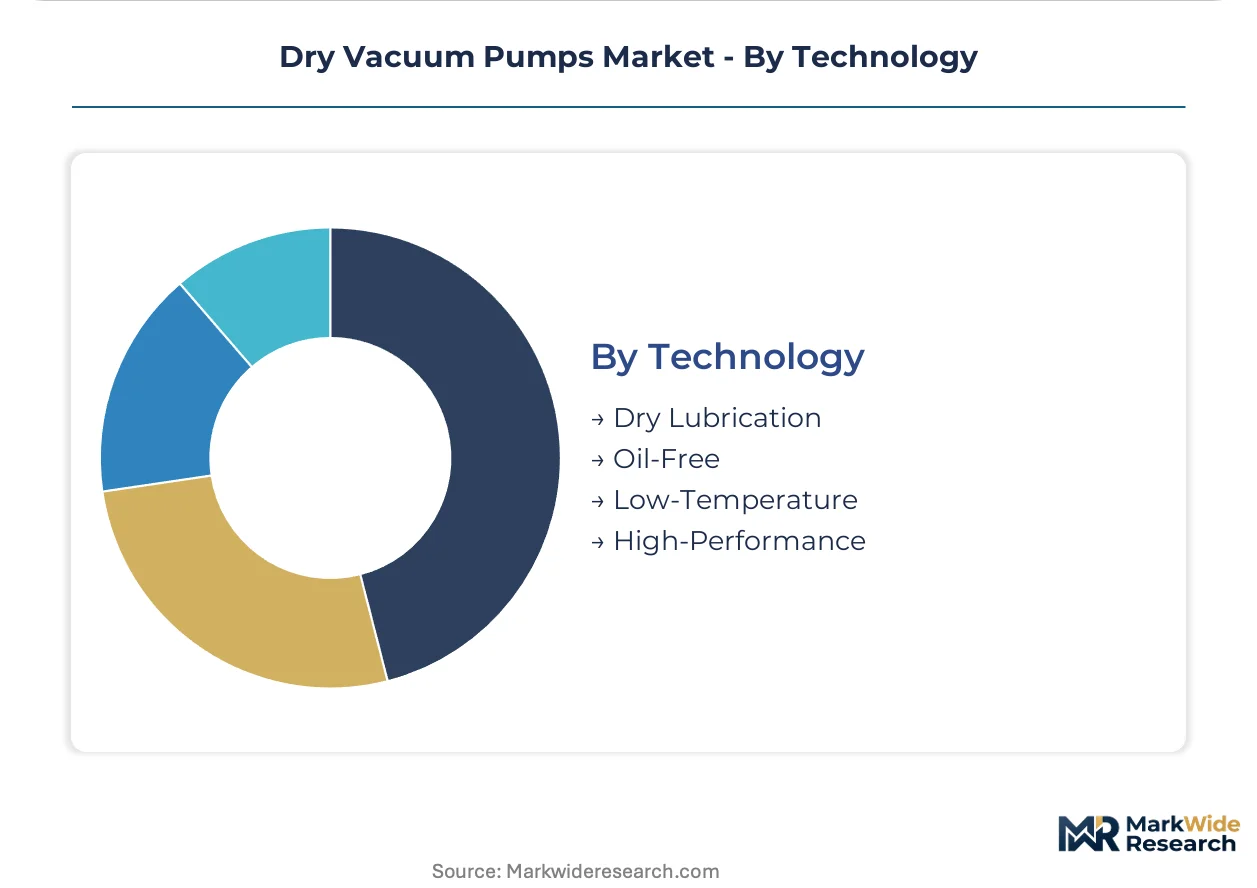
Technology:
Performance tiering separates premium architectures with predictive maintenance integration from baseline specifications competing on initial capital cost.
- Oil-Free:Complete elimination of hydrocarbon sealing fluids satisfies semiconductor contamination thresholds and pharmaceutical regulatory mandates. South Korean memory foundries deploy edge-computing modules on every oil-free pump for predictive maintenance. Real-time telemetry reduces unplanned downtime from days to hours.
- Dry Lubrication:Solid lubricant coatings on rotors and vanes extend service intervals in moderate vacuum applications without full oil elimination.
- High-Performance:Variable pitch screw designs and advanced ceramic coatings achieve ultimate pressures below 0.001 mbar for previously excluded high-vacuum process steps.
- Low-Temperature:Specialized cooling architectures handle condensable vapor loads in chemical processing and solvent recovery applications.
Oil-free technology anchors current volume while high-performance variants capture expanding share at the steepest rate as process requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German suppliers dominate rotor manufacturing, concentrating silicon carbide and diamond-like carbon coating capacity in Nagano and Dresden industrial corridors. Taiwan and South Korean fabs absorb the dominant procurement volume for advanced node production.
Taiwan
TSMC and United Microelectronics Corporation are expanding 3nm and 2nm fabrication capacity at Tainan and Hsinchu Science Parks. The National Development Council subsidizes domestic equipment procurement under the A+ Industrial Innovation Program. Each new advanced fab installation requires 500-800 dry pump units across etch, deposition, and lithography modules.
South Korea
Samsung Electronics and SK Hynix are scaling memory foundry output for high-bandwidth DRAM and 3D NAND stacks. The Ministry of Trade, Industry and Energy (METI) channels support through the K-Semiconductor Belt initiative. Pyeongtaek and Yongin clusters now deploy edge-computing modules on every dry pump for predictive maintenance telemetry.
United States
Intel and Micron Technology are reshoring advanced logic and memory fabrication to Arizona and New York. EPA emissions guidelines restrict fluorinated greenhouse gas releases from wet pump exhaust streams, accelerating dry pump retrofits. The CHIPS and Science Act directs $52 billion toward domestic semiconductor manufacturing infrastructure.
Germany
Infineon Technologies and Bosch are expanding automotive-grade chip foundry capacity in Dresden and Reutlingen. The EU F-Gas Regulation mandates elimination of fluorinated refrigerants in wet pump exhaust systems, redirecting capital toward oil-free alternatives. Bavarian chemical processors face parallel REACH chemical restrictions on pharmaceutical lyophilization equipment.
China
SMIC and Hua Hong Semiconductor are ramping 300mm wafer capacity in Shanghai and Wuxi. MIIT energy-efficiency directives and GB standards for industrial emissions push domestic manufacturers toward high-performance dry pump platforms. Yangtze River Delta fabrication zones concentrate the majority of indigenous dry pump demand.
Dry Vacuum Pumps Market Vendor Landscape
Integrated industrial conglomerates and specialized vacuum technology firms split the market between volume-scale semiconductor fab contracts and precision applications requiring custom engineering. The vendor base concentrates around three strategic archetypes: diversified compressor heritage players leveraging cross-selling synergies, dedicated vacuum OEMs with captive coating and rotor manufacturing, and regional Asian fabricators serving domestic foundry procurement. Competitive moves center on localized refurbishment network expansion and predictive maintenance service contract bundling.
Within the diversified industrial tier, Atlas Copco and Gardner Denver occupy positions anchored by compressor product heritage and integrated air system portfolios. Pfeiffer Vacuum exemplifies the dedicated vacuum archetype with European turbopump-dry pump hybrid positioning. Edwards Vacuum represents the Asia-Pacific service infrastructure model through localized refurbishment center deployment.
| Leading Market Players |
|---|
| Atlas Copco |
| Pfeiffer Vacuum |
| Edwards Vacuum |
| Busch Vacuum Solutions |
| Ebara Corporation |
| ULVAC |
| Gardner Denver |
| Agilent Technologies |
| Leybold |
| Others |
Supply Flow & Price Mechanics
The Kaohsiung-Taoyuan freight corridor carries silicon carbide rotors and diamond-like carbon coatings from Japanese suppliers to Taiwanese foundries, with logistics costs compressing margins on standard-grade pumps while enabling premium pricing for contamination-certified architectures. This corridor's cost dynamics concentrate supply power among Nagano and Dresden coating specialists, forcing buyers into long-term offtake contracts or accepting extended lead times for spot procurement.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across pharmaceutical and semiconductor applications, separating oil-free certified architectures from dry-lubrication alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects contamination thresholds, with atomic layer deposition modules commanding the highest tier due to sub-ppb hydrocarbon limits. Cost compression in standard-grade rotary vane configurations is intensifying because South Korean memory fabs prioritize throughput economics over ultimate vacuum performance. Chemical processors exhibit the highest price sensitivity, while Taiwanese pure-play foundries accept premium positioning for zero-backstreaming guarantees.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now anchor supplier-finance arrangements for Japanese and German rotor manufacturers serving Asian fab clusters. Geographic supply concentration centers on Japan for silicon carbide substrates, Germany for diamond-like carbon deposition chambers, and Taiwan for final pump assembly and refurbishment. Raw material dependencies draw from rare earth magnet suppliers in China, precision bearing manufacturers in Sweden, and ceramic coating specialists in Japan. Single-source vulnerability around Nagano-based silicon carbide capacity creates structural risk during capacity tightens. Distribution runs through equipment OEMs including Applied Materials and Lam Research, which now specify pumps as integrated subsystems rather than standalone capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry vacuum pumps market sits at an inflection where EU F-Gas Regulation mandates are eliminating wet pump alternatives, creating forced-upgrade cycles across pharmaceutical lyophilization and semiconductor etch applications. This regulatory disruption compounds with 3nm and 2nm node expansion to generate sustained demand visibility.
For Market Incumbents: Harden service network moats by expanding localized refurbishment capacity in Gujarat and Tamil Nadu ahead of India's PLI scheme fabrication zone ramp. Deepen backward integration into silicon carbide rotor manufacturing to reduce exposure to Nagano supply concentration. Lock in multi-year predictive maintenance contracts with South Korean memory foundries before edge-computing telemetry becomes commoditized. For New Entrants and Emerging Players: Establish a beachhead in battery dry room applications for lithium-ion electrode drying, where dew point specifications below -40°C now match oil-free scroll pump capabilities. Target pharmaceutical retrofit markets in Ireland and the Netherlands where 18-36 month validation cycles create incumbent lock-in elsewhere. Pursue joint development agreements with Indian domestic foundries under MIIT energy-efficiency directives as a go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming vacuum divisions lacking semiconductor fab relationships. Long-term viability hinges on predictive maintenance software integration and captive coating capacity. Monitor edge-computing module deployment rates at South Korean foundries as the signal indicating when telemetry-enabled service contracts become table stakes rather than differentiators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Rotor Manufacturing | Captive supply of critical components reduces exposure to Nagano capacity constraints and margin pressure. |
| Predictive Maintenance Service Contract Bundling | Edge-computing telemetry at Samsung and SK Hynix facilities shifts revenue from equipment sales to performance guarantees. |
| Localized Refurbishment Center Deployment | Gujarat and Tamil Nadu infrastructure captures India's PLI scheme semiconductor subsidy pipeline before competitors establish presence. |
| Pharmaceutical Lyophilization Retrofit Program | EU F-Gas Regulation compliance deadlines in Germany and the Netherlands create concentrated demand for oil-free architectures. |
| Battery Dry Room Application Development | Lithium-ion cell manufacturing specifications for electrode drying match oil-free scroll pump performance envelopes. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC equipment OEM filings, and EU regulatory enforcement records. Primary interviews engaged fab engineering directors, vacuum pump procurement leads at memory foundries, pharmaceutical lyophilization equipment managers, and aftermarket service heads at refurbishment centers. Secondary validation drew from ECHA REACH restriction updates, EPA emissions guideline revisions, and MIIT energy-efficiency directive filings. Bottom-up unit demand estimates from individual fab capacity announcements triangulate against top-down market sizing from equipment OEM revenue disclosures.
Forecast inputs incorporate semiconductor node transition timelines, battery dry room capacity buildouts, and pharmaceutical validation cycle durations across the projection horizon. Segmentation dimensions modeled include pump mechanism type, ultimate pressure tier, contamination specification level, end-use application, and regional regulatory cluster. CAGRs derive from weighted capacity expansion schedules and replacement cycle compression in high-duty etch applications. Industry-specific inputs include EU F-Gas Regulation phase-out deadlines and India's PLI scheme disbursement triggers.
Sensitivities concentrate around semiconductor capital expenditure volatility, rare earth magnet export restrictions, and pharmaceutical validation timeline extensions. Forecasts reflect assumptions about node migration speeds and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Brine Tanks Market