
 Elevator Motors Market | 2026-2036
Elevator Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Elevator Motors Market Foresight
The EU F-Gas Regulation is shifting procurement criteria across European building portfolios toward lower lifecycle energy consumption. Mitsubishi Electric Corporation leverages its in-house permanent magnet motor production to capture premium retrofit contracts. KONE Corporation anchors its competitive stance through digital predictive maintenance platforms bundled with synchronous motor upgrades. Otis Elevator Company differentiates via modular gearless designs that reduce shaft space requirements in high-density Asian developments.
Elevator motors convert electrical energy into mechanical torque for vertical transportation systems, typically operating at speeds from 0.5 to 10 meters per second depending on building height and load capacity. Gearless synchronous motors now dominate super-tall installations because they eliminate transmission losses and reduce acoustic emissions in occupied shafts. Induction motor configurations retain cost advantages in mid-rise residential applications where speed requirements remain modest. Variable Frequency Drive control systems command the widest installed base, though digital control architectures are displacing legacy mechanical governors in modernization programs across aging building stocks.
The US Department of Energy enforces minimum efficiency standards for commercial elevator systems under federal appliance regulations, while China's GB standards mandate energy consumption labeling for new installations. Japan's METI administers Top Runner programs that continuously ratchet motor efficiency benchmarks for building equipment. Stakeholders must track evolving carbon disclosure requirements from ESG rating agencies that now capture embodied emissions in vertical transportation infrastructure.
Market Dynamics
Gearless permanent magnet synchronous machines are compressing demand for legacy induction configurations as super-tall construction mandates shaft-space efficiency and acoustic compliance. State-mandated urban renewal across China and EU F-Gas Regulation tightening are accelerating replacement cycles in aging commercial towers.
Growth Catalysts
- EU F-Gas Regulation:Building portfolio managers in Germany and France must now factor lifecycle energy consumption into procurement criteria, elevating premium synchronous motor specifications.
- Urban renewal mandates:China's state-directed programs are replacing aging traction systems in thousands of commercial towers across Beijing and Shanghai.
- High-rise residential absorption:Mumbai and São Paulo developers specify gearless permanent magnet machines to meet speed and noise requirements in dense vertical housing.
Market Restraints
- Rare earth supply concentration:Permanent magnet motor production depends on neodymium processing concentrated in China, creating input vulnerability for European and Japanese manufacturers.
- Copper price volatility:Induction motor windings and power electronics remain exposed to commodity swings that compress margins in mid-rise residential segments.
- Shaft retrofit complexity:Legacy buildings with constrained machine room footprints cannot accommodate gearless synchronous hardware without structural modification.
Strategic Opportunities
- Digital predictive maintenance convergence:Sensor-embedded motors paired with cloud analytics platforms create recurring revenue streams from uptime guarantees.
- India's Smart Cities Mission:Metro rail and transit-oriented development projects in Delhi and Bengaluru specify regenerative drive systems with energy recovery.
- Japan METI Top Runner programs:Continuous efficiency benchmark ratcheting positions premium motor suppliers for government building retrofits.
Industry Challenges
- Electromechanical technician scarcity:Variable frequency drive commissioning and permanent magnet rotor balancing require skills concentrated in aging workforces across North America and Europe.
- GB standard certification timelines:China's energy consumption labeling mandates for new installations extend product validation cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevator Motors Market |
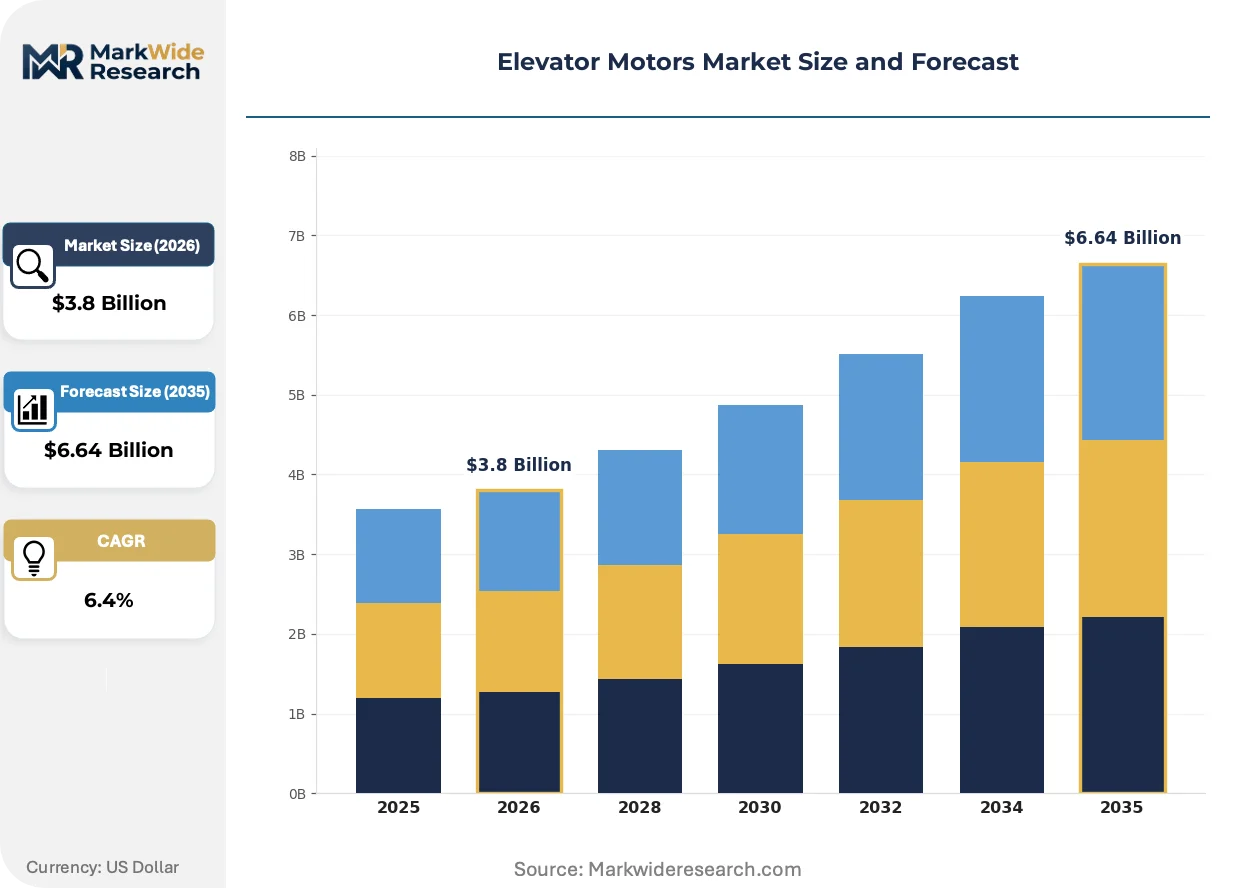
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Synchronous, Induction, Gearless, Gear-driven Application: Residential, Commercial, Industrial, Infrastructure Power Rating: Low Power, Medium Power, High Power, Ultra High Power Control System: Variable Frequency Drive, Manual Control, Digital Control, Mechanical Control |
| Companies Covered | Mitsubishi Electric Corporation, Hitachi Ltd., Otis Elevator Company, Ningbo Xinda Elevator Traction Technology Co., Ltd., Fujitec Co., Ltd., KONE Corporation, Thyssenkrupp Elevator, Hyundai Elevator Co., Ltd., Schindler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevator Motors Market Shifts & Advancements
Permanent magnet motor architectures are compressing the competitive set around energy density and acoustic performance. Regulatory pressure on building lifecycle emissions is coupling hardware specifications with digital service layers. Procurement criteria now weight total cost of ownership over upfront capital outlay.
Axial-flux permanent magnet motors are absorbing design attention for their superior torque density and compact axial envelope. High-rise developers in Singapore and Dubai specify these configurations for sky lobby and express shuttle applications. The technology is absorbing market share from conventional radial designs by eliminating gearbox bulk and reducing machine room footprint by thirty to forty percent.
EU F-Gas Regulation amendments are tightening refrigerant phase-out schedules that indirectly cascade into elevator efficiency requirements. Building system integrators must now document combined HVAC and vertical transportation energy budgets for ESG disclosure. European retrofit contractors respond by bundling synchronous motor upgrades with heat pump replacements to meet portfolio-level carbon targets.
Service contract unbundling is fragmenting the traditional full-maintenance model. Large property managers in New York and London now separate predictive analytics subscriptions from physical maintenance dispatch, sourcing motor monitoring from specialized software vendors. This shift compresses OEM service margins while opening hardware-agnostic platform opportunities for independent software providers.
Elevator Motors Market Segmentation
Elevator motor procurement divides sharply between new installation specifications and modernization requirements. Segment boundaries shift as building codes tighten and super-tall construction redefines performance thresholds.
Motor Type:
Upgrade cycles favor configurations that minimize shaft footprint and acoustic intrusion in occupied buildings.
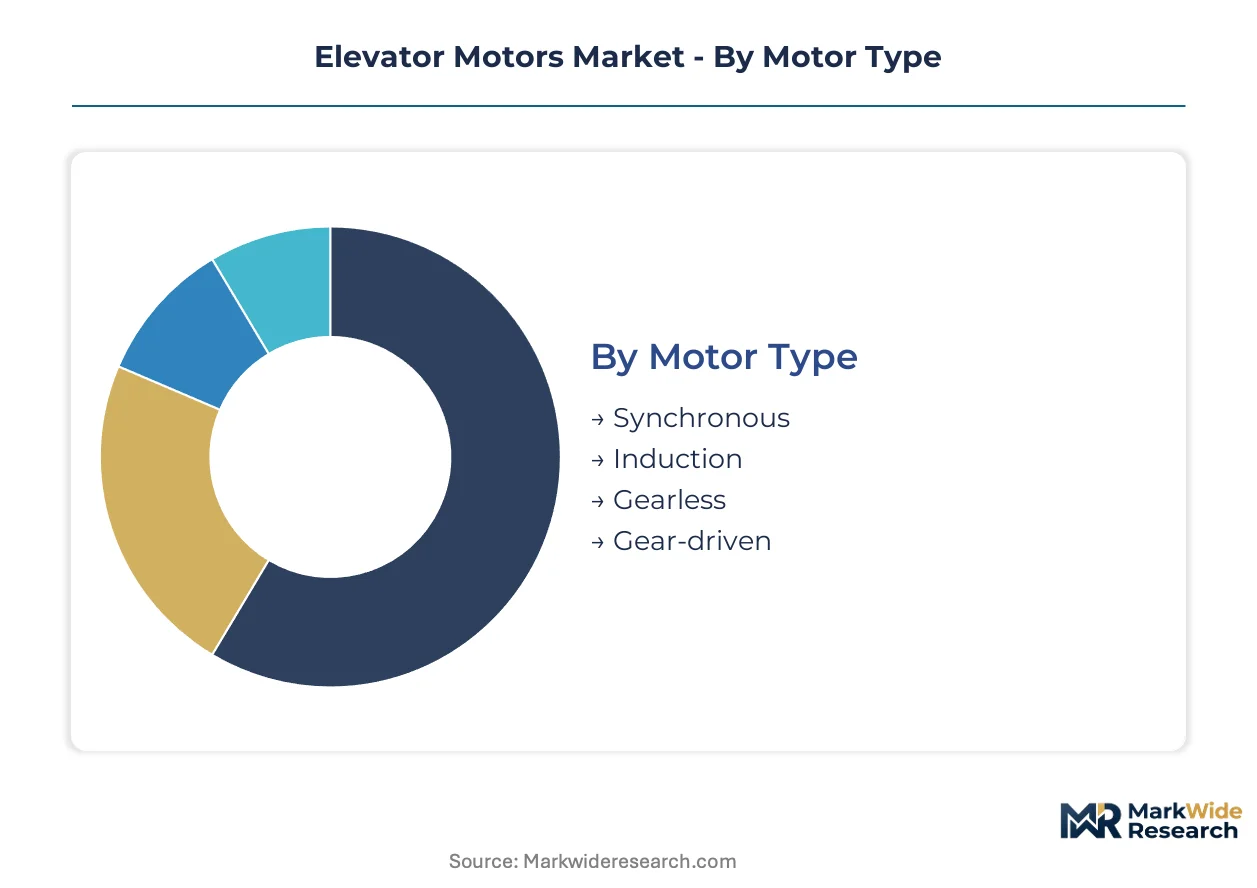
- Synchronous:Permanent magnet synchronous machines eliminate transmission losses through direct drive coupling. Gearless variants dominate super-tall installations in Singapore and Dubai where machine room space commands premium real estate valuations.
- Induction:Squirrel-cage induction motors retain cost advantages in mid-rise residential retrofits across São Paulo and Mumbai. Copper winding configurations face margin pressure from commodity volatility but satisfy modest speed requirements without permanent magnet supply exposure.
- Gearless:Direct-drive architectures reduce acoustic emissions below 55 decibels for hospital and hospitality specifications.
- Gear-driven:Worm and helical gear configurations persist in legacy building stocks with established machine room footprints.
Synchronous sits at the top of the volume ranking, with Gearless climbing the fastest.
Application:
End-use concentration tracks urban density gradients and regulatory retrofit mandates.
- Commercial:Office tower specifications prioritize regenerative drive compatibility and ESG disclosure alignment. China's state-mandated urban renewal programs in Beijing and Shanghai are absorbing thousands of traction system replacements.
- Residential:High-rise vertical housing in Mumbai and São Paulo specifies gearless permanent magnet machines to meet noise ordinances in dense neighborhoods.
- Industrial:Freight and manufacturing applications tolerate higher acoustic profiles for load capacity.
- Infrastructure:Metro rail and airport specifications demand redundant braking systems and extended duty cycles.
Commercial commands the largest installed base, with Residential expanding most quickly.
Power Rating:
Building height and cab capacity determine torque requirements across the specification spectrum.
- Low Power:Motors below 5 kW serve duplex and triplex residential installations with minimal speed demands.
- Medium Power:5-15 kW ratings cover standard commercial mid-rise specifications.
- High Power:15-50 kW machines handle express shuttle applications in super-tall towers. Sky lobby configurations in Dubai and New York absorb concentrated demand for compact high-torque density.
- Ultra High Power:Exceeding 50 kW for heavy freight and specialized industrial vertical transport.
Medium Power dominates unit shipments, with High Power gaining share fastest.
Control System:
Modernization programs are displacing legacy governors with digital architectures.
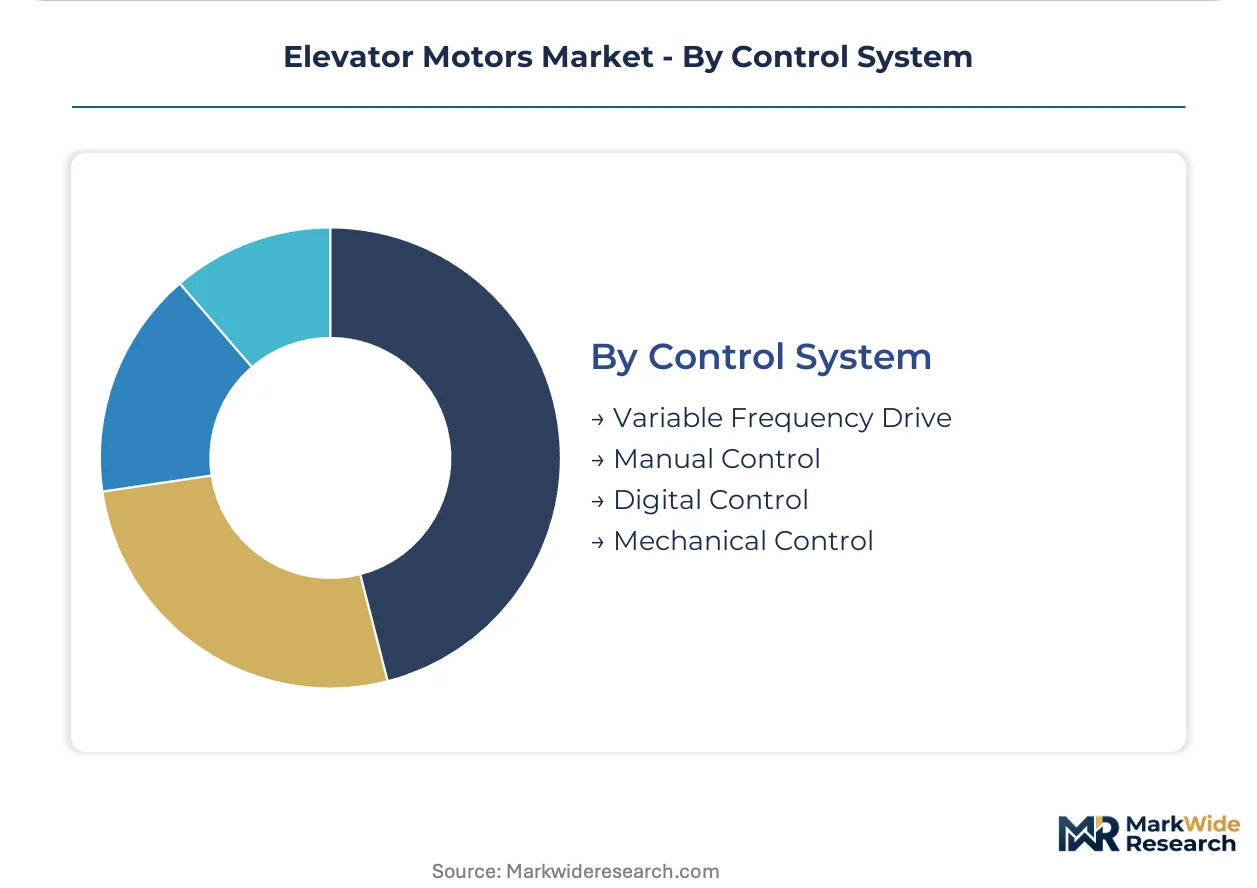
- Variable Frequency Drive:PWM-based speed control commands the widest installed base across aging building stocks. VFD commissioning requires technician skills concentrated in aging North American and European workforces.
- Digital Control:Sensor-embedded architectures enable predictive maintenance platforms and cloud analytics integration.
- Manual Control:Mechanical governors persist in heritage building preservation projects.
- Mechanical Control:Rope brake and centrifugal governor systems face obsolescence under updated safety codes.
Variable Frequency Drive maintains volume leadership, with Digital Control ascending the growth curve fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elevator motor manufacturing traces its industrial lineage to early 20th-century American steel-frame construction, where Otis pioneered safety braking systems for Chicago and New York skyscrapers. German engineering firms later refined gearless traction technology for European high-rise density. Japanese manufacturers subsequently dominated permanent magnet synchronous motor miniaturization during the 1980s bubble economy expansion.
China
State-mandated urban renewal programs in Beijing and Shanghai are replacing aging traction systems across thousands of commercial towers. GB standards enforce energy consumption labeling that extends product validation cycles. The Yangtze River Delta manufacturing corridor concentrates domestic motor production for both indigenous elevator brands and multinational supply chains.
United States
The Department of Energy enforces minimum efficiency standards for commercial elevator systems under federal appliance regulations. New York and Chicago high-rise portfolios drive modernization demand for regenerative drive compatibility. The Northeast Corridor absorbs concentrated premium synchronous motor specifications for Class A office retrofits.
Germany
The EU F-Gas Regulation compels building portfolio managers to weight lifecycle energy consumption in procurement decisions. REACH compliance requirements filter permanent magnet supply chains for neodymium sourcing transparency. The Rhine-Ruhr industrial cluster anchors gearless motor R&D for super-tall European developments.
Japan
METI Top Runner programs continuously ratchet motor efficiency benchmarks for government building retrofits. Tokyo's vertical density mandates acoustic compliance below 55 decibels in residential shafts. The Kanto manufacturing belt retains concentrated expertise in permanent magnet rotor balancing for premium export markets.
India
The Smart Cities Mission drives metro rail and transit-oriented development specifications for regenerative drive systems. BIS certification timelines compress deployment schedules for foreign OEMs. Mumbai and Delhi-NCR high-rise residential construction absorbs gearless permanent magnet machines for noise ordinance compliance.
Elevator Motors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service bundling dimensions. The vendor base organizes into three tiers: integrated elevator OEMs with captive motor production, specialized traction motor fabricators supplying multiple brands, and regional maintenance contractors sourcing hardware-agnostic replacements. Dominant competitive moves include digital predictive maintenance platform integration and axial-flux motor architecture licensing for sky lobby applications.
Within the integrated OEM tier, Mitsubishi Electric Corporation and KONE Corporation exemplify archetypes combining in-house permanent magnet production with service contract bundling. Otis Elevator Company anchors the premium modular design segment. Among specialized fabricators, Ningbo Xinda Elevator Traction Technology Co., Ltd. occupies a position serving domestic Chinese elevator assemblers and export markets. Hitachi Ltd. and Fujitec Co., Ltd. represent Japanese engineering-intensive positioning for high-rise Asian developments.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Otis Elevator Company |
| Ningbo Xinda Elevator Traction Technology Co., Ltd. |
| Fujitec Co., Ltd. |
| KONE Corporation |
| Thyssenkrupp Elevator |
| Hyundai Elevator Co., Ltd. |
| Schindler Group |
| Others |
Supply & Pricing Matrix
Premium-commodity bifurcation between gearless permanent magnet synchronous systems and conventional induction configurations governs both margin structures and sourcing strategies across the elevator motors ecosystem. China's GB standards and EU F-Gas Regulation compliance costs concentrate pricing power with integrated OEMs while compressing margins for commodity-tier fabricators dependent on copper winding architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and after-sales bundling intensity. Premium synchronous motor specifications command substantial markups in super-tall developments across Singapore and Dubai where machine room space constraints override capital cost sensitivity. Cost compression in mid-rise residential segments is intensifying because copper price volatility and rare earth supply concentration squeeze induction motor fabricators serving São Paulo and Mumbai developers. Standard-tier buyers exhibit highest price sensitivity, while premium-tier purchasers weight total cost of ownership and predictive maintenance subscriptions over upfront outlay.
Supply Chain Analysis
Domestic-content mandates in China's state-mandated urban renewal programs are reshaping sourcing patterns for multinational OEMs seeking traction system replacement contracts in Beijing and Shanghai. Permanent magnet production draws from neodymium processing concentrated in China, with secondary winding and power electronics fabrication anchored in Japan and Germany. Single-source vulnerability in rare earth supply creates structural exposure for European and Japanese manufacturers. Distribution runs through elevator OEM captive channels, specialized traction motor fabricators, and regional maintenance contractors sourcing hardware-agnostic replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elevator motors market functions as a stable compounder underpinned by regulatory-mandated replacement cycles in aging commercial building stocks across China and Europe.
For Market Incumbents: Cement defensible positioning through captive permanent magnet motor production and predictive maintenance platform bundling. Vertical integration into neodymium supply partnerships mitigates rare earth concentration risk. Digital service layer investments protect margins against unbundling pressures from specialized software vendors in New York and London property management markets. For New Entrants and Emerging Players: Axial-flux permanent magnet architectures offer technology-first wedge opportunities in sky lobby and express shuttle applications where torque density requirements exceed incumbent radial design capabilities. India's Smart Cities Mission metro rail specifications present the most penetrable geography for regenerative drive system specialists. Go-to-market execution should prioritize BIS certification acceleration and partnerships with domestic elevator assemblers in the Yangtze River Delta. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized traction motor fabricators possessing axial-flux licensing and established supply relationships with premium OEMs. Long-term viability centers on regulatory tailwinds from building lifecycle emissions disclosure requirements and continuous efficiency benchmark ratcheting under Japan METI Top Runner programs. Monitor GB standard certification timeline extensions as inflection indicator for foreign OEM competitive positioning in China's replacement cycle.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Supply | Neodymium sourcing partnerships with Chinese processors reduce input vulnerability for European and Japanese manufacturers. |
| Predictive Maintenance Platform Launch | Sensor-embedded motor architectures bundled with cloud analytics create recurring revenue streams from uptime guarantees. |
| Axial-Flux Motor Architecture Licensing | Compact torque density specifications capture sky lobby demand in Dubai and New York super-tall developments. |
| GB Standard Certification Investment | Accelerated validation cycles unlock state-mandated urban renewal contracts across Beijing and Shanghai commercial towers. |
| Joint Venture with Domestic Chinese Assemblers | Local production footprint satisfies domestic-content requirements for Yangtze River Delta supply chain integration. |
Research Methodology
Direct dialogue with elevator OEM product managers, traction motor procurement leads at major developers, electromechanical maintenance contractors, and regulatory compliance officers grounded qualitative findings. Secondary validation drew from GB standards documentation, EU F-Gas Regulation amendments, METI Top Runner program specifications, and SEC filings from listed elevator manufacturers. Bottom-up and top-down triangulation cross-referenced unit shipment estimates with installed base modernization requirements across geographic markets.
Bottom-up modeling segmented volume and value outputs across motor type, application, power rating, and control system dimensions throughout the forecast period. CAGRs were derived from replacement cycle analysis tied to building age distributions and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated copper price trajectory assumptions and rare earth supply elasticity parameters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruption, electromechanical technician workforce availability, and GB standard certification timeline volatility. Forecasts reflect assumptions around continuous efficiency benchmark ratcheting and ESG disclosure requirement expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Spargers Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
North America Induction Motor Market