
 Computer-Aided Manufacturing (CAM) Market | 2026-2036
Computer-Aided Manufacturing (CAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Computer-Aided Manufacturing (CAM) Market Intelligence
China's significant investment in advanced manufacturing infrastructure is reconfiguring the competitive landscape for CAM software providers. Siemens AG leverages its deep integration with industrial automation hardware to offer end-to-end solutions for machine shops. Dassault Systèmes differentiates its offerings through the comprehensive 3DEXPERIENCE platform, which combines design, simulation, and manufacturing. Meanwhile, Autodesk Inc. competes by providing accessible and powerful software suites tailored to both small and large enterprises.
Computer-Aided Manufacturing (CAM) software translates computer-aided design (CAD) models into machine-readable instructions, primarily G-code, for automated equipment. Its core function is to generate optimal toolpaths for CNC machines to execute cutting, milling, or turning operations with high precision. Demand for 5-Axis Milling technology is strong, particularly for producing complex aerospace components with intricate geometries. The machine shops and automotive suppliers end-user segments constitute a large volume market, often utilizing less complex 3-axis milling and turning applications.
Regulatory frameworks directly influence CAM software development and deployment. In the United States, FAA mandates for part traceability and quality assurance drive feature requirements for aerospace applications. In Europe, CE marking for machinery safety and interoperability under the Machinery Directive shapes how CAM systems integrate with physical hardware. ISO quality management standards also compel vendors to embed process control and documentation capabilities. Vendor selection will increasingly depend on the software's ability to support hybrid manufacturing processes within connected digital factory ecosystems.
Market Dynamics
The convergence of CAM with additive and hybrid manufacturing processes creates a central structural force. This requires software to manage not just subtractive toolpaths but also material deposition, fundamentally altering software architecture and vendor capabilities.
Growth Catalysts
- Aerospace Component Complexity:Demand from the aerospace industry for lightweight, high-strength parts manufactured from composites and superalloys necessitates advanced 5-axis and multi-function CAM software to machine intricate geometries.
- National Industrial Policies:Government-led initiatives, such as China's industrial modernization programs, stimulate significant domestic investment in advanced machine tools and the corresponding CAM software needed to operate them.
- Hybrid Manufacturing Integration:The combination of additive (3D printing) and subtractive (CNC machining) processes within a single machine tool drives requirements for CAM systems that can program both functions seamlessly.
Market Restraints
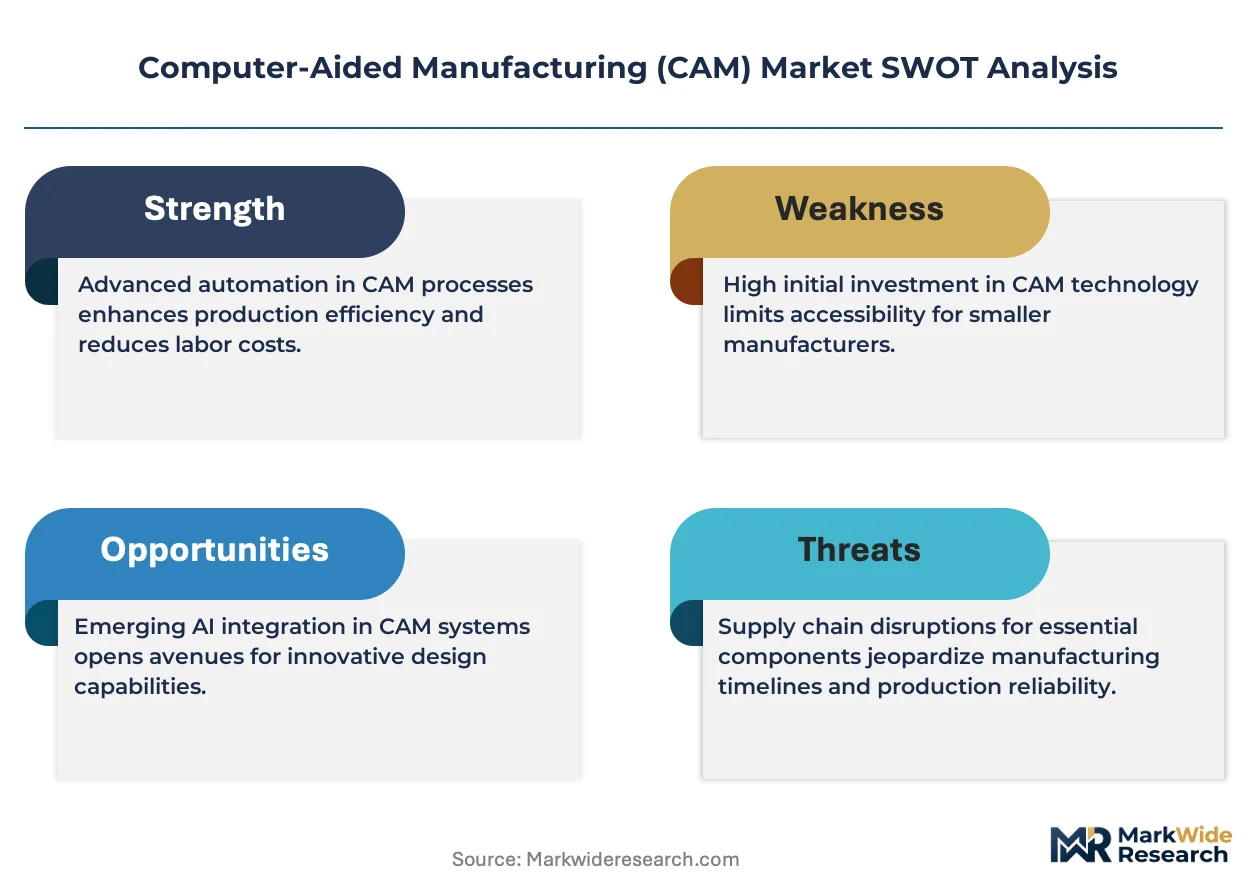
- High Software and Hardware Costs:The initial investment for high-end CAM software licenses, subscriptions, and the powerful computer workstations required to run them remains a significant barrier for smaller machine shops.
- Interoperability Deficiencies:Persistent challenges in data translation between different CAD formats and CAM systems, as well as between CAM output and specific CNC machine controllers, create workflow inefficiencies.
- Open-Source Alternatives:The availability of increasingly capable free and open-source CAM software presents a substitution threat, particularly for 3-axis milling applications in the hobbyist and small business segments.
Strategic Opportunities
- Generative Design and AI:Integrating artificial intelligence and machine learning algorithms into CAM software can automate toolpath generation and optimize machining strategies for new part designs, reducing programming time.
- Medical Device Manufacturing:The growing need for patient-specific medical implants, surgical guides, and orthopedic devices, often with complex organic shapes, opens a high-value application segment for precision CAM.
- Southeast Asian Industrialization:Manufacturing economies in Vietnam, Thailand, and Malaysia are upgrading their industrial capabilities, creating new demand for CAM solutions as they adopt more automated production technologies.
Industry Challenges
- Skilled Programmer Shortage:A widening skills gap exists for manufacturing engineers and CNC programmers who possess the expertise to effectively use advanced CAM software for complex multi-axis machining.
- Legacy System Integration:Integrating modern CAM software into existing factory IT infrastructure, including older Manufacturing Execution Systems (MES) and Enterprise Resource Planning (ERP) systems, is often complex and costly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer-Aided Manufacturing (CAM) Market |
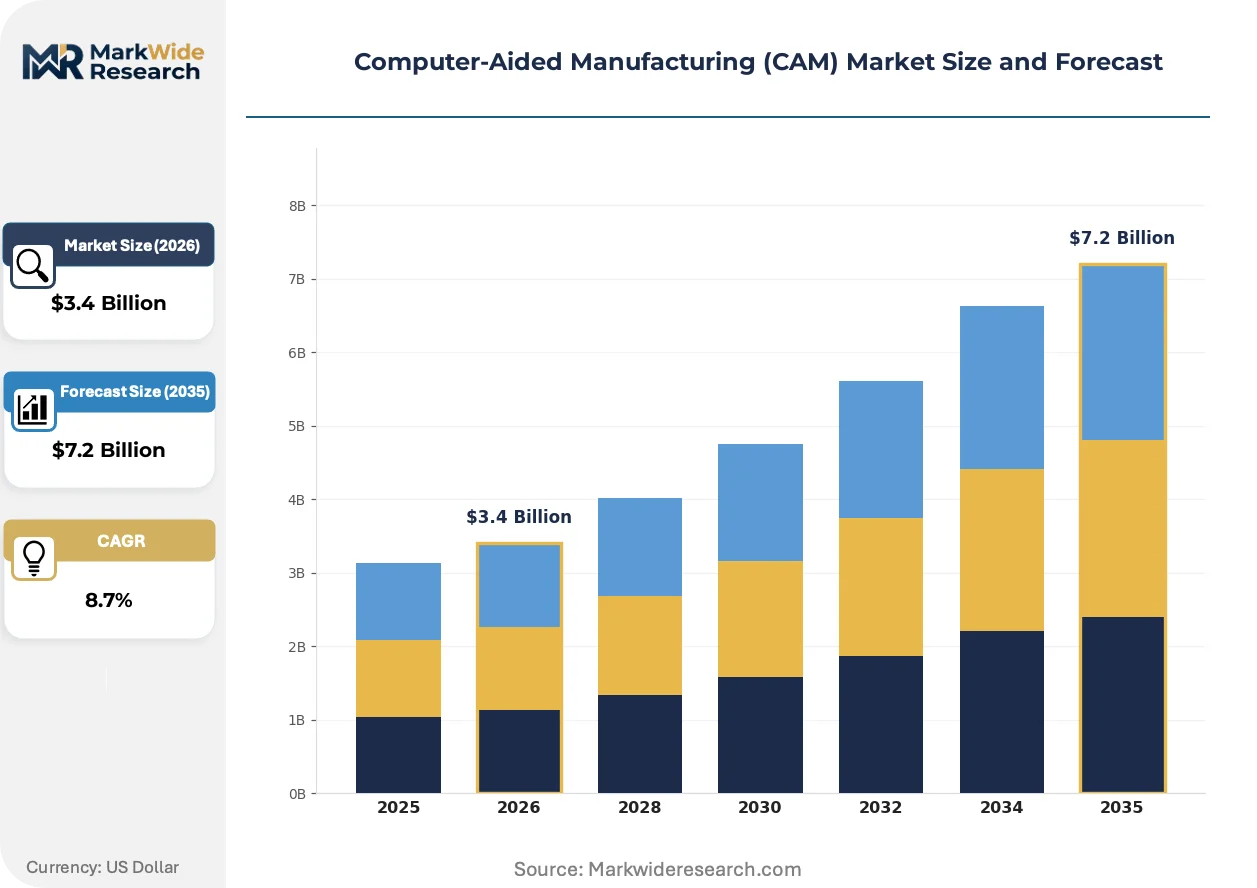
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD/CAM Software, CNC Machine Integration, Simulation Software, Post-Processing Software, Toolpath Software Technology: 3-Axis Milling, 5-Axis Milling, Turn-Mill, Wire EDM, Laser Cutting Application: Aerospace Components, Electronic Enclosures, Customized Molds, Precision Gears, Consumer Electronics Parts End User: Machine Shops, Aerospace Manufacturers, Electronics Fabricators, Mold Makers, Automotive Suppliers |
| Companies Covered | Hexagon AB, NTT Data Engineering Systems, Autodesk Inc., SolidCAM, Hypertherm, Siemens AG, PTC, Mastercam, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer-Aided Manufacturing (CAM) Market Strategic Shifts & Innovations
CAM software's evolution beyond simple toolpath generation is defining the current market. The technology is becoming an integrated data and simulation hub within the digital factory ecosystem, connecting design intent directly to shop floor execution.
Digital twin technology provides a high-fidelity virtual model of a CNC machine and its manufacturing process. Aerospace and automotive manufacturers are rapidly adopting it for collision checking and process optimization before any metal is cut. This advancement is virtualizing the entire machine setup and proving-out phase, drastically reducing physical trial runs and material waste.
The European Union’s forthcoming Cyber Resilience Act (CRA) mandates stringent cybersecurity standards for all products with digital elements sold in the region. This regulation compels CAM software developers to embed security-by-design principles to protect against data breaches in connected manufacturing networks. Vendors across the globe targeting the EU market must now prioritize software hardening and vulnerability management.
A transition from perpetual software licenses to cloud-based subscription models is altering purchasing behavior. This model disrupts the traditional Value-Added Reseller channel by enabling direct-to-customer sales and continuous updates. The shift is most pronounced among small and medium-sized machine shops in North America and Europe seeking lower initial capital outlay.
Computer-Aided Manufacturing (CAM) Market Segmentation
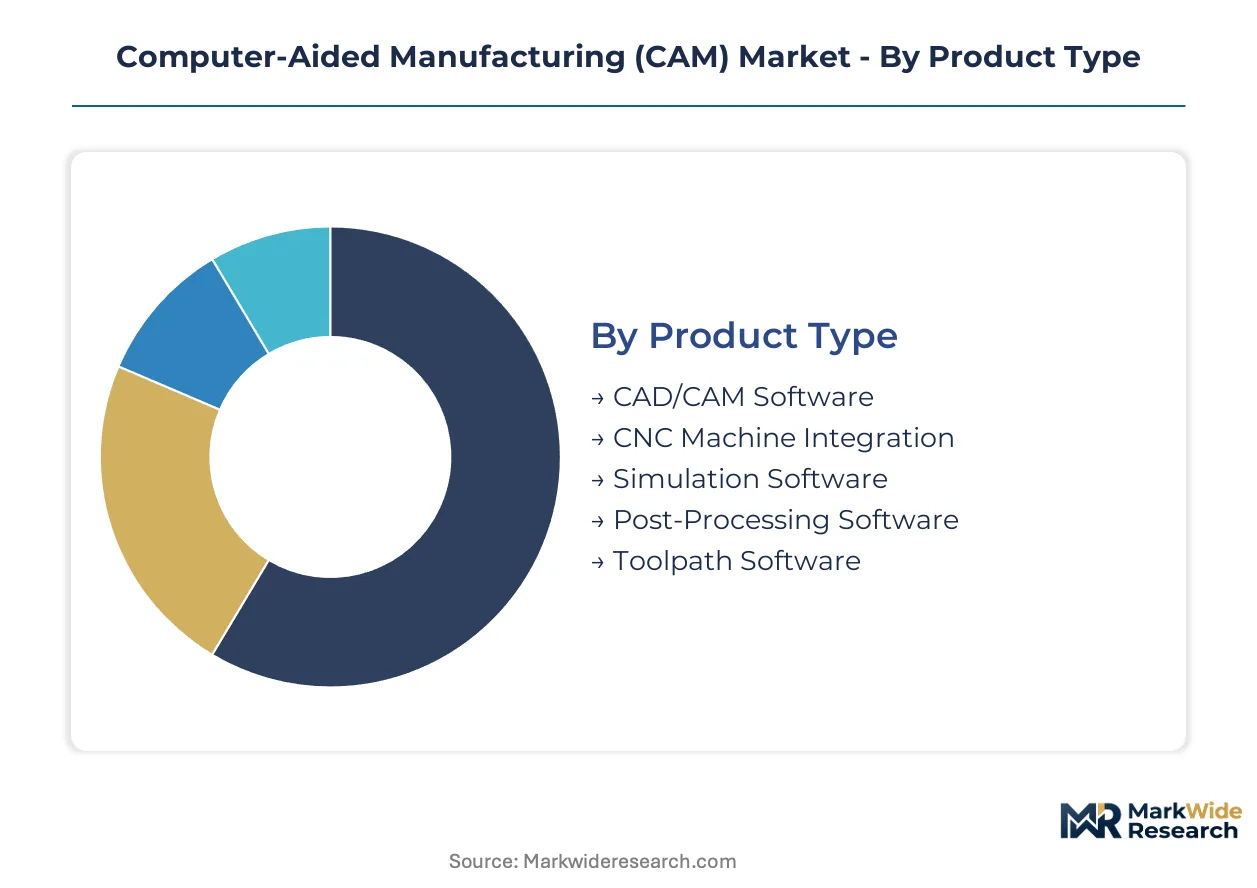
The Computer-Aided Manufacturing (CAM) market segments provide a granular view of solution specialization and end-user requirements. Understanding these divisions helps software providers tailor their offerings to specific industry demands. Each segment highlights distinct technical capabilities and operational benefits.
Product Type:
The product type dimension delineates the functional capabilities offered by CAM solutions.
- CAD/CAM Software:This integrated software combines design and manufacturing functionalities, streamlining the product development lifecycle from concept to production. Demand concentrates heavily within China's advanced manufacturing sector, driven by national industrial modernization policies.
- CNC Machine Integration:This category focuses on connecting CAM output directly with automated equipment for seamless operation and data exchange on the shop floor.
- Simulation Software:This software provides virtual testing environments for toolpaths and machining processes, reducing physical prototyping and material waste. Aerospace and automotive manufacturers rapidly adopt this for collision checking and process optimization.
- Post-Processing Software:These tools translate generic CAM output into machine-specific G-code, ensuring compatibility with various CNC controllers.
- Toolpath Software:This specialized software generates optimized cutting paths for CNC machines based on CAD models, ensuring precision and material efficiency.
CAD/CAM Software commands the established base. The steepest expansion runs through Simulation Software.
Technology:
The technological sophistication of CAM systems reflects the complexity of manufacturing operations.
- 3-Axis Milling:This technology performs machining operations along three axes, suitable for simpler geometries and general-purpose part production. Machine shops and automotive suppliers represent a large volume market for these applications.
- 5-Axis Milling:This advanced technology offers multi-directional machining for intricate geometries, crucial for complex aerospace components and medical devices. Demand for this technology is strong, particularly for producing complex aerospace components with intricate geometries.
- Turn-Mill:This technology combines turning and milling operations on a single machine, enhancing efficiency for cylindrical parts and reducing setup times.
- Wire EDM:This process utilizes an electrically charged wire to cut conductive materials with high precision, often for tool and die making.
- Laser Cutting:This method employs a focused laser beam to cut materials, widely used in sheet metal fabrication and prototyping across industries.
5-Axis Milling technology currently exhibits the fastest expansion trajectory.
Application:
Customer requirements define the application segments, driving specialized CAM feature development.
- Aerospace Components:This segment involves manufacturing lightweight, high-strength parts from composites and superalloys, necessitating advanced 5-axis and multi-function CAM software. FAA mandates for part traceability in the United States drive specific feature requirements.
- Electronic Enclosures:This application focuses on precise machining for housings and cases of electronic devices, demanding high surface finish and accuracy.
- Customized Molds:This segment requires highly accurate machining for unique mold designs, often used in injection molding for various industries. The medical device manufacturing sector increasingly relies on this for patient-specific implants.
- Precision Gears:This application involves tight tolerance machining for gears used in automotive and industrial machinery, critical for mechanical performance.
- Consumer Electronics Parts:This segment addresses high-volume production of components for devices like smartphones and laptops, emphasizing efficiency and repeatability.
Aerospace Components drive significant high-value demand.
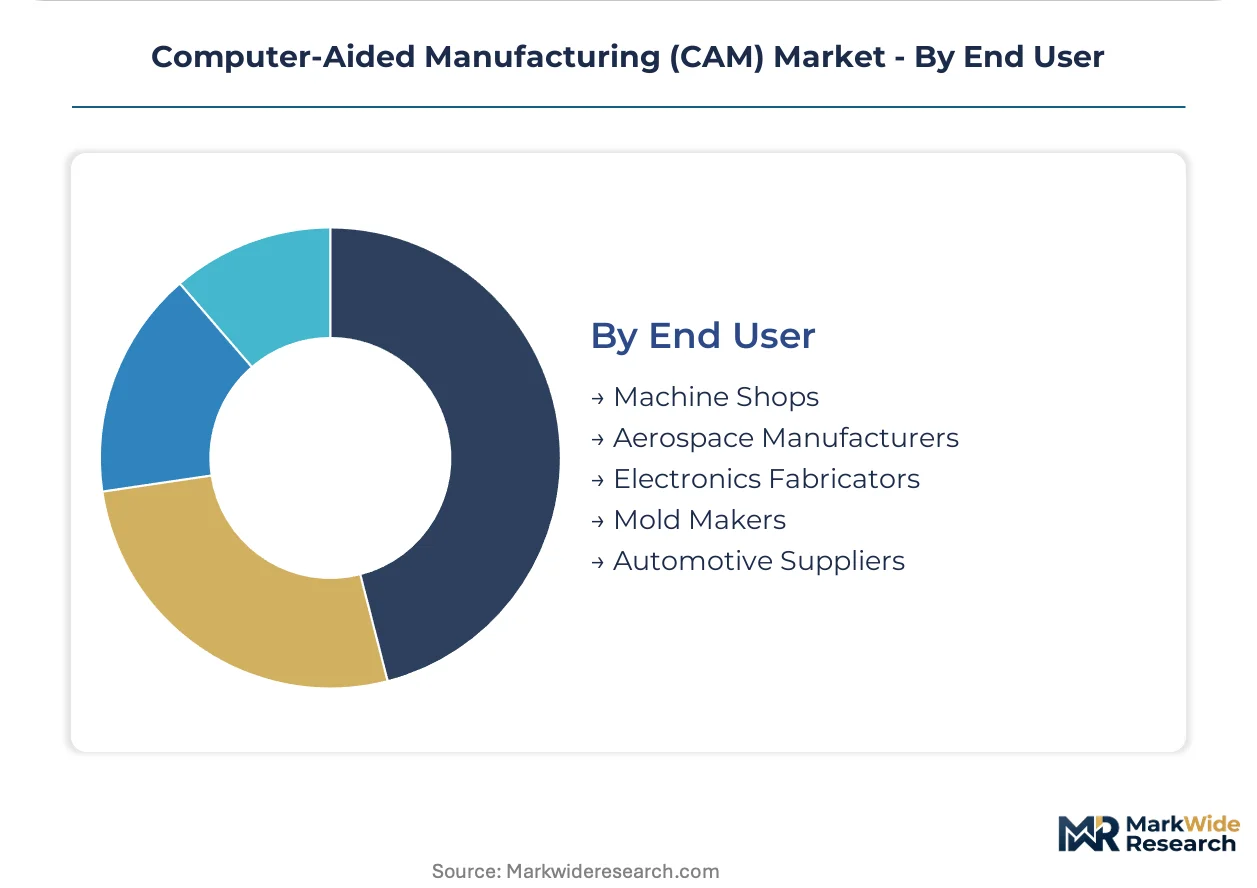
End User:
The end-user landscape shapes specific CAM software needs and deployment strategies.
- Machine Shops:These facilities, ranging from small businesses to large enterprises, utilize CAM for diverse manufacturing tasks, often seeking accessible and powerful software suites. The shift to cloud-based subscription models benefits smaller shops in North America and Europe.
- Aerospace Manufacturers:These manufacturers require highly specialized CAM for complex geometries, advanced materials, and stringent regulatory compliance, such as FAA quality assurance. Digital twin technology is rapidly adopted by these manufacturers for process optimization.
- Electronics Fabricators:These companies employ CAM for creating circuit boards, enclosures, and other components for electronic devices, focusing on precision.
- Mold Makers:These specialists produce molds and dies, demanding high precision and surface finish capabilities from CAM software for intricate tooling.
- Automotive Suppliers:These firms utilize CAM for manufacturing components, tooling, and fixtures for the automotive industry, focusing on efficiency and volume production.
Machine Shops constitute a foundational demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT initiatives, coupled with national industrial policies, anchor significant investment in advanced manufacturing, driving demand for CAM software. This global market sees varied adoption rates and technological focuses across key industrial nations. Regulatory frameworks and industrial modernization programs shape regional CAM market dynamics.
China
National industrial modernization policies stimulate substantial domestic investment in advanced machine tools and the CAM software required for their operation. Government-led initiatives, including those from the MIIT, foster a competitive environment for local and international software providers. The Yangtze River Delta region, particularly around Shanghai, sees heavy concentration of advanced manufacturing industries adopting CAM solutions.
United States
Demand for advanced CAM software stems from the aerospace industry's need for complex component manufacturing and the medical device sector's precision requirements. FAA mandates for part traceability and quality assurance directly influence feature requirements for aerospace applications. Aerospace clusters in the Pacific Northwest, especially around Seattle, drive high-value CAM software adoption for intricate geometries.
Germany
Industry 4.0 integration and a strong automotive manufacturing base propel the adoption of sophisticated CAM solutions. CE marking for machinery safety and interoperability under the Machinery Directive shapes how CAM systems integrate with physical hardware. Bavaria, with its robust automotive and industrial machinery sectors, represents a key hub for advanced CAM technology deployment.
Japan
High-tech manufacturing, including precision gears and robotics, necessitates advanced CAM capabilities for intricate part production and process optimization. METI initiatives encourage smart factory development and the integration of digital manufacturing technologies. The Kansai region, encompassing Osaka and Kyoto, remains a significant manufacturing hub utilizing sophisticated CAM systems.
India
Industrialization efforts and a growing automotive supplier base create foundational demand for CAM solutions, particularly for 3-axis milling and turning applications. Government programs, such as PLI schemes, aim to boost domestic manufacturing capabilities, increasing the need for automated production tools. Chennai, a major automotive manufacturing center, drives demand for efficient CAM software in volume production.
Computer-Aided Manufacturing (CAM) Market Key Industry Players
End-to-end solution providers and specialized software developers split the market, catering to diverse industrial needs. The competitive landscape features a mix of established players offering comprehensive platforms and niche vendors focusing on specific machining technologies. Companies increasingly pursue portfolio diversification and strategic partnerships to expand their market reach and technological offerings.
Within the end-to-end solution provider archetype, Siemens AG exemplifies deep integration with industrial automation hardware, offering comprehensive solutions for machine shops. Dassault Systèmes anchors the market with its comprehensive 3DEXPERIENCE platform, which combines design, simulation, and manufacturing capabilities. Autodesk Inc. sits within the segment providing accessible and powerful software suites tailored to both small and large enterprises, representing broad market accessibility.
| Leading Market Players |
|---|
| Hexagon AB |
| NTT Data Engineering Systems |
| Autodesk Inc. |
| SolidCAM |
| Hypertherm |
| Siemens AG |
| PTC |
| Mastercam |
| Dassault Systèmes |
| Others |
Cost & Logistics Intelligence
China's national industrial policies anchor significant investment in advanced manufacturing, which concentrates CAM software demand and influences pricing power for specialized solutions. This concentration directly impacts margin pools for vendors catering to high-growth segments.
Pricing Analysis
Pricing for CAM software exhibits significant regional variation, with higher costs in developed markets like the United States and Germany reflecting advanced feature sets and regulatory compliance. The dominant pricing structure transitions from perpetual licenses to cloud-based subscription models, particularly in North America and Europe. Price differentiation stems from software complexity, such as 5-axis capabilities, and bundled after-sales service. Pricing pressure intensifies for 3-axis milling applications due to open-source alternatives. Smaller machine shops are most price-sensitive, while aerospace manufacturers prioritize advanced features over cost.
Supply Chain Analysis
Interoperability deficiencies between CAD formats and CAM systems present a significant supply chain risk, hindering seamless data flow for manufacturing workflows. The supply of core CAM software development talent concentrates in established technology hubs across the United States, Germany, and France. Key component dependencies include high-performance computing hardware and specialized graphics processing units. Regulatory restrictions, such as the EU Cyber Resilience Act, also shape software development and deployment. Distribution runs through a mix of direct sales and value-added resellers, with a shift towards direct cloud-based delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Computer-Aided Manufacturing market experiences high-growth disruption driven by the integration of AI and generative design, fundamentally altering toolpath optimization. This technological inflection creates new opportunities and challenges across the manufacturing ecosystem.
For Market Incumbents: Insulate core market share by deepening integration with industrial automation hardware, as exemplified by Siemens AG. Invest in advanced simulation and digital twin capabilities to counter the threat from niche AI-driven optimization tools. Control the customer relationship through comprehensive 3DEXPERIENCE-like platforms, bundling design, simulation, and manufacturing functionalities to mitigate competitive pressure from open-source alternatives. Expand service offerings for hybrid manufacturing processes, securing long-term contracts with aerospace and automotive clients.
For New Entrants and Emerging Players: Accessible cloud-native CAM solutions tailored for small and medium-sized machine shops in Southeast Asia represent the most penetrable entry point. Target the medical device manufacturing segment with specialized software for patient-specific implants and complex organic shapes. A go-to-market angle involves offering flexible subscription models combined with robust online training and community support to reduce initial investment barriers. Focus on niche 5-axis applications where existing solutions are overly complex or expensive.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established software providers specializing in niche CAM applications or specific industry verticals. Long-term viability hinges on platforms that support hybrid manufacturing and integrate generative design capabilities over the next decade. Acquisition targets should include firms with strong intellectual property in AI-driven toolpath optimization or robust data interoperability solutions. The signal to watch is the increasing adoption rate of digital twin technology across diverse manufacturing sectors, indicating readiness for advanced CAM integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Introduce AI-powered generative design modules to automate toolpath creation for complex parts. |
| Platform Integration | Integrate CAM solutions with broader MES/ERP systems to enable seamless digital factory ecosystems. |
| Strategic Partnership | Form alliances with additive manufacturing hardware vendors to co-develop hybrid CAM capabilities. |
| Acquisition of Specialist Firm | Acquire companies with expertise in medical device CAM or advanced simulation software. |
| Geographic Expansion | Establish direct sales and support channels in industrializing Southeast Asian economies. |
Research Approach
Initial hypotheses were tested against primary input from manufacturing engineers, CNC programmers, procurement leads, and R&D directors, then refined through iterative feedback. This approach combined in-depth interviews with secondary validation from industry reports, government publications (e.g., MIIT, FAA), and company financial filings. Bottom-up data collection from end-user segments was triangulated with top-down market sizing for comprehensive analysis.
Demand-supply balance models underpinned the market forecast across the analysis window, integrating historical trends with future projections. Segmentation dimensions modeled included product type, technology, application, end-user, and regional adoption patterns. Compound Annual Growth Rates were derived from an assessment of technological advancements and industrial policy impacts. Key forecast inputs included aerospace production forecasts and industrial automation investment trends.
Practitioners should monitor shifts in global trade policies and the pace of AI integration for early signals of market revision. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Europe ICS Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Motion Control Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Europe Water Automation and Instrumentation Market