
 Europe Sortation Systems Market | 2026-2036
Europe Sortation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sortation Systems Market Foresight
E-commerce fulfillment networks across Europe are reshaping how parcel and package flows move through regional distribution hubs. Daifuku leverages its deep installed base in automated material handling to sustain project pipelines across Central European logistics parks. Vanderlande Industries anchors its position through long-term service contracts with major airport baggage and parcel operators. TGW Systems specializes in high-throughput solutions for grocery and fashion retailers navigating same-day delivery pressures.
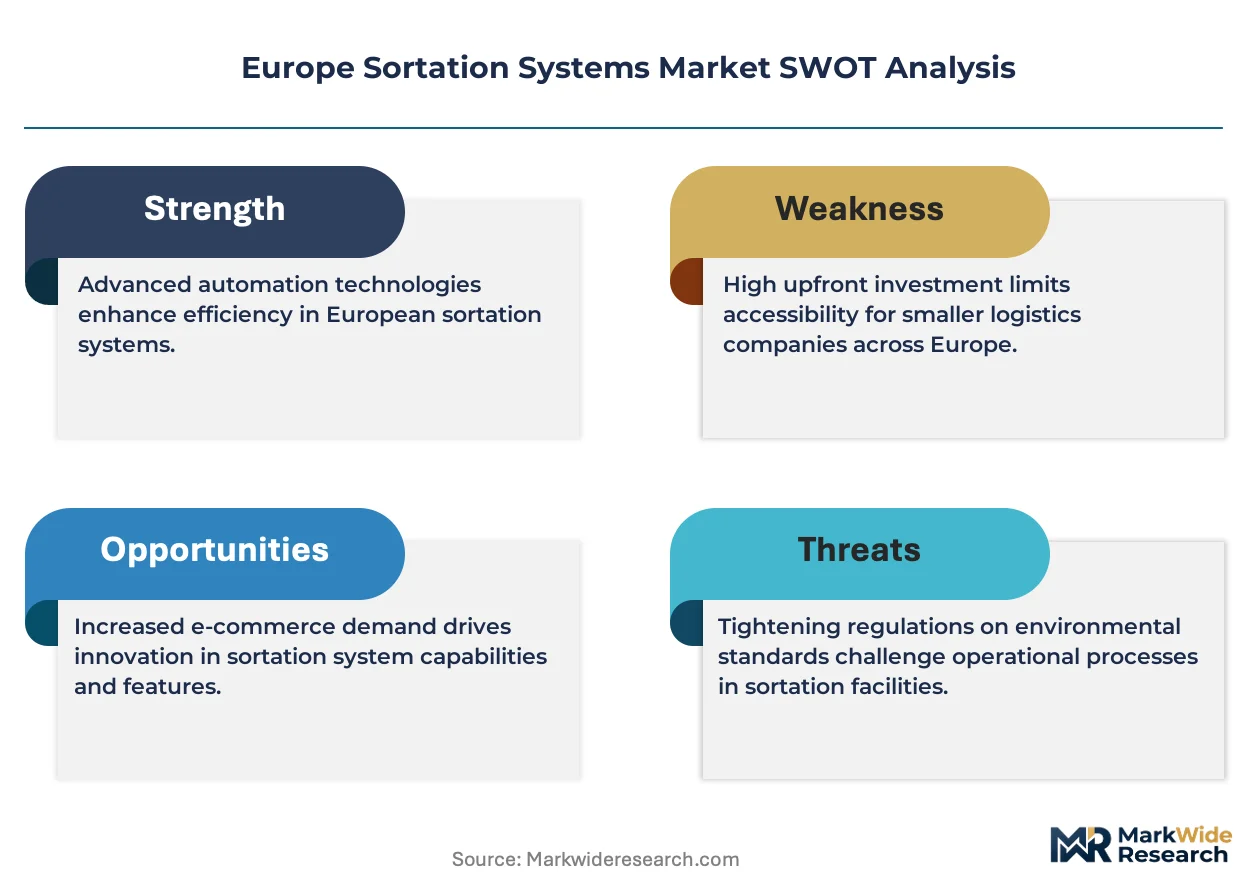
Sortation systems comprise mechanized equipment that diverts items to designated destinations using conveyors, diverters, sensors, and control software, typically processing thousands of items per hour based on barcode, RFID, or optical identification inputs. Their primary purpose centers on eliminating manual handling bottlenecks in warehouses, distribution centers, and parcel hubs where throughput velocity directly determines operational economics. Automated sortation systems now capture the dominant share of capital expenditure as labor scarcity and throughput requirements intensify across European logistics networks. Cross-belt sortation systems represent the fastest-growing product category, driven by e-commerce parcel profiles that demand gentle handling of variable package dimensions at high speeds. Manual sortation systems persist in smaller facilities and seasonal overflow operations where capital constraints outweigh throughput optimization goals.
CE marking requirements under the EU Machinery Directive establish baseline safety and interoperability standards that all installed systems must satisfy before operational deployment. The EU Green Deal's carbon accounting frameworks and national energy efficiency regulations in Germany and France are steering procurement specifications toward lower-consumption drive technologies and regenerative power systems. REACH compliance for lubricants, coatings, and electronic components adds material traceability obligations that filter through supplier qualification processes. Stakeholders must monitor how the EU AI Act's risk classification rules will affect automated control systems incorporating machine vision and predictive routing algorithms, as compliance timelines will reshape R&D priorities and vendor selection criteria across the continent.
Market Dynamics
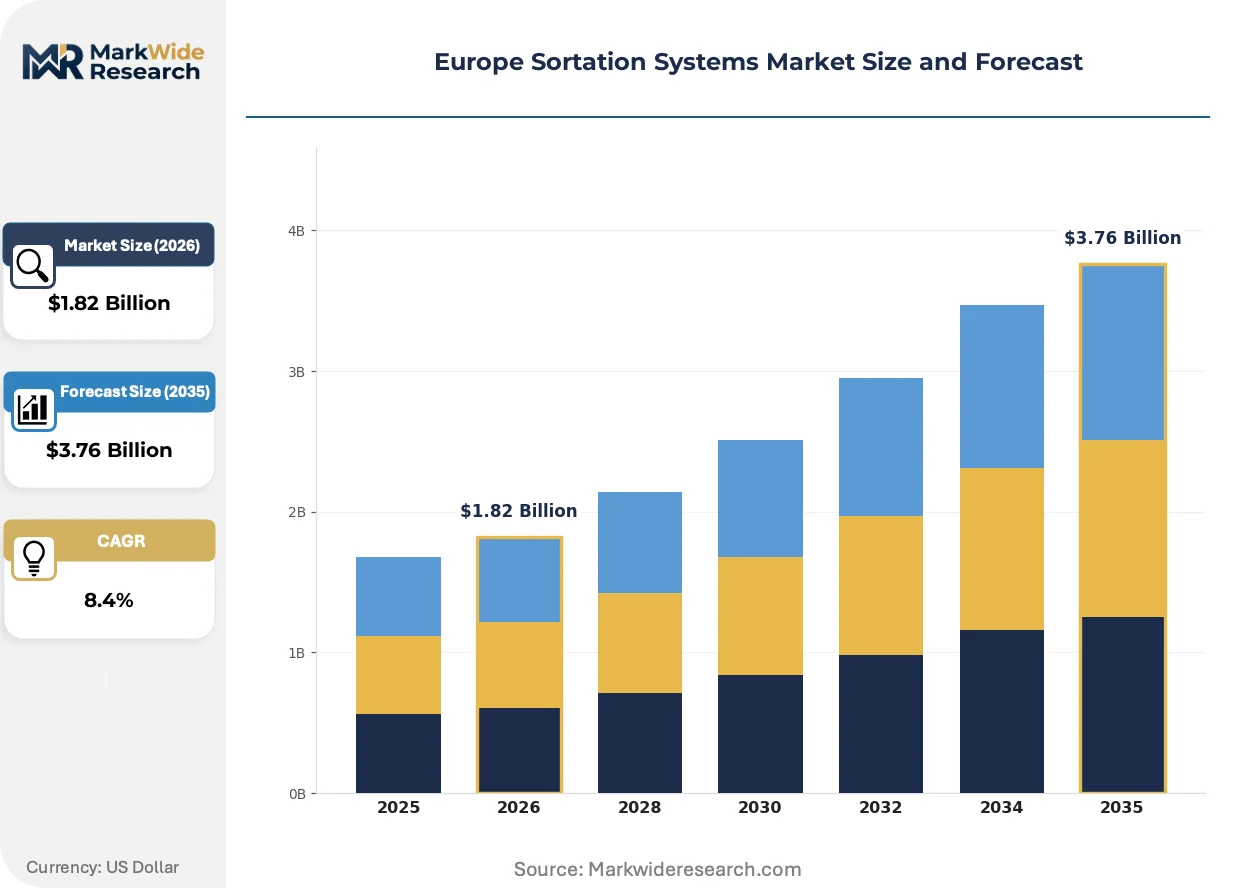
The EU Green Deal's carbon accounting frameworks are forcing logistics operators across Germany, France, and the Netherlands to retire energy-intensive legacy sortation infrastructure and accelerate procurement of regenerative-drive systems. This regulatory pressure is concentrating capital deployment in the Rhine-Ruhr corridor and Parisian distribution clusters.
Growth Catalysts
- CE marking under EU Machinery Directive:Harmonized safety standards reduce cross-border certification costs for sortation system vendors deploying across Belgium, Poland, and Spain.
- E-commerce parcel volumes:Fashion and grocery retailers in Germany and France require high-throughput handling of variable package dimensions at speeds exceeding 15,000 items per hour.
- Cross-belt sortation technology:Gentle handling capabilities capture fragile goods segments previously restricted to manual processing, expanding addressable market for pharmaceutical and electronics fulfillment.
Market Restraints
- Steel and rare-earth magnet costs:Drive motor and conveyor belt input volatility compresses project margins for systems integrators bidding on fixed-price contracts.
- Control software concentration:Dependency on German and Austrian automation software vendors creates single-source risk for predictive routing algorithms.
- Substitution by AMR-based sortation:Autonomous mobile robots with onboard diverters threaten fixed-conveyor installations in facilities under 50,000 square meters.
Strategic Opportunities
- Polish logistics corridor expansion:Underpenetrated e-commerce fulfillment infrastructure between Warsaw and Łódź offers first-mover positioning for automated parcel hubs.
- EU AI Act risk classification:Machine vision systems with predictive maintenance modules qualify for regulatory tailwinds if vendors pre-certify control algorithms before 2026 enforcement deadlines.
- Convergence of IoT sensors and digital twins:Real-time throughput optimization creates aftermarket service revenue streams beyond hardware installation.
Industry Challenges
- Mechatronics technician scarcity:Germany's KBA and industrial employer associations report unfilled vacancies for conveyor maintenance and PLC programming specialists.
- REACH compliance timelines:Material traceability obligations for lubricants and electronic coatings extend supplier qualification cycles by 8-14 months.
- Legacy WCS integration:Warehouse control software from 1990s-era installations requires custom middleware development for API connectivity with modern sortation controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sortation Systems Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Sortation Systems, Manual Sortation Systems, Semi-Automated Sortation Systems, Cross-Belt Sortation Systems End User: E-Commerce, Retail, Food & Beverage, Pharmaceuticals Technology: Barcode Scanning, RFID Technology, Optical Recognition, Automated Controls Installation: On-Site Installation, Off-Site Installation, Integrated Solutions, Customized Solutions |
| Companies Covered | Daifuku, Vanderlande Industries, TGW Systems, KNAPP AG, Beumer Group, Interroll Holding AG, Viastore Systems GmbH, Fives Group, Dematic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sortation Systems Market Shifts & Advancements
Regenerative power recovery and AI-driven routing algorithms are compressing operational expenditure profiles for European distribution operators. These advances are redrawing competitive boundaries between mechanical engineering heritage and software-native entrants.
Cross-belt sortation with regenerative braking is collapsing energy consumption benchmarks for high-velocity parcel handling. German postal operators and French e-commerce fulfillment centers are deploying these systems at replacement cycle intervals of 7-10 years. The technology is collapsing the total cost of ownership gap between fixed automation and manual labor in facilities processing over 20,000 parcels per hour.
REACH compliance for lubricants and coatings is tightening material specifications across the supplier base. Industrial consequence includes mandatory substitution of mineral-oil-based hydraulic fluids with bio-synthetic alternatives in Dutch and Belgian installations. Food and pharmaceutical logistics segments are most affected, with operators accelerating procurement of stainless-steel conveyor assemblies to preempt ECHA substance restrictions.
Buyer concentration among pan-European e-commerce platforms is compressing vendor negotiation cycles and unbundling after-sales service contracts. Fixed automation providers now face disintermediation by systems integrators offering outcome-based throughput guarantees. This pattern is most visible in Germany's Rhine-Ruhr corridor, where Amazon and Zalando procurement teams demand performance-based payment terms tied to uptime metrics rather than capital equipment transfers.
Europe Sortation Systems Market Segmentation
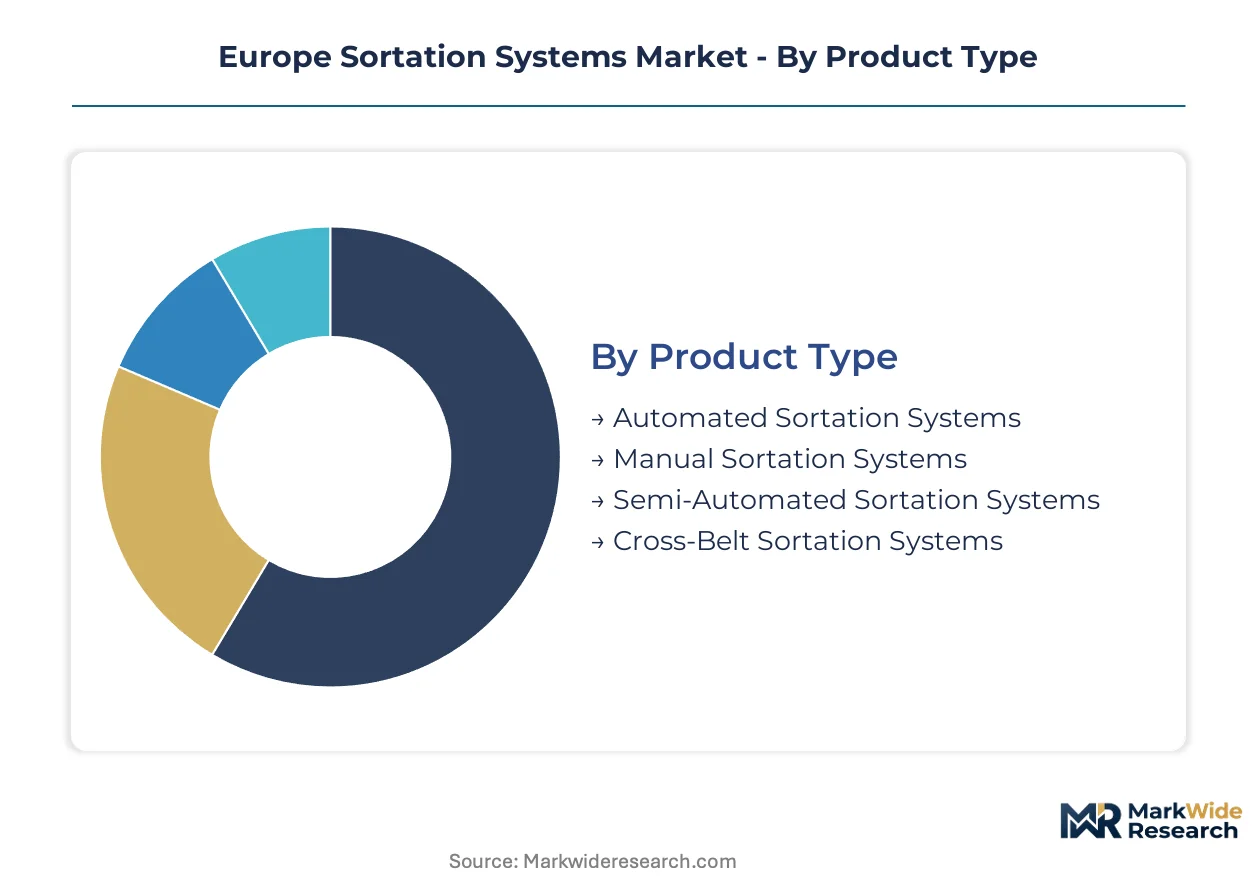
European logistics operators select sortation configurations based on throughput velocity, labor availability, and facility footprint constraints. Procurement patterns diverge sharply between parcel hubs demanding 20,000-plus items per hour and smaller fulfillment centers optimizing capital deployment. The four segmentation dimensions capture how technology choices cascade through deployment economics and operational performance.
Product Type:
Cost tier determines capital allocation across European distribution networks, with energy consumption and labor substitution rates driving procurement specifications.
- Automated Sortation Systems:Conveyor-based architectures with programmable logic controllers process variable package dimensions at sustained velocities. German postal operators and French e-commerce fulfillment centers deploy these systems in Rhine-Ruhr and Parisian distribution clusters to offset technician scarcity.
- Cross-Belt Sortation Systems:Cartridge-based diverters with regenerative braking handle fragile goods at speeds exceeding 15,000 items per hour. Pharmaceutical and electronics fulfillment segments in the Netherlands and Belgium specify these configurations to satisfy REACH compliance for gentle handling.
- Manual Sortation Systems:Human-directed parcel routing persists in seasonal overflow operations and facilities under 10,000 square meters across Poland and Spain.
- Semi-Automated Sortation Systems:Hybrid configurations blending conveyor feed with manual divert stations serve mid-tier retailers in Italy and Portugal managing capital constraints.
Automated sortation holds installed capacity. Cross-belt sortation is rotating up the share rankings.
End User:
Application-specific throughput requirements reshape equipment specifications across European verticals, with delivery velocity commitments dictating automation intensity.
- E-Commerce:Fashion and grocery platforms processing same-day delivery commitments require systems handling 25,000 parcels per hour with 99.5% read rates. German and French marketplaces drive specification intensity for variable-dimension handling.
- Retail:Omnichannel distribution centers serving store replenishment and direct-to-consumer flows deploy modular sortation architectures. Belgian and Dutch retail conglomerates prioritize interoperability with existing warehouse management systems.
- Food & Beverage:Temperature-controlled sortation with stainless-steel construction addresses hygiene protocols in dairy and fresh produce segments.
- Pharmaceuticals:Track-and-trace compliance with serialization mandates shapes validation requirements for European medicinal product distribution.
E-commerce commands the steepest expansion trajectory. Retail maintains the broadest installed base across national markets.
Technology:
Identification modality selection hinges on read accuracy requirements, package surface variability, and integration complexity with upstream systems.
- Barcode Scanning:Laser and camera-based readers capture 1D and 2D symbologies at conveyor speeds up to 3 meters per second. Polish and Spanish parcel hubs standardize on multi-sided scanning tunnels to maximize read rates on damaged labels.
- RFID Technology:UHF tag interrogation enables bulk reading without line-of-sight constraints. German automotive parts distributors and French luxury goods fulfillment centers deploy RFID for high-value inventory authentication.
- Optical Recognition:Machine vision systems with dimensional weighing capture package geometry for volumetric pricing and load optimization.
- Automated Controls:PLC and IPC-based routing algorithms with digital twin integration enable real-time throughput optimization across German and Austrian software architectures.
Barcode scanning retains dominant share. RFID is climbing the fastest among identification technologies.
Installation:
Deployment modality reflects facility lifecycle stage, capital availability, and operational continuity requirements across European logistics real estate.
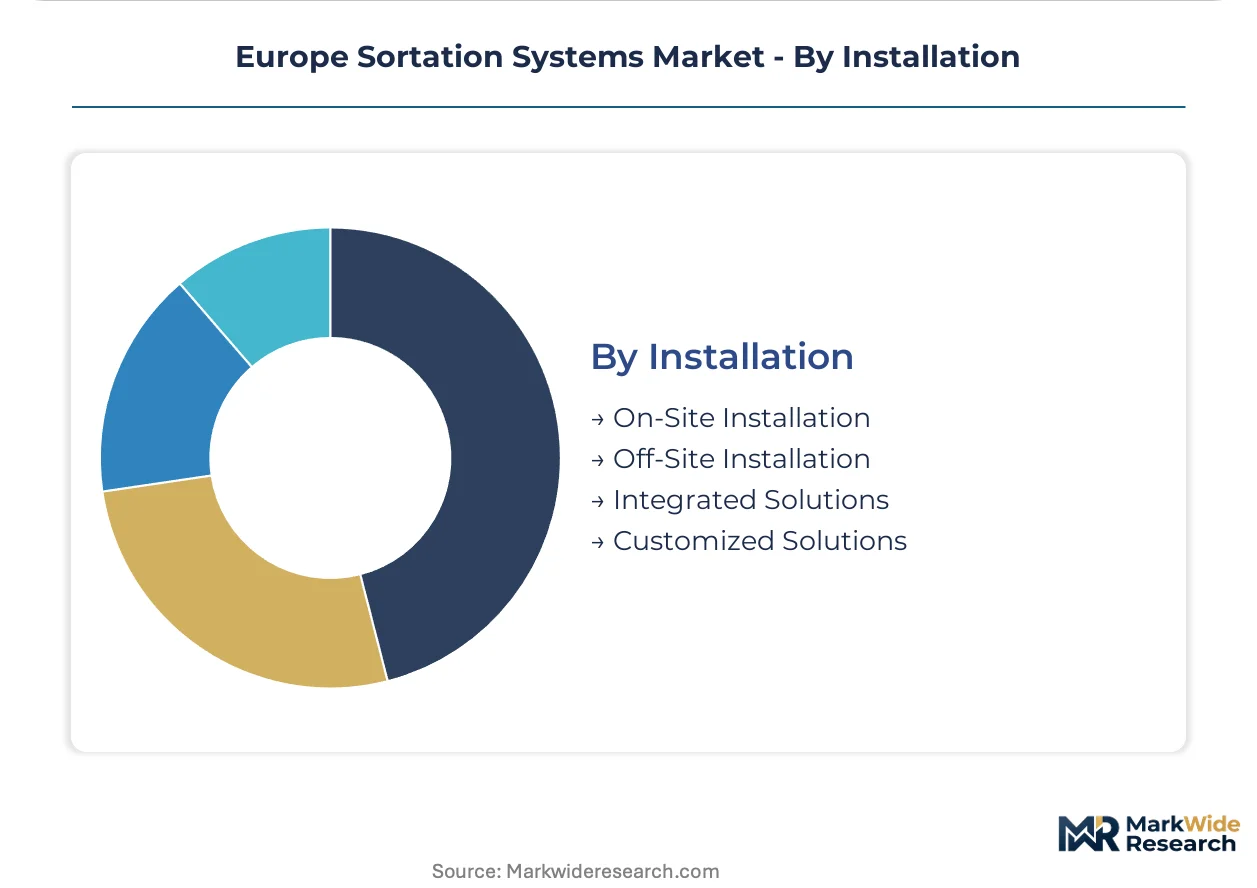
- On-Site Installation:Greenfield and brownfield construction projects in Germany's Rhine-Ruhr corridor and Netherlands distribution parks integrate sortation systems during facility buildout. General contractors coordinate mechatronic installation with building envelope completion.
- Integrated Solutions:Turnkey contracts bundling mechanical, electrical, and software commissioning reduce vendor fragmentation. French and Belgian logistics operators favor single-source accountability for performance guarantees.
- Customized Solutions:Retrofit configurations adapting to legacy building constraints serve urban infill distribution centers in London and Paris with restricted ceiling heights.
- Off-Site Installation:Prefabricated modular systems assembled in factory conditions reduce on-site commissioning time for Polish and Czech greenfield developments.
On-site installation holds installed capacity. Integrated solutions are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Rhine-Ruhr corridor while French and Polish operators negotiate from positions of capital constraint. This asymmetry shapes deployment timelines and specification intensity across continental logistics networks.
Germany
E-commerce fulfillment networks and postal modernization drive capital deployment in North Rhine-Westphalia and Bavaria. KBA technician certification requirements and EU Green Deal carbon accounting frameworks mandate energy-efficient retrofits. The Rhine-Ruhr logistics corridor hosts major distribution hub modernizations where Daifuku and Vanderlande Industries sustain deep installed bases.
France
Fashion retail platforms and grocery omnichannel networks accelerate automated handling specifications in Île-de-France. ANSM pharmaceutical serialization mandates and national energy efficiency regulations steer procurement toward stainless-steel, hygienic configurations. Parisian distribution clusters concentrate demand for high-throughput systems processing variable package dimensions.
Netherlands
Port-centric logistics and temperature-controlled food distribution shape automation priorities in the Randstad region. REACH compliance timelines for lubricants and coatings accelerate bio-synthetic fluid adoption in dairy and fresh produce segments. Rotterdam-Antwerp corridor facilities deploy regenerative-drive systems to satisfy EU Green Deal decarbonization targets.
Poland
Underpenetrated e-commerce infrastructure between Warsaw and Łódź offers greenfield positioning for parcel hub operators. CE marking harmonization reduces cross-border certification costs for vendors deploying from Western European bases. Polish logistics corridor expansion attracts systems integrators seeking first-mover positioning in Central European fulfillment networks.
Belgium
Benelux distribution gateway functions and pharmaceutical logistics clusters drive specification complexity in Flanders and Wallonia. ECHA substance restrictions on coatings and electronic components extend supplier qualification cycles. Belgian retail conglomerates prioritize warehouse management system interoperability in omnichannel distribution center deployments.
Europe Sortation Systems Market Competitive Landscape
Pan-European integrators and regional specialists split the market along lines of project scale and service intensity. Consolidation pressures concentrate among mid-tier vendors facing buyer concentration from Amazon and Zalando procurement teams. Two archetypes dominate: heritage mechanical engineering houses with deep installed bases, and software-native entrants offering outcome-based throughput guarantees. Competitive moves center on M&A for geographic coverage and strategic partnerships for AI-driven routing capabilities.
Within the heritage engineering tier, Daifuku Co., Ltd. and Vanderlande Industries occupy positions anchored by long-term service contracts and airport baggage expertise. TGW Systems GmbH exemplifies the specialization archetype, with its Austrian base supporting concentrated R&D in high-throughput grocery and fashion configurations. These three entities represent distinct competitive vectors: Japanese conglomerate scale, Dutch airport-to-parcel diversification, and Austrian vertical focus on retail velocity requirements.
| Leading Market Players |
|---|
| Daifuku |
| Vanderlande Industries |
| TGW Systems |
| KNAPP AG |
| Beumer Group |
| Interroll Holding AG |
| Viastore Systems GmbH |
| Fives Group |
| Dematic |
| Others |
Supply & Pricing Matrix
Germany's Rhine-Ruhr logistics corridor concentrates high-throughput sortation capacity, and this geographic density grants incumbent systems integrators substantial pricing leverage over downstream e-commerce operators facing delivery velocity mandates. Buyers in Poland and Spain negotiate from positions of capital constraint, compressing project margins for vendors bidding on fixed-price brownfield retrofits. Steel and rare-earth magnet cost volatility feeds directly into equipment quotations, forcing integrators to index major component costs or absorb margin erosion.
Pricing Analysis
The customization-premium spread separates configured-to-order cross-belt installations from standard conveyor architectures by 40-60 percent on a per-meter basis. Project-based pricing dominates, with after-sales service bundling and performance-based uptime guarantees commanding premium positioning over pure hardware transfers. Price differentiation rests on CE marking tier and software integration complexity. Cost compression in mid-tier semi-automated configurations is intensifying because AMR-based alternatives threaten fixed-conveyor economics in facilities under 50,000 square meters. Polish logistics operators exhibit highest price sensitivity; German postal and French luxury fulfillment centers prioritize throughput guarantees over capital expenditure minimization.
Supply Chain Analysis
Upstream feedstock for drive motors and conveyor assemblies draws from China, Germany, and Japan, with rare-earth magnet processing concentrated in Chinese refining operations. Control software architectures rest on German and Austrian automation vendors, creating single-source vulnerability for predictive routing algorithms. Steel sheet and precision bearing supply chains face tariff exposure from trade policy shifts affecting EU-China industrial equipment flows. Distribution runs through systems integrators offering turnkey commissioning, though direct procurement by Amazon and Zalando procurement teams is disintermediating traditional channel structures in the Rhine-Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sortation systems increasingly monetize through recurring revenue layers, with digital twin subscriptions and predictive maintenance modules expanding faster than mechanical hardware replacement cycles. This service-attach dynamic repositions vendor economics toward lifetime customer value rather than project-based margin capture.
For Market Incumbents: Pre-empt AMR substitution threats by embedding modular retrofit capabilities into legacy installed bases, allowing brownfield sites to upgrade controller intelligence without full mechanical replacement. Capture vertical integration into regenerative drive technologies to defend margin position against steel and magnet cost volatility. CE marking pre-certification for AI-driven routing algorithms creates defensive moats before EU AI Act enforcement timelines reshape procurement specifications.
For New Entrants and Emerging Players: Establish a beachhead in Poland's Warsaw-Łódź logistics corridor, where underpenetrated e-commerce infrastructure offers greenfield positioning without incumbent service contract entrenchment. Target pharmaceutical and electronics fulfillment segments requiring REACH-compliant gentle handling configurations, as these verticals command pricing premiums and exhibit lower price elasticity than fashion retail. Lead with outcome-based throughput guarantees rather than capital equipment sales to bypass buyer capital constraint objections.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-native entrants with AI-driven routing capabilities over pure mechanical engineering heritage, as regenerative power recovery and machine vision integration reshape competitive boundaries. Long-term viability favors vendors controlling both hardware commissioning and aftermarket digital service layers. The signal to watch is consolidation pressure among mid-tier Austrian and German automation software vendors, as buyer concentration from pan-European e-commerce platforms compresses vendor negotiation cycles and rewards scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regenerative Drive Manufacturing | Captures margin from rare-earth magnet cost volatility affecting German and Dutch installations. |
| Digital Twin Platform Launch | Creates recurring revenue streams beyond hardware installation for Rhine-Ruhr corridor operators. |
| CE Marking Pre-Certification for AI Control Modules | Secures compliance runway before EU AI Act risk classification deadlines reshape R&D priorities. |
| Joint Venture with Polish Systems Integrator | Accelerates first-mover positioning in Warsaw-Łódź greenfield developments without full capital commitment. |
| Long-Term Service Contract Restructuring | Defends against disintermediation by outcome-based procurement teams at Amazon and Zalando. |
Research Methodology
A spread of perspectives from logistics operators, systems integrators, mechatronics technicians, and warehouse control software architects converged on the working assumptions shaping this analysis. Primary interviews with maintenance directors at German distribution hubs, procurement leads at French e-commerce platforms, and aftermarket service heads at Austrian automation vendors were cross-referenced against secondary validation from EU Machinery Directive filings, ECHA REACH substance databases, KBA technician vacancy reports, and customs trade data on industrial equipment imports. Bottom-up project pipeline assessments and top-down capital expenditure forecasts were triangulated to establish demand boundaries.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with capacity utilization rates at Rhine-Ruhr distribution clusters and technician scarcity metrics informing supply-side constraints. Segmentation dimensions modeled include product type tier, end-use vertical, identification technology modality, and installation configuration. CAGRs were derived from installation volume trajectories and replacement cycle intervals observed in postal and e-commerce fulfillment networks. Forecast inputs incorporated EU Green Deal carbon accounting compliance timelines and ANSM pharmaceutical serialization mandates.
Stress conditions across steel and rare-earth magnet price bands, AMR substitution penetration rates, and EU AI Act enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding labor scarcity persistence and e-commerce delivery velocity commitments. Cross-checking against EIT Climate-KIC decarbonization investment flows and Eurostat industrial production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Geosteering Technology Market