
 South Korea Factory Automation and Industrial Controls Market | 2026-2036
South Korea Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Factory Automation and Industrial Controls Market Analytics
Software-defined maintenance subscriptions is shifting how Korean automation vendors monetize hardware deployments. LS Electric leverages its domestic distribution network to anchor service revenue across power and control systems. Hanwha Robotics competes through specialized collaborative robot platforms designed for electronics assembly floors. Siemens AG extends its digital twin software footprint into Korean automotive tier-one suppliers.
Factory automation and industrial controls encompass electromechanical systems, programmable logic devices, sensor networks, and supervisory software that orchestrate manufacturing processes with millisecond-level precision and ISO-defined reliability classes. These systems enable mass-customization, defect reduction, and continuous throughput in high-volume production environments. Controllers and sensors capture dominant margin pools as semiconductor fabs and battery plants demand higher I/O density and real-time edge processing. Industrial IoT and robotics segments show fastest expansion as 5G-integrated shop floors replace legacy wired architectures. PLCs and SCADA retain stable replacement cycles across mature automotive stamping and welding lines.
MFDS equipment safety certification, KOSHA occupational health mandates, and KTL electromagnetic compatibility standards collectively shape product design thresholds and market entry requirements for foreign and domestic suppliers alike. The Korea Agency for Technology and Standards enforces GB-aligned interoperability protocols that influence procurement specifications at chaebol-led manufacturing groups. Stakeholders must monitor how Korea's carbon-neutral industrial roadmap rewrites energy-efficiency benchmarks for motor drives and power distribution components.
Market Dynamics
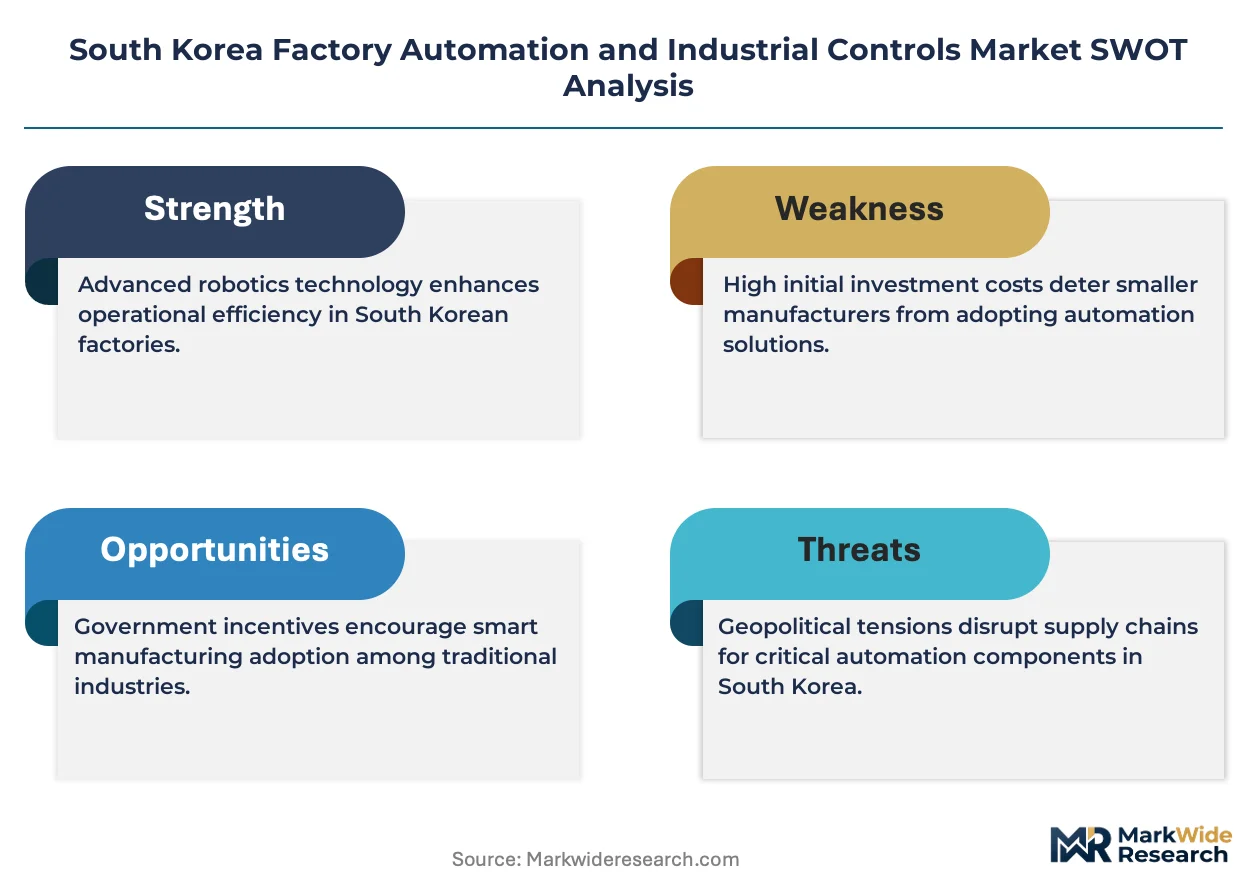
Process automation upgrades now dominate capital allocation in South Korean semiconductor fabrication facilities, compressing replacement cycles for legacy electromechanical systems while MFDS safety certification and KOSHA industrial standards reshape vendor qualification requirements.
Growth Catalysts
- Electronics Assembly Automation:Collaborative robotics deployment accelerates under MFDS safety guidelines as Gyeonggi Province manufacturers retool surface-mount technology lines for higher-mix production.
- MFDS Equipment Certification:Mandatory safety validation for programmable machinery creates predictable procurement pipelines for certified control system suppliers serving domestic battery cell plants.
- Semiconductor Fab Expansion:Pyeongtaek and Hwaseong process nodes drive demand for high-I/O density controllers with real-time edge processing capabilities.
Market Restraints
- Controller Hardware Import Dependence:High-performance industrial processors and precision motion encoders concentrate in Taiwanese and German supply chains, exposing Korean integrators to lead-time volatility.
- KTL Electromagnetic Compatibility Testing:Multi-stage certification timelines for factory networking equipment delay 5G-integrated shop floor deployments by six to nine months.
- Legacy System Interoperability:Proprietary fieldbus protocols in mature automotive stamping lines resist migration to Ethernet-based architectures without complete controller replacement.
Strategic Opportunities
- Carbon-Neutral Industrial Roadmap:Korea's 2050 net-zero mandate rewrites energy-efficiency benchmarks for motor drives and power distribution components, creating replacement demand in heavy manufacturing.
- Software-Defined Maintenance Subscriptions:Korean automation vendors monetize hardware deployments through recurring service revenue anchored by domestic distribution networks.
- 5G-Integrated Shop Floors:Wireless sensor networks displace legacy wired architectures in electronics assembly, enabling millisecond-level synchronization across distributed robotic cells.
Industry Challenges
- Embedded Systems Engineering Talent:Scarce expertise in real-time operating systems and safety-critical firmware development constrains domestic controller design capabilities.
- Multi-Standard Compliance Burden:Simultaneous adherence to KOSHA occupational health mandates, KTL electromagnetic compatibility standards, and Korea Agency for Technology and Standards interoperability protocols extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Factory Automation and Industrial Controls Market |
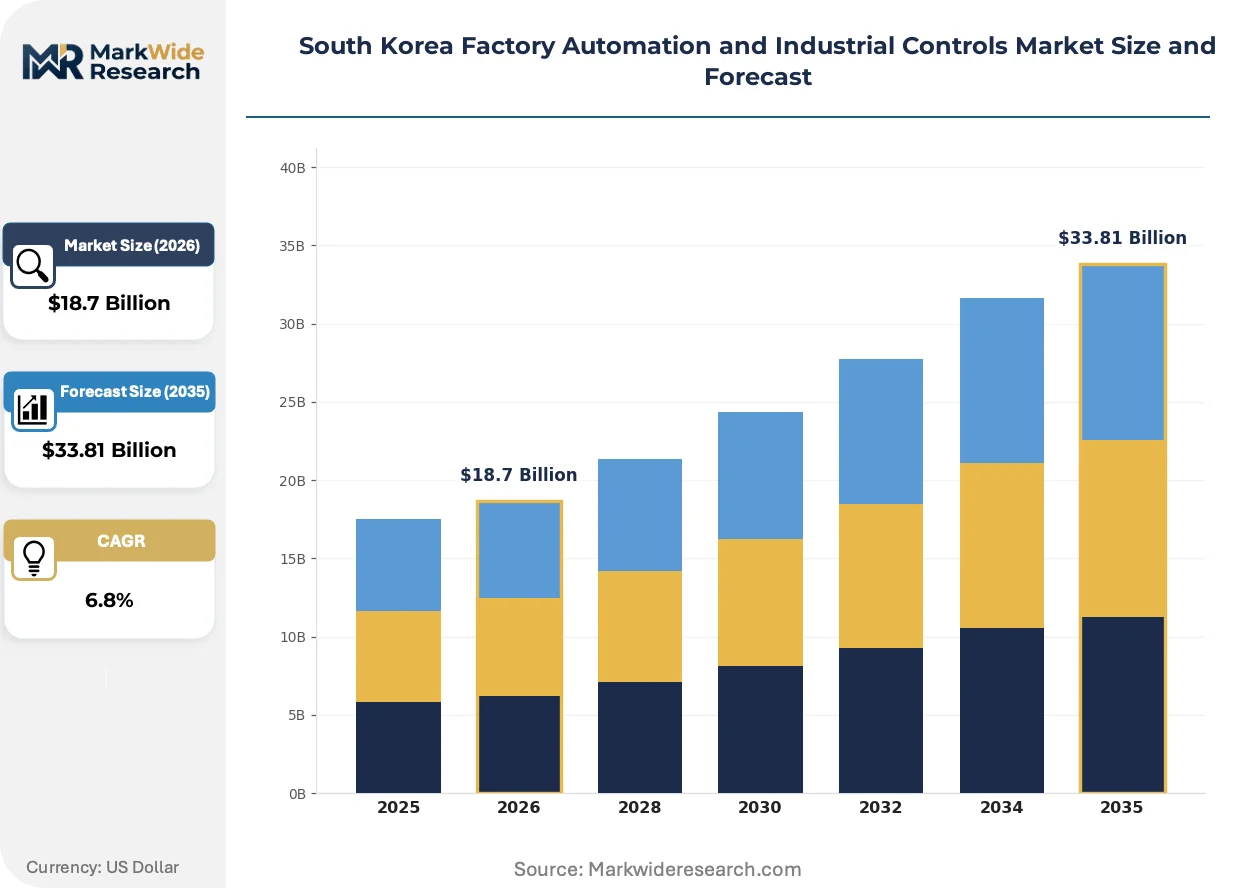
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Actuators, Sensors, Human-Machine Interfaces Technology: Industrial IoT, Robotics, PLCs, SCADA End User: Manufacturing, Electronics, Automotive, Food & Beverage Application: Assembly Lines, Quality Control, Process Automation, Material Handling |
| Companies Covered | LS Electric, Hanwha Robotics, Hyundai Robotics, ABB Ltd, Siemens AG, Mitsubishi Electric Corporation, Rockwell Automation Inc, Schneider Electric SE, Yokogawa Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Factory Automation and Industrial Controls Market Evolving Landscape
Digital twin software architectures are penetrating Korean automotive tier-one suppliers, compressing commissioning cycles for new production lines while edge computing nodes displace centralized SCADA for latency-critical process control.
Edge AI inference engines are converging with programmable logic controllers in semiconductor fabrication facilities, enabling defect detection at sub-millisecond response times without cloud dependency. Samsung Electronics and SK Hynix are piloting these architectures in Pyeongtaek memory wafer plants. This convergence is compressing the traditional separation between OT and IT infrastructure layers.
KOSHA's 2024 revision of collaborative robot safety protocols mandates force-limiting verification and workspace monitoring systems for human-robot interaction zones. Electronics manufacturers in Suwon and Ansan must retrofit existing installations or face operational suspension. Battery assembly plants show fastest compliance adaptation due to higher injury risk premiums.
Buyers now unbundle hardware procurement from lifecycle service contracts, forcing Korean distributors to compete on transparent software subscription pricing rather than bundled maintenance margins. This pattern concentrates in automotive stamping and welding lines where chaebol procurement offices exercise centralized vendor management. Secondary machinery dealers in Incheon and Busan report compressed equipment residual values as subscription models displace traditional capital purchase structures.
South Korea Factory Automation and Industrial Controls Market Segmentation
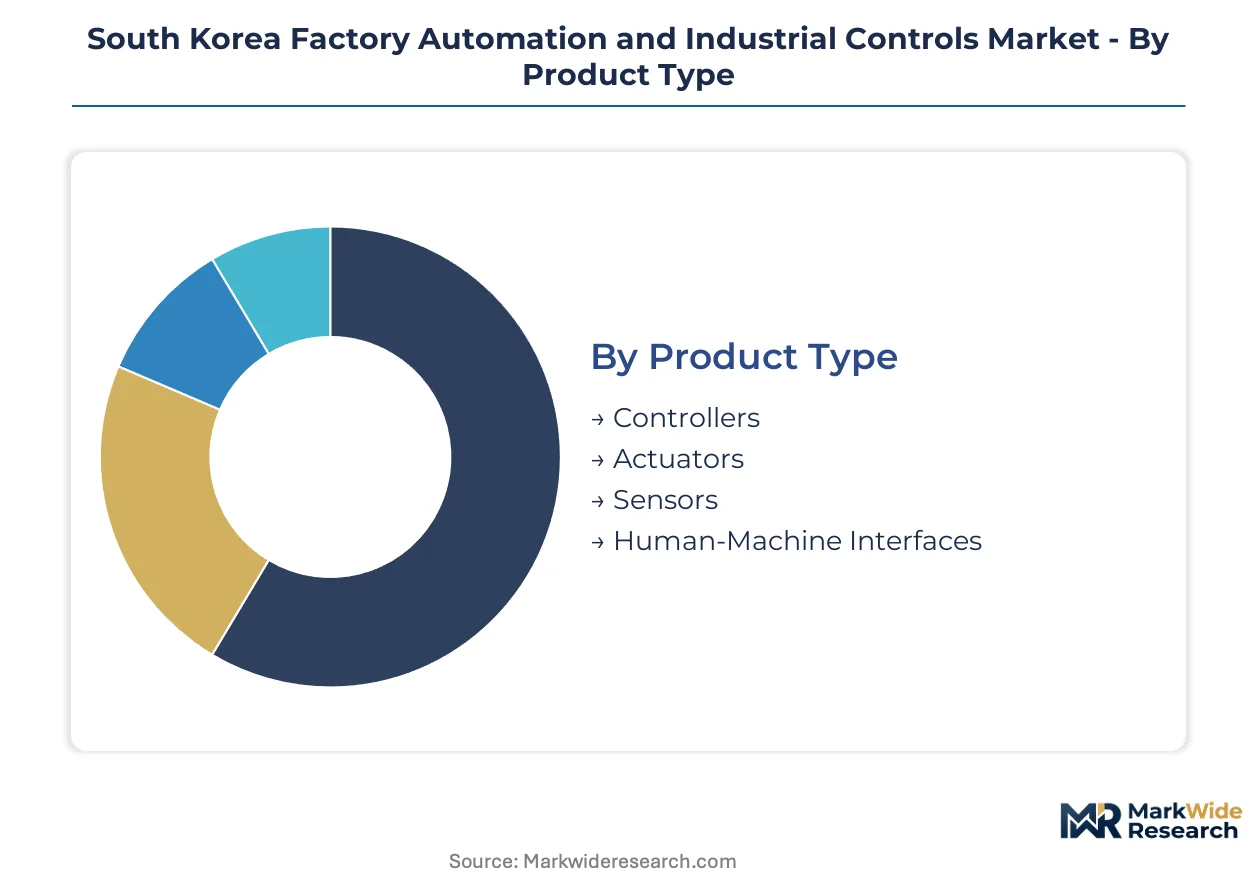
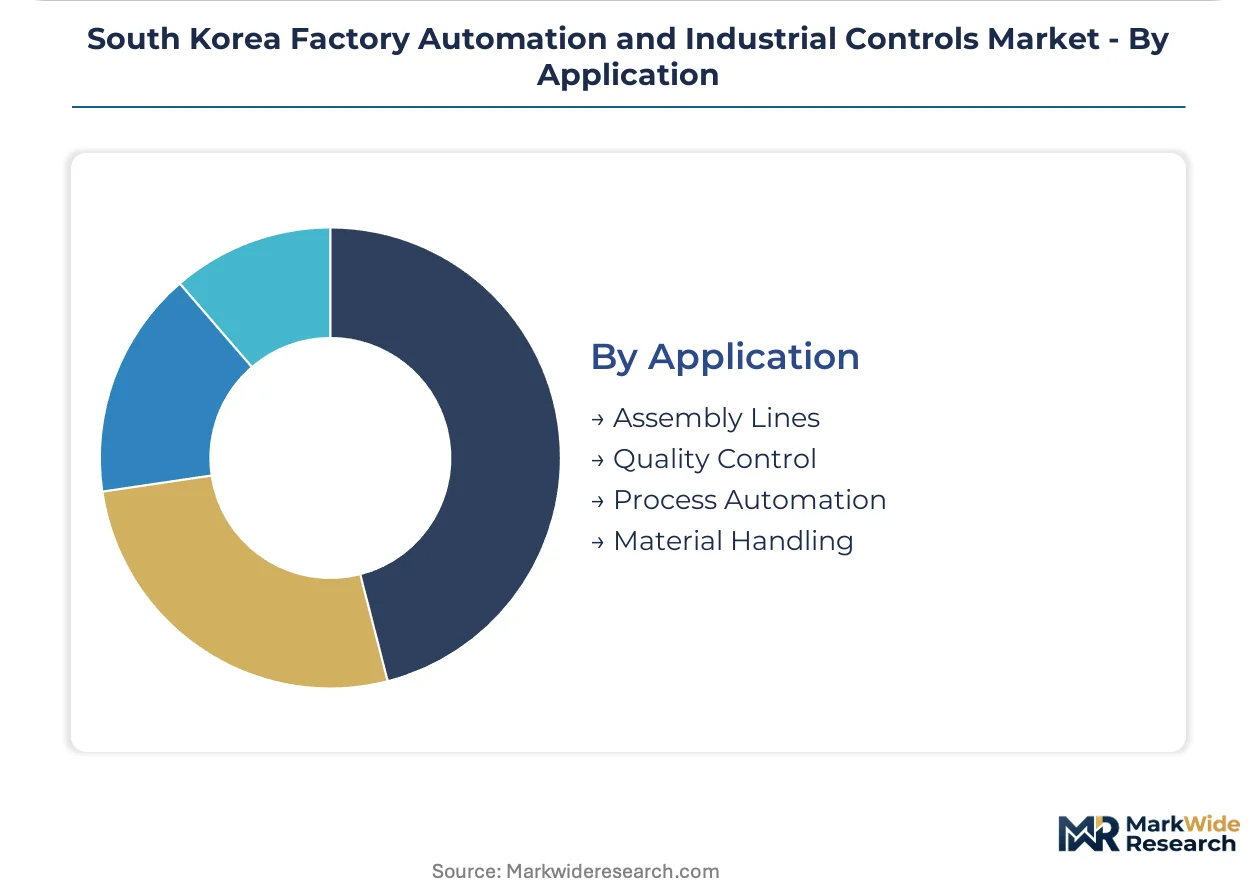
Segmentation in South Korean factory automation reveals how capital allocation splits between semiconductor-driven precision demands and automotive legacy system replacement. Product type and technology choices reflect divergent procurement priorities across Gyeonggi electronics clusters versus mature Busan manufacturing corridors.
Product Type:
Volume shipments concentrate in sensor arrays and compact controllers, while premium margin pools sit with precision actuators and integrated HMI platforms.
- Controllers:Programmable logic devices and motion control units with real-time deterministic processing anchor semiconductor fab automation in Pyeongtaek. Samsung Electronics and SK Hynix procurement specifications demand sub-millisecond I/O response for wafer handling robotics.
- Sensors:Vision systems, proximity detectors, and force-torque transducers enable defect detection at micron-level resolution. Gyeonggi Province surface-mount technology lines drive replacement cycles as manufacturers retool for higher-mix electronics production.
- Actuators:Servo motors and linear positioning systems with IP67 sealing for cleanroom environments.
- Human-Machine Interfaces:Touch panels and industrial PCs with KTL electromagnetic compatibility certification.
Mature deployment sits with standalone controllers in automotive stamping lines. Newer deployment is concentrated in sensor-integrated collaborative robotics under revised KOSHA safety protocols.
Technology:
Application maturity separates established SCADA architectures from emerging Industrial IoT stacks, with robotics platforms bridging both generations.
- Industrial IoT:Wireless sensor networks and edge computing nodes with 5G-integrated shop floor synchronization displace legacy wired fieldbus in Suwon electronics plants. MFDS equipment safety certification mandates shape gateway hardware specifications.
- Robotics:Collaborative robot platforms with force-limiting verification and workspace monitoring dominate battery assembly plant retrofits. Hanwha Robotics and domestic integrators compete on MFDS-compliant human-robot interaction zones.
- PLCs:Compact modular controllers with Ethernet-based communication replacing proprietary protocols.
- SCADA:Centralized supervisory systems retaining stable replacement demand in heavy manufacturing.
Procurement patterns favor Industrial IoT in greenfield semiconductor facilities, while PLC replacement cycles sustain revenue in mature Hwaseong automotive tier-one supplier networks.
End User:
Electronics manufacturers command premium pricing for contamination-resistant components, whereas food and beverage buyers prioritize washdown-rated actuators at standard margins.
- Electronics:Semiconductor fabrication and surface-mount technology lines in Pyeongtaek and Hwaseong demand ISO Class 1-3 cleanroom compatibility. Process node shrinkage drives continuous controller upgrade cycles as lithography precision requirements tighten.
- Automotive:Stamping, welding, and powertrain assembly lines in Ulsan and Asan balance legacy system maintenance against digital twin pilot programs. Tier-one suppliers trial Siemens AG software architectures for commissioning compression.
- Manufacturing:General industrial machinery and metal fabrication in Busan and Incheon.
- Food & Beverage:Packaging and processing lines requiring IP69K-rated components.
Electronics end users show steepest expansion trajectory for collaborative robotics, while automotive procurement concentrates on software-defined maintenance subscriptions.
Application:
Process automation captures the dominant capital allocation share, with quality control systems gaining share fastest as edge AI inference penetrates wafer inspection.
- Process Automation:Continuous flow control and batch processing systems with real-time edge processing dominate battery cell plant investments. Korea's carbon-neutral industrial roadmap rewrites energy-efficiency benchmarks for motor drive retrofits.
- Quality Control:Machine vision and dimensional inspection with sub-millisecond defect response times converge programmable logic with AI inference engines. Samsung Electronics pilots these architectures in memory wafer plants.
- Assembly Lines:Discrete manufacturing synchronization for electronics and automotive component fitting.
- Material Handling:Automated guided vehicles and conveyor systems with 5G positioning.
Process automation retains the largest installed base across heavy manufacturing. Quality control applications expand most quickly as semiconductor yield management tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea produces more factory automation equipment than it consumes, with Gyeonggi Province fabs exporting precision controllers while domestic battery plants import German motion systems. This production-consumption asymmetry shapes regional investment flows across the peninsula.
Seoul Capital Area
Semiconductor equipment demand concentrates in Pyeongtaek and Hwaseong, where Samsung Electronics and SK Hynix procurement specifications drive sub-millisecond controller upgrades. MFDS equipment safety certification mandates reshape vendor qualification for collaborative robotics deployment. Suwon electronics corridors retrofit surface-mount technology lines under revised KOSHA 2024 safety protocols.
Busan-Ulsan
Automotive stamping and shipbuilding automation sustain PLC replacement cycles across mature manufacturing corridors. Korea Agency for Technology and Standards interoperability protocols influence procurement at Hyundai Motor Group tier-one suppliers. Ulsan heavy industrial zones balance legacy system maintenance against carbon-neutral motor drive retrofits.
Daegu-Gyeongbuk
Textile machinery and electronics component suppliers anchor mid-tier controller demand in this northeastern manufacturing belt. KTL electromagnetic compatibility testing requirements delay 5G-integrated shop floor deployments by six to nine months. Gumi industrial complexes show fastest adoption of software-defined maintenance subscriptions among secondary machinery operators.
Daejeon-Sejong
Government research institutes and defense contractors drive specialized automation procurement with stringent security requirements. Korea Institute of Industrial Technology standards influence specifications for domestic controller design capabilities. Sejong smart city pilot programs test edge AI inference engines for distributed manufacturing networks.
Gwangju-Honam
Food processing and agricultural equipment manufacturing generate steady demand for washdown-rated actuators and IP69K-certified components. Regional procurement prioritizes cost-efficient PLC architectures over premium collaborative robotics platforms. Suncheon Bay industrial zones attract battery material suppliers expanding beyond Gyeonggi Province capacity constraints.
South Korea Factory Automation and Industrial Controls Market Competitive Landscape
Top-tier vendors anchor premium controller and robotics segments, while mid-tier domestic integrators compete on MFDS certification speed and localized service networks. The vendor base splits between multinational automation conglomerates with digital twin software portfolios and Korean specialists leveraging domestic distribution density. Two strategic archetypes dominate: semiconductor-focused precision system suppliers and automotive-anchored maintenance service providers. Competitive moves concentrate on software subscription bundling and 5G-integrated shop floor partnerships.
Within the domestic specialist tier, LS Electric and Hanwha Robotics exemplify contrasting positioning archetypes. LS Electric leverages its nationwide distribution infrastructure to anchor recurring service revenue across power and control system deployments. Hanwha Robotics occupies a position representing MFDS-compliant collaborative platform specialization for electronics assembly environments. Among multinational participants, Siemens AG sits within the digital twin software tier extending architectures into Korean automotive supplier networks.
| Leading Market Players |
|---|
| LS Electric |
| Hanwha Robotics |
| Hyundai Robotics |
| ABB Ltd |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Rockwell Automation Inc |
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap integrators anchor South Korea's automation supply base, channeling procurement discipline through long-standing relationships with chaebol manufacturing groups while compressing margin pools for foreign component suppliers. This ownership pattern concentrates pricing power among domestic distributors who bundle hardware with mandatory MFDS certification services.
Pricing Analysis
Cost-down pressure on precision motion controllers accelerates because semiconductor fabs demand sub-millisecond I/O response at volume scale. Pricing stratifies across MFDS-certified premium tiers, KTL-compliant standard tiers, and uncertified economy imports. Price differentiation rests on certification grade and after-sales service bundling. Battery assembly plants show highest price sensitivity due to thin cell margins, while semiconductor equipment buyers prioritize performance over unit cost.
Supply Chain Analysis
Freight cost volatility from Taiwanese and German component sources compresses margin buffers for Korean system integrators serving Pyeongtaek fab expansions. High-performance industrial processors and precision encoders draw from Taiwan, Germany, and Japan. Raw material dependencies span rare-earth magnets, silicon carbide substrates, and high-purity aluminum housings. Single-source vulnerability concentrates in Taiwanese foundry capacity for motion control ASICs. Distribution runs through LS Electric's nationwide service network and specialized robotics integrators in Gyeonggi Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's factory automation market functions as a cost-of-compliance story where MFDS equipment safety certification erects formidable barriers to entry, rewarding incumbent vendors with recurring service revenue streams and locking out uncertified competitors.
For Market Incumbents: Hedge against controller hardware import dependence by deepening captive supply relationships with Taiwanese semiconductor foundries or qualifying secondary German motion encoder sources. Accelerate software-defined maintenance subscription penetration across automotive tier-one suppliers before chaebol procurement offices consolidate vendor panels. MFDS certification speed remains the critical defensive lever against emerging domestic challengers. For New Entrants and Emerging Players: Secondary machinery operators in Daegu-Gyeongbuk textile corridors represent an underserved buyer archetype with compressed service coverage from major distributors. Battery material suppliers expanding into Suncheon Bay industrial zones offer fastest penetration potential given capacity constraints in Gyeonggi Province. A go-to-market angle anchored on rapid KTL electromagnetic compatibility testing completion differentiates against incumbent certification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-capable mid-tier integrators in Busan-Ulsan automotive corridors facing legacy system replacement pressures. Long-term viability hinges on carbon-neutral industrial roadmap compliance capabilities and 5G-integrated shop floor deployment expertise. Watch for inflection signals in chaebol procurement office centralization patterns that consolidate vendor relationships toward fewer certified partners.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Acceleration | Compresses vendor qualification timelines for battery cell plant deployments under KOSHA mandates. |
| Software-Defined Maintenance Platform | Enables recurring revenue capture from Hanwha Robotics and LS Electric hardware installations. |
| 5G-Integrated Shop Floor Partnership | Displaces legacy wired architectures in Samsung Electronics and SK Hynix surface-mount lines. |
| Carbon-Neutral Motor Drive Retrofit | Aligns with Korea Agency for Technology and Standards energy-efficiency benchmarks for heavy manufacturing. |
| Edge AI Inference Integration | Converges programmable logic with defect detection in Pyeongtaek memory wafer plants. |
Research Methodology
Trade association filings, Korea Agency for Technology and Standards certification databases, and semiconductor equipment customs records formed the secondary backbone, cross-referenced against primary interviews with plant engineers at Samsung Electronics and SK Hynix, automation procurement leads at Hyundai Motor Group tier-one suppliers, and aftermarket service heads at LS Electric distribution partners. Bottom-up equipment shipment tallies and top-down manufacturing capex allocations were triangulated to anchor market sizing.
Historical trendline analysis of controller replacement cycles, robotics deployment rates, and software subscription adoption informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user industry, and regional manufacturing cluster. CAGRs were derived from equipment procurement pipeline analysis and capital allocation surveys. Industry-specific forecast inputs encompassed MFDS certification queue lengths and 5G network rollout timelines in Gyeonggi Province electronics corridors.
Revisions become necessary when KOSHA safety protocol amendments, Taiwan semiconductor export restrictions, or chaebol procurement centralization initiatives materialize outside baseline assumptions. Forecasts reflect documented scenario parameters without claiming predictive certainty. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Agricultural Automation Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
HMI Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market