
 Industrial Robotic Motors Market | 2026-2036
Industrial Robotic Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Robotic Motors Market Intelligence
Direct supply contracts between motor manufacturers and robot OEMs are rewriting procurement pathways across the industrial automation sector. Nidec Corporation leverages its vertical manufacturing scale to dominate high-torque servo applications. Yaskawa Electric Corporation anchors demand through integrated motion control platforms. Maxon Motor AG specializes in precision brushless systems for collaborative robot joints.
Industrial robotic motors are electromechanical actuators that convert electrical energy into controlled mechanical motion, typically achieving positioning accuracy within 0.01 degrees through encoder feedback systems. These motors power articulated arms, gantry systems, and SCARA configurations across factory floors worldwide. Servo motors capture the largest value share due to closed-loop precision requirements in welding operations and quality inspection cells. Brushless DC variants represent the fastest-expanding product category as manufacturers eliminate commutator maintenance in continuous-duty packaging lines. Field oriented control technology commands premium positioning because it enables torque production at zero speed for material handling grippers.
IEC 60034 efficiency classes and NEMA MG1 standards dictate minimum performance thresholds for motors deployed in North American and European automation installations. China's GB standards and Japan's JIS certification requirements create parallel compliance pathways for suppliers serving Asia-Pacific robot builders. Stakeholders must monitor how regional efficiency mandates alter motor topology choices and thermal management specifications.
Market Dynamics
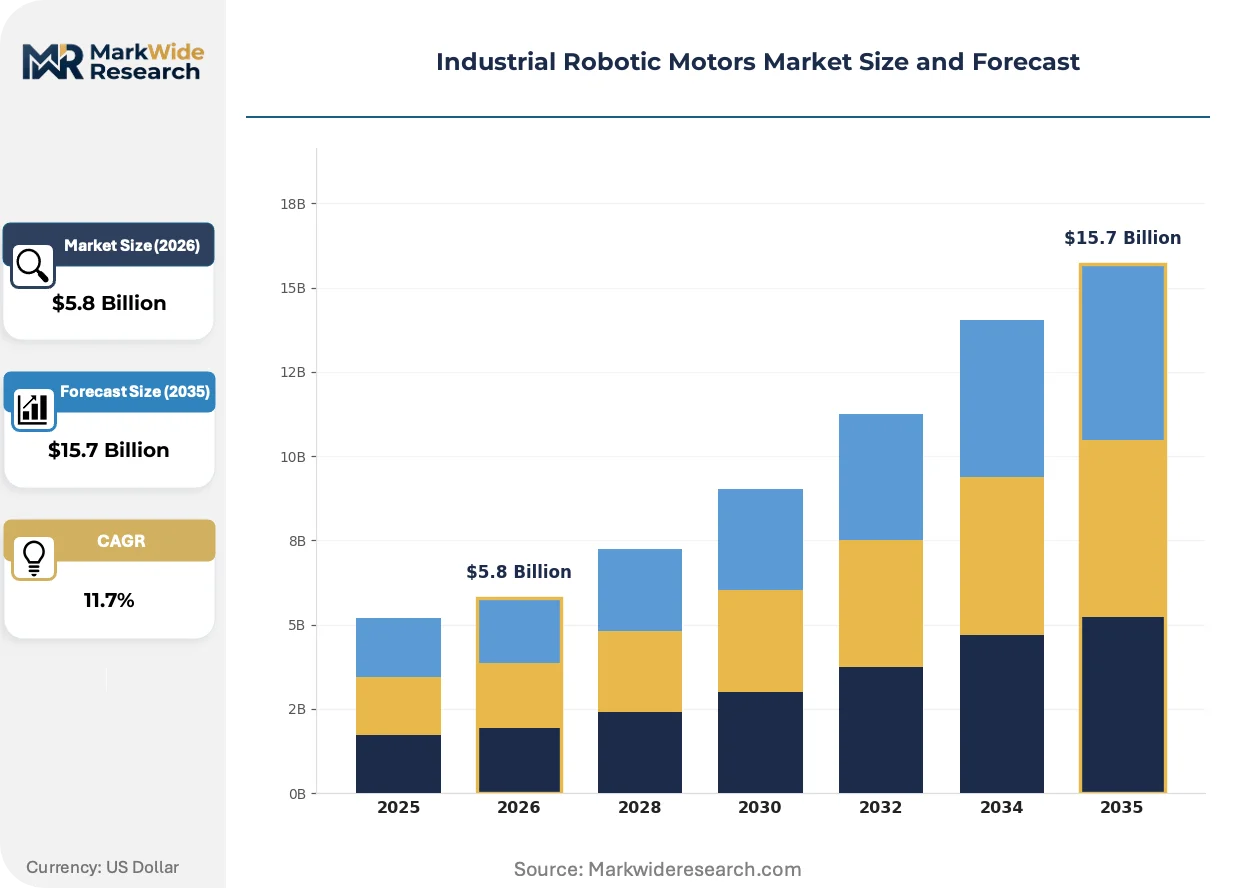
Direct supply contracts between motor manufacturers and robot OEMs are compressing traditional distribution layers, while IEC 60034 and NEMA MG1 efficiency mandates force redesigns of thermal management systems and winding topologies across production portfolios.
Growth Catalysts
- Automotive assembly automation:Battery electric vehicle production lines in Germany and China require high-torque servo motors for welding and precision fastening operations.
- IEC 60034-30-1 efficiency tiers:IE4 and IE5 classifications mandate premium motor designs, creating replacement cycles across European manufacturing bases.
- Collaborative robot proliferation:Force-limited joint actuators using frameless torque motors expand addressable applications in small-batch electronics assembly.
Market Restraints
- Rare earth magnet dependency:Neodymium supply concentration in Chinese processing facilities exposes motor costs to export quota volatility.
- NEMA MG1 retrofit friction:Legacy motor inventories in North American plants face stranded asset risk from updated efficiency minimums.
- Copper winding cost exposure:Commodity price swings for magnet wire directly compress gross margins on custom servo builds.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for industrial automation create greenfield motor procurement pipelines in Gujarat and Tamil Nadu.
- AI-driven predictive maintenance:Edge computing integration with servo drives enables condition-based service contracts displacing fixed-interval maintenance.
- Food-grade stainless enclosures:IP69K-rated washdown motors address unmet demand in meat processing and dairy packaging lines.
Industry Challenges
- Motion control engineering scarcity:Field-oriented control algorithm expertise concentrates among aging specialist workforces in Japan and Germany.
- Multi-axis synchronization complexity:EtherCAT and PROFINET integration timelines extend commissioning phases for gantry system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Robotic Motors Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.7 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servo Motors, Stepper Motors, DC Motors, AC Motors, Brushless Motors Technology: Encoder Technology, Resolver Technology, Sensorless Control, Field Oriented Control, Direct Torque Control Application: Material Handling, Assembly Automation, Packaging, Welding Operations, Quality Inspection End User Industry: Electronics Manufacturing, Aerospace Manufacturing, Food & Beverage Processing, Pharmaceutical Production, Textile Fabrication |
| Companies Covered | Nidec Corporation, Maxon Motor AG, Yaskawa Electric Corporation, Moog Inc., Schneider Electric, ElectroCraft Inc., Faulhaber Group, Oriental Motor Co., Ltd., Kollmorgen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Robotic Motors Market Strategic Shifts & Innovations
Digital twin technology is compressing motor validation cycles, while efficiency regulations and buyer consolidation reshape competitive requirements across the value chain.
Integrated servo-drive modules with embedded encoders are digitizing commissioning workflows for SCARA and delta robot installations. Automotive tier-one suppliers in Stuttgart and Shanghai are specifying these unified packages to reduce cabinet wiring complexity. The technology is digitizing supplier-customer technical interfaces, compressing weeks of integration into days of parameter upload.
EU F-Gas Regulation phase-down schedules are accelerating transitions to air-cooled servo architectures in European packaging machinery. Thermal design teams must now validate performance without hydrofluorocarbon-based refrigerants in continuous-duty cycles. German OEMs are responding with liquid-cooled frameless motors for high-torque density applications.
Robot OEMs are consolidating motor vendor lists from twelve suppliers to three approved partners per platform generation. This concentration forces component manufacturers to assume inventory risk and provide consignment stock at assembly plant locations. The pattern is most pronounced in Japanese and South Korean robotics manufacturing clusters where just-in-time discipline dominates procurement culture.
Industrial Robotic Motors Market Segmentation
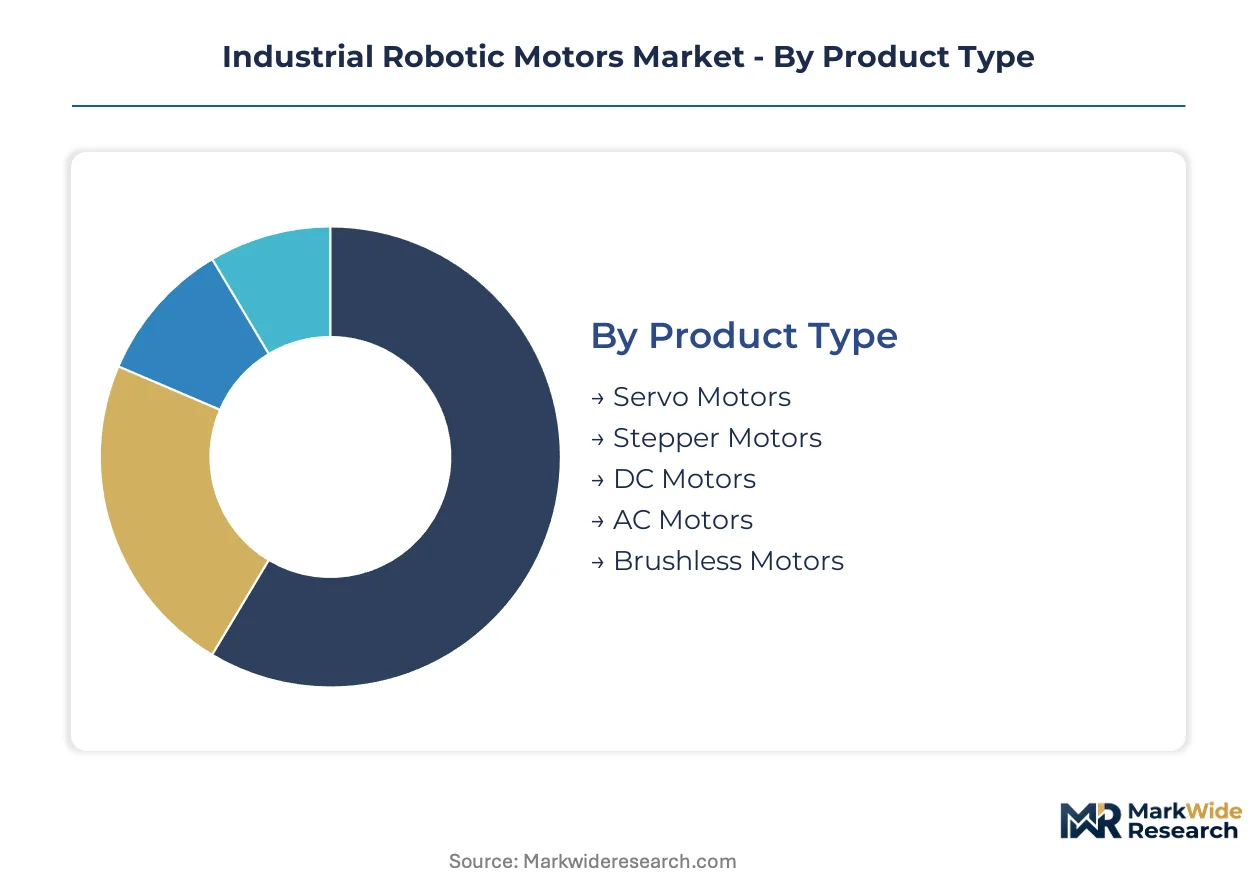
Motor specification varies sharply across robot architectures, with closed-loop precision requirements and duty cycle profiles dictating component selection. Segmentation clarity enables suppliers to align winding topologies and thermal management systems with distinct procurement patterns.
Product Type:
After-sales service intensity escalates with motor complexity, as servo systems demand encoder recalibration and bearing replacement programs that stepper units rarely require.
- Servo Motors:Closed-loop systems with encoder feedback achieve positioning accuracy within 0.01 degrees. Automotive battery assembly lines in Germany and China specify these for welding torque control, though rare earth magnet supply concentration creates cost volatility.
- Brushless Motors:Eliminating commutator maintenance reduces downtime in continuous-duty packaging operations. Food-grade stainless variants with IP69K enclosures are gaining traction in washdown environments where grease contamination risks exist.
- Stepper Motors:Open-loop positioning suffices for low-speed indexing applications with predictable load profiles.
- DC Motors:Brushed architectures persist in cost-sensitive Cartesian coordinate systems with intermittent duty cycles.
- AC Motors:Induction designs serve high-inertia gantry applications where vector control complexity is acceptable.
Servo motors hold the largest share; momentum sits with brushless architectures.
Technology:
Cost tier stratification separates premium field-oriented implementations from commodity sensorless alternatives, with resolver-based systems occupying mid-tier positioning in aerospace-qualified supply chains.
- Field Oriented Control:Vector algorithms enable torque production at zero speed for material handling grippers. IEC 60034-30-1 IE4 and IE5 efficiency mandates in European installations accelerate adoption, though algorithm expertise concentrates in aging specialist workforces across Japan and Germany.
- Encoder Technology:Optical and magnetic feedback devices deliver sub-arcminute positioning for SCARA and delta configurations. Integrated servo-drive modules with embedded encoders are compressing commissioning timelines from weeks to days in Stuttgart and Shanghai automotive plants.
- Direct Torque Control:Rapid torque response benefits high-dynamic pick-and-place operations without intermediate current loops.
- Resolver Technology:Rugged electromagnetic sensors withstand vibration in aerospace manufacturing environments.
- Sensorless Control:Eliminating physical feedback reduces bill-of-materials cost in volume-constrained collaborative robot joints.
Encoder-based systems dominate value capture; direct torque control is climbing the fastest.
Application:
Volume concentration in automotive assembly creates procurement scale that packaging and inspection segments cannot match, with welding operations demanding the highest torque density specifications.
- Assembly Automation:Multi-axis synchronization for precision fastening requires EtherCAT and PROFINET integration. Battery electric vehicle production lines specify high-torque servo motors, though commissioning timeline extensions for gantry deployments create project risk.
- Welding Operations:Arc and spot welding demand sustained torque at stall conditions with advanced thermal management. EU F-Gas Regulation phase-downs are accelerating transitions to liquid-cooled frameless architectures in German OEM portfolios.
- Material Handling:Palletizing and conveyor systems prioritize reliability over positioning precision.
- Packaging:Continuous-duty cycles favor brushless elimination of commutator maintenance.
- Quality Inspection:Vision-guided metrology depends on smooth velocity profiles for blur-free image capture.
Assembly automation holds the largest share; welding applications are expanding most quickly.
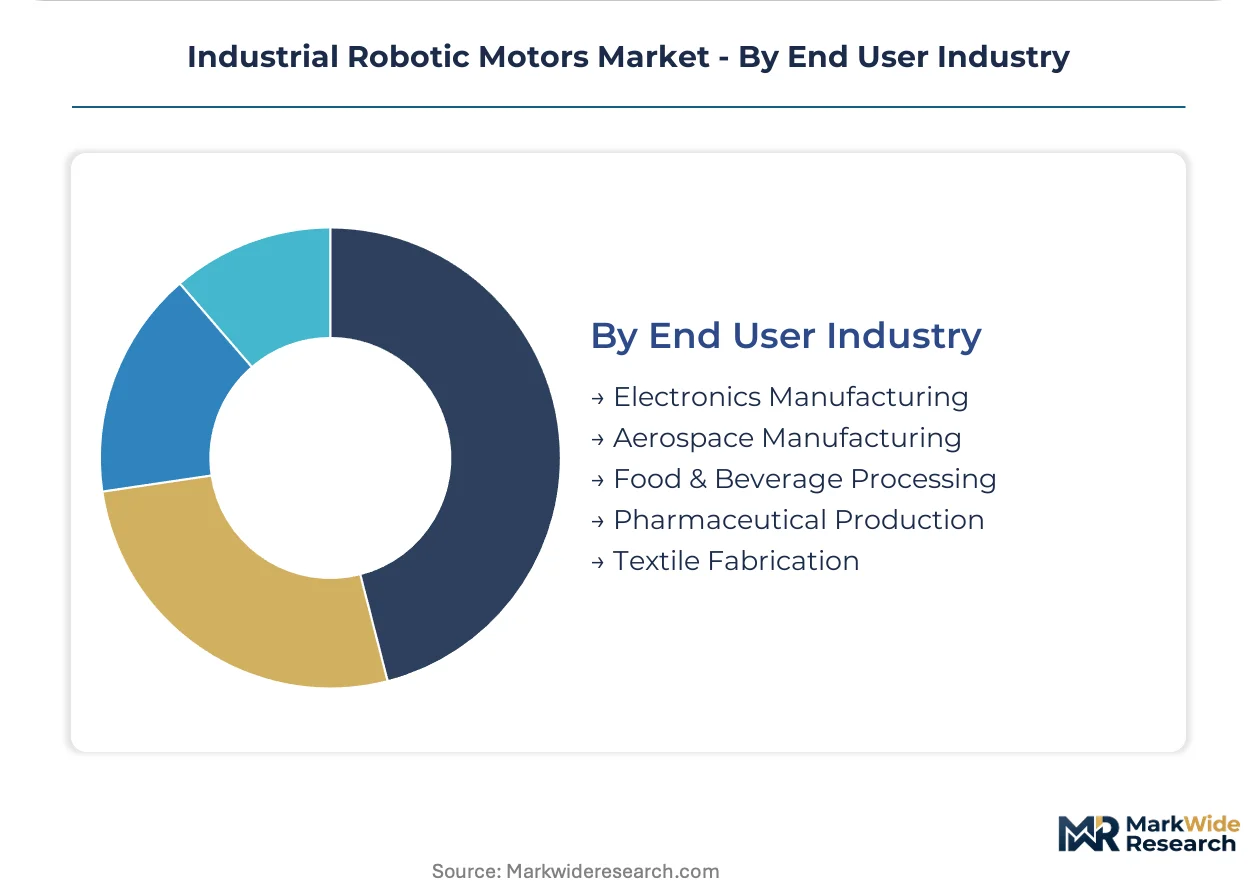
End User Industry:
Customer type differentiation separates aerospace qualification requirements from food-grade washdown standards, with electronics manufacturing driving the highest unit volumes through collaborative robot proliferation.
- Electronics Manufacturing:Small-batch assembly and force-limited collaborative joints require compact frameless torque motors. India's PLI scheme incentives for industrial automation are creating greenfield procurement pipelines in Gujarat and Tamil Nadu.
- Food & Beverage Processing:IP69K-rated stainless enclosures address unmet demand in meat processing and dairy packaging lines where caustic washdown protocols degrade standard motor finishes.
- Aerospace Manufacturing:Resolver-based feedback and extended temperature qualification dominate carbon fiber layup and drilling applications.
- Pharmaceutical Production:Cleanroom-compatible lubricants and sealed housings prevent particulate contamination.
- Textile Fabrication:High-speed spindle applications prioritize power density over positioning accuracy.
Electronics manufacturing holds the largest share; food and beverage processing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German and Japanese suppliers while Chinese manufacturers compete on volume. Motor procurement contracts in Stuttgart and Nagoya command 15-20% premiums over Shenzhen-equivalent specifications. This asymmetry reflects certification depth and motion-control engineering concentration.
China
Battery electric vehicle plants in Shanghai and Shenzhen drive high-torque servo procurement at scale. GB standards and MIIT efficiency mandates reshape domestic motor topology requirements. The Yangtze River Delta robotics cluster concentrates frameless torque motor production for collaborative robot exports.
Germany
Automotive welding automation in Stuttgart and Munich sustains demand for liquid-cooled servo architectures. EU F-Gas Regulation phase-downs accelerate transitions away from hydrofluorocarbon-based thermal management. Bavarian OEMs are consolidating vendor lists to three approved motor partners per platform generation.
Japan
Precision electronics assembly in Nagoya and Osaka requires force-limited joint actuators with sub-arcminute positioning. METI industrial policy and JIS certification standards maintain technical barriers for foreign suppliers. The Kanto region anchors integrated motion control platform development.
United States
Packaging machinery rebuilds in Chicago and Detroit face NEMA MG1 retrofit friction from legacy motor inventories. EPA and OSHA workplace safety regulations intersect with efficiency mandates in plant upgrade decisions. Midwest automotive tier-one suppliers are specifying integrated servo-drive modules to compress commissioning timelines.
India
Electronics manufacturing incentives in Gujarat and Tamil Nadu create greenfield motor procurement pipelines. PLI scheme subsidies for industrial automation attract robot OEM assembly operations. The Delhi-NCR corridor is emerging as a distribution hub for South Asian automation component flows.
Industrial Robotic Motors Market Key Industry Players
Vertically integrated conglomerates and specialized precision engineering houses split the market into distinct capability tiers. Consolidation pressure from robot OEM vendor list reductions favors scale players with captive magnet wire and lamination capacity. Two strategic archetypes dominate: Japanese-German integrated motion control platforms and Swiss-German precision brushless specialists. Competitive moves center on backward integration into rare earth magnet supply chains and consignment stock arrangements at just-in-time assembly plants.
Among Japanese electrical conglomerates, Nidec Corporation and Yaskawa Electric Corporation exemplify the integrated platform archetype, leveraging domestic supply chain density and motion control algorithm expertise. Maxon Motor AG represents the Swiss precision engineering tier, occupying a position defined by collaborative robot joint specialization and medical-grade quality systems. These three anchors illustrate how geographic clustering around regulatory certification and engineering labor pools creates defensible positioning.
| Leading Market Players |
|---|
| Nidec Corporation |
| Maxon Motor AG |
| Yaskawa Electric Corporation |
| Moog Inc. |
| Schneider Electric |
| ElectroCraft Inc. |
| Faulhaber Group |
| Oriental Motor Co., Ltd. |
| Kollmorgen Corporation |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta robotics cluster concentrates frameless torque motor production for collaborative robot exports, concentrating supply-side leverage among domestic Chinese suppliers and compressing margins for foreign competitors serving the same procurement pipelines.
Pricing Analysis
Configured-to-order servo systems command 25-40% premiums over standard catalog units, with pricing stratifying across premium, standard, and economy tiers driven by certification depth and encoder resolution specifications. IEC 60034-30-1 IE4 and IE5 compliance tiers extract further premiums in European installations. Pricing pressure stems from rare earth magnet cost volatility concentrated in Chinese processing facilities. Small-batch electronics manufacturers exhibit highest price sensitivity; automotive tier-one suppliers in Stuttgart and Shanghai demonstrate lowest.
Supply Chain Analysis
Export-control regimes limiting flows of high-performance servo controllers and precision encoders constrain technology transfer to certain robotics manufacturing jurisdictions. China, Japan, and Germany anchor production capacity for rare earth magnets, magnet wire, and laminated steel cores respectively. Neodymium supply draws from Chinese concentration; copper winding costs hinge on LME price movements. Single-source vulnerability in magnet processing creates procurement risk. Distribution runs through direct OEM contracts with consignment stock at just-in-time assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
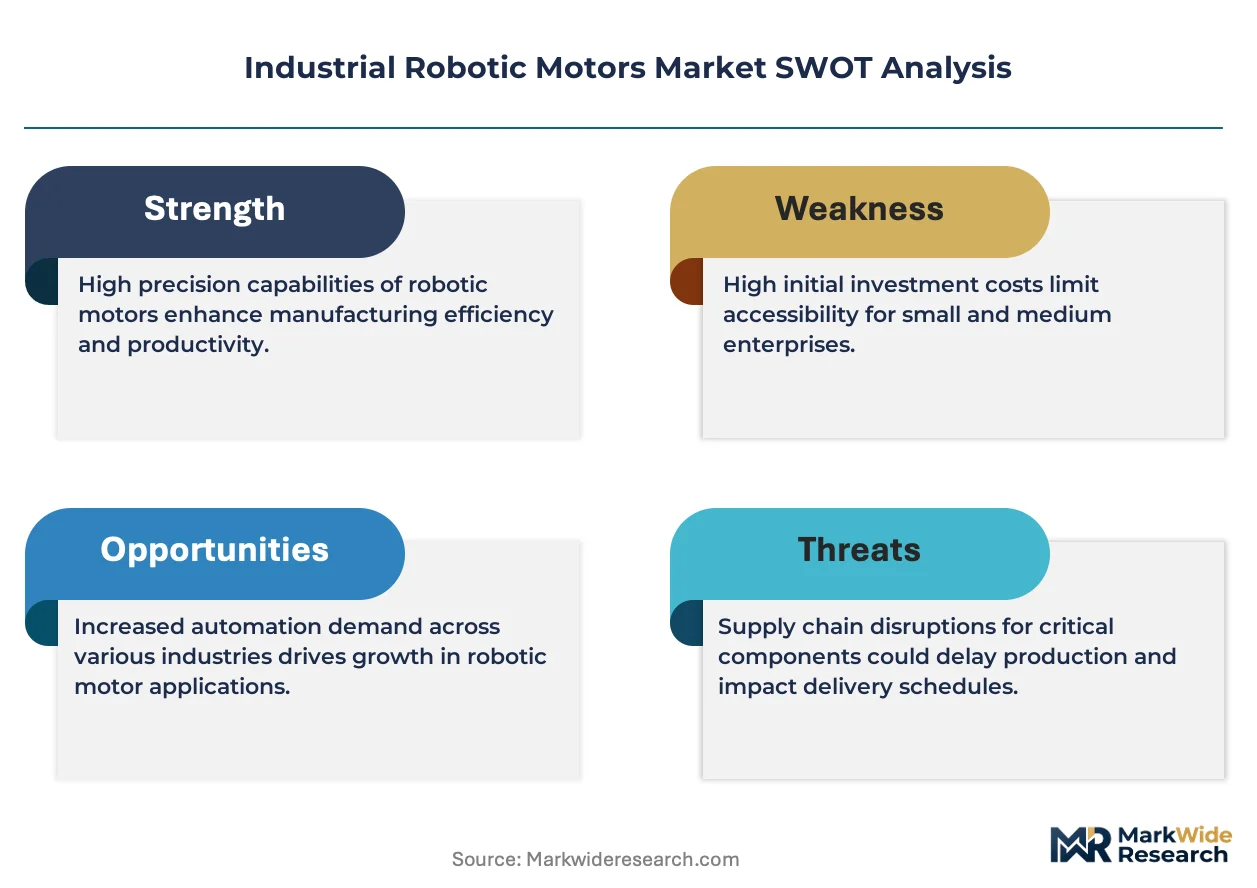
Frameless torque motors and integrated servo-drive modules pose substitution threats to traditional motor-encoder-drive configurations, forcing incumbents to defend against technology displacement while maintaining service revenue from installed bases.
For Market Incumbents: Entrench position through backward integration into rare earth magnet supply chains and captive magnet wire production in Guangdong or Bavaria. Accelerate field-oriented control algorithm development to offset aging specialist workforce concentration in Japan and Germany. Defend against integrated servo-drive substitution by bundling predictive maintenance software with hardware contracts. For New Entrants and Emerging Players: Food-grade stainless washdown motors for meat processing and dairy packaging lines represent the most penetrable entry point, with IP69K-rated enclosures addressing unmet demand where caustic protocols degrade standard finishes. India's PLI scheme incentives in Gujarat and Tamil Nadu create greenfield procurement pipelines with limited incumbent relationships. Target collaborative robot joint specialization with frameless torque motor designs to bypass established servo platform competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision brushless specialists with medical-grade quality systems and collaborative robot joint expertise. Five-to-ten year viability rests on algorithm differentiation and rare earth supply security rather than scale alone. Monitor neodymium export quota announcements from Chinese regulatory authorities as the critical inflection signal for cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnets | Captive neodymium supply insulates margin structures from Chinese export quota volatility. |
| Integrated Servo-Drive Module Development | Embedded encoder architectures compress commissioning timelines for Stuttgart and Shanghai automotive plants. |
| Food-Grade Stainless Enclosure Certification | IP69K-rated washdown motors unlock meat processing and dairy packaging procurement pipelines. |
| AI-Driven Predictive Maintenance Platform | Edge computing integration with servo drives enables condition-based service contracts displacing fixed-interval maintenance. |
| India Manufacturing Footprint Expansion | PLI scheme subsidies for industrial automation attract robot OEM assembly operations in Gujarat and Tamil Nadu. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across motor procurement, motion control engineering, and robotics platform development functions. Primary interviews captured perspectives from plant engineers at automotive tier-one suppliers, OEM procurement teams specifying servo systems, aftermarket service heads managing encoder recalibration programs, and technical R&D directors developing frameless torque architectures. Secondary validation drew from IEC 60034 and NEMA MG1 regulatory filings, customs trade data for rare earth magnet flows, SEC 10-K disclosures from electrical conglomerates, and robotics industry production databases. Bottom-up unit shipment estimates triangulated against top-down value projections.
Calibration against historical efficiency mandate implementation cycles and rare earth price shock periods anchored growth trajectory assumptions across the analysis window. Segmentation modeling spanned product type, control technology, robot application, and end-user industry verticals. CAGRs derived from fitted adoption curves for IE4/IE5 efficiency tiers and collaborative robot joint actuator penetration. Industry-specific inputs included neodymium price elasticity coefficients and automotive battery assembly line automation capex cycles.
Stress conditions across rare earth export restrictions, copper price volatility bands, and IEC efficiency mandate acceleration scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding robot OEM vendor list consolidation patterns and thermal management technology transitions. Material shifts in Chinese rare earth processing policy or EU F-Gas Regulation phase-down timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe SCADA Market
Industrial Automation
Global SCADA Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market