
 Gas Purifiers Market | 2026-2036
Gas Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Purifiers Market Foresight
EU F-Gas Regulation is pivoting the cost-of-entry calculus for gas purification equipment across European industrial processing. Entegris, Inc. leverages its materials science heritage to dominate semiconductor-grade gas delivery systems. Linde plc anchors its position through backward integration into on-site gas generation and purification. Parker Hannifin competes via fluid control specialization that extends into point-of-use purification hardware.
Gas purifiers are engineered systems that remove contaminants—particulates, moisture, oxygen, hydrocarbons, and metallic impurities—from process gases to achieve purity levels measured in parts-per-billion, essential for protecting sensitive manufacturing processes and analytical instruments. Membrane purifiers lead product type demand due to their energy efficiency and compatibility with continuous-flow industrial operations, while electrochemical devices represent the fastest-growing category driven by hydrogen economy applications. Among end users, the semiconductor industry commands the deepest purification requirements and associated margin pools, whereas medical applications sustain steady demand through regulatory-mandated air quality protocols.
EPA standards in the United States, REACH in Europe, and China's GB standards collectively dictate material compatibility, emission limits, and verification protocols for gas purification systems. FDA oversight of medical gas purity and OSHA workplace exposure thresholds further constrain product design and certification pathways. Stakeholders must monitor evolving semiconductor node transitions and hydrogen infrastructure buildouts to align R&D portfolios with the next wave of purity specification tightening.
Market Dynamics
Sub-3nm semiconductor node transitions are compressing purity specifications from parts-per-billion to parts-per-trillion, forcing gas purification infrastructure upgrades across Taiwan, South Korea, and Arizona manufacturing corridors.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants and process gases is accelerating membrane-based purification retrofits across European chemical processing and electronics manufacturing sites.
- Taiwan Semiconductor Manufacturing Cluster:Captive gas supply chains serving leading foundries are expanding point-of-use purification capacity to support advanced logic and memory production ramps.
- Hydrogen Economy Buildout:Electrolyzer and fuel cell manufacturing is creating demand for electrochemical purification systems that remove oxygen and moisture from hydrogen feedstocks.
Market Restraints
- High-Purity Palladium Input Costs:Membrane purifiers depend on palladium alloy components whose price volatility constrains margin flexibility for equipment manufacturers.
- East Asian Supply Concentration:Critical ceramic and metallic membrane substrates originate from Japanese and South Korean suppliers, creating geographic single-source exposure.
- Technical Limitation at Extreme Purity:Existing getter-based systems face throughput constraints when processing large-volume inert gas streams for flat-panel display manufacturing.
Strategic Opportunities
- India Semiconductor Mission:The country's PLI scheme and designated fabrication zones in Gujarat and Tamil Nadu present greenfield demand for on-site gas generation and purification infrastructure.
- Green Hydrogen Certification Mandates:Emerging purity standards for renewable hydrogen are creating specification-driven replacement cycles in European electrolyzer installations.
- Convergence of AI and Process Control:Machine learning-enabled predictive maintenance is opening service-attach revenue streams for purification system vendors serving continuous-flow chemical operations.
Industry Challenges
- Specialized Welding and Cleanroom Assembly Talent:Fabrication of ultra-high-purity hardware requires certified technicians in short supply across North American and European manufacturing bases.
- Extended SEMI S2 and CE Marking Timelines:Semiconductor equipment safety certification cycles now stretch 14-18 months, delaying revenue recognition for new purification platform introductions.
- Legacy System Integration Complexity:Retrofitting membrane purifiers into existing bulk gas distribution architectures requires custom manifold redesigns that extend project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Purifiers Market |
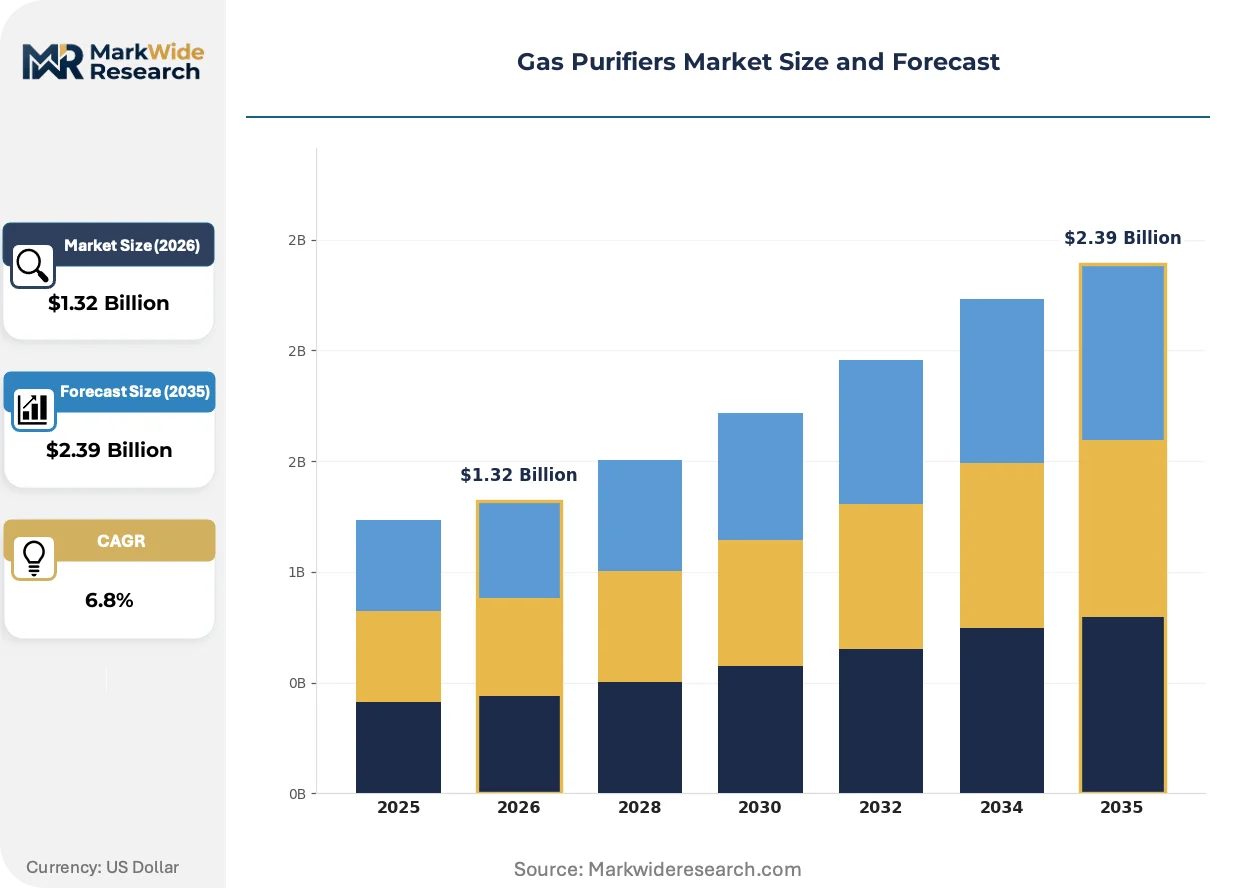
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Purifiers, Thermal Purifiers, Chemical Absorbers, Electrochemical Devices Application: Industrial Processing, Air Quality Control, Laboratory Use, Medical Applications End User: Manufacturing Plants, Research Laboratories, Hospitals, Semiconductor Industry Technology: Activated Carbon, Ionic Filters, UV Light Systems, Adsorption Technology |
| Companies Covered | Entegris, Inc., Linde plc, Parker Hannifin, Air Liquide, Merck KGaA, Mott, SAES Pure Gas, MATHESON, NuPure Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Purifiers Market Shifts & Advancements
Active materials science breakthroughs and regulatory chemistry restrictions are simultaneously expanding performance boundaries and constraining design freedom across gas purification platforms.
Metal-organic framework adsorbents are consolidating position as the preferred media for trace moisture and oxygen removal in portable analytical instrument applications. Research institutions and environmental monitoring agencies are adopting MOF-based purifiers for field-deployable mass spectrometry systems. The technology is consolidating market share previously held by traditional zeolite and activated alumina configurations by offering regeneration at lower thermal energy inputs.
REACH authorization requirements for per- and polyfluoroalkyl substances are restricting fluoropolymer membrane chemistries previously standard in corrosive gas handling. European chemical processors must now qualify alternative membrane materials or implement closed-loop recovery systems to maintain operational compliance. Semiconductor fabs in Germany and the Netherlands are accelerating validation of ceramic and metallic membrane substitutes for fluoropolymer-dependent process steps.
Consolidated procurement through integrated gas suppliers is displacing direct equipment purchases by smaller semiconductor and display manufacturers. Linde, Air Liquide, and regional competitors are bundling purification hardware with long-term gas supply contracts, compressing standalone equipment vendor access to mid-tier fabs. This pattern is most pronounced in China and Southeast Asia where captive gas infrastructure investments accompany new fabrication facility construction.
Gas Purifiers Market Segmentation
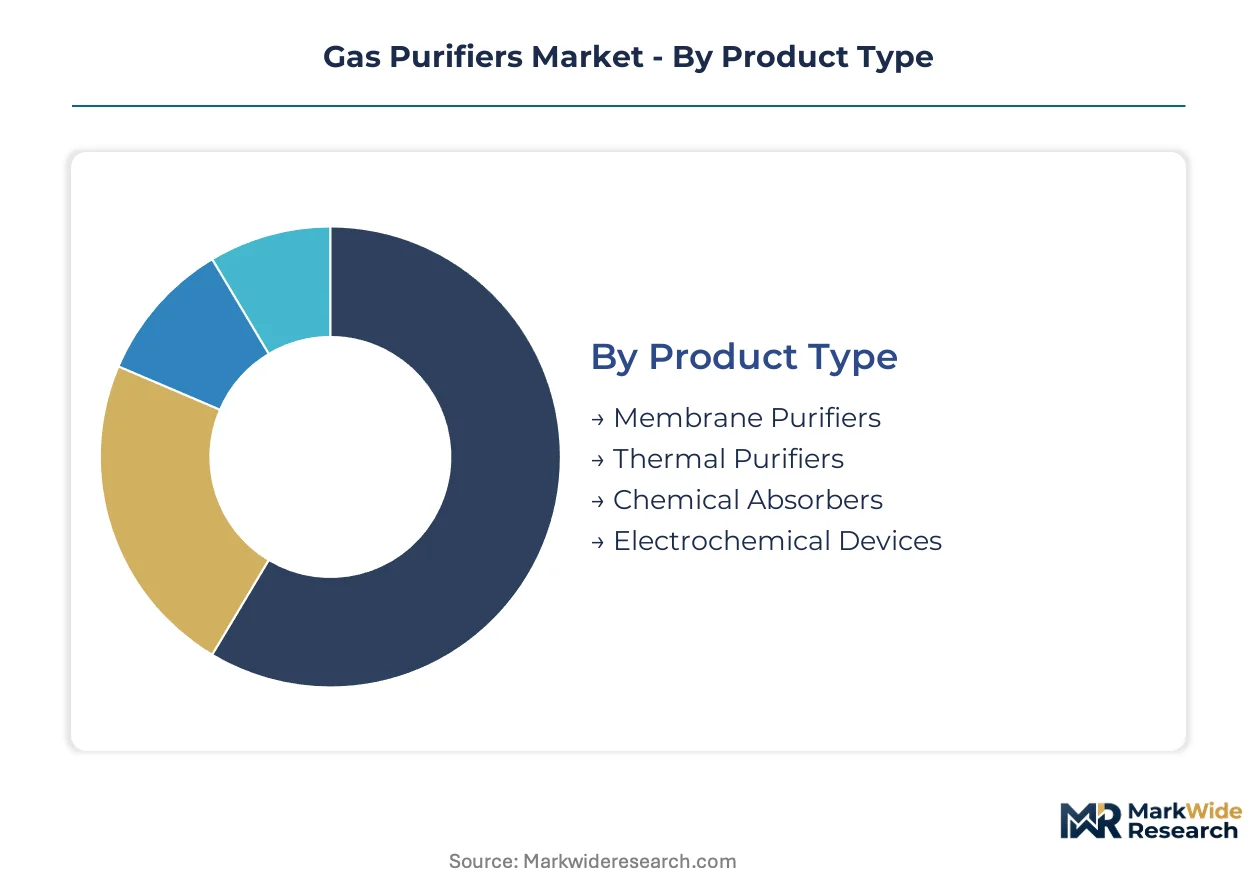
Gas purifier procurement patterns diverge sharply across application contexts. Semiconductor fabs demand parts-per-trillion performance with captive supply chain integration, while medical and laboratory buyers prioritize regulatory certification over throughput specifications.
Product Type:
Supply concentration in palladium alloy and ceramic membrane substrates dictates competitive positioning across purification architectures.
- Membrane Purifiers:Palladium alloy and polymeric membranes separate contaminants through selective permeability barriers, achieving continuous-flow operation without regeneration cycles. Taiwan and South Korean semiconductor corridors anchor demand as sub-3nm node transitions compress purity tolerances. EU F-Gas Regulation retrofits in German and Dutch chemical processing sites are accelerating metallic membrane substitution for fluoropolymer-dependent steps.
- Electrochemical Devices:Solid-state electrolytic cells remove oxygen and moisture through redox reactions at catalytic electrodes, offering modular scaling for distributed hydrogen infrastructure. European electrolyzer installations under green hydrogen certification mandates are driving specification-driven replacement cycles. These systems are expanding most quickly among product categories as hydrogen economy buildouts mature.
- Thermal Purifiers:High-temperature getter materials react with reactive contaminants to form stable compounds, delivering extreme purity for inert gas streams.
- Chemical Absorbers:Packed-bed configurations using activated alumina, molecular sieves, or proprietary media target specific contaminant classes through chemisorption.
Today's leader: Membrane Purifiers. Tomorrow's challenger: Electrochemical Devices.
Application:
Cost tier differentiation separates continuous-flow industrial systems from batch-mode analytical and medical configurations.
- Industrial Processing:Bulk gas distribution systems serving petrochemical, steel, and electronics manufacturing require ton-scale throughput with 99.999% baseline purity. Taiwan Semiconductor Manufacturing clusters and Arizona fabrication corridors are expanding point-of-use capacity. REACH authorization constraints on fluoropolymer chemistries are forcing membrane material requalification across European chemical processing sites.
- Medical Applications:Breathing gas and surgical air systems must satisfy FDA purity protocols and ISO 7396-1 medical gas pipeline standards, with redundancy mandates for patient safety. Hospitals in the United States and Germany sustain steady replacement demand through regulatory-mandated air quality verification cycles.
- Air Quality Control:Ambient and workplace atmosphere purification targets particulate and gaseous pollutant removal for occupational health compliance.
- Laboratory Use:Analytical instrument protection and research-grade gas conditioning emphasize compact footprint and rapid regeneration over absolute throughput.
Industrial Processing commands the steepest expansion trajectory. Medical Applications provide the most stable recurring revenue base.
End User:
Customer type fragmentation creates distinct procurement channels from integrated gas suppliers versus direct equipment vendors.
- Semiconductor Industry:Logic and memory foundries impose the deepest purity specifications across all end-user categories, with captive gas supply chains bundling purification hardware into long-term contracts. Linde and Air Liquide are consolidating procurement relationships through integrated gas supply agreements, compressing standalone vendor access.
- Manufacturing Plants:Flat-panel display, photovoltaic, and general electronics assembly operations balance purity requirements against capital efficiency, often sourcing through regional gas distributors rather than global suppliers.
- Research Laboratories:National research institutions and environmental monitoring agencies are adopting metal-organic framework purifiers for field-deployable mass spectrometry systems.
- Hospitals:Healthcare facility engineering departments manage medical gas infrastructure under joint commission accreditation and national pharmaceutical regulator oversight.
Semiconductor Industry absorbs the premium pricing tier. Manufacturing Plants represent the volume scaling opportunity.
Technology:
Maturity gradients separate established adsorption methods from emerging material science platforms.
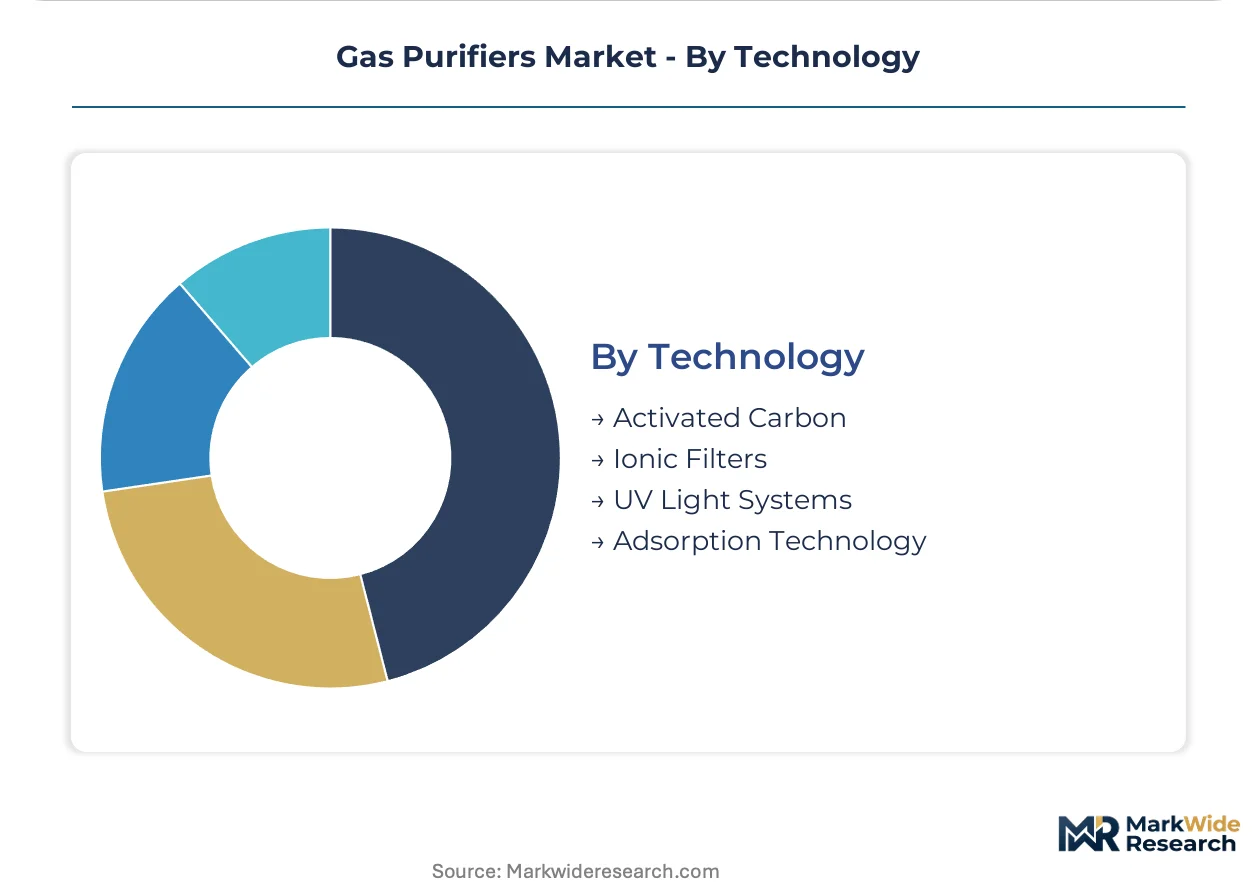
- Adsorption Technology:Zeolite, activated alumina, and carbon molecular sieves dominate baseline moisture and hydrocarbon removal through physisorption mechanisms, with regeneration thermal energy inputs determining operational economics. Metal-organic frameworks are consolidating position in portable analytical applications by enabling lower-temperature regeneration.
- Activated Carbon:High-surface-area carbon structures target organic vapor and chlorine compound removal in compressed air and process gas conditioning.
- Ionic Filters:Electrostatic precipitation and ion exchange media address metallic ion contamination in ultrapure water and gas co-purification systems.
- UV Light Systems:Photochemical oxidation breaks organic contaminants and microbial loads in medical and laboratory gas streams.
Adsorption Technology holds installed base dominance. Ionic Filters are gaining share fastest in next-generation semiconductor wet chemistry integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welding technicians and cleanroom assembly specialists concentrate in East Asian manufacturing corridors where sub-3nm semiconductor node transitions demand ultrapure gas infrastructure. Taiwan and South Korea anchor the deepest talent pools for palladium alloy membrane fabrication.
United States
EPA emission standards and OSHA workplace exposure thresholds govern material compatibility in gas purification systems. Arizona fabrication corridors expand point-of-use capacity as Intel and TSMC advance domestic chipmaking. The Inflation Reduction Act accelerates hydrogen infrastructure investments requiring electrochemical purification systems.
Germany
REACH authorization constraints on fluoropolymer chemistries force membrane material requalification across chemical processing sites. The EU F-Gas Regulation mandates metallic membrane substitution for hydrofluorocarbon-dependent process steps. Bavarian industrial clusters validate ceramic membrane alternatives for semiconductor wet chemistry integration.
China
GB standards dictate verification protocols for gas purification equipment serving domestic semiconductor fabs. The country's dual carbon goals drive electrolyzer manufacturing demand for hydrogen feedstock conditioning. Yangtze River Delta fabrication zones expand captive gas supply chains for memory and logic production ramps.
South Korea
METI-aligned industrial policy supports palladium alloy membrane substrate development through national materials science programs. Seoul Capital Area foundries compress purity specifications from parts-per-billion to parts-per-trillion for sub-3nm processes. Busan-Ulsan chemical processing corridors retrofit bulk gas distribution with membrane-based purification.
India
The PLI scheme and designated fabrication zones in Gujarat and Tamil Nadu present greenfield demand for on-site gas generation infrastructure. BIS certification requirements shape equipment qualification pathways for medical and industrial gas systems. Maharashtra research institutions adopt metal-organic framework purifiers for field-deployable analytical instrumentation.
Gas Purifiers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Industrial gas majors leverage backward integration into on-site generation and purification, compressing standalone equipment vendor access to mid-tier fabs. Three archetypes dominate: integrated gas suppliers bundling hardware into long-term contracts, materials science specialists commanding semiconductor-grade delivery systems, and fluid control experts extending into point-of-use hardware. Capacity expansion and strategic partnerships represent the dominant competitive vectors as stakeholders secure palladium alloy and ceramic membrane substrate supply.
Among integrated gas suppliers, Linde plc and Air Liquide occupy positions anchoring procurement consolidation through bundled long-term contracts. Entegris, Inc. exemplifies the materials science heritage archetype, while Parker Hannifin represents fluid control specialization extending into purification hardware. These three companies illustrate the competitive tension between scale-driven bundling and technology-focused differentiation.
| Leading Market Players |
|---|
| Entegris, Inc. |
| Linde plc |
| Parker Hannifin |
| Air Liquide |
| Merck KGaA |
| Mott |
| SAES Pure Gas |
| MATHESON |
| NuPure Corporation |
| Others |
Supply & Pricing Matrix
Sub-3nm semiconductor node transitions simultaneously reshape cost economics and supply concentration by forcing palladium alloy membrane upgrades that tether equipment margins to volatile precious metal markets. Integrated gas suppliers exploit this dependency by bundling purification hardware into long-term contracts, compressing standalone vendor pricing power.
Pricing Analysis
Bundled service contracts versus unbundled equipment sales split pricing power across the Gas Purifiers Market. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade systems from industrial processing units and medical configurations. Price differentiation hinges on SEMI S2 certification tier and captive supply chain integration depth. Cost compression in mid-tier industrial segments intensifies because consolidated procurement through Linde and Air Liquide displaces direct vendor relationships. Manufacturing plants exhibit highest price sensitivity due to capital efficiency mandates, while semiconductor fabs absorb premium tiers without volume negotiation.
Supply Chain Analysis
Freight cost escalation for palladium alloy substrates and ceramic membranes amplifies geographic supply concentration risks. Critical membrane materials originate from Japan, South Korea, and Germany, drawing equipment fabricators into single-source exposure for high-purity inputs. Raw material dependencies center on palladium alloys, ceramic substrates, and fluoropolymer alternatives under REACH authorization. Distribution runs through integrated gas suppliers serving East Asian manufacturing corridors. Tariff exposure on Japanese-sourced palladium components threatens margin stability for North American and European equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gas Purifiers Market functions as a stable compounder where regulatory-mandated purity specification tightening sustains replacement demand across semiconductor and hydrogen infrastructure end uses.
For Market Incumbents: Deploy backward integration into palladium alloy membrane substrate production to defend against Japanese and South Korean supply concentration. Entrench SEMI S2 certification capabilities to extend 14-18 month safety validation timelines as competitive moats. Capacity addition in Gujarat and Tamil Nadu fabrication zones captures India Semiconductor Mission greenfield demand before regional gas suppliers consolidate procurement relationships. For New Entrants and Emerging Players: Capture European electrolyzer retrofit demand driven by green hydrogen certification mandates where specification-driven replacement cycles outpace incumbent response bandwidth. Target medical gas infrastructure in German and US hospital systems where regulatory-mandated verification cycles sustain recurring revenue without semiconductor-grade technical barriers. Partner with regional gas distributors in Southeast Asia to bypass integrated supplier bundling that blocks direct fab access. For Investors and Strategic Acquirers: Valuations sit cheapest among fluid control specialists extending into point-of-use purification hardware rather than integrated gas majors or materials science heritage players. Five-to-ten year viability hinges on hydrogen economy buildout maturation and sub-3nm node transition persistence. Watch palladium price volatility as inflection indicator for margin compression timing across membrane-dependent equipment vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrates | Reduces palladium supply exposure for equipment manufacturers serving Taiwan and South Korea fabs. |
| SEMI S2 Certification Investment | Extends 14-18 month validation timelines that protect incumbent revenue recognition schedules. |
| Green Hydrogen Certification Alignment | Captures European electrolyzer replacement cycles under emerging renewable hydrogen purity standards. |
| Regional Gas Distributor Partnership | Bypasses Linde and Air Liquide bundling to access mid-tier manufacturing plant procurement channels. |
| Metal-Organic Framework R&D Expansion | Enables lower-temperature regeneration that displaces zeolite configurations in portable analytical applications. |
Research Methodology
Direct dialogue with semiconductor fab engineering directors, gas supply chain procurement leads, palladium alloy membrane substrate manufacturers, and hydrogen infrastructure project developers grounded qualitative findings. Secondary validation drew from SEMI industry filings, EPA emission standard updates, EU F-Gas Regulation implementation reports, and customs data tracking palladium alloy trade flows. Bottom-up equipment shipment analysis and top-down gas consumption modeling triangulated market sizing across the analysis window.
Segmented outputs across membrane purifiers, electrochemical devices, thermal purifiers, and chemical absorbers combined with semiconductor, medical, industrial processing, and laboratory end-use splits. CAGRs derived from node transition roadmaps, hydrogen electrolyzer deployment pipelines, and regulatory phase-in schedules without year-specific anchoring. Palladium price volatility indices and SEMI S2 certification timeline distributions served as industry-specific forecast inputs.
Semiconductor capital expenditure cycle shifts, REACH authorization timeline accelerations, and hydrogen infrastructure subsidy modifications are the dominant revision risks that could compress or extend the projection horizon. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Oxygen Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Welding Gas Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
Argon Gas Market