
 North America Medical Plastics Extrusion Market | 2026-2036
North America Medical Plastics Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Plastics Extrusion Market Analytics
Multi-source procurement for precision extruded components is pivoting toward qualified regional suppliers as medical device OEMs reduce sole-source risk. MedPlast Technologies leverages integrated cleanroom manufacturing across multiple US sites to anchor catheter tubing supply chains for tier-one device makers. Spectrum Plastics Group competes through specialized multi-lumen and braid-reinforced configurations that command premium positioning in neurovascular applications. Putnam Plastics differentiates via deep expertise in tight-tolerance fluoropolymer extrusions for drug-delivery catheters.
Medical plastics extrusion encompasses the continuous shaping of thermoplastic resins into tubular, film, sheet, or profile geometries using single-screw or twin-screw extruders with downstream calibration, cooling, and cutting systems, typically achieving dimensional tolerances of ±0.001 inch for critical luminal applications. The process serves primarily as an enabling fabrication method for sterile, single-use medical devices requiring consistent wall thickness, surface finish, and material purity across high-volume production runs. Tubing dominates product-type revenue owing to its ubiquity in fluid management and access devices, while polyethylene leads material consumption for its balance of chemical resistance, processability, and cost position in high-volume disposables. Diagnostic equipment applications represent the fastest-growing demand segment as point-of-care testing platforms proliferate and require customized microbore and multi-lumen conduit systems.
FDA enforcement of ISO 10993 biocompatibility endpoints and USP Class VI testing requirements shapes material selection and supplier qualification timelines for extrusion houses serving regulated device markets. OSHA workplace exposure limits for plastic processing additives and emerging EPA scrutiny of per- and polyfluoroalkyl substances in medical applications are forcing compound reformulation and process ventilation investments across the value chain. Stakeholders must monitor how state-level extended producer responsibility frameworks in California and New York propagate upstream to resin selection and recycling infrastructure commitments for single-use medical plastics.
Market Dynamics
ISO 10993 biocompatibility enforcement is compressing supplier qualification timelines while catheter OEMs consolidate procurement around validated cleanroom extruders with proven FDA master file submissions. This regulatory pressure is reshaping competitive positioning toward integrated compounder-extruder networks.
Growth Catalysts
- Minimally invasive procedure expansion:Cardiovascular and neurovascular catheter volumes are rising across US hospital systems and Mexican manufacturing parks, pulling multi-lumen tubing demand through qualified regional supply chains.
- REACH and EPA perfluoroalkyl substance scrutiny:European and American environmental regulators are restricting legacy fluoropolymer additives, accelerating qualification of next-generation PEEK and bioabsorbable polymer extrusions for drug-delivery applications.
- Point-of-care diagnostic platform proliferation:Microfluidic cartridge manufacturers in the US Great Lakes corridor are scaling customized microbore tubing orders for molecular testing devices.
Market Restraints
- Specialized resin supply concentration:Medical-grade fluoropolymers and implantable-grade PEEK rely on a limited set of compounders in Germany and the United States, exposing extruders to allocation risk during polymer supply shocks.
- Cleanroom capex intensity:Validated ISO Class 7 extrusion suites require seven-figure capital deployment per production line, freezing out mid-scale processors from tier-one device supply chains.
- Biocompatibility testing timeline friction:FDA ISO 10993-18 chemical characterization requirements extend material qualification to 18-24 months, delaying new product introductions for emerging device categories.
Strategic Opportunities
- Mexico nearshoring acceleration:Tijuana and Monterrey medical device clusters are attracting catheter assembly operations, creating demand for regional extrusion toll processors with validated cleanroom capabilities.
- Continuous manufacturing technology convergence:Real-time rheology monitoring fused with laser micrometer feedback loops is enabling zero-defect tubing production for neurovascular applications at commercial scale.
- California extended producer responsibility frameworks:State-level mandates for single-use medical plastic recycling are creating first-mover advantage for extruders with validated regrind protocols and closed-loop material traceability systems.
Industry Challenges
- Polymer processing engineering talent scarcity:The specialized skill set combining twin-screw extrusion science with medical device regulatory knowledge commands premium compensation and limits expansion capacity for regional processors.
- Legacy equipment integration complexity:Retrofitting 1990s-vintage extrusion lines with Industry 4.0 sensor networks and batch record digitization requires substantial downtime and validation re-work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Plastics Extrusion Market |
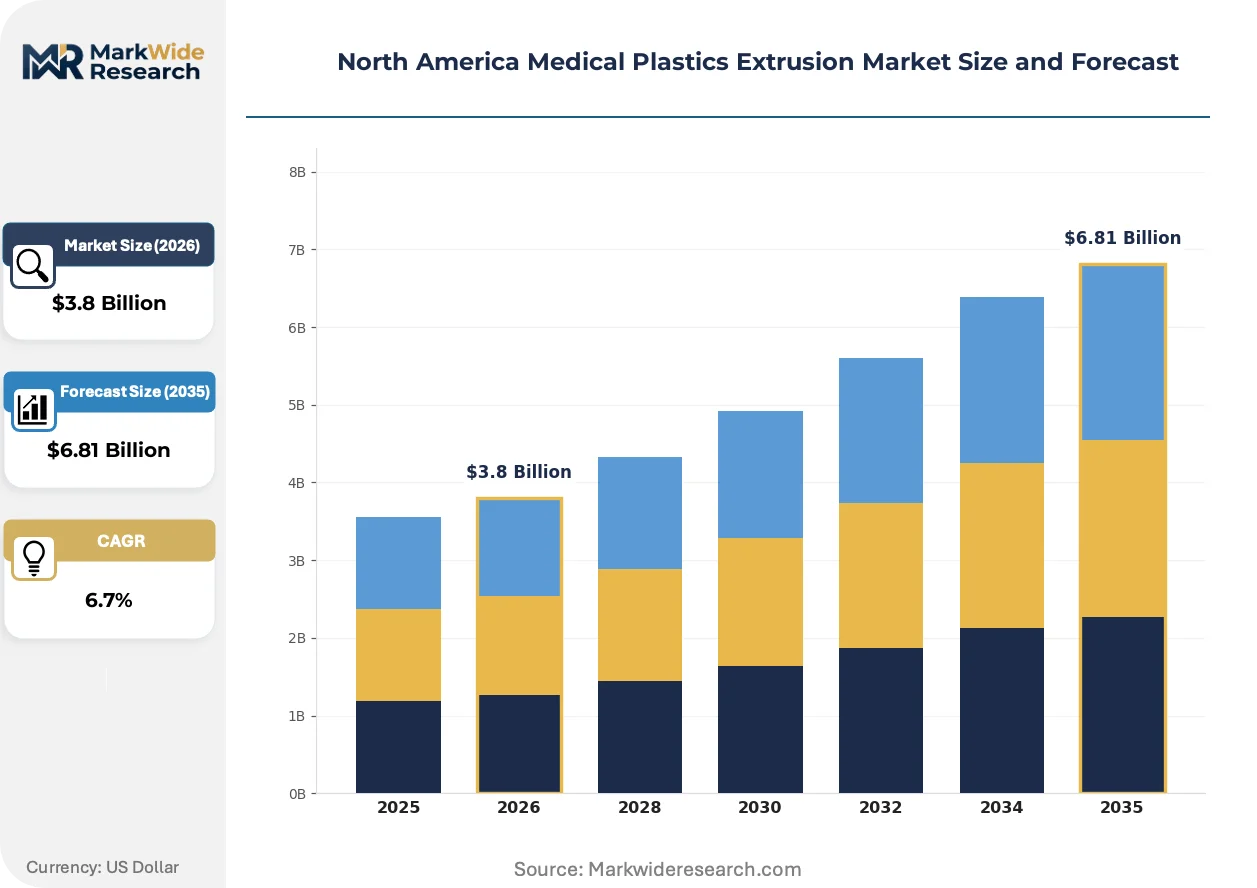
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubing, Films, Sheet, Profiles Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Hospitals, Clinics, Medical Device Manufacturers, Laboratories Application: Packaging, Disposable Items, Surgical Instruments, Diagnostic Equipment |
| Companies Covered | MedPlast Technologies, PrimeFlex Plastics, PolyMed Extrusions, Putnam Plastics, Pexco, Extruded Medical Solutions Inc., VistaMed, Teel Plastics, Spectrum Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Plastics Extrusion Market Evolving Landscape
Extrusion process intelligence and material science advances are converging to enable sub-micron tolerance tubing for next-generation interventional devices. Three developments are commanding capital allocation and engineering resources across the value chain.
Multi-layer coextrusion with embedded radiopaque stripes is automating quality assurance workflows for cardiovascular catheter manufacturers. Siemens Healthineers and Boston Scientific procurement teams are mandating automated vision inspection integration from tubing suppliers. This technology is automating defect detection that previously required manual bore gauge sampling, compressing incoming quality control timelines from days to hours.
FDA enforcement of updated ISO 10993-23 guidance for irritation and sensitization endpoints is forcing compound reformulation across the supply base. Extruders serving neurovascular and drug-delivery segments are resubmitting master files with expanded chemical characterization datasets. The neurovascular catheter segment is absorbing the highest compliance burden, with OEMs dual-sourcing from extruders with pre-validated biocompatibility packages.
Consignment inventory programs are displacing traditional purchase-order relationships between device assemblers and tubing suppliers. Cardinal Health and Medtronic vascular divisions are pushing vendor-managed inventory agreements onto extrusion houses, transferring working capital burden upstream. This shift is most visible in the US Great Lakes manufacturing corridor, where just-in-time delivery windows have compressed from two weeks to 48 hours.
North America Medical Plastics Extrusion Market Segmentation
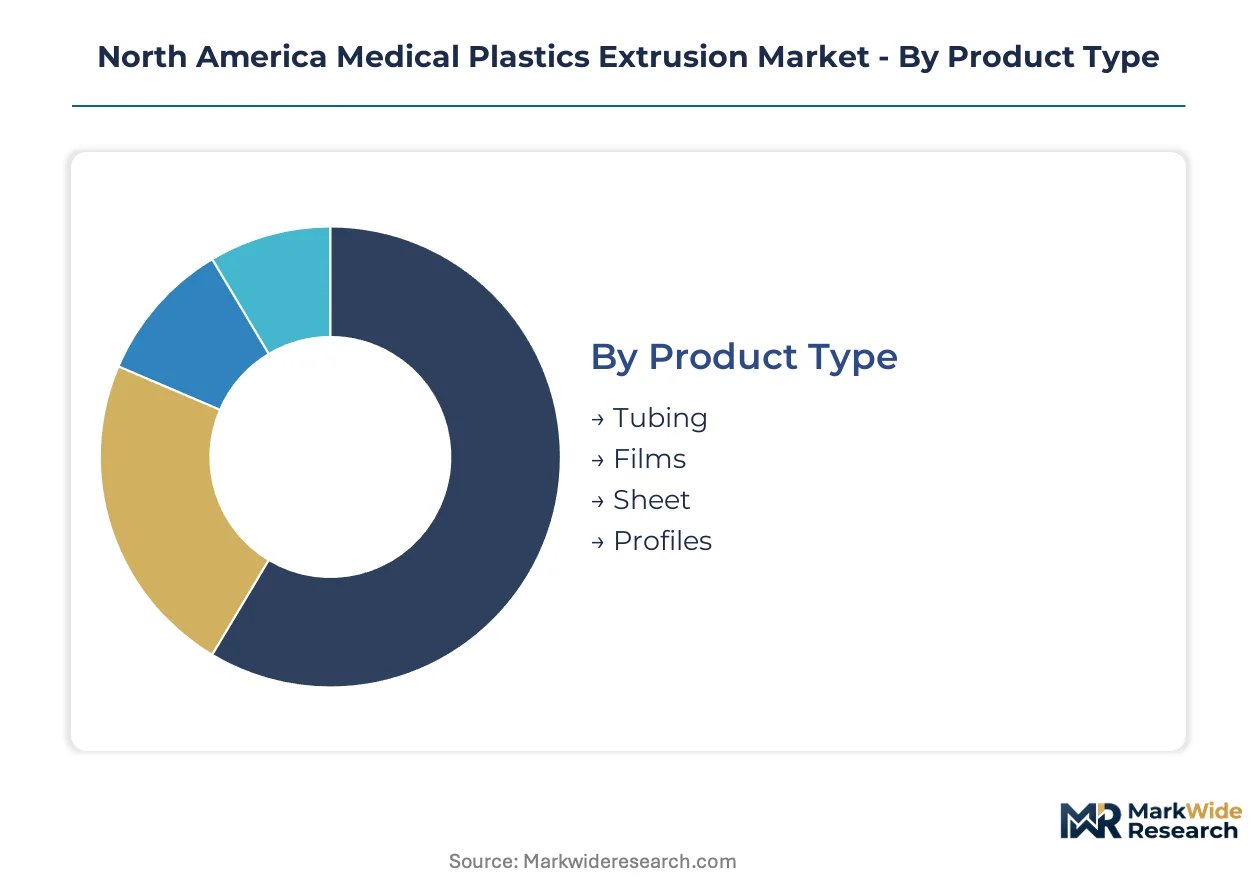
Medical plastics extrusion segmentation reveals how capital deployment and regulatory burden concentrate differently across product geometries, material grades, and end-use specifications. OEM procurement teams segment suppliers by validated process capabilities rather than commodity resin categories alone.
Product Type:
Cleanroom extrusion suites require differentiated capital intensity depending on luminal complexity and dimensional tolerance demands.
- Tubing:Continuous extrusion of single-lumen, multi-lumen, and braid-reinforced configurations achieves ±0.001 inch tolerances for fluid management and access devices. Cardiovascular catheter OEMs in the US Great Lakes corridor are consolidating procurement around regional extruders with validated ISO Class 7 lines and FDA master file submissions.
- Films:Cast and blown film extrusion for sterile barrier packaging and medical-grade pouches runs on lower-tolerance equipment but requires extensive leachables testing. Demand from Mexican maquiladora operations near Tijuana is pulling capacity investments for just-in-time delivery to device assembly plants.
- Sheet:Thermoformable extruded sheet serves blister packaging and procedure tray applications with moderate tolerance requirements.
- Profiles:Custom geometric extrusions for device housings and structural components occupy niche specification volumes with higher tooling amortization per SKU.
Most installed capacity flows through tubing. Expansion is steepest in multi-lumen configurations for minimally invasive devices.
Material:
Biocompatibility qualification timelines and resin supply concentration create divergent sourcing risk profiles across polymer families.
- Polyethylene:LDPE and HDPE grades dominate high-volume disposables for their chemical resistance, sealability, and cost position. US compounders in Texas and Louisiana anchor supply for IV bag and drainage device manufacturers requiring USP Class VI certification.
- Polypropylene:Clarified and random copolymer grades offer autoclave resistance for surgical tray and sterilization container applications. California device makers are qualifying recycled-content PP grades ahead of extended producer responsibility mandates.
- Polyvinyl Chloride:Plasticized and unplasticized formulations face EPA scrutiny over phthalate additives, forcing compound reformulation for legacy blood bag and tubing sets.
- Polystyrene:Crystal and high-impact grades serve diagnostic cuvette and tissue culture applications with lower regulatory burden than implantable-contact materials.
Polyethylene commands the largest production volumes. Polypropylene is gaining share fastest in sterilization-resistant applications.
End User:
Customer scale and specification intensity determine whether extruders operate on consignment inventory or transactional purchase order terms.
- Medical Device Manufacturers:Tier-one OEMs like Boston Scientific and Medtronic vascular divisions mandate vendor-managed inventory with 48-hour delivery windows, transferring working capital burden upstream to extrusion houses.
- Hospitals:IDN procurement consortia source standardized tubing and packaging through distribution intermediaries rather than direct extruder relationships.
- Clinics:Ambulatory surgery centers purchase lower-SKU-count disposable sets with less specification customization than acute care facilities.
- Laboratories:Molecular diagnostic and microfluidic cartridge producers in the US Great Lakes corridor require microbore tubing with tight lot-to-lot consistency for point-of-care platforms.
Device manufacturers absorb the majority of qualified extrusion output. Diagnostic laboratories are expanding procurement fastest as microfluidic platforms scale.
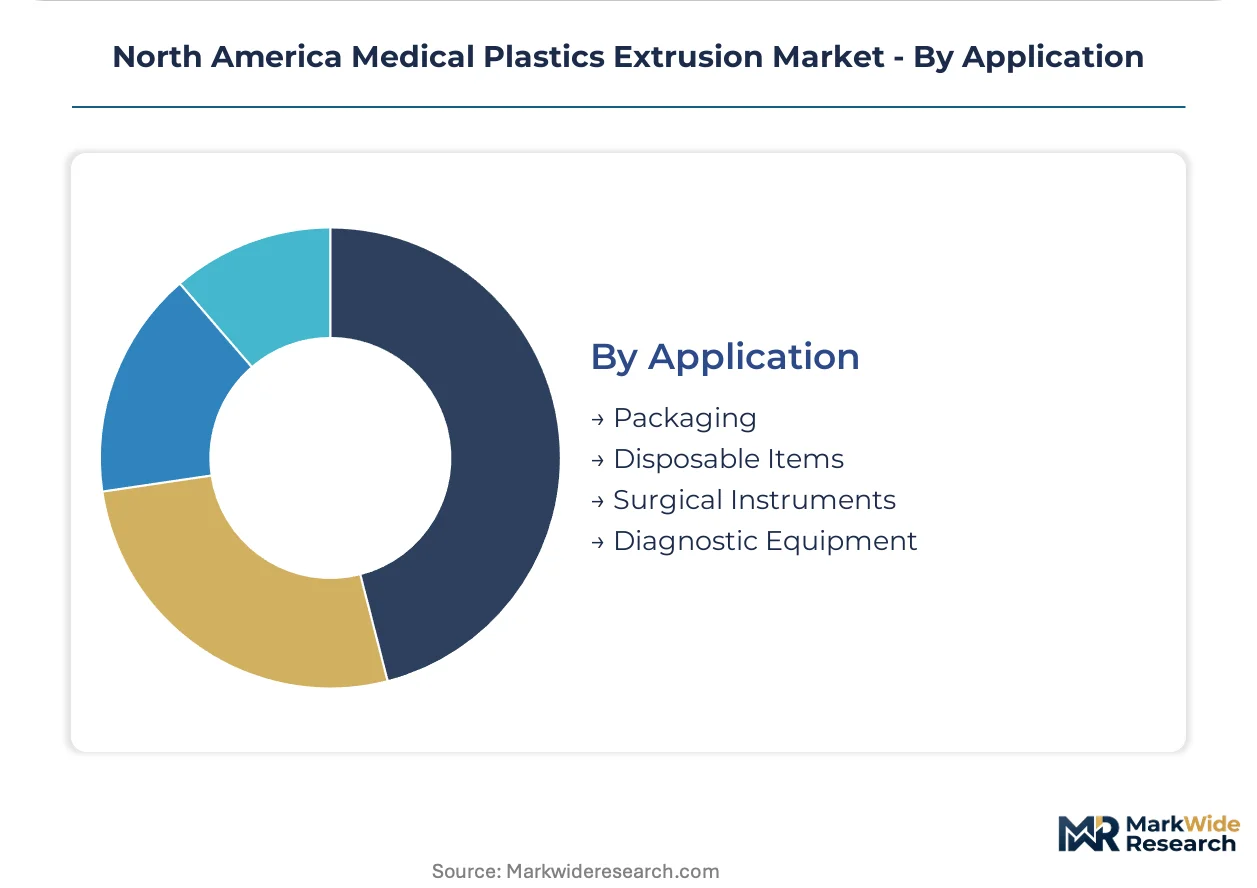
Application:
Regulatory classification and sterilization requirements segment extrusion capabilities by validation depth and cleanroom certification tier.
- Disposable Items:Single-use tubing, bags, and drapes for fluid management and sterile barriers represent the highest volume application with moderate tolerance requirements. Mexican assembly operations near Monterrey are pulling regional capacity for catheter and infusion set components.
- Diagnostic Equipment:Microbore and multi-lumen conduits for molecular testing and point-of-care cartridges demand sub-micron tolerances and extensive biocompatibility documentation. FDA ISO 10993-18 chemical characterization requirements extend qualification timelines to 18-24 months.
- Packaging:Sterile barrier films and thermoformed trays require seal integrity validation but lower dimensional precision than luminal devices.
- Surgical Instruments:Instrument handles and procedural device housings utilize profile extrusion with moderate cosmetic and structural specifications.
Disposable items consume the most resin tonnage. Diagnostic equipment commands the steepest expansion trajectory as testing platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Great Lakes manufacturing corridor anchors North American medical plastics extrusion demand, with device OEMs clustering near specialized polymer compounders and toll processors across Michigan, Ohio, and Illinois.
United States
Cardiovascular catheter manufacturers in Minneapolis and Boston are scaling multi-lumen tubing purchases as minimally invasive procedure volumes expand across hospital systems. FDA enforcement of ISO 10993-18 chemical characterization requirements extends material qualification timelines to 18-24 months, compressing supplier selection windows. The Great Lakes corridor concentrates validated cleanroom extrusion capacity, with MedPlast Technologies and Spectrum Plastics Group operating integrated manufacturing sites near device assembly clusters.
Canada
Health Canada biocompatibility requirements for Class III device components are driving Ontario-based extruders toward ISO 13485 certification upgrades. The Greater Toronto Area hosts specialized toll processors serving US OEMs seeking tariff-advantaged supply alternatives. Vancouver-area compounders are qualifying bioabsorbable polymer grades for emerging drug-delivery applications.
Mexico
Tijuana and Monterrey medical device maquiladoras are attracting catheter assembly operations from US OEMs seeking labor cost optimization. Mexican federal health regulator COFEPRIS alignment with FDA quality system requirements is accelerating dual-qualification of regional extrusion suppliers. Baja California extrusion toll processors are investing in ISO Class 7 cleanroom suites to capture consignment inventory contracts from San Diego-based device makers.
California
Silicon Valley microfluidic cartridge producers require sub-micron tolerance microbore tubing for point-of-care molecular testing platforms. California's extended producer responsibility framework for single-use medical plastics is forcing extruders to validate closed-loop regrind protocols ahead of 2027 mandates. San Diego neurovascular device clusters are dual-sourcing from extruders with pre-validated biocompatibility packages.
North America Medical Plastics Extrusion Market Competitive Landscape
Global majors compete with regional champions across cleanroom certification tiers, with market structure consolidating around validated FDA master file holders. Tier-one device OEMs are compressing supplier bases to reduce qualification burden, favoring integrated compounder-extruder networks over transactional toll processors. Three archetypes dominate: integrated cleanroom manufacturers, specialized fluoropolymer processors, and regional toll extruders. Competitive moves center on M&A for geographic expansion and strategic partnerships for resin supply security.
Among integrated cleanroom manufacturers, MedPlast Technologies exemplifies the multi-site validation archetype, while Spectrum Plastics Group occupies a position in specialized multi-lumen configurations. Putnam Plastics represents the tight-tolerance fluoropolymer specialization tier. These three anchors illustrate how competitive positioning diverges across certification depth and material expertise rather than scale alone.
| Leading Market Players |
|---|
| MedPlast Technologies |
| PrimeFlex Plastics |
| PolyMed Extrusions |
| Putnam Plastics |
| Pexco |
| Extruded Medical Solutions Inc. |
| VistaMed |
| Teel Plastics |
| Spectrum Plastics Group |
| Others |
Value Network & Pricing Analysis
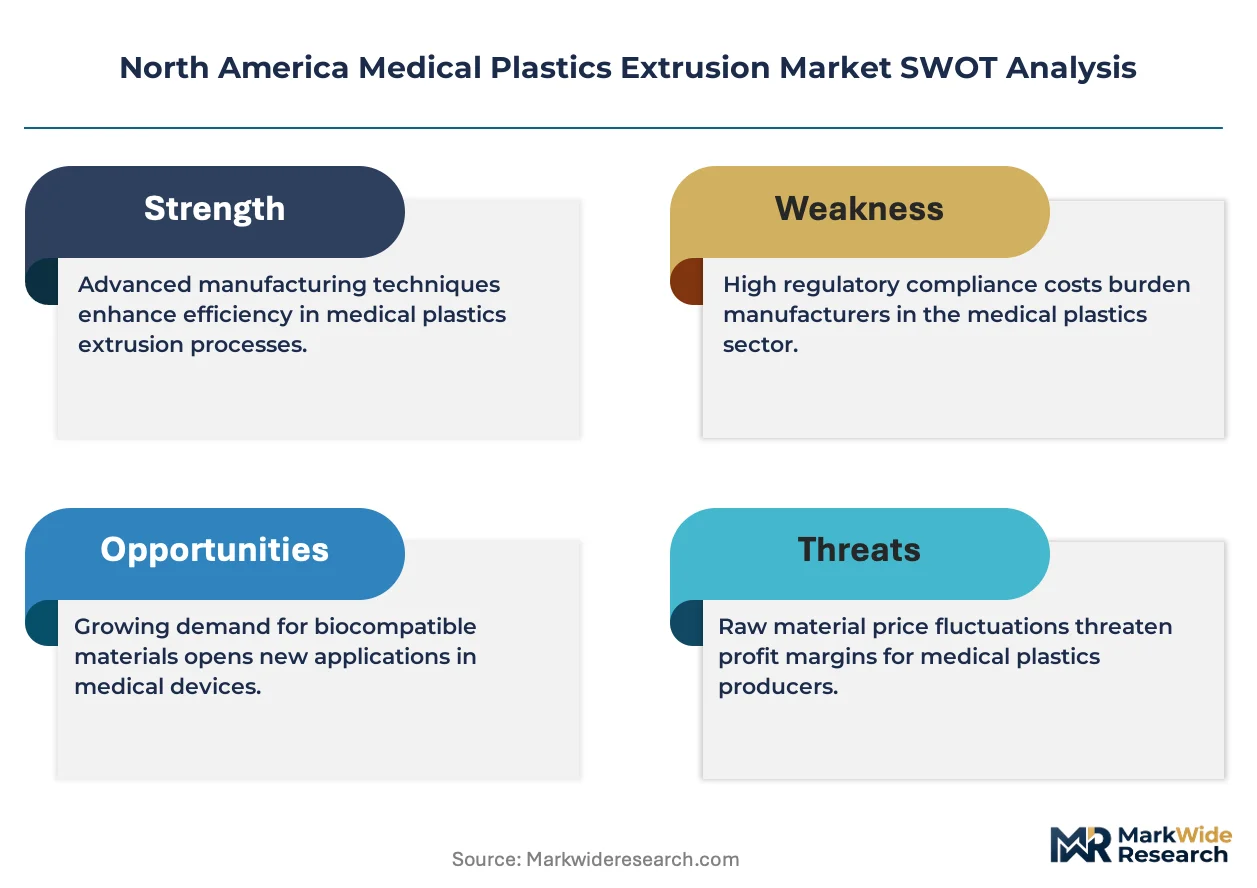
Vendor-managed inventory mandates from Boston Scientific and Medtronic are forcing extrusion houses to absorb working capital burdens, compressing margins and favoring processors with captive resin supply or multi-site manufacturing networks that can offset logistics costs through geographic density.
Pricing Analysis
Medical-grade fluoropolymer and implantable-grade PEEK resin costs pass through directly to tubing pricing, with compounders in Germany and the United States anchoring supply. Pricing stratifies across FDA master file tiers, with validated cleanroom extruders commanding premiums over transactional toll processors. Cost compression in standard polyethylene tubing runs through Mexican maquiladora competition. Academic medical centers and IDN procurement consortia exhibit highest price sensitivity, while neurovascular OEMs prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Cardinal Health and Siemens Healthineers procurement teams are fragmenting volume across qualified regional suppliers rather than concentrating with single vendors. Supply concentrates in the United States, Germany, and Mexico, with specialized compounding capacity tethered to FDA and EMA regulatory clusters. Medical-grade fluoropolymers, radiopaque fillers, and bioabsorbable polymers constitute critical input dependencies. Single-source vulnerability runs through German implantable-grade PEEK compounders. Distribution runs through consignment inventory programs with 48-hour delivery windows to Great Lakes device assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America medical plastics extrusion market compounds steadily as minimally invasive procedure volumes expand across US hospital systems and Mexican manufacturing parks, creating durable demand pull for qualified tubing supply.
For Market Incumbents: Hedge against resin allocation risk by securing long-term supply agreements with German PEEK compounders and US fluoropolymer producers. Expand ISO Class 7 cleanroom capacity in Monterrey and Tijuana to capture nearshoring demand from San Diego neurovascular clusters. Backward integration into compounding capabilities defends margin position against raw material volatility. For New Entrants and Emerging Players: Capture microfluidic diagnostic tubing demand from Silicon Valley and Great Lakes molecular testing platforms, where qualification timelines favor agile processors willing to absorb 18-24 month ISO 10993-18 testing cycles. Target California extended producer responsibility mandates as a first-mover entry point, validating closed-loop regrind protocols ahead of regulatory enforcement. Lead with sustainability-certified product lines to differentiate against legacy extruders. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional extruders holding FDA master file submissions and validated cleanroom infrastructure in underserved geographies. Long-term viability hinges on regulatory compliance depth rather than scale alone, with compounder-extruder integration commanding scarcity premiums. Watch COFEPRIS-FDA dual-qualification momentum in Baja California as an inflection signal for Mexican supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 suites in Monterrey capture consignment contracts from San Diego device makers. |
| Backward Integration into Compounding | In-house medical-grade fluoropolymer production reduces allocation exposure to German suppliers. |
| FDA Master File Resubmission | Expanded ISO 10993-23 datasets defend supplier positioning against biocompatibility enforcement. |
| Continuous Manufacturing Technology Deployment | Real-time rheology monitoring enables zero-defect neurovascular tubing at commercial scale. |
| Closed-loop Regrind Validation | California EPR compliance creates first-mover advantage in sustainable medical plastics supply. |
Research Methodology
Bottom-up catheter and diagnostic device modeling reconciled against top-down resin consumption tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and extrusion plant managers were combined with secondary validation from FDA 510(k) filings, USP Class VI certification databases, and customs import records for medical-grade polymers. Triangulation across stakeholder inputs and trade data ensures segmentation integrity.
Input-output matrices map resin tonnage to finished device volumes across tubing, film, sheet, and profile geometries. Modeled dimensions include luminal complexity, material biocompatibility tier, end-use sterilization requirement, and regional regulatory cluster. CAGRs were derived from procedure volume growth rates and device content per procedure assumptions. Forecast inputs incorporate ISO 10993 testing timeline friction and Mexican maquiladora expansion trajectories.
Underlying measurement precision varies by segment; diagnostic equipment and neurovascular applications carry tighter precision than commodity packaging films. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and resin supply continuity. Deviation in FDA ISO 10993-18 chemical characterization timeline extensions or German PEEK compounder allocation events would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Foam Insulation Market