
 Polyurethane Insulation Board Market | 2026-2036
Polyurethane Insulation Board Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Insulation Board Market Insights
The EU Green Deal's building renovation targets are recalibrating specification standards across European construction procurement. BASF SE leverages its integrated polyol supply chain to secure feedstock cost advantages in rigid foam formulations. Kingspan Group anchors its position through controlled distribution of pre-cut panel systems to contractor networks. Owens Corning differentiates via sustained R&D intensity in fire-resistant facing technologies for commercial envelopes.
Polyurethane insulation board comprises a rigid cellular polymer structure formed by reacting polyols with isocyanates, typically achieving thermal conductivity values between 0.022 and 0.028 W/m·K, and serves primarily to reduce energy transfer in building envelopes and industrial equipment. Polyiso dominates commercial roofing assemblies where compressive strength and dimensional stability command premium positioning. Spray Foam competes in irregular cavity applications where custom sizes from the delivery mode segment cannot achieve complete fill. The residential application category remains mature in North America while agricultural cold storage drives incremental volume in select European markets.
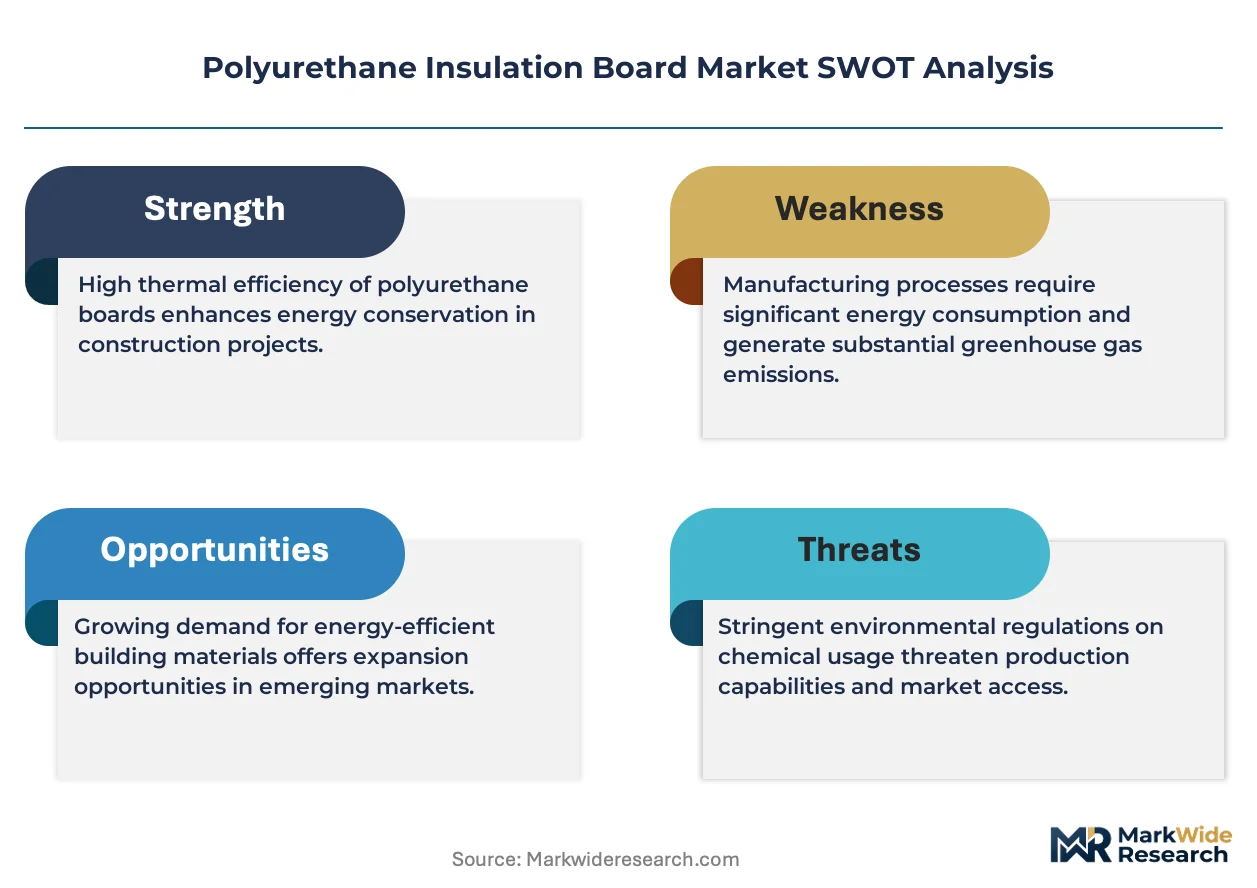
REACH restrictions on flame retardant chemistries and the F-Gas Regulation's hydrofluorocarbon quotas jointly constrain formulation flexibility for producers serving European projects. The EPA's AIM Act phase-down schedule in the United States imposes parallel compliance burdens on blowing agent transitions across the transatlantic supply base. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
The EPA's AIM Act hydrofluorocarbon phase-down is forcing wholesale reformulation of blowing agent chemistries across North American rigid foam production, compressing margins while accelerating capital deployment into next-generation low-GWP alternatives.
Growth Catalysts
- EU Green Deal building renovation targets:The framework mandates deep energy retrofits across member states, expanding specification opportunities for high-performance envelope materials in Germany, Poland, and the Czech Republic.
- Cold chain logistics expansion:Refrigerated warehouse construction in the United States and agricultural storage upgrades across France and Spain are absorbing premium-grade polyiso panels with enhanced dimensional stability.
- Passive house construction clusters:Central European building codes in Austria, Switzerland, and southern Germany are embedding ultralow thermal conductivity requirements that exclude mineral wool alternatives.
Market Restraints
- Feedstock concentration risk:MDI supply concentrates among Asian petrochemical complexes, exposing European and North American formulators to freight cost volatility and force majeure exposure.
- REACH flame retardant restrictions:ECHA's evolving substance evaluation protocols are constraining halogenated additive options, forcing costly reformulation cycles ahead of compliance deadlines.
- Spray foam substitution in irregular cavities:Open-cell and closed-cell polyurethane spray systems capture share in complex geometries where pre-fabricated board dimensions create thermal bridging risks.
Strategic Opportunities
- Agricultural cold storage underpenetration:Eastern European markets including Romania and Bulgaria retain legacy insulation in food processing facilities, creating upgrade cycles tied to EU cohesion fund access.
- Fire-resistant facing technology convergence:Integration of intumescent coatings with glass fiber mat facers is enabling single-pass assembly in commercial roofing, compressing installation labor requirements.
- Pre-cut panel distribution innovation:Direct-to-contractor digital platforms in the United States are bypassing traditional two-step distribution, capturing margin and reducing lead times for midsize roofing jobs.
Industry Challenges
- Blowing agent transition capex intensity:Converting production lines from HFC-245fa to hydroolefin alternatives requires reactor modification and safety system upgrades that strain mid-capitalization producers.
- Fire performance certification complexity:Divergent reaction-to-fire testing protocols between EN 13501-1 and ASTM E84 create duplicate testing burdens for suppliers serving transatlantic projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Insulation Board Market |
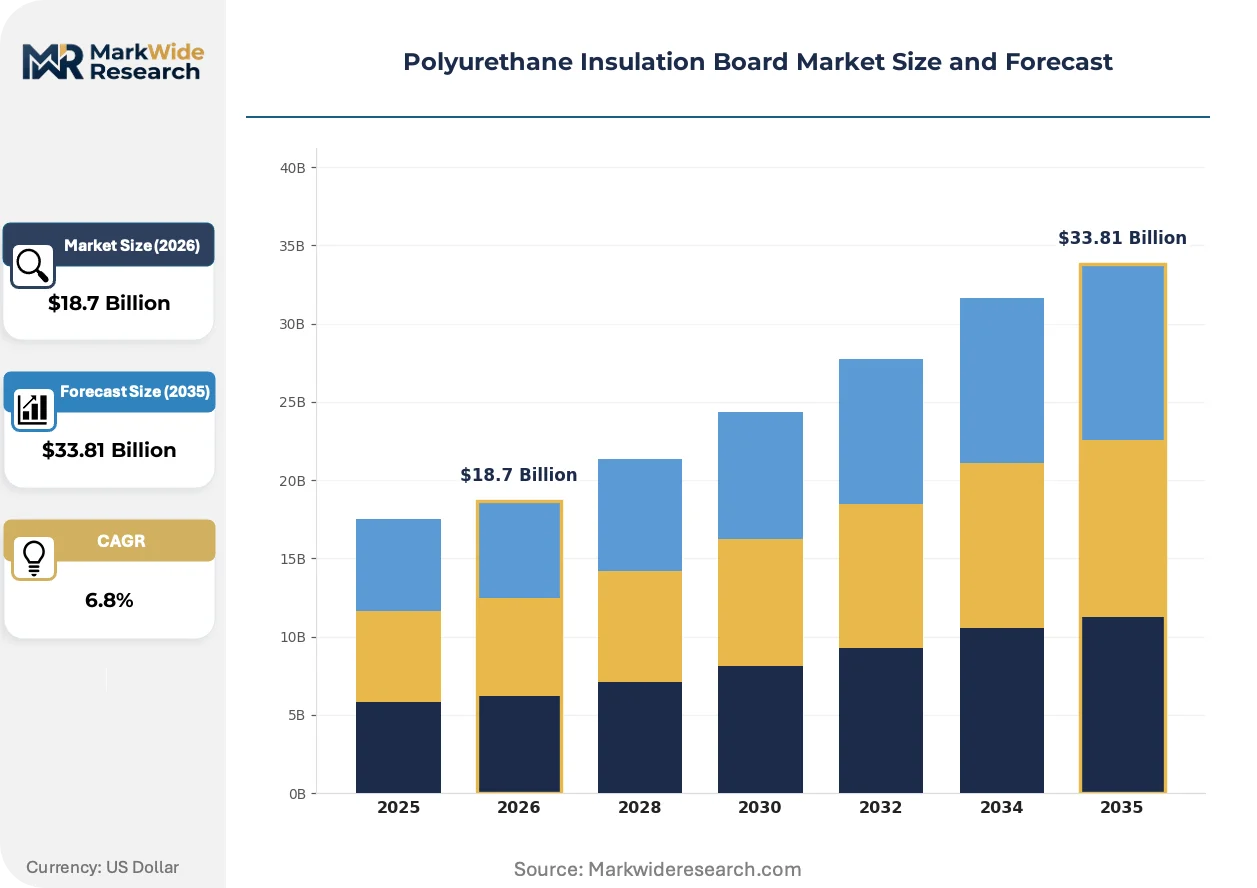
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyiso, EPS, XPS, Spray Foam Application: Residential, Commercial, Industrial, Agricultural End User: Contractors, Builders, Architects, Manufacturers Delivery Mode: Pre-cut Panels, Custom Sizes, Roll Form, Bulk Orders |
| Companies Covered | Owens Corning, Kingspan Group, BASF SE, Dow, Recticel, Johns Manville, Saint-Gobain, Huntsman Corporation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Insulation Board Market Trends and Innovations
Formulation chemistry, regulatory compliance architecture, and procurement digitization are converging to reshape competitive advantage in rigid foam insulation, compressing traditional differentiation mechanisms while elevating technical service capabilities.
Next-generation hydroolefin blowing agents are unifying thermal performance and environmental compliance in a single platform. Commercial roofing contractors in the United States are specifying these formulations at accelerating rates as EPA phase-down deadlines approach. The technology is unifying what had been a bifurcated supply base into consolidated procurement channels favoring integrated producers with captive polyol supply.
REACH restrictions on halogenated flame retardants are recalibrating formulation portfolios across European production assets. ECHA's substance evaluation roadmap is compressing the approved chemical inventory, forcing R&D redirection toward phosphorus-based and mineral alternatives. Residential and light commercial segments in Germany and Austria are absorbing premium pricing for certified low-toxicity boards as green building procurement standards tighten.
Specification authority is migrating from general contractors to envelope specialist subcontractors with direct engineering accountability. This channel compression in the United States and United Kingdom is displacing traditional distributor influence with technical sales teams capable of thermal modeling and code compliance documentation. Cold storage and data center verticals exhibit the most pronounced concentration of buying power among specialized installers.
Polyurethane Insulation Board Market Segmentation
Polyurethane insulation board procurement hinges on thermal performance thresholds, installation geometry, and regulatory compliance architecture. Specification authority migrates differently across product categories, with fire-rated assemblies demanding engineering validation while standard residential applications prioritize cost-per-R-value metrics.
Product Type:
Thermal conductivity coefficients and compressive strength specifications drive contractor selection between rigid foam alternatives.
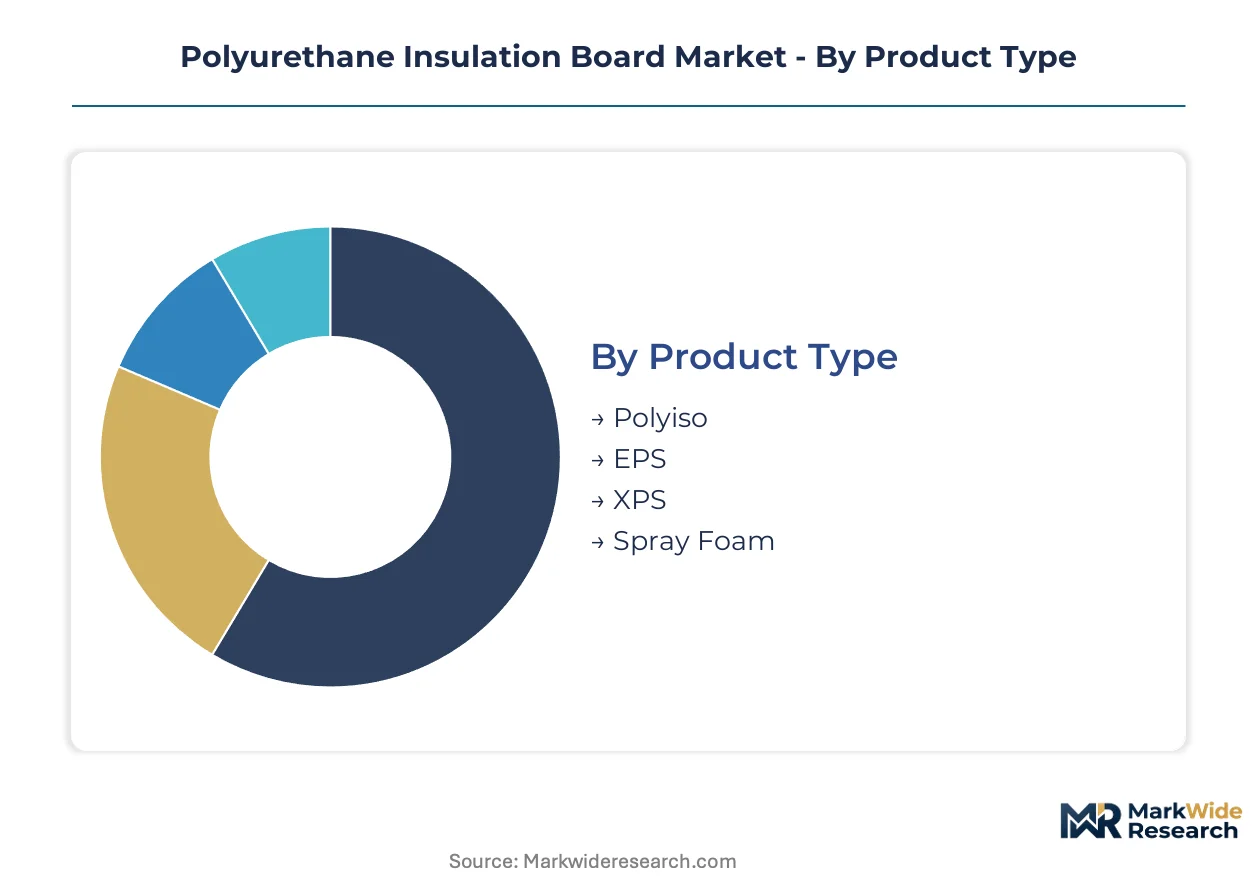
- Polyiso:Closed-cell thermoset foam achieves thermal conductivity values between 0.022 and 0.028 W/m·K, forming the dominant specification in commercial roofing assemblies across the United States where compressive strength and dimensional stability command premium positioning.
- EPS:Expanded polystyrene boards offer lower unit economics but inferior thermal resistance per inch, capturing below-grade and foundation applications in Germany's passive house construction cluster where thick wall assemblies accommodate lower R-value density.
- XPS:Extruded polystyrene delivers higher moisture resistance than EPS, serving foundation perimeters and protected membrane roofing in cold climate zones.
- Spray Foam:On-site polyurethane application fills irregular cavities completely, displacing pre-fabricated boards in complex geometries where thermal bridging risks dominate specification decisions.
Volume sits with Polyiso; growth tilts toward Spray Foam as retrofit activity accelerates in aging building stock.
Application:
Building code stringency and energy certification targets fragment demand across construction verticals with divergent performance requirements.
- Commercial:Fire-resistant facing technologies and ASTM E84 compliance dominate envelope specifications in data centers and refrigerated warehouses across the United States, with Kingspan Group and Owens Corning anchoring supply through controlled distribution networks.
- Industrial:Process equipment insulation and cold chain logistics infrastructure absorb premium-grade polyiso panels with enhanced dimensional stability in agricultural storage facilities across France and Spain.
- Residential:North American single-family construction maintains mature demand patterns, with cost-per-square-foot metrics favoring mineral wool alternatives in price-sensitive segments.
- Agricultural:Food processing facility upgrades in Romania and Bulgaria retain legacy insulation, creating replacement cycles tied to EU cohesion fund access and sanitary compliance modernization.
Commercial commands the revenue concentration; Agricultural exhibits the steepest expansion trajectory as Eastern European markets align with EU building renovation targets.
End User:
Technical accountability distribution determines specification authority and procurement channel selection.
- Contractors:Direct-to-contractor digital platforms in the United States are bypassing traditional two-step distribution, capturing margin and reducing lead times for midsize roofing jobs through pre-cut panel procurement.
- Builders:Production homebuilders prioritize standardized dimensions and volume pricing, consolidating procurement through national distribution agreements.
- Architects:Passive house certification requirements in Austria and Switzerland embed ultralow thermal conductivity specifications that exclude mineral wool alternatives from envelope designs.
- Manufacturers:OEM insulation for appliances and transportation equipment demands consistent thermal performance with batch certification documentation.
Builders move the highest tonnage; Architects drive the premium tier specification migration.
Delivery Mode:
Supply chain configuration and installation labor economics shape fulfillment modality preferences.
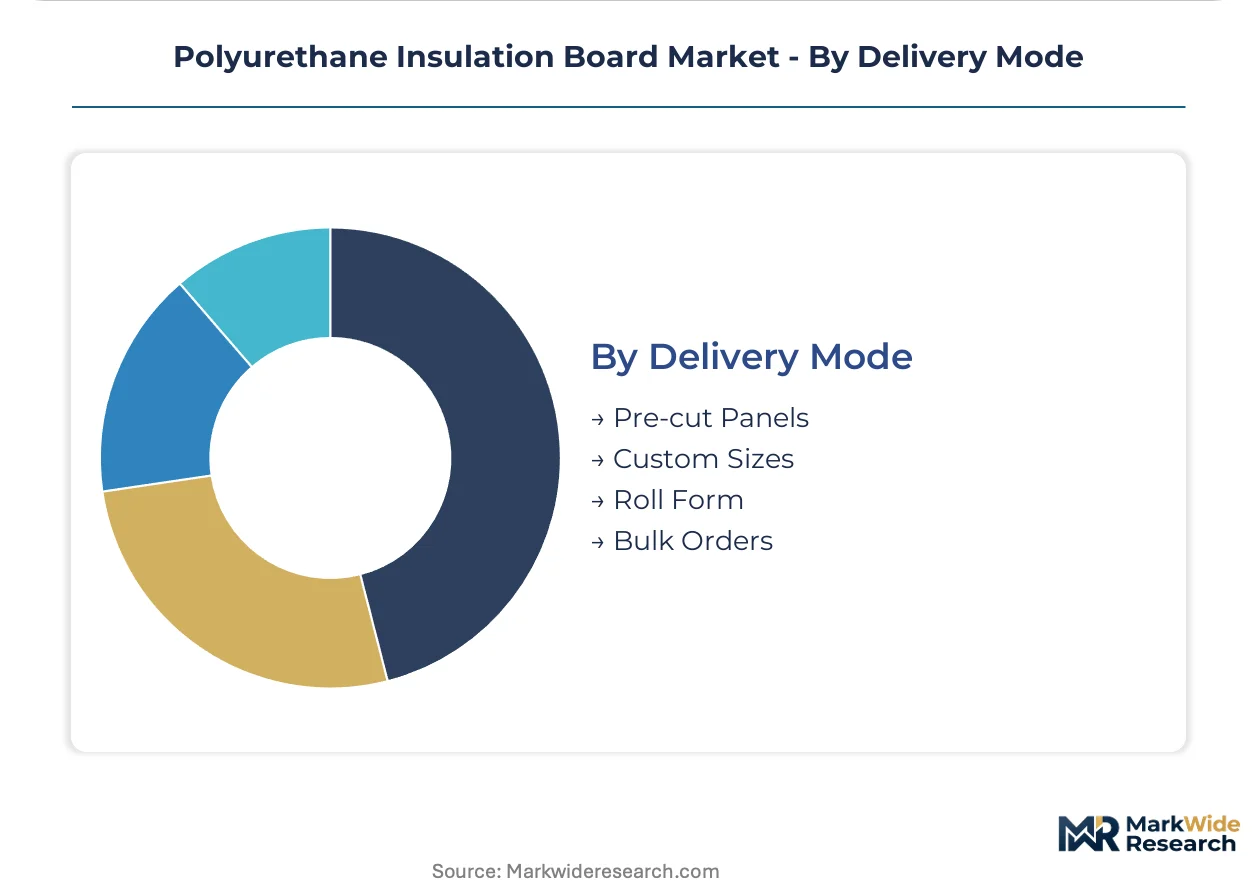
- Pre-cut Panels:Factory-dimensioned boards reduce field cutting waste and accelerate installation timelines, dominating commercial roofing contractor procurement in the United Kingdom where envelope specialist subcontractors concentrate buying power.
- Custom Sizes:Project-specific dimensional requirements serve retrofit corridors in Poland and the Czech Republic where existing building constraints demand non-standard thickness configurations.
- Roll Form:Continuous insulation applications in metal building systems favor flexible delivery formats.
- Bulk Orders:National distributor consolidation and volume pricing structures serve large-scale residential developers and industrial facility constructors with predictable demand schedules.
Bulk Orders anchor the volume base; Custom Sizes gain share fastest as deep energy retrofits expand across Central European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in German and Belgian chemical corridors while consumption tilts toward North American commercial construction and Central European deep retrofit markets. This geographic mismatch creates freight cost exposure for formulators serving transatlantic project pipelines.
United States
Commercial roofing contractors drive polyiso specification as the EPA's AIM Act hydrofluorocarbon phase-down compresses blowing agent transition timelines. Data center construction clusters in Northern Virginia and Phoenix absorb premium fire-rated panels with ASTM E84 compliance documentation. Cold chain logistics operators in California's Central Valley are expanding refrigerated warehouse footprints ahead of 2027 compliance deadlines.
Germany
Passive house construction in Bavaria and Baden-Württemberg embeds ultralow thermal conductivity requirements that exclude mineral wool from envelope specifications. The EU Green Deal's building renovation targets accelerate specification migration in Berlin's retrofit corridors. BASF SE leverages its Ludwigshafen polyol complex to secure feedstock cost advantages for rigid foam formulations serving Central European projects.
France
Agricultural cold storage upgrades in the Loire Valley and Champagne regions absorb premium-grade panels with enhanced dimensional stability. ECHA's REACH flame retardant restrictions are constraining halogenated additive options ahead of 2025 substance evaluation deadlines. Envelope specialist subcontractors in Lyon and Marseille are consolidating specification authority away from traditional distributor channels.
Poland
EU cohesion fund access is unlocking deep energy retrofit cycles in Kraków and Wrocław municipal housing stock. Custom-sized panel demand dominates procurement as existing building constraints resist standardized dimensions. The F-Gas Regulation's hydrofluorocarbon quotas are forcing blowing agent transitions ahead of neighboring member state schedules.
Spain
Food processing facility modernization in Catalonia and Andalusia is replacing legacy insulation tied to sanitary compliance upgrades. Agricultural storage construction in the Ebro Valley is absorbing volume-grade polyiso with cost-per-R-value procurement metrics. The country's national building energy efficiency regulator is tightening envelope performance coefficients for commercial permits.
Polyurethane Insulation Board Market Competitive Landscape
The competitive structure tilts toward integrated chemical producers with captive polyol supply and specialized building envelope fabricators with controlled distribution networks. Mid-capitalization formulators face margin compression from feedstock volatility and blowing agent transition capex requirements. Two strategic archetypes dominate: multinational chemical conglomerates with backward integration into isocyanate production, and regional panel fabricators with pre-cut customization capabilities. Capacity expansion and fire-resistant facing technology licensing represent the dominant competitive moves across both tiers.
Among integrated chemical producers, BASF SE and Covestro AG exemplify the upstream-controlled archetype with in-house polyol and isocyanate production assets. Owens Corning occupies a position on the premium-tier vector through sustained R&D intensity in fire-resistant facing technologies for commercial envelope applications. Kingspan Group anchors the specialized fabricator segment through controlled distribution of pre-cut panel systems to contractor networks in the United Kingdom and North America.
| Leading Market Players |
|---|
| Owens Corning |
| Kingspan Group |
| BASF SE |
| Dow |
| Recticel |
| Johns Manville |
| Saint-Gobain |
| Huntsman Corporation |
| Covestro AG |
| Others |
Pricing and Supply Chain Analysis
Hydroolefin blowing agent transitions across North American and European production assets are simultaneously elevating capital intensity and consolidating procurement channels toward integrated producers with captive polyol supply. This technical migration compresses margins for mid-capitalization formulators while rewarding backward-integrated chemical conglomerates with pricing power in premium-grade rigid foam segments.
Pricing Analysis
Margin tightening in standard-grade polyiso reflects feedstock volatility in MDI supply chains and the capital burden of reactor modifications for low-GWP compliance. Pricing stratifies across premium, standard, and economy tiers based on fire-resistance certification grade and customization level. Cost compression accelerates in residential segments as mineral wool alternatives capture price-sensitive volume. Commercial roofing contractors exhibit the lowest price sensitivity, prioritizing ASTM E84 documentation and dimensional stability over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Belgium, and the United States anchor hub-and-spoke fulfillment patterns for pre-cut panel systems. Production concentrates in German and Belgian chemical corridors, drawing from MDI feedstocks sourced from Asian petrochemical complexes and polyol streams from integrated Ludwigshafen assets. Single-source vulnerability in isocyanate supply exposes European and North American formulators to freight cost volatility and force majeure disruption. Distribution runs through controlled contractor networks and direct-to-installer digital platforms, displacing traditional two-step wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyurethane insulation board market functions as a cost-of-compliance arena where the EPA's AIM Act hydrofluorocarbon phase-down and the EU F-Gas Regulation construct regulatory moats favoring capitalized incumbents with integrated supply chains.
For Market Incumbents: Acquire regional panel fabrication assets in Eastern European retrofit corridors to secure proximity to EU cohesion fund deployment. Consolidate specification authority through pre-cut customization capabilities and fire-resistant facing technology licensing. Spray foam substitution in irregular cavity applications threatens rigid board volume; defend position by embedding technical sales teams with thermal modeling expertise in envelope specialist subcontractor networks. For New Entrants and Emerging Players: The EU Green Deal's building renovation targets in Poland and the Czech Republic open a window for custom-sized panel specialists serving deep energy retrofit cycles. Agricultural cold storage underpenetration in Romania and Bulgaria offers white-space expansion tied to sanitary compliance modernization. Pursue direct-to-contractor digital platforms bypassing traditional distribution markups, capturing margin compression opportunities in midsize commercial roofing procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking regional panel fabrication footprints. Long-term viability favors targets with captive polyol supply or licensed fire-resistant facing technology. The signal to watch is EPA enforcement intensity on hydrofluorocarbon phase-down timelines, which will accelerate distressed asset availability among non-compliant mid-capitalization formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Captive feedstock production insulates BASF and Covestro from MDI price volatility in European formulations. |
| Fire-Resistant Facing Technology Licensing | Intumescent coating integration enables Owens Corning to capture premium positioning in ASTM E84-compliant commercial roofing. |
| Pre-cut Panel Distribution Platform | Kingspan's direct-to-contractor channels compress lead times and displace traditional two-step wholesale markups. |
| Low-GWP Blowing Agent Transition | Hydroolefin formulation investments align production with EPA AIM Act deadlines and EU F-Gas Regulation quotas. |
| Eastern European Capacity Expansion | Proximity to Poland and Czech retrofit corridors reduces freight exposure to Central European demand clusters. |
Research Methodology
Independent corroboration across regulatory filings, customs trade data, and industry association disclosures underwrites the qualitative findings in this study. Primary interviews with rigid foam plant managers, commercial roofing procurement leads, envelope specialist subcontractors, and ECHA regulatory affairs directors combined with secondary validation from EPA AIM Act implementation documents, EU F-Gas Regulation compliance databases, and SEC 10-K filings. Bottom-up volume estimates from installation activity and top-down cross-checks against chemical feedstock consumption established analytical triangulation.
Comparable-period anchoring to historical blowing agent transition cycles and building code adoption timelines structured the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, application vertical, end-user procurement channel, and regional regulatory cluster. CAGRs derived from polynomial trend fitting against retrofit penetration curves and cold chain logistics construction permits. Industry-specific inputs incorporated REACH substance evaluation roadmaps and EPA enforcement intensity projections.
The model assumes a particular technology adoption path; alternative pathways for hydroolefin blowing agent thermal performance would alter the outlook for mid-capitalization formulator viability. Forecasts reflect documented assumptions on regulatory phase-down schedules and feedstock supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Tooling Board Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market