
 Middle-East and Africa Engineering Plastics Market | 2026-2036
Middle-East and Africa Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Engineering Plastics Market Foresight
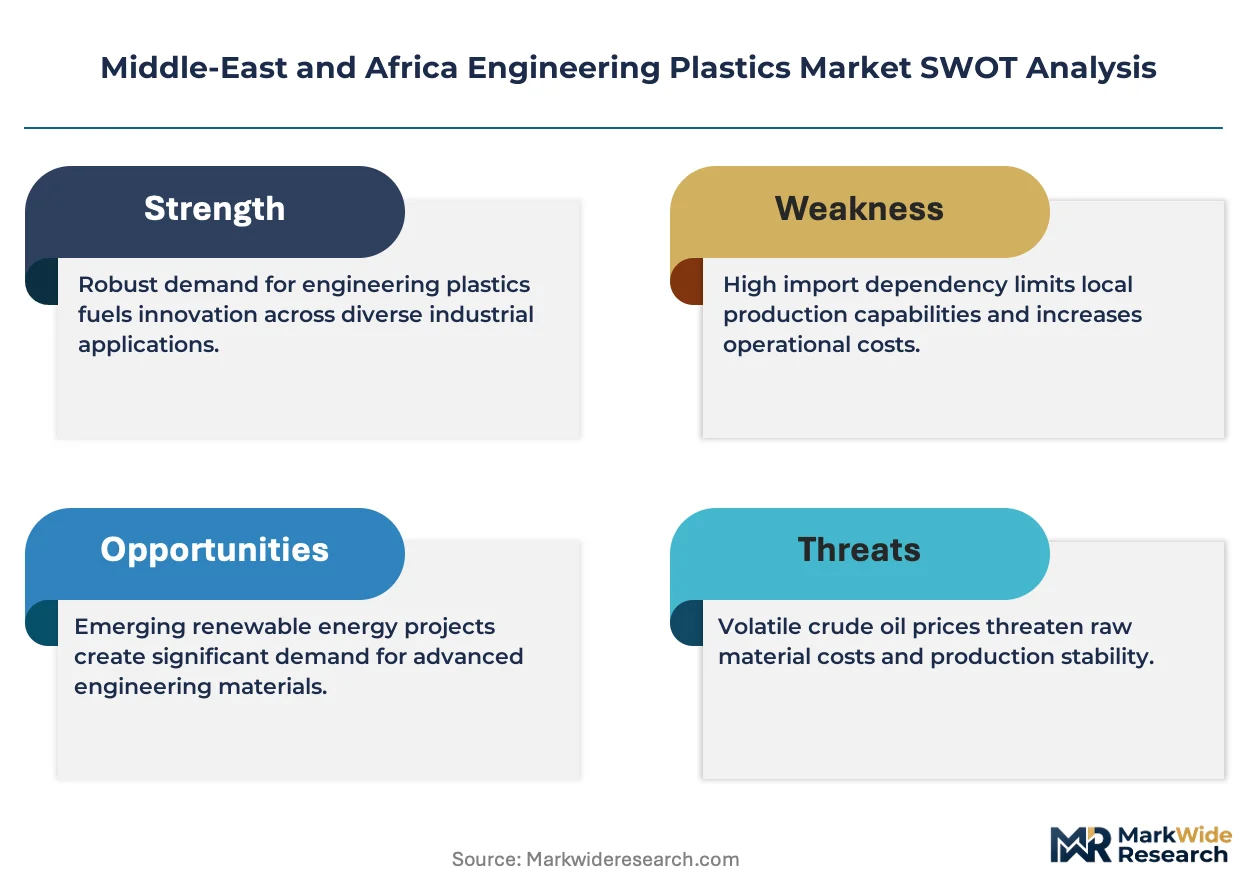
Modular component bundling is hardening as the dominant procurement pattern across Middle-East and Africa engineering plastics buyers, with automotive and electronics OEMs specifying pre-compounded grades with integrated additive packages rather than sourcing base resins and modifiers separately. SABIC leverages its captive feedstock position at Jubail and Yanbu to dominate regional polycarbonate and polypropylene supply. BASF SE anchors its position through specialty nylon grades tailored for Gulf construction applications requiring UV and thermal resistance. DuPont competes on high-performance polyoxymethylene formulations aimed at precision industrial parts in South African manufacturing.
Middle-East and Africa engineering plastics comprise thermoplastic polymers with mechanical strength exceeding 40 MPa tensile strength and continuous service temperatures above 100°C, produced through melt polycondensation or catalytic polymerization processes to replace metals in load-bearing applications. Polycarbonate leads product-type value generation due to optical clarity requirements in electronics housings and aerospace glazing across Dubai and Riyadh industrial zones. Nylon captures expanding share in automotive components, particularly glass-filled grades for engine bay applications where South African assemblers specify localized supply. Polyoxymethylene maintains premium positioning in industrial parts requiring low friction coefficients and dimensional stability under cyclic loading.
Saudi Arabia's SFDA enforces polymer contact-grade certification for food-processing and medical device applications, while the UAE's national standards body mandates flame-retardancy testing under Gulf Technical Regulation schemes for construction materials. South Africa's National Regulator for Compulsory Specifications enforces automotive material homologation aligned with UN ECE protocols, restricting uncertified imports. Stakeholders must monitor evolving Gulf Cooperation Council harmonization of polymer standards and assess localized compounding investments against import duty structures.
Market Dynamics
Modular component bundling now dominates procurement across Middle-East and Africa engineering plastics, with automotive and electronics OEMs demanding pre-compounded grades that integrate additives, colorants, and reinforcements into single-source supply agreements rather than managing multiple resin and modifier vendors.
Growth Catalysts
- SFDA polymer certification mandates:Saudi Arabia's tightening food-contact and medical-grade polymer standards are forcing domestic compounders to upgrade quality systems, creating captive demand for certified engineering plastics in packaging and healthcare devices.
- Automotive under-hood specifications:Glass-filled nylon grades specified by South African vehicle assemblers for engine bay components are displacing metal stampings in localized supply chains.
- Jubail-Yanbu feedstock integration:Saudi petrochemical complexes provide regional compounders with cost-advantaged polycarbonate and polypropylene feedstock, anchoring export competitiveness to African and Levantine buyers.
Market Restraints
- Acrylonitrile price volatility:ABS and specialty nylon compounders face margin compression when benzene and propylene derivatives spike, with limited hedging instruments available in regional commodity markets.
- Concentrated polycarbonate supply:SABIC's dominance at Yanbu creates single-source risk for optical-grade polycarbonate buyers in UAE aerospace and electronics clusters.
- Homologation timeline friction:South Africa's NRCS automotive material certification aligned with UN ECE protocols extends qualification cycles to 18-24 months, blocking rapid product substitution.
Strategic Opportunities
- Egyptian manufacturing expansion:Suez Canal Economic Zone industrial parks attract compounders serving North African appliance and automotive wire-harness markets with duty-advantaged export positioning.
- Flame-retardant construction mandates:UAE Gulf Technical Regulation schemes for building materials create specification pull for halogen-free polycarbonate and PBT grades in high-rise glazing and electrical conduit.
- Recycled-content integration:Mechanical recycling of post-industrial polycarbonate scrap from Dubai electronics manufacturing is converging with virgin compounding to meet emerging buyer sustainability criteria.
Industry Challenges
- Compounding technician scarcity:Regional polymer engineering programs graduate fewer than 200 specialists annually, forcing compounders to import Egyptian and Indian talent for twin-screw extrusion and quality lab functions.
- Multi-standard certification burden:Suppliers serving both Saudi SFDA medical-grade and UAE construction flame-retardancy regimes must maintain parallel testing protocols, doubling quality assurance overhead.
- Legacy ERP integration:Mid-sized compounders in South Africa and Morocco struggle to connect batch-level traceability systems with automotive OEM supplier portals, delaying qualification for just-in-sequence delivery contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Engineering Plastics Market |
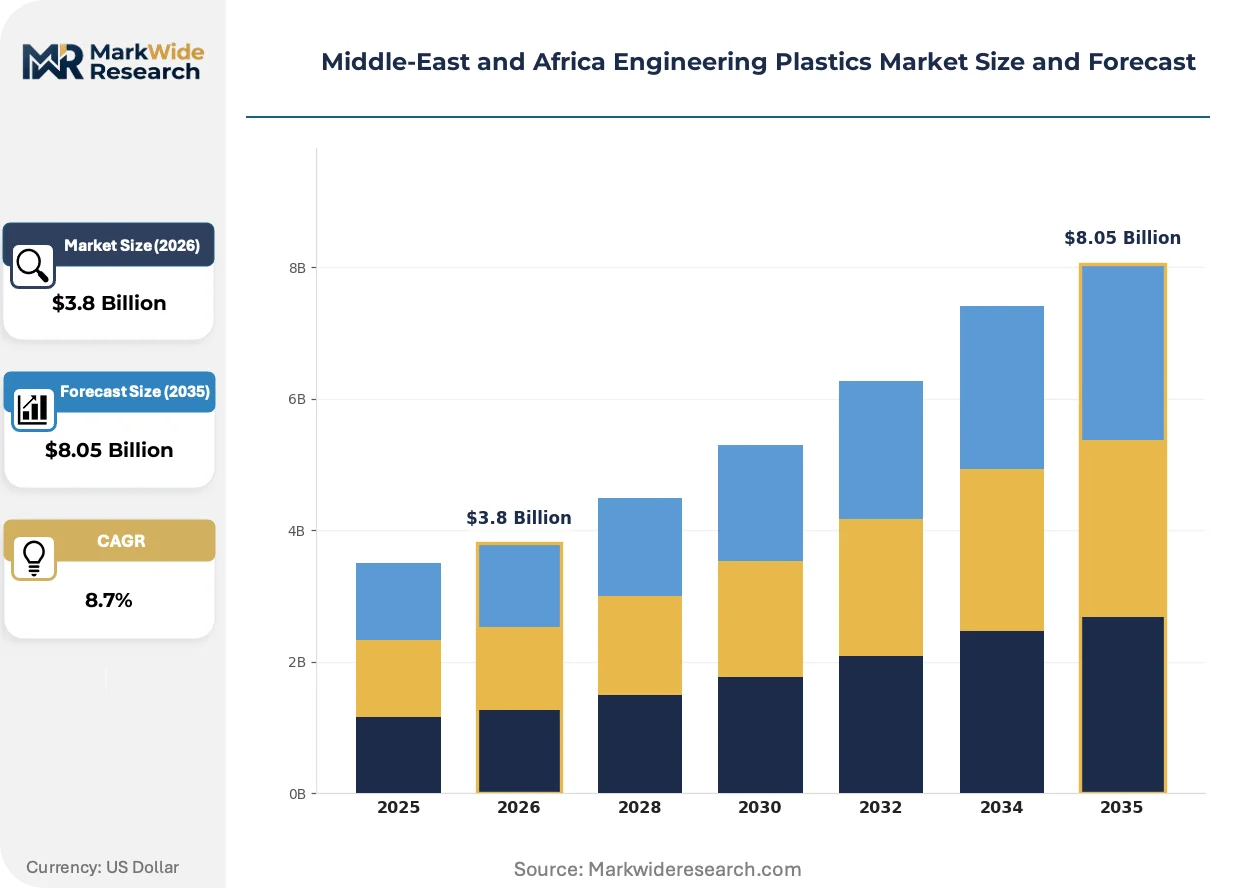
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Nylon, Polypropylene, Polyoxymethylene End User: Aerospace, Electronics, Construction, Automotive Application: Electrical Insulation, Automotive Components, Consumer Goods, Industrial Parts Form: Injection Molding, Extrusion, 3D Printing, Compounding |
| Companies Covered | SABIC, BASF SE, DuPont, Covestro AG, Solvay, Alfa S.A.B. de C.V., IVL Dhunseri Petrochem Industries Private Limited, Borouge PJSC, Celanese Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Engineering Plastics Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are compressing product development cycles across Middle-East and Africa engineering plastics, with compounders investing in co-development partnerships rather than specification-selling to secure long-term supply agreements.
Long-fiber thermoplastic (LFT) direct compounding is rewriting structural metal replacement economics in automotive and industrial applications. Tier-1 suppliers in South Africa and Turkey are adopting in-line LFT extrusion for bumper beams and under-body shields, cutting pellet inventory and enabling part-specific fiber length optimization. This technology is compressing the cost gap between compression-molded SMC and injection-molded engineering plastics in medium-volume production runs.
UAE's Gulf Technical Regulation for construction material flame-retardancy is forcing reformulation of polycarbonate and ABS grades used in high-rise glazing and electrical distribution. Compounders serving Dubai and Riyadh projects must now certify to EN 13501-1 reaction-to-fire classes, displacing legacy UL-94 testing for premium building contracts. Electrical conduit and LED housing manufacturers are accelerating halogen-free phosphorous-nitrogen flame retardant adoption to maintain specification eligibility.
Specification-driven consolidation among procurement functions at Gulf automotive and electronics OEMs is compressing vendor lists and elevating technical service expectations. Buyers in Jebel Ali free zones now require compounders to maintain localized application development labs with injection molding simulation and failure analysis capability, displacing pure trading relationships. This pattern concentrates contract awards with SABIC, BASF, and regional compounders maintaining Dubai or Johannesburg technical centers.
Middle-East and Africa Engineering Plastics Market Segmentation
Engineering plastics procurement in the Middle-East and Africa clusters around material specifications that satisfy divergent regulatory regimes across Saudi Arabia, the UAE, and South Africa. Compounders must align product portfolios with end-use certification requirements rather than generic resin grades.
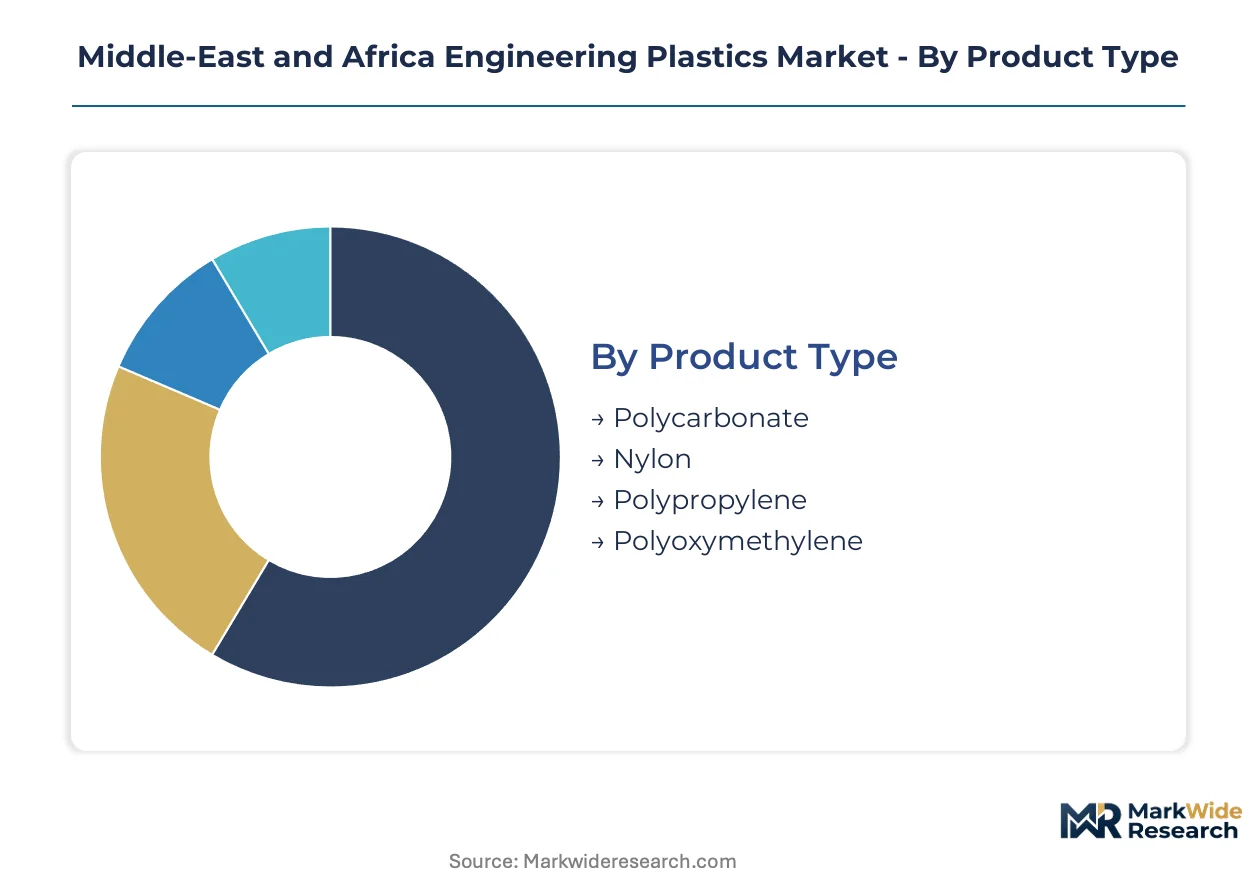
Product Type:
Capital intensity varies sharply across polymer chemistries, with melt polycondensation processes demanding substantially higher upfront investment than catalytic olefin routes.
- Polycarbonate:Aromatic carbonate-linked thermoplastic produced via interfacial or melt-phase polymerization, delivering optical clarity above 90% light transmission. Demand concentrates in Dubai and Riyadh electronics manufacturing clusters, where aerospace glazing and LED housing specifications require flame-retardant grades certified to Gulf Technical Regulation schemes. High-purity optical grades command premium positioning due to SABIC's concentrated supply position at Yanbu.
- Nylon:Polyamide family synthesized through condensation of diamines and dicarboxylic acids, with glass-filled grades achieving tensile strengths exceeding 80 MPa. South African automotive assemblers specify localized supply for engine bay components, displacing metal stampings in under-hood applications where thermal resistance above 150°C is mandatory. Aliphatic grades dominate volume; aromatic variants serve high-heat electrical insulation.
- Polypropylene:Isotactic polymer produced via Ziegler-Natta or metallocene catalysis, offering the lowest capital barrier to entry among engineering thermoplastics. Long-fiber reinforced grades from Jubail feedstock anchor automotive bumper beam applications.
- Polyoxymethylene:Formaldehyde-based homopolymer and copolymer grades delivering exceptional dimensional stability and low friction coefficients. Precision industrial parts in South African manufacturing specify these formulations for gear and bearing applications under cyclic loading.
Polycarbonate absorbs the bulk of installed capacity; nylon is expanding most quickly.
End User:
Customer concentration patterns split between specification-driven OEMs with captive technical service requirements and price-sensitive distributors serving fragmented downstream fabrication.
- Aerospace:Cabin interior and structural glazing applications in Dubai and Riyadh industrial zones demand optical-grade polycarbonate with traceable batch certification. Emirates and Saudia maintenance programs specify localized compounder technical centers for failure analysis support.
- Electronics:Housing and connector applications across Jebel Ali free-zone manufacturing clusters drive demand for halogen-free flame-retardant grades. LED lighting manufacturers in the UAE face Gulf Technical Regulation mandates for reaction-to-fire testing under EN 13501-1 protocols.
- Construction:High-rise glazing and electrical conduit applications in the UAE and Saudi Arabia require certified flame-retardancy performance. Polycarbonate and PBT grades displace legacy materials as building codes tighten across Gulf Cooperation Council jurisdictions.
- Automotive:South African vehicle assemblers specify glass-filled nylon for localized engine bay component supply, with homologation timelines extending 18-24 months under NRCS protocols aligned with UN ECE standards.
Automotive commands the deepest technical service relationships; electronics is climbing the fastest.
Application:
Performance requirements stratify by mechanical load, thermal exposure, and electrical property demands, with each application imposing distinct compounding expertise barriers.
- Electrical Insulation:High-dielectric-strength nylon and PBT grades serve transformer housings and connector systems across Saudi utility infrastructure projects. SFDA certification requirements for medical-grade electrical devices add parallel testing protocols for compounders serving healthcare equipment manufacturers.
- Automotive Components:Glass-filled nylon and long-fiber thermoplastic grades displace metal in under-hood and structural applications. South African assemblers prioritize localized supply chains to mitigate currency volatility and import duty exposure.
- Consumer Goods:Appliance housings and power tool components in North African markets favor cost-optimized polypropylene and ABS blends. Egyptian manufacturing expansion in the Suez Canal Economic Zone attracts compounders serving duty-advantaged export positioning.
- Industrial Parts:Polyoxymethylene formulations deliver low-friction, wear-resistant performance for precision gears and conveyor components. South African mining equipment maintenance programs specify these grades for replacement part fabrication.
Automotive components absorb the bulk of installed capacity; electrical insulation is gaining share fastest.
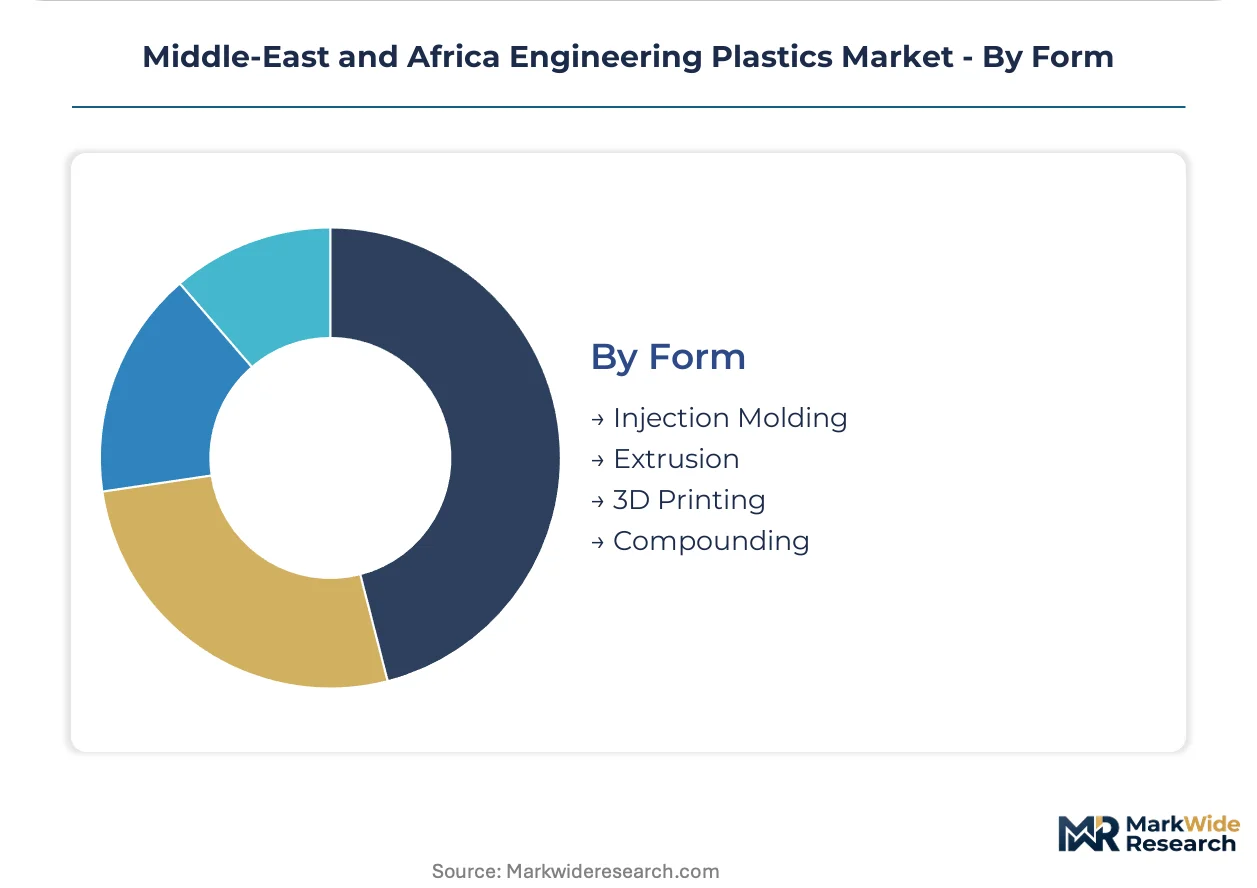
Form:
Processing technology selection determines compounder equipment investment and technical staffing requirements, with twin-screw extrusion lines representing the highest capital commitment.
- Injection Molding:Pelletized grades optimized for high-cavitation tooling dominate electronics and automotive volume production. Dubai and Johannesburg technical centers maintain injection molding simulation capability to support OEM qualification programs.
- Extrusion:Sheet, profile, and film grades serve construction glazing and electrical conduit applications. UAE flame-retardant mandates are forcing reformulation of legacy polycarbonate extrusion recipes.
- 3D Printing:Filament and powder formulations for fused deposition modeling and selective laser sintering address prototyping and low-volume production in aerospace and medical device development. Material qualification protocols remain underdeveloped across regional standards bodies.
- Compounding:Custom additive integration—reinforcements, stabilizers, colorants—into base resins represents the highest value-add segment. Regional technician scarcity forces compounders to import Egyptian and Indian talent for twin-screw extrusion operations.
Injection molding absorbs the bulk of installed capacity; compounding is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Saudi Arabia's Jubail-Yanbu petrochemical corridor while consumption spreads across Gulf manufacturing clusters and South African automotive assembly zones. This geographic split shapes logistics costs and localized compounding investments.
Saudi Arabia
SFDA polymer certification mandates for food-contact and medical-grade applications drive domestic compounder quality upgrades. The national standards body enforces construction-grade polymer testing aligned with Gulf Technical Regulation schemes. Yanbu industrial city anchors polycarbonate production serving UAE aerospace glazing and electronics housing demand.
United Arab Emirates
Petrochemical feedstock access and free-zone manufacturing clusters attract compounders serving regional aerospace and electronics buyers. MOHAP and the national standards body mandate flame-retardancy testing under Gulf Technical Regulation schemes for construction materials. Jebel Ali free-zone technical centers maintain injection molding simulation capability for OEM qualification programs.
South Africa
Automotive manufacturers specify glass-filled nylon grades for localized engine bay component supply. The National Regulator for Compulsory Specifications enforces automotive material homologation aligned with UN ECE protocols. Durban and Johannesburg industrial corridors concentrate compounding capacity for mining equipment and vehicle assembly supply chains.
Egypt
Suez Canal Economic Zone industrial parks attract compounders serving North African appliance and automotive wire-harness markets. Duty-advantaged export positioning to Levantine and sub-Saharan buyers drives foreign direct investment. Cairo-Alexandria manufacturing corridor concentrates polypropylene compounding for consumer goods and power tool housing production.
Turkey
Long-fiber thermoplastic direct compounding adoption rewrites structural metal replacement economics in automotive applications. Istanbul and Bursa industrial zones serve as export gateways to Central Asian and Caucasus markets. Tier-1 suppliers adopt in-line LFT extrusion for bumper beams and under-body shields, cutting pellet inventory costs.
Middle-East and Africa Engineering Plastics Market Competitive Landscape
The competitive structure tilts toward petrochemical-integrated majors with captive feedstock positions. SABIC dominates regional polycarbonate and polypropylene supply through Yanbu production assets, while European and North American specialty compounders anchor premium-grade segments through localized technical service centers. Three archetypes populate the market: integrated petrochemical producers with backward feedstock control, global specialty material suppliers with application development labs, and regional compounders serving price-sensitive fabrication markets. Dominant competitive moves include strategic partnerships with automotive OEMs for just-in-sequence supply contracts and geographic expansion through Dubai and Johannesburg technical center investments.
Among petrochemical-integrated producers, SABIC anchors supply security for optical-grade polycarbonate buyers in UAE aerospace clusters. BASF SE and DuPont occupy positions within the specialty-grade tier, with the former representing European technical service capabilities and the latter exemplifying high-performance formulation expertise. Covestro AG and Solvay sit alongside these anchors as additional specialty material suppliers, though the analysis focuses on the three named entities as representative archetypes. Regional compounders such as Borouge PJSC exemplify the mid-tier position, leveraging proximity to Gulf manufacturing demand without fully integrated feedstock positions.
| Leading Market Players |
|---|
| SABIC |
| BASF SE |
| DuPont |
| Covestro AG |
| Solvay |
| Alfa S.A.B. de C.V. |
| IVL Dhunseri Petrochem Industries Private Limited |
| Borouge PJSC |
| Celanese Corporation |
| Others |
Supply & Pricing Matrix
Long-fiber thermoplastic direct compounding is compressing pellet inventory economics while simultaneously redrawing supply concentration maps across Middle-East and Africa engineering plastics, as in-line extrusion adoption in Turkish and South African automotive clusters cuts intermediate compounder margins and shifts bargaining power toward feedstock-integrated producers.
Pricing Analysis
Margin tightening in standard-grade polypropylene reflects SABIC's captive feedstock position at Yanbu, which anchors regional cost floors. Three-tier pricing structure across optical-grade polycarbonate, glass-filled nylon, and commodity polypropylene separates specification-driven aerospace buyers from price-sensitive appliance manufacturers. Cost-down pressure on construction-grade compounds accelerates as UAE flame-retardancy mandates force reformulation investments. Electronics OEMs in Jebel Ali free zones exhibit lowest price sensitivity due to technical service requirements, while North African consumer goods fabricators drive hardest bargain on volume contracts.
Supply Chain Analysis
Single-source vulnerability sits with polycarbonate optical-grade supply concentrated at Yanbu, where SABIC's production assets feed UAE aerospace and electronics clusters. Geographic supply concentration centers on Saudi Arabia, South Africa, and Turkey, with Egyptian Suez Canal expansion emerging as a fourth node. Raw material dependencies draw from benzene and propylene derivatives for ABS and specialty nylon, formaldehyde feedstock for polyoxymethylene, and bisphenol-A for polycarbonate. Supply chain risk traces to acrylonitrile price volatility with limited regional hedging instruments. Distribution runs through Dubai and Johannesburg technical centers serving OEM direct procurement, with fragmented North African markets served via distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Saudi SFDA polymer certification mandates erect barrier-to-entry moats favoring compounders with quality system investments already amortized.
For Market Incumbents: Cement feedstock integration advantages through backward control over polycarbonate and polypropylene supply chains at Jubail-Yanbu, while simultaneously hardening technical service capabilities in Dubai and Johannesburg to defend against emerging Turkish LFT compounders. Priority lever sits with multi-standard certification infrastructure serving parallel Saudi SFDA medical-grade and UAE construction flame-retardancy regimes. For New Entrants and Emerging Players: Halogen-free flame-retardant formulation expertise offers the most penetrable wedge into UAE construction materials procurement, where Gulf Technical Regulation EN 13501-1 certification gaps persist among mid-tier compounders. Target Egyptian Suez Canal Economic Zone manufacturing parks for duty-advantaged export positioning to Levantine and sub-Saharan appliance markets. Go-to-market angle centers on co-development partnerships with LED housing and electrical conduit manufacturers seeking localized supply alternatives. For Investors and Strategic Acquirers: Exit pathways concentrate in technical-service-enabled compounders with automotive OEM qualification credentials, where just-in-sequence supply contracts generate sticky revenue streams. Long-term viability favors assets with demonstrated batch traceability ERP integration and captive feedstock arrangements. Signal to watch is Gulf Cooperation Council regulatory harmonization momentum, which would compress multi-standard compliance overhead and reward scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | SABIC's Yanbu polycarbonate assets anchor cost competitiveness for UAE aerospace glazing demand. |
| Localized Technical Center Investment | Dubai and Johannesburg labs with injection molding simulation capability secure OEM qualification contracts. |
| Multi-Standard Certification Infrastructure | Parallel SFDA medical-grade and UAE flame-retardancy testing protocols defend against import competition. |
| Long-Fiber Thermoplastic Direct Compounding | In-line extrusion adoption in Turkish automotive clusters cuts pellet inventory and metal replacement costs. |
| Suez Canal Economic Zone Manufacturing Footprint | Egyptian industrial parks attract compounders serving duty-advantaged North African appliance export markets. |
Research Methodology
Document review covered customs and trade flow databases, petrochemical industry association reports, and national standards body regulatory filings, complemented by interviews with compounder plant managers, automotive Tier 1 procurement leads, aerospace material qualification engineers, and construction project specification consultants. Secondary validation drew from Saudi SFDA certification registries, UAE Gulf Technical Regulation implementation guidance, South African NRCS automotive homologation protocols, and SEC filings from publicly traded material suppliers. Bottom-up demand modeling triangulated against top-down petrochemical capacity assessments.
Historical volume trajectories cross-referenced against panel input from procurement executives at Dubai and Riyadh industrial clusters to generate segment-level projections across the analysis window. Segmentation dimensions modeled include polymer chemistry grade, end-use industry vertical, processing form factor, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand curves incorporating automotive production forecasts and construction permitting activity. Industry-specific inputs encompassed acrylonitrile price volatility indices and SFDA certification timeline data.
Several conditions sit outside the modeled scope, including potential Gulf Cooperation Council tariff harmonization shifts, currency devaluation scenarios affecting South African import parity, and breakthrough bio-based polymer substitutions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Vinyl Extrusion Equipment Market
Industrial Materials
Metal Molds Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Lip Seals Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Steel Cord Market
Industrial Materials
Silica Fume Market