
 Warehouse Automation Equipment Market | 2026-2036
Warehouse Automation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Warehouse Automation Equipment Market Insights
Buyer concentration among third-party logistics providers is hardening as DHL Supply Chain and GXO Logistics consolidate multi-site automation contracts across North America and Europe. Daifuku Co., Ltd. leverages its vertical integration in semiconductor cleanroom logistics to anchor premium positioning in Asia-Pacific electronics distribution. Dematic sustains technology leadership in shuttle-based storage systems for grocery and general merchandise verticals. SSI Schaefer AG specializes in modular software architectures that allow phased retrofitting of existing brownfield warehouses without full operational shutdowns.
Warehouse automation equipment encompasses electromechanical systems, control software, and sensor networks designed to execute material movement, storage, retrieval, and sorting with minimal human intervention, typically operating at throughput rates exceeding 1,000 picks per hour in high-density configurations. The primary purpose is to compress order cycle times, reduce picking error rates below 0.1%, and optimize cubic space utilization in distribution facilities facing labor scarcity and velocity pressures. Automated Storage and Retrieval Systems dominate capital deployment in ambient and cold-chain environments where vertical space exceeds 40 feet and pallet-level inventory turnover demands continuous crane operation. Robotics Arms represent the fastest-expanding product category, driven by piece-picking advances in machine vision and compliant gripping that extend automation from cases to individual SKUs in apparel, pharmaceuticals, and consumer electronics.
The EU Machinery Directive and ISO 10218-1/2 robot safety standards mandate risk assessments, protective measures, and documented conformity for autonomous mobile robots and articulated arms deployed in collaborative human-machine zones. OSHA lockout/tagout regulations and ANSI/RIA R15.06 in the United States impose additional guarding and training requirements that lengthen sales cycles but create compliance differentiation among vendors with certified integration protocols. Stakeholders must monitor divergence between European CE marking requirements and emerging state-level warehouse safety legislation in California and New York, as regulatory fragmentation threatens to multiply certification costs for equipment vendors serving multinational customers.
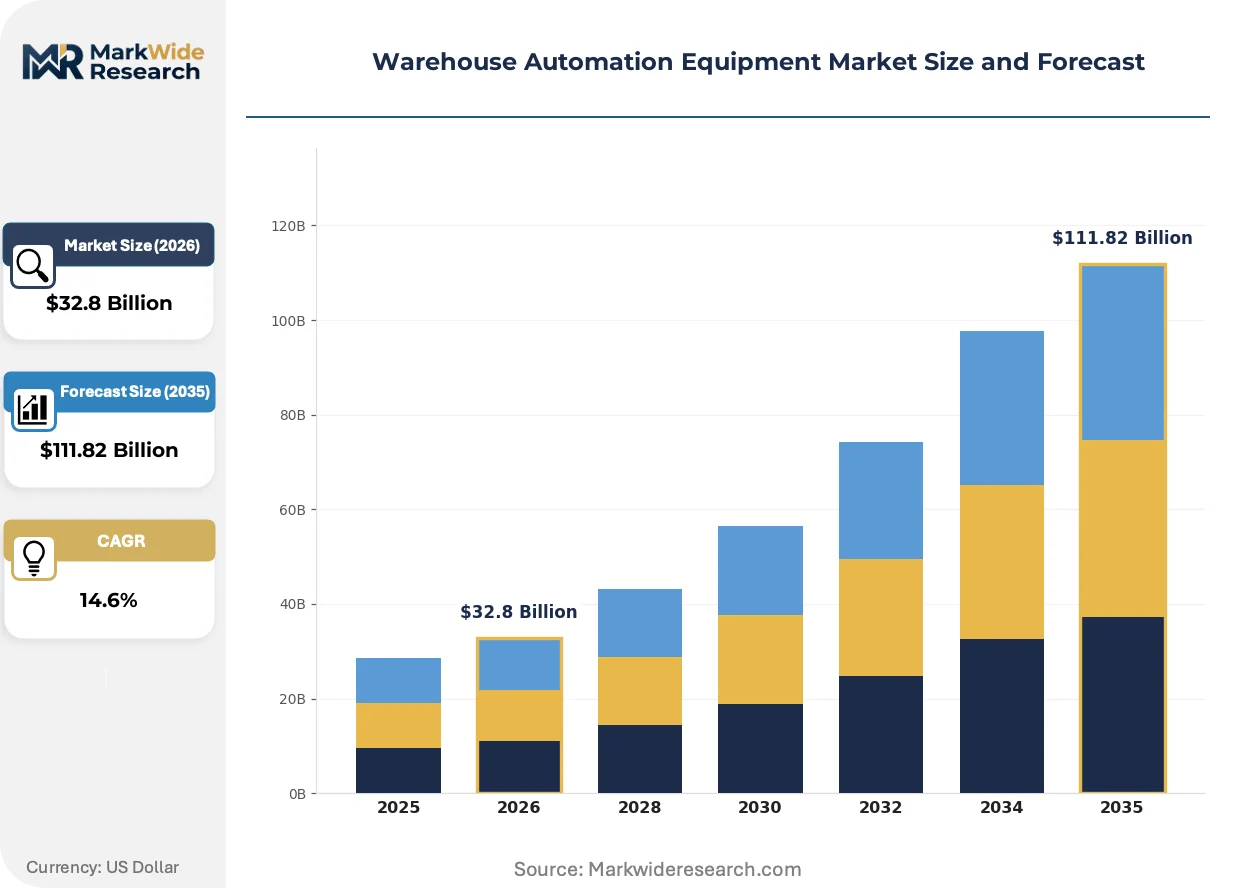
Market Dynamics
E-commerce fulfillment velocity requirements are compressing order cycle times from days to hours, forcing warehouse operators to prioritize robotic piece-picking and shuttle-based storage over conventional forklift operations. This structural pressure is reshaping capital allocation across distribution networks.
Growth Catalysts
- ISO 10218 Robot Safety Standards:Harmonized CE marking requirements under the EU Machinery Directive are reducing certification friction for autonomous mobile robots, accelerating cross-border deployment in German automotive distribution hubs.
- Machine Vision Advances:Deep-learning-based gripping algorithms now enable robotic arms to handle deformable packaging in apparel and pharmaceuticals, extending automation to previously manual piece-picking operations.
- Labor Scarcity in Logistics:Warehouse operator vacancy rates exceeding 15% in North American distribution corridors are forcing 3PLs to automate storage, retrieval, and sortation to maintain throughput commitments.
Market Restraints
- Steel and Servomotor Cost Volatility:Input price swings for precision linear actuators and high-torque motors are compressing margins on automated storage and retrieval systems during contract negotiation windows.
- Integration Complexity:Brownfield facilities with 30-year-old warehouse management software require expensive middleware development to interface with modern robotic control systems.
- OSHA Lockout/Tagout Compliance:Extended safety certification timelines for collaborative robot deployments are lengthening sales cycles by 4-8 months in United States distribution markets.
Strategic Opportunities
- Cold-Chain Automation:Underpenetrated pharmaceutical distribution networks in India present white space for temperature-controlled automated storage systems serving vaccine and biologics logistics.
- Convergence of Digital Twin and AMR Fleets:Real-time simulation of autonomous mobile robot routing is enabling dynamic slotting optimization that compresses travel time by 20-35% in high-SKU environments.
- California Warehouse Safety Legislation:Emerging state-level ergonomic mandates for manual lifting are creating regulatory tailwinds for robotic palletizing and depalletizing equipment in West Coast distribution clusters.
Industry Challenges
- Controls Engineering Talent Gap:Shortage of PLC programmers and robotic integration specialists is delaying commissioning timelines for multi-vendor automation projects.
- Legacy WMS Interoperability:Proprietary data protocols in 1990s-era warehouse management systems require costly custom API development to synchronize with modern robotic fleet management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehouse Automation Equipment Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $111.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Conveyor Systems, Sortation Systems, Automated Storage and Retrieval Systems, Robotics Arms Technology: Machine Vision, RFID Systems, Artificial Intelligence, Wireless Sensor Networks, Voice Recognition Application: Order Fulfillment, Inventory Management, Material Handling, Packaging, Cross-Docking End User: Third-Party Logistics Providers, E-commerce Fulfillment Centers, Cold Storage Facilities, Manufacturing Plants |
| Companies Covered | Daifuku Co., Ltd., Dematic, SSI Schaefer AG, Honeywell Intelligrated, Swisslog Holding AG, KNAPP AG, AutoStore Holdings Ltd., Murata Machinery, Ltd., TGW Logistics Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehouse Automation Equipment Market Trends and Innovations
Automation architectures are fragmenting from monolithic installations toward composable subsystems that permit phased capital deployment. This shift is compressing payback periods and lowering barriers for mid-size warehouse operators.
Shuttle-based storage technology is modularizing around standardized 25-meter rack configurations that integrate with existing facility footprints. Grocery and general merchandise distributors are adopting these systems at 18-24 month replacement cycles for legacy crane-based AS/RS. The technology is modularizing capital deployment, allowing operators to expand capacity in 5,000-SKU increments rather than full-facility overhauls.
The EU AI Act's risk classification framework for autonomous decision-making systems is imposing documentation burdens on robot manufacturers deploying machine vision for piece-picking. Industrial consequence includes mandatory conformity assessments for high-risk AI applications in collaborative zones. Pharmaceutical distribution facilities in Germany and the Netherlands are responding by pre-certifying robotic workcells through notified bodies to accelerate site acceptance testing.
Third-party logistics providers are consolidating automation procurement under multi-year framework agreements that bundle hardware, software, and lifecycle services. Traditional equipment distributors are losing access to these accounts as DHL Supply Chain and GXO Logistics negotiate direct OEM relationships. This concentration is most visible in North American e-commerce fulfillment, where top-10 3PLs now control 40% of robotic picking system deployments.
Warehouse Automation Equipment Market Segmentation
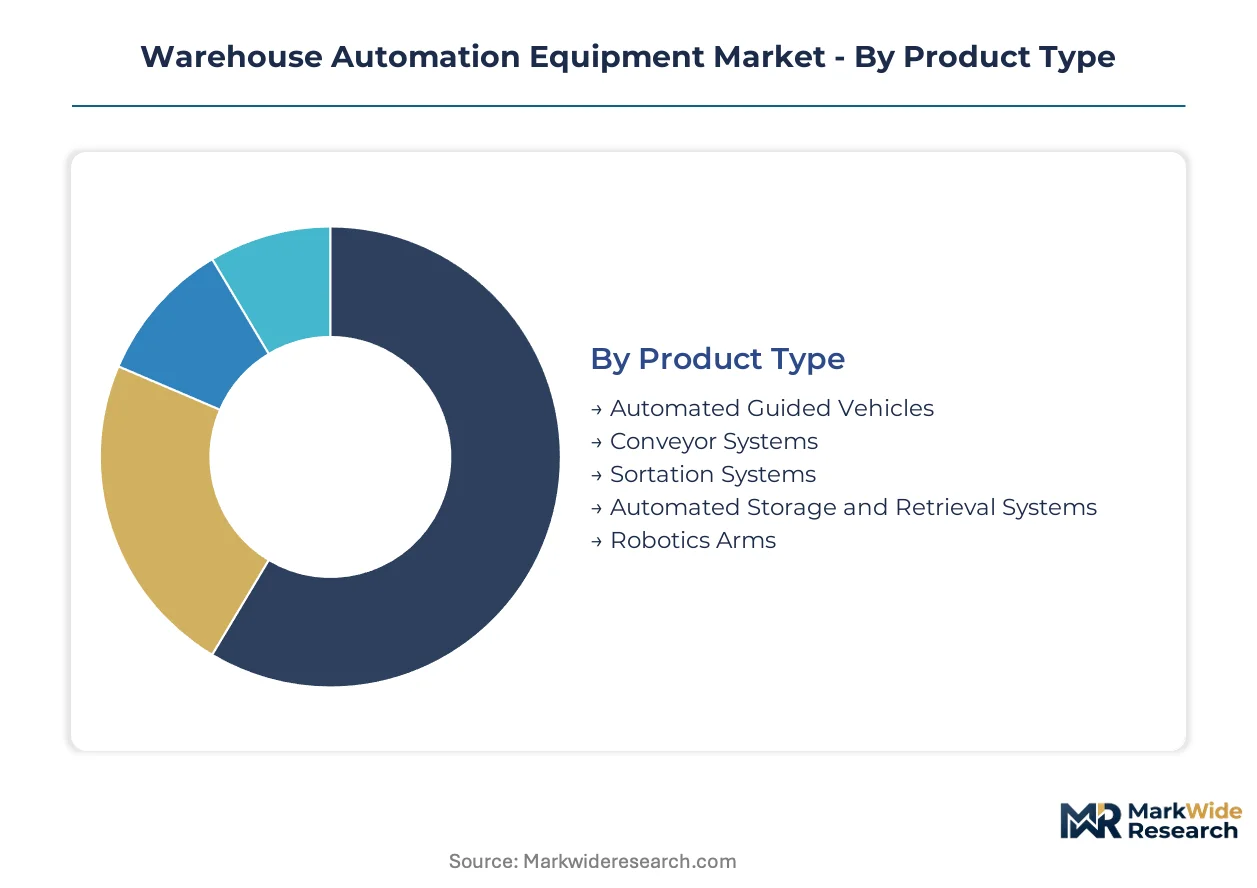
Warehouse automation equipment segments diverge sharply in certification burden and integration complexity. Equipment vendors must align product roadmaps with divergent regulatory pathways across autonomous mobile systems, fixed infrastructure, and collaborative robotics.
Product Type:
CE marking under the EU Machinery Directive and ISO 10218-1/2 compliance requirements vary substantially across equipment categories, with articulated arms and autonomous vehicles facing the most intensive conformity assessment protocols.
- Automated Storage and Retrieval Systems:Rack-mounted crane systems with vertical travel exceeding 40 feet dominate capital deployment in ambient and cold-chain distribution. German automotive and pharmaceutical hubs are modernizing legacy facilities with continuous-operation crane systems certified under harmonized EN 528 standards.
- Robotics Arms:Articulated systems with compliant gripping and deep-learning vision now execute piece-picking for deformable packaging. ISO 10218-2 protective measures and documented risk assessments are mandatory for collaborative deployments in Dutch and German pharmaceutical workcells.
- Automated Guided Vehicles:Laser-guided and vision-navigated mobile platforms transport pallets and totes across distribution floors. EN 1525 safety requirements govern driverless industrial truck operation in European facilities.
- Conveyor Systems:Belt and roller configurations with variable-speed drives handle case and parcel movement between process zones. Modular designs allow phased retrofitting without full operational shutdowns.
- Sortation Systems:Tilt-tray, cross-belt, and sliding-shoe technologies direct parcels to shipping lanes at throughput rates exceeding 10,000 units per hour. High-velocity grocery and general merchandise distributors in North America drive replacement demand.
Leading the category by volume: Automated Storage and Retrieval Systems. Growing fastest: Robotics Arms.
Technology:
Technology segments stratify by hardware-software integration intensity and data governance exposure under the EU AI Act's risk classification framework.
- Machine Vision:Deep-learning cameras and 3D sensors enable robotic piece-picking of transparent, reflective, and deformable surfaces. High-risk AI conformity assessments are mandatory for pharmaceutical distribution applications in Germany and the Netherlands.
- Artificial Intelligence:Predictive maintenance algorithms and dynamic slotting optimization compress travel time by 20-35% in high-SKU environments. Documentation burdens under EU AI Act risk frameworks are reshaping vendor development cycles.
- RFID Systems:Passive and active radio-frequency identification enables real-time inventory tracking without line-of-sight requirements. Cold storage facilities in North America deploy UHF tags for temperature-sensitive pharmaceutical tracking.
- Wireless Sensor Networks:Mesh-configured IoT devices monitor equipment health, environmental conditions, and energy consumption across warehouse zones. Battery life and cybersecurity hardening remain primary procurement criteria.
- Voice Recognition:Headset-directed picking systems guide warehouse associates through order assembly in hands-free environments. Cost-tier positioning below vision-guided alternatives sustains adoption in mid-size distribution operations.
Widest deployment: Machine Vision. Steepest expansion trajectory: Artificial Intelligence.
Application:
Application segments map directly to labor scarcity pressure points, with order fulfillment and material handling absorbing the highest automation capital allocation.
- Order Fulfillment:Robotic piece-picking, shuttle-based storage, and AMR fleets compress e-commerce cycle times from days to hours. Third-party logistics providers consolidate multi-site contracts around fulfillment automation in North America and Europe.
- Material Handling:Pallet movement, case conveying, and tote transport operations face 15%+ vacancy rates in North American distribution corridors. OSHA lockout/tagout regulations extend safety certification timelines by 4-8 months.
- Inventory Management:Cycle counting, put-away optimization, and slotting algorithms maximize cubic space utilization in high-rent urban distribution facilities.
- Packaging:Automated carton erection, void fill, and sealing systems reduce manual handling in final-mile preparation zones. California ergonomic mandates for manual lifting are accelerating robotic palletizing adoption on the West Coast.
- Cross-Docking:High-velocity sortation and direct-to-ship staging minimize dwell time for time-definite freight networks. Retail and grocery distributors prioritize these configurations for perishable and promotional goods.
Dominant by capital deployed: Order Fulfillment. Gaining share fastest: Packaging.
End User:
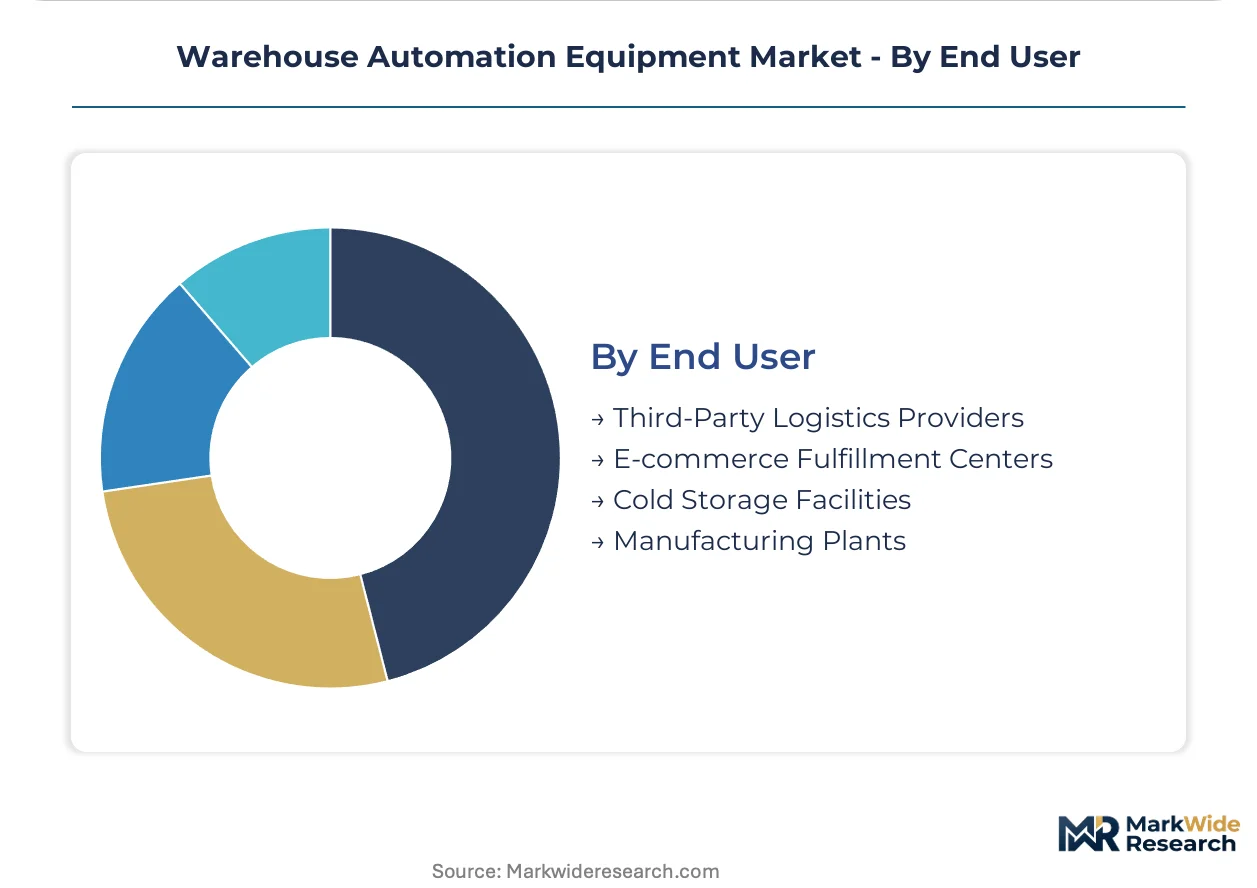
End-user concentration is hardening around third-party logistics providers with multi-site procurement leverage, while cold storage remains underpenetrated relative to ambient distribution.
- Third-Party Logistics Providers:DHL Supply Chain and GXO Logistics negotiate direct OEM relationships for hardware-software-service bundles. Top-10 3PLs now control 40% of robotic picking system deployments in North American e-commerce.
- E-commerce Fulfillment Centers:Velocity pressures and SKU proliferation are driving 18-24 month replacement cycles for legacy crane-based systems. Shuttle-based storage modularization permits capacity expansion in 5,000-SKU increments.
- Cold Storage Facilities:Temperature-controlled automated storage serving vaccine and biologics logistics presents white space in Indian pharmaceutical distribution networks. Precision linear actuator cost volatility compresses margins during contract negotiations.
- Manufacturing Plants:Inbound material sequencing and finished goods staging integrate warehouse automation with production lines. Automotive and electronics verticals in Germany anchor demand for semiconductor cleanroom logistics configurations.
Controlling procurement volume: Third-Party Logistics Providers. Expanding most quickly: E-commerce Fulfillment Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel servomotor supply chains and precision actuator fabrication anchor automation equipment production in Germany, Japan, and the United States. These three manufacturing bases feed distribution hub modernization across their respective domestic markets and export into adjacent economies. Regional demand patterns diverge sharply based on e-commerce velocity, labor scarcity severity, and regulatory enforcement intensity.
United States
OSHA lockout/tagout regulations extend safety certification timelines by 4-8 months for collaborative robot deployments. California warehouse safety legislation mandates ergonomic protections that accelerate robotic palletizing adoption in West Coast distribution clusters. The Inland Empire and Central Valley logistics corridors absorb 40% of North American shuttle-based storage capital deployment.
Germany
Automotive and pharmaceutical distribution hubs in Stuttgart and Frankfurt are modernizing legacy facilities with continuous-operation crane systems. EU Machinery Directive CE marking requirements under harmonized EN 528 standards reduce cross-border certification friction for autonomous mobile robots. Bavarian electronics distributors anchor premium demand for semiconductor cleanroom logistics configurations.
Japan
METI industrial automation incentives support robotic integration in aging warehouse infrastructure across the Kanto and Kansai regions. JIS safety standards for automated guided vehicles create compliance differentiation for domestic equipment vendors. Osaka-based pharmaceutical distributors drive piece-picking robot deployment for biologics handling.
China
MIIT smart logistics initiatives accelerate AS/RS adoption in Yangtze River Delta e-commerce fulfillment centers. GB standards for industrial robot safety are converging toward ISO 10218 frameworks to facilitate export certification. Shenzhen electronics distributors represent the fastest-expanding customer segment for machine vision-enabled picking systems.
India
PLI scheme incentives for pharmaceutical manufacturing are spilling into temperature-controlled distribution infrastructure investment. CDSCO cold-chain requirements for vaccine logistics create white space for automated storage systems in Mumbai and Hyderabad. Karnataka and Maharashtra warehouse operators face 15%+ vacancy rates that force automation procurement.
Warehouse Automation Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular software architectures and phased brownfield retrofit capabilities. The vendor base stratifies across three maturity tiers: integrated hardware-software providers, specialized subsystem fabricators, and regional installation contractors. Strategic archetypes include vertical integration specialists, software-centric disruptors, and service-anchored incumbents. Dominant competitive moves encompass multi-year framework agreements bundling hardware-software-service and direct OEM relationships bypassing traditional distribution channels.
Within the integrated tier, Daifuku Co., Ltd. and Dematic exemplify scale-driven positioning across multiple equipment categories. SSI Schaefer AG occupies a specialist position in modular software architectures. These three anchors represent divergent geographic origins and structural configurations: Osaka-based Daifuku leverages in-house production of precision components; Dematic operates as a US-anchored systems integrator; SSI Schaefer AG functions as a German GmbH with software-centric differentiation.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Dematic |
| SSI Schaefer AG |
| Honeywell Intelligrated |
| Swisslog Holding AG |
| KNAPP AG |
| AutoStore Holdings Ltd. |
| Murata Machinery, Ltd. |
| TGW Logistics Group GmbH |
| Others |
Pricing and Supply Chain Analysis
Steel price indices and servomotor commodity benchmarks cascade through warehouse automation equipment supply chains into three distinct pricing tiers. Precision linear actuator cost volatility compresses margins on automated storage systems during contract windows, while buyers with multi-site procurement leverage extract bundled lifecycle service concessions.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors offering decade-long maintenance contracts from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10218-2 certification grade and volume scale. Cost compression in standard-tier shuttle systems intensifies because steel input volatility feeds directly into rack fabrication. Third-party logistics providers with framework agreements demonstrate lowest price sensitivity; mid-size brownfield operators face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from DHL Supply Chain and GXO Logistics, bypassing traditional equipment distributors. Manufacturing gravity centers on Germany, Japan, and the United States for precision actuator fabrication and servomotor assembly. Supply chains draw from high-grade steel, rare-earth magnets, and semiconductor-grade sensors. Single-source vulnerability in precision linear motion components creates exposure to extended lead times. Distribution runs through systems integrators and regional installation contractors serving brownfield retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controls engineering talent scarcity props pricing power for vendors with certified integration protocols. Capacity bottlenecks in PLC programming and robotic commissioning constrain supply expansion.
For Market Incumbents: Extend software-centric differentiation through modular architectures that enable phased brownfield retrofitting without operational shutdowns. Defend against emerging subsystem fabricators by anchoring multi-year framework agreements with top-10 third-party logistics providers. Capacity addition in German automotive distribution corridors reinforces geographic concentration. For New Entrants and Emerging Players: Regional installation contractors represent the most accessible channel partner type for penetrating mid-size warehouse operators. White-space targets include cold-chain automation in Indian pharmaceutical distribution and voice-directed picking systems in cost-sensitive North American mid-market facilities. Target California warehouse safety legislation compliance as a go-to-market wedge for robotic palletizing equipment. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-centric disruptors with modular brownfield capabilities in European pharmaceutical logistics. Long-term viability across the projection horizon hinges on EU AI Act conformity assessment infrastructure. Acquisition target archetype: subsystem fabricators with ISO 10218-2 pre-certification. Monitor divergence between European CE marking and emerging state-level warehouse safety legislation as an inflection indicator for certification cost multiplication.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Framework Agreements | DHL Supply Chain and GXO Logistics consolidate procurement leverage across North American and European sites. |
| Modular Software Architecture Development | SSI Schaefer AG enables phased retrofitting without full operational shutdowns in legacy brownfield warehouses. |
| Cold-Chain Certification Investment | Temperature-controlled automated storage addresses CDSCO requirements for Indian vaccine and biologics logistics. |
| Machine Vision Capability Acquisition | Deep-learning gripping algorithms extend automation to deformable packaging in apparel and pharmaceutical verticals. |
| Direct OEM Relationship Establishment | Bypassing traditional distributors captures procurement volume from consolidating third-party logistics providers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this warehouse automation equipment analysis. Primary interviews with warehouse operations directors, OEM procurement teams, systems integration specialists, and aftermarket service heads combined with secondary validation from OSHA enforcement databases, EU Machinery Directive conformity assessments, and SEC equipment vendor filings. Bottom-up SKU-level modeling and top-down regional aggregation enabled triangulation across data sources.
Granularity-level framing modeled equipment categories at the product-type level, technology segments at the hardware-software integration intensity tier, and end-user concentration at the buyer-archetype level. CAGRs derived from unit shipment trajectories and average selling price movements across the analysis window. Industry-specific forecast inputs included e-commerce fulfillment velocity requirements and labor scarcity indices in North American distribution corridors.
Caveats apply where steel and servomotor cost volatility, regulatory fragmentation between European and state-level U.S. safety standards, or controls engineering talent shortages could materially shift the outlook. Forecasts reflect documented assumptions about certification timeline standardization and brownfield retrofit adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Intralogistics Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
United States SCADA Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
HMI Market
Industrial Automation
Cold Storage AGV Market