
 Latin America Automated Storage and Retrieval System Market | 2026-2036
Latin America Automated Storage and Retrieval System Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automated Storage and Retrieval System Market Foresight
Skilled technician availability across Latin America is bifurcating the competitive landscape between full-service providers and equipment-only vendors. KION GROUP AG anchors its regional position through captive service networks that sustain uptime guarantees for multinational manufacturers. SSI Schaefer AG competes on software platform depth, while Bastian Solutions, LLC differentiates through modular integration capabilities that reduce deployment timelines for mid-market warehouses.
Automated Storage and Retrieval Systems comprise computer-controlled mechanical structures that store and retrieve loads from defined storage locations, typically operating at heights exceeding twelve meters with throughput rates of 150–400 dual cycles per hour depending on crane configuration. Unit Load AS/RS dominates capital deployment across heavy manufacturing verticals where palletized inventory density justifies infrastructure investment, while Mini Load AS/RS and Vertical Lift Modules capture faster growth in pharmaceutical and electronics sectors where tote-handling precision reduces picking error rates. Software Platforms within the technology dimension increasingly determine system performance ceilings as warehouse execution systems coordinate robotic subsystems in real time.
Brazil's ANVISA imposes traceability requirements on pharmaceutical and food distribution chains that directly mandate automated lot-tracking capabilities, while Mexico's NOM standards for industrial safety shape crane and conveyor certification protocols. ISO 3691-4 for autonomous mobile robots and IEC 61508 for functional safety create compliance baselines that filter non-certified vendors from premium project tenders. Stakeholders must weigh total cost of ownership against localization requirements as regional content rules tighten in Brazilian infrastructure concessions.
Market Dynamics
Labor scarcity among certified crane technicians across Brazil and Mexico is forcing warehouse operators toward robotics-based AS/RS configurations that reduce human intervention requirements. This structural pressure concentrates procurement decisions on vendors with captive service networks capable of sustaining uptime guarantees.
Growth Catalysts
- E-commerce fulfillment acceleration:São Paulo's logistics corridor and Mexico City's industrial belt are witnessing concentrated demand from online retail operators seeking pallet-density optimization through Unit Load AS/RS deployments.
- ANVISA traceability mandates:Brazil's pharmaceutical and food distribution chains now require automated lot-tracking capabilities that only integrated AS/RS software platforms can reliably deliver.
- Robotics convergence:The integration of autonomous mobile robots with fixed crane infrastructure is creating hybrid systems that expand throughput capacity without proportional labor expansion.
Market Restraints
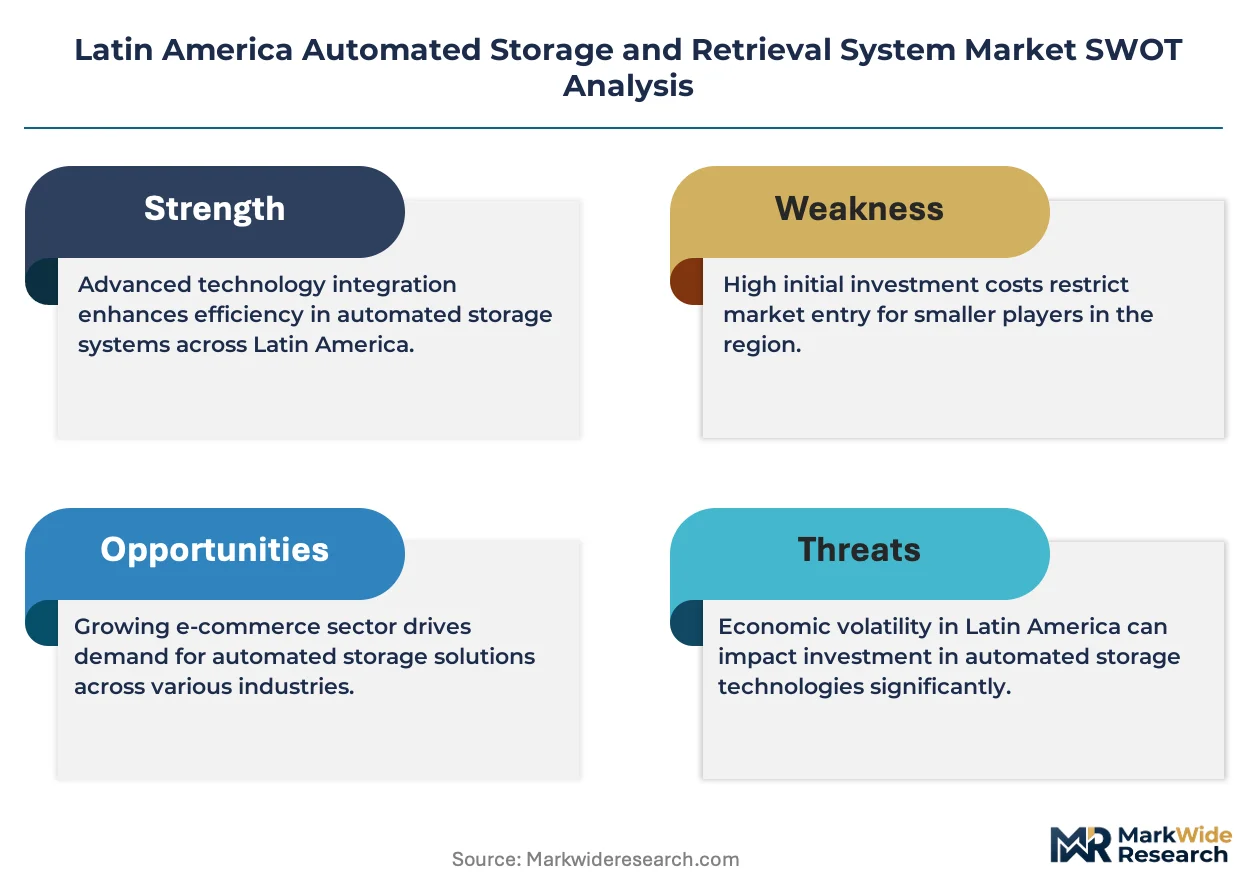
- Capital intensity barriers:Unit Load AS/RS installations exceeding twelve meters in height require specialized foundation work and seismic reinforcement that inflate upfront project costs.
- Technician supply concentration:Brazil's certified maintenance workforce clusters disproportionately in São Paulo state, leaving northern and northeastern logistics hubs underserved for reactive repair services.
- Substitution pressure from manual alternatives:Vertical Lift Modules face competition from dense manual shelving in micro-fulfillment centers where capital constraints outweigh throughput requirements.
Strategic Opportunities
- Underpenetrated Colombian corridor:Bogotá's emerging logistics belt offers first-mover positioning for AS/RS vendors before e-commerce saturation triggers competitive bidding wars.
- Pharmaceutical precision applications:Mini Load AS/RS configurations for tote-handling in temperature-controlled environments address ANVISA's serialization requirements while reducing picking error rates.
- ISO 3691-4 certification arbitrage:Vendors achieving autonomous mobile robot compliance ahead of regional peers gain preferential access to multinational manufacturer tenders requiring standardized safety protocols.
Industry Challenges
- Integration complexity with legacy WMS:Warehouse management systems predating real-time robotic coordination require expensive middleware development that extends deployment timelines.
- IEC 61508 functional safety certification timelines:Crane subsystem validation for safety integrity levels stretches project delivery schedules, particularly for greenfield pharmaceutical installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automated Storage and Retrieval System Market |
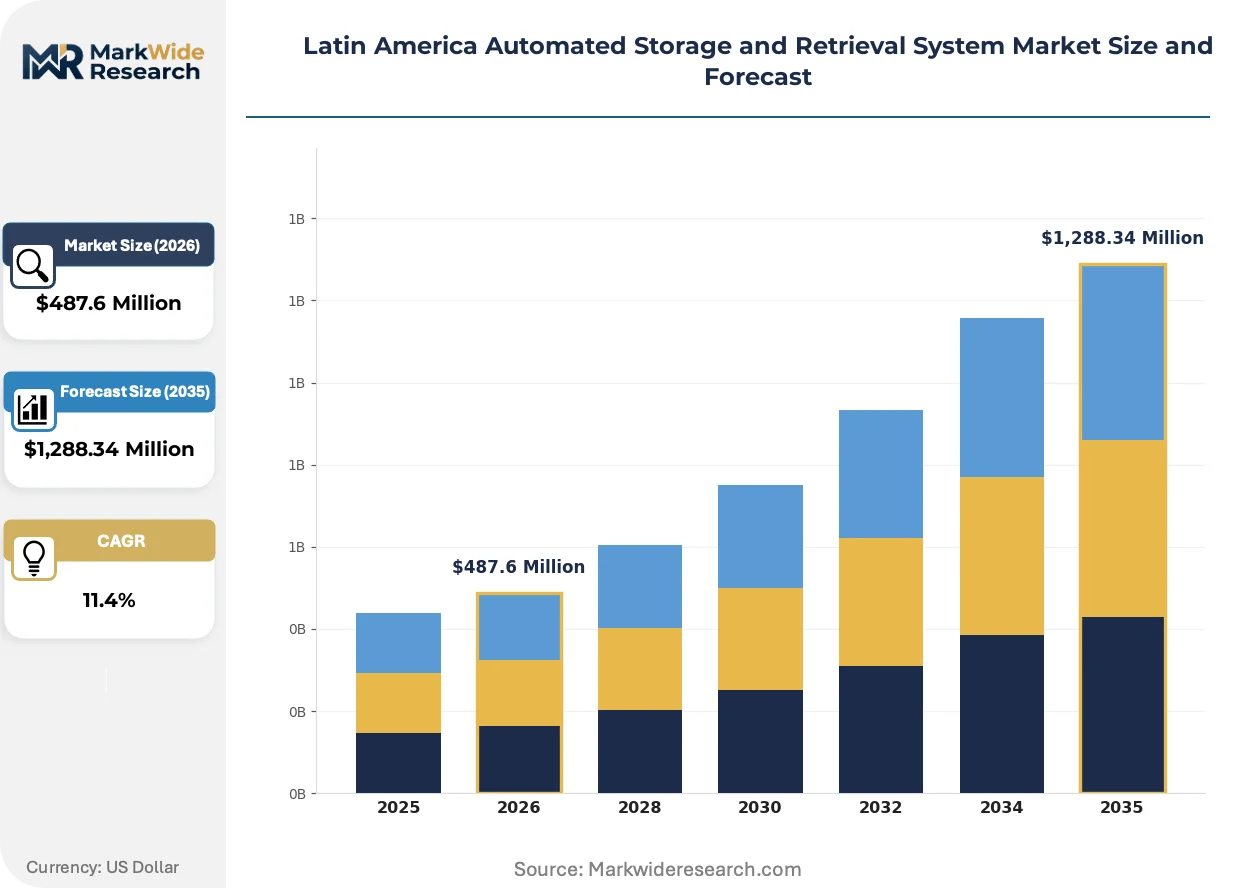
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Unit Load AS/RS, Mini Load AS/RS, Vertical Lift Module, Horizontal Carousel End User: Retail, Manufacturing, Healthcare, Food & Beverage Technology: Automated Guided Vehicles, Robotics, Software Platforms, Barcode Scanning Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Murata Machinery Ltd., Geek+ Inc, KION GROUP AG, Beumer Group, Hanel Storage Systems, Bastian Solutions, LLC, KNAPP AG, Automation Logistics Corporation, SSI Schaefer AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automated Storage and Retrieval System Market Shifts & Advancements
Software-defined coordination between robotic subsystems is displacing hardware-centric competitive differentiation across Latin American warehouse automation. This shift elevates real-time execution platforms above mechanical specifications in procurement evaluations.
Shuttle-based storage and retrieval technology is fragmenting the traditional crane-dominated landscape by enabling modular scalability that matches capital deployment to actual throughput growth. Pharmaceutical distributors in São Paulo and electronics manufacturers in Guadalajara are piloting these configurations to defer full-scale infrastructure commitments. The technology is fragmenting vendor revenue models away from large turnkey projects toward recurring software and expansion-module transactions.
Mexico's NOM industrial safety standards for crane and conveyor certification are tightening compliance baselines that filter non-certified vendors from premium project tenders. These protocols mandate third-party structural validation that adds documentation burden but reduces liability exposure for multinational operators. Heavy manufacturing verticals with established safety cultures are absorbing these requirements fastest, while mid-market warehouses delay procurement pending clarity on enforcement timelines.
After-sales service unbundling is disrupting the traditional full-service vendor lock-in that previously dominated regional procurement patterns. Large e-commerce operators in Mexico City now separately contract maintenance technicians and software updates, compressing vendor margins while expanding buyer flexibility. This pattern is most visible among digitally native retailers with internal engineering capabilities that reduce dependence on captive service networks.
Latin America Automated Storage and Retrieval System Market Segmentation
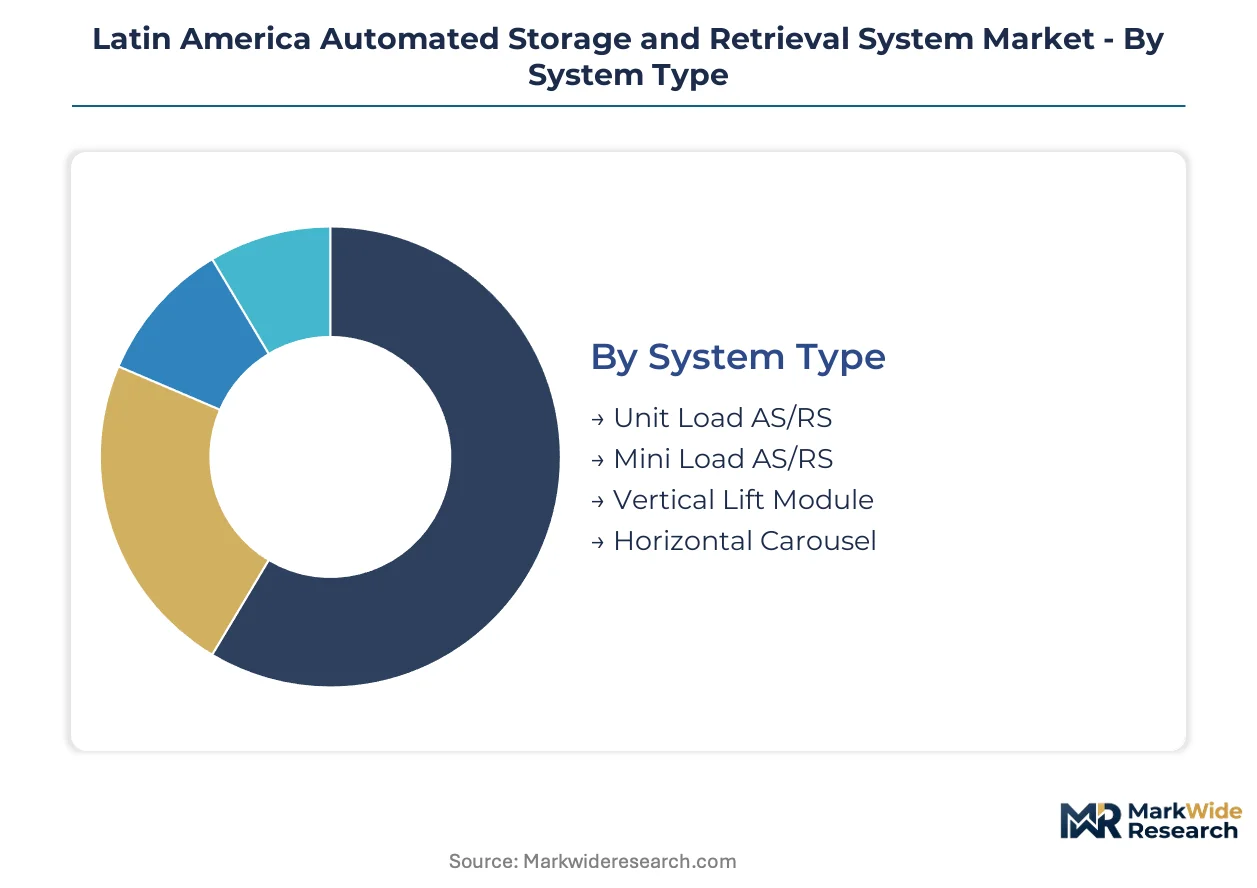
Segmentation reveals how capital deployment patterns diverge across Latin American warehouse automation. Procurement decisions in São Paulo and Mexico City track distinct technical requirements that reshape vendor competitive positioning.
System Type:
Vertical Lift Modules face the most acute substitution pressure from dense manual shelving in micro-fulfillment centers where throughput requirements fail to justify infrastructure investment.
- Unit Load AS/RS:Computer-controlled crane systems handle palletized loads at heights exceeding twelve meters with throughput rates of 150–400 dual cycles per hour. Demand concentrates in São Paulo's logistics corridor where e-commerce fulfillment operators seek pallet-density optimization for heavy manufacturing verticals.
- Mini Load AS/RS:Tote-handling configurations operate at lower heights with precision picking capabilities that reduce error rates. Pharmaceutical distributors across Brazil deploy these systems to satisfy ANVISA traceability mandates for lot-tracking in temperature-controlled environments.
- Vertical Lift Module:Modular storage towers face competition from manual alternatives in capital-constrained micro-fulfillment settings.
- Horizontal Carousel:Rotating shelf systems serve low-ceiling warehouses with moderate throughput requirements in northern Brazilian logistics hubs.
Unit Load AS/RS retains volume leadership; Mini Load AS/RS holds the steepest expansion curve.
End User:
Cost tier stratification separates premium automation adopters from price-sensitive segments delaying procurement.
- Retail:E-commerce operators in Mexico City's industrial belt drive concentrated demand for robotics-integrated fulfillment systems.
- Manufacturing:Heavy industrial verticals justify Unit Load AS/RS infrastructure through inventory density requirements and established safety cultures.
- Healthcare:Pharmaceutical distributors require Mini Load configurations with serialization capabilities to meet Brazil's ANVISA regulations.
- Food & Beverage:Cold chain operators face extended certification timelines for IEC 61508 functional safety compliance.
Retail captures the largest deployment share; healthcare is climbing the fastest.
Technology:
Software platform maturity now determines performance ceilings more than mechanical specifications.
- Automated Guided Vehicles:Fixed-path transport systems integrate with crane infrastructure to create hybrid configurations that expand throughput without proportional labor expansion.
- Robotics:Autonomous mobile robots certified to ISO 3691-4 standards gain preferential access to multinational manufacturer tenders requiring standardized safety protocols.
- Software Platforms:Real-time warehouse execution systems coordinate robotic subsystems and displace hardware-centric competitive differentiation.
- Barcode Scanning:Legacy identification technology persists in mid-market warehouses with limited middleware budgets.
Software Platforms anchor procurement evaluations; Robotics is expanding most quickly.
Deployment Model:
Customer engineering capabilities determine unbundling patterns that compress traditional full-service vendor margins.
- On-Premises:Capital-intensive installations requiring specialized foundation work and seismic reinforcement dominate heavy manufacturing verticals.
- Cloud-Based:Subscription execution platforms enable digitally native retailers to separately contract software updates from hardware maintenance.
- Hybrid:Mixed configurations balance data sovereignty requirements with remote monitoring capabilities.
- Managed Services:Outsourced operations appeal to operators lacking captive service networks for uptime guarantees.
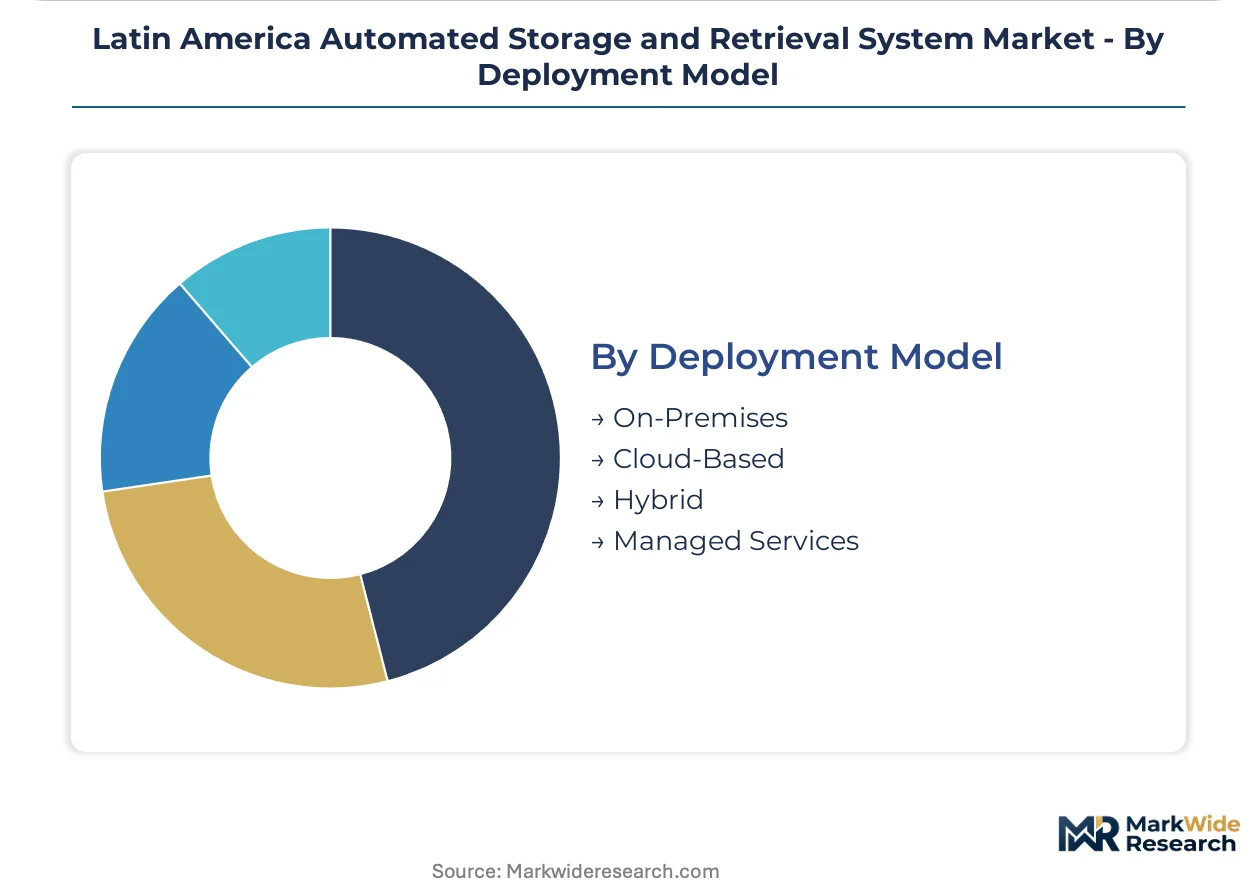
On-Premises retains deployment dominance; Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil deploys Unit Load AS/RS for heavy manufacturing density while Mexico favors robotics-integrated fulfillment systems for e-commerce velocity. This consumption-mix differential separates pallet-density optimization from throughput-speed priorities across the region.
Brazil
São Paulo's logistics corridor concentrates e-commerce fulfillment demand for pallet-density optimization through Unit Load AS/RS installations. ANVISA traceability mandates for pharmaceutical and food distribution chains require automated lot-tracking capabilities that only integrated software platforms deliver. Certified maintenance technicians cluster disproportionately in São Paulo state, leaving northern and northeastern logistics hubs underserved for reactive repair services.
Mexico
Mexico City's industrial belt drives concentrated procurement of robotics-integrated fulfillment systems from online retail operators. NOM industrial safety standards for crane and conveyor certification mandate third-party structural validation that filters non-certified vendors from premium project tenders. Guadalajara's electronics manufacturers pilot shuttle-based storage configurations to defer full-scale infrastructure commitments.
Colombia
Bogotá's emerging logistics belt offers first-mover positioning for AS/RS vendors before e-commerce saturation triggers competitive bidding wars. The country's national pharmaceutical regulator imposes serialization requirements that favor Mini Load configurations with temperature-controlled precision. Capital deployment lags regional peers due to infrastructure financing constraints and extended certification timelines.
Chile
Santiago's mining supply chain operators deploy Unit Load AS/RS for heavy equipment parts density in seismically reinforced installations. The country's national industrial safety authority enforces crane certification protocols aligned with IEC 61508 functional safety standards. Port logistics clusters in Valparaíso absorb compliance requirements fastest due to established safety cultures among multinational operators.
Argentina
Buenos Aires pharmaceutical distributors pilot Mini Load configurations to address traceability mandates while navigating capital constraint pressures. The country's national food and drug administration imposes lot-tracking requirements that favor automated storage over manual alternatives. Regional logistics hubs in Córdoba and Rosario remain underpenetrated due to technician supply scarcity and currency volatility impacts on import-dependent equipment procurement.
Latin America Automated Storage and Retrieval System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on modular deployment speed and software platform depth. Full-service providers with captive technician networks sustain uptime guarantees for multinational manufacturers, while equipment-only vendors compete on capital efficiency for mid-market warehouses. Two strategic archetypes dominate: vertically integrated system integrators and software-centric platform specialists. Competitive moves concentrate on geographic expansion through localized service partnerships and technology licensing arrangements that accelerate regulatory compliance.
Within the integrated leader tier, KION GROUP AG and SSI Schaefer AG exemplify contrasting approaches to regional positioning. KION GROUP AG anchors its presence through captive service networks that address technician scarcity across São Paulo and Mexico City logistics corridors. SSI Schaefer AG occupies a position emphasizing software platform depth in procurement evaluations where real-time execution capabilities determine performance ceilings. Bastian Solutions, LLC represents the modular integration archetype that reduces deployment timelines for mid-market warehouses seeking capital-efficient automation entry points.
| Leading Market Players |
|---|
| Murata Machinery Ltd. |
| Geek+ Inc |
| KION GROUP AG |
| Beumer Group |
| Hanel Storage Systems |
| Bastian Solutions, LLC |
| KNAPP AG |
| Automation Logistics Corporation |
| SSI Schaefer AG |
| Others |
Supply & Pricing Matrix
Project-based contracting with milestone-linked payments locks in supply access for AS/RS crane systems while anchoring price visibility against steel and semiconductor cost volatility across São Paulo and Mexico City logistics corridors.
Pricing Analysis
Long-term offtake agreements dominate procurement for Unit Load AS/RS installations exceeding twelve meters, with pricing stratifying across ISO 3691-4 certified robotics, IEC 61508 validated crane subsystems, and uncertified equipment-only tiers. Certification premiums widen as ANVISA traceability mandates filter non-compliant vendors from pharmaceutical tenders. Cost compression in mid-market warehouses intensifies because after-sales service unbundling lets buyers separately negotiate maintenance contracts. Micro-fulfillment operators show highest price sensitivity; multinational manufacturers with captive engineering teams absorb premium tiers for uptime guarantees.
Supply Chain Analysis
Inventory lead times for precision servo motors and safety-rated PLCs stretch project delivery schedules across Latin American warehouse automation. Component manufacturing concentrates in Germany, Japan, and South Korea for high-reliability crane subsystems. Steel structural frames and conveyor belting draw from Brazilian and Mexican domestic mills. Single-source vulnerability sits with specialized encoder suppliers for functional safety certification. Distribution runs through São Paulo-based system integrators with captive technician networks serving northern Brazil and Mexico City industrial belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software platform interoperability is reconfiguring competitive boundaries as warehouse execution systems displace hardware specifications in procurement evaluations, with shuttle-based modularity enabling ecosystem entry for non-traditional vendors.
For Market Incumbents: Fortify captive service networks in technician-scarce northern Brazil before emerging modular vendors establish maintenance partnerships. Deepen backward integration into safety-certified PLC supply to counter ISO 3691-4 certification arbitrage by robotics specialists. Anchor position through ANVISA pre-validated software platforms that shorten pharmaceutical deployment timelines. For New Entrants and Emerging Players: IEC 61508 fast-track certification opens premium pharmaceutical tenders in São Paulo and Bogotá where validation timelines currently filter incumbents. Underpenetrated Colombian logistics corridors offer white-space positioning before e-commerce density triggers competitive bidding. Target cloud-based execution platform licensing to digitally native retailers with internal engineering capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-centric platform specialists with shuttle-based expansion modules that defer full infrastructure commitments. Long-term viability hinges on regulatory compliance automation as traceability mandates tighten across Brazil and Mexico. Watch for ISO 3691-4 certification velocity as inflection signal separating scalable robotics vendors from equipment-only suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Integration | Real-time execution coordination displaces hardware-centric vendor selection criteria in São Paulo tenders. |
| Shuttle-Based Modularity Deployment | Pharmaceutical distributors in Guadalajara pilot scalable configurations that defer full-scale infrastructure commitments. |
| Captive Service Network Expansion | KION GROUP AG anchors uptime guarantees through technician concentration in Mexico City logistics corridors. |
| Regulatory Pre-Certification Investment | ANVISA-validated lot-tracking capabilities filter non-compliant vendors from Brazilian pharmaceutical procurement. |
| Cloud-Based Execution Licensing | Subscription models enable digitally native retailers to unbundle software from hardware maintenance contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with warehouse operations directors, maintenance managers at e-commerce fulfillment centers, pharmaceutical distribution executives, and system integration specialists; and secondary validation through ANVISA regulatory filings, NOM certification databases, SEC equipment manufacturer disclosures, and Latin American customs import records for automation components. Bottom-up installation tracking across São Paulo, Mexico City, and Bogotá logistics corridors combined with top-down capital expenditure analysis from regional e-commerce operators.
Across the analysis window, the forecasting framework modeled system type segmentation by throughput requirement and height specification, end-user verticals by regulatory exposure and inventory density needs, technology layers by software platform maturity and robotics certification status, and deployment models by customer engineering capability and data sovereignty preferences. CAGRs derived from equipment shipment trajectories, warehouse automation capex surveys, and technician supply-demand imbalances across Brazilian states.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce fulfillment acceleration or abrupt regulatory enforcement delays would require recalibration. Forecasts reflect documented assumptions about labor scarcity persistence and certification timeline standardization. Currency volatility impacts on import-dependent equipment procurement in Argentina represent specific revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Smart Factory Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Agricultural Automation Market