
 Supervisory Control and Data Acquisition (SCADA) Market | 2026-2036
Supervisory Control and Data Acquisition (SCADA) Market Size, Share, and Industry Trends Forecast 2026-2036
Supervisory Control and Data Acquisition (SCADA) Market Intelligence
The transition from monolithic SCADA platforms to cloud-native, microservices-based architectures is fragmenting the traditional system integration model. Siemens leverages its extensive industrial automation portfolio to offer integrated solutions for complex process industries. Schneider Electric specializes in energy management and grid automation, targeting utility-scale deployments. Emerson Electric Co. competes by focusing on process control systems for the oil and gas sector.
Supervisory Control and Data Acquisition systems are centralized software and hardware architectures used for industrial process control. These systems gather real-time data from remote terminal units (RTUs) and programmable logic controllers (PLCs) to monitor and manage critical infrastructure. While on-premises deployment remains dominant in sensitive sectors, cloud-based solutions are gaining traction due to lower capital expenditure. Within applications, the water management and power generation sectors represent mature, high-value segments demanding high-reliability hardware components.
Regulatory frameworks like the NERC CIP standards in the United States and the EU's NIS Directive mandate stringent cybersecurity measures for critical infrastructure operators. In China, the Multi-Level Protection Scheme (MLPS 2.0) imposes similar security obligations, directly shaping SCADA system specifications and procurement. Vendors must now decide whether to develop universal platforms or specialize in solutions compliant with specific regional cybersecurity and data sovereignty rules.
Market Dynamics
The modernization of electrical grids, accelerated by stringent cybersecurity mandates like NERC CIP, is the central force shaping the market. This pressure is forcing a convergence of information technology and operational technology, redefining system architecture and vendor responsibilities across critical infrastructure sectors.
Growth Catalysts
- Smart Grid Investment:State-led initiatives, particularly in China, are funneling significant capital into smart grid infrastructure. This investment mandates the deployment of advanced SCADA systems to improve grid efficiency, reliability, and integration of renewable energy sources.
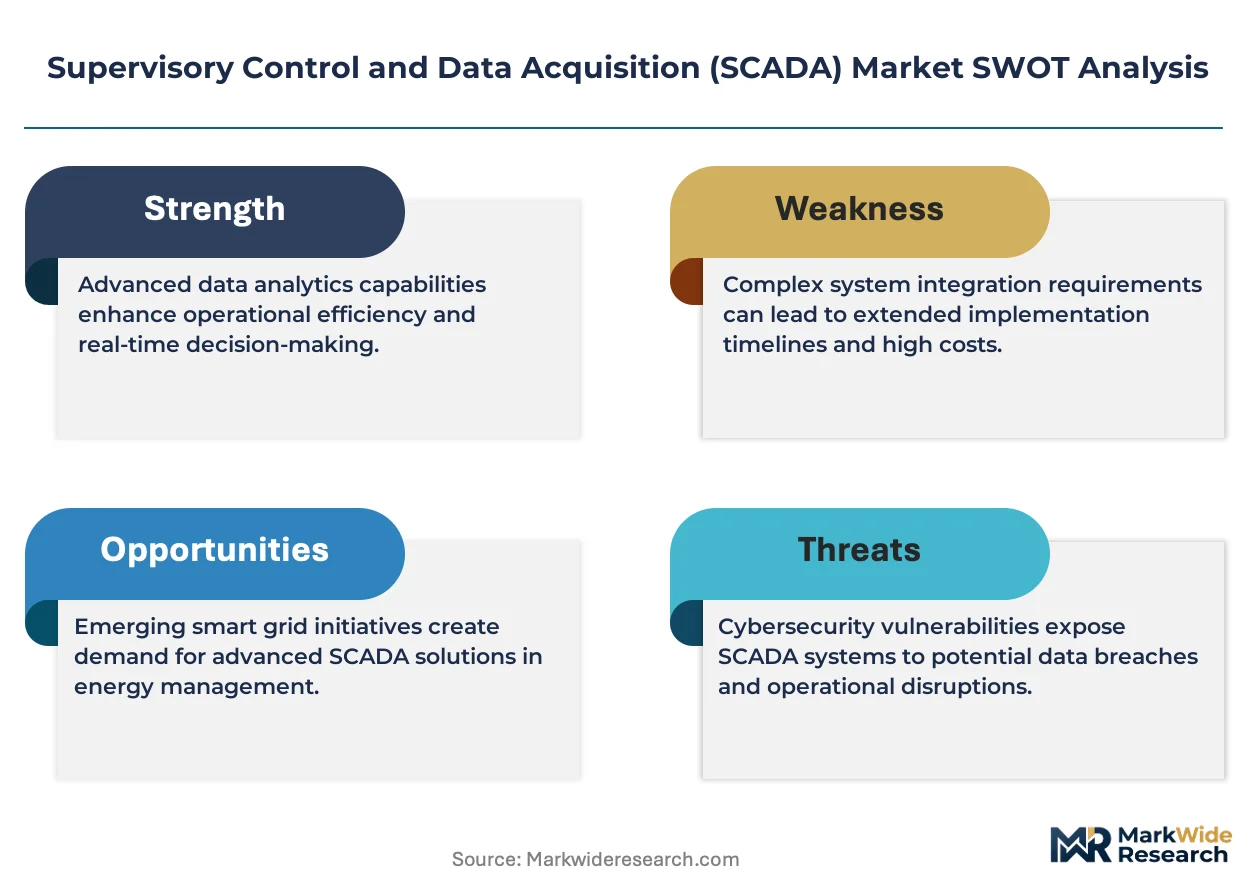
- Cybersecurity Regulations:Standards such as the NERC CIP in the United States and the NIS Directive in Europe compel utilities to upgrade or replace legacy SCADA systems. Compliance requires implementing platforms with modern security controls and threat detection capabilities.
- Cloud Architecture Adoption:The availability of cloud-native SCADA solutions reduces upfront capital expenditure for end-users. This model provides scalability and remote access, making advanced control systems more accessible to smaller operators in sectors like water management.
Market Restraints
- High Implementation Costs:The substantial initial investment required for on-premises SCADA hardware and software, particularly for high-reliability systems in the power generation sector, remains a significant barrier for many organizations.
- Legacy System Integration:Integrating modern SCADA platforms with aging operational technology, including proprietary RTUs and PLCs from various vendors, creates significant technical complexity and increases project timelines and costs.
- Data Sovereignty Rules:Regulations like the EU's GDPR and China's MLPS 2.0 impose strict controls on cross-border data flow. This complicates the architecture of cloud-based SCADA solutions for multinational operators, often requiring region-specific deployments.
Strategic Opportunities
- Renewable Energy Management:The global expansion of wind and solar power generation creates a substantial opportunity for SCADA systems designed to manage distributed energy resources and ensure grid stability.
- AI-Powered Predictive Maintenance:Integrating artificial intelligence and machine learning algorithms with SCADA data enables predictive maintenance in industrial processes. This is a high-value application in the oil and gas and water treatment sectors.
- Edge Computing Integration:Deploying SCADA logic on edge devices closer to the process reduces latency and improves real-time control. This creates opportunities for specialized hardware and software solutions tailored for edge environments.
Industry Challenges
- Cybersecurity Skills Gap:A persistent shortage of professionals with expertise in both operational technology and modern cybersecurity practices hinders the secure implementation and maintenance of SCADA systems, especially for smaller utilities.
- Interoperability Standards:A lack of universal communication standards between devices from different manufacturers complicates system integration. End-users face challenges in creating a unified control environment without being locked into a single vendor.
- Certification Delays:The lengthy and rigorous process of certifying SCADA components and systems against industry-specific standards like NERC CIP can significantly delay the deployment of new technologies in critical infrastructure projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supervisory Control and Data Acquisition (SCADA) Market |
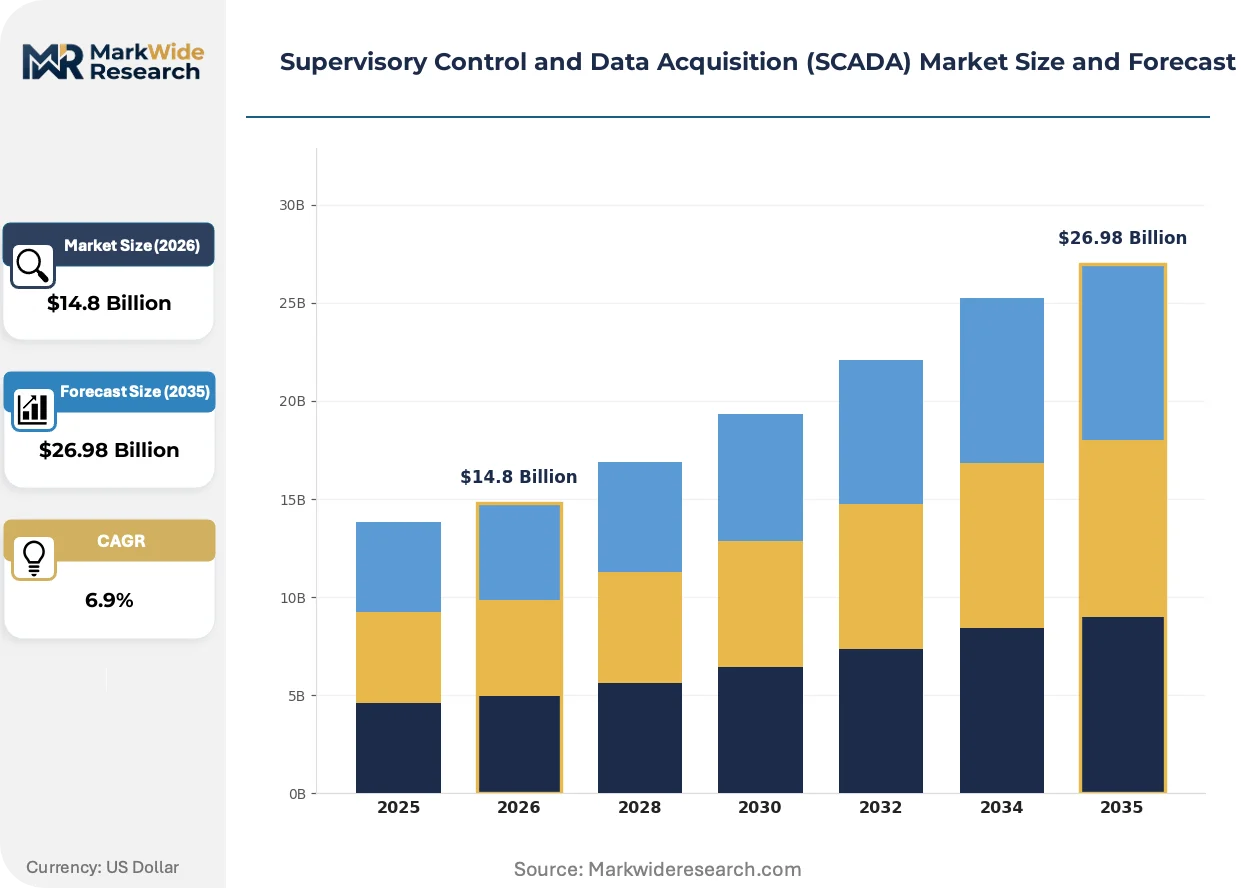
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Solution Type: Software Platforms, Hardware Components, Communication Protocols, Integration Services Application: Water Management, Power Generation, Oil Refining, Manufacturing Automation, Transportation Control End User: Electric Utilities, Wastewater Treatment Plants, Petroleum Refiners, Factory Operations, Railway Authorities |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., Siemens, General Electric, AVEVA, Schneider Electric, Rockwell Automation, Yokogawa, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supervisory Control and Data Acquisition (SCADA) Market Strategic Shifts & Innovations
The evolution from monolithic, on-premises SCADA systems toward distributed, cloud-enabled architectures defines the current innovation cycle. This transition prioritizes interoperability, data analytics, and enhanced security to manage increasingly complex industrial operations.
Edge computing enables data processing closer to remote terminal units and programmable logic controllers, reducing network latency. Industrial sectors like manufacturing and energy are adopting this for faster decision-making. The market's core architecture is migrating from centralized master stations to intelligent, distributed nodes at the operational periphery.
Mandates like the EU's NIS Directive and its successor, NIS2, impose strict cybersecurity and incident reporting requirements on critical infrastructure operators. This directly influences system design, compelling vendors to embed advanced security features from the ground up. The power generation and transmission sectors are most impacted, requiring verifiable compliance for all new deployments.
A transition toward subscription-based SCADA-as-a-Service models is challenging the dominance of perpetual software licenses. This approach lowers the entry barrier for small to mid-sized utilities by converting capital costs into operational expenses. The shift is most pronounced in the North American water management sector, where budget flexibility is a key purchasing factor.
Supervisory Control and Data Acquisition (SCADA) Market Segmentation
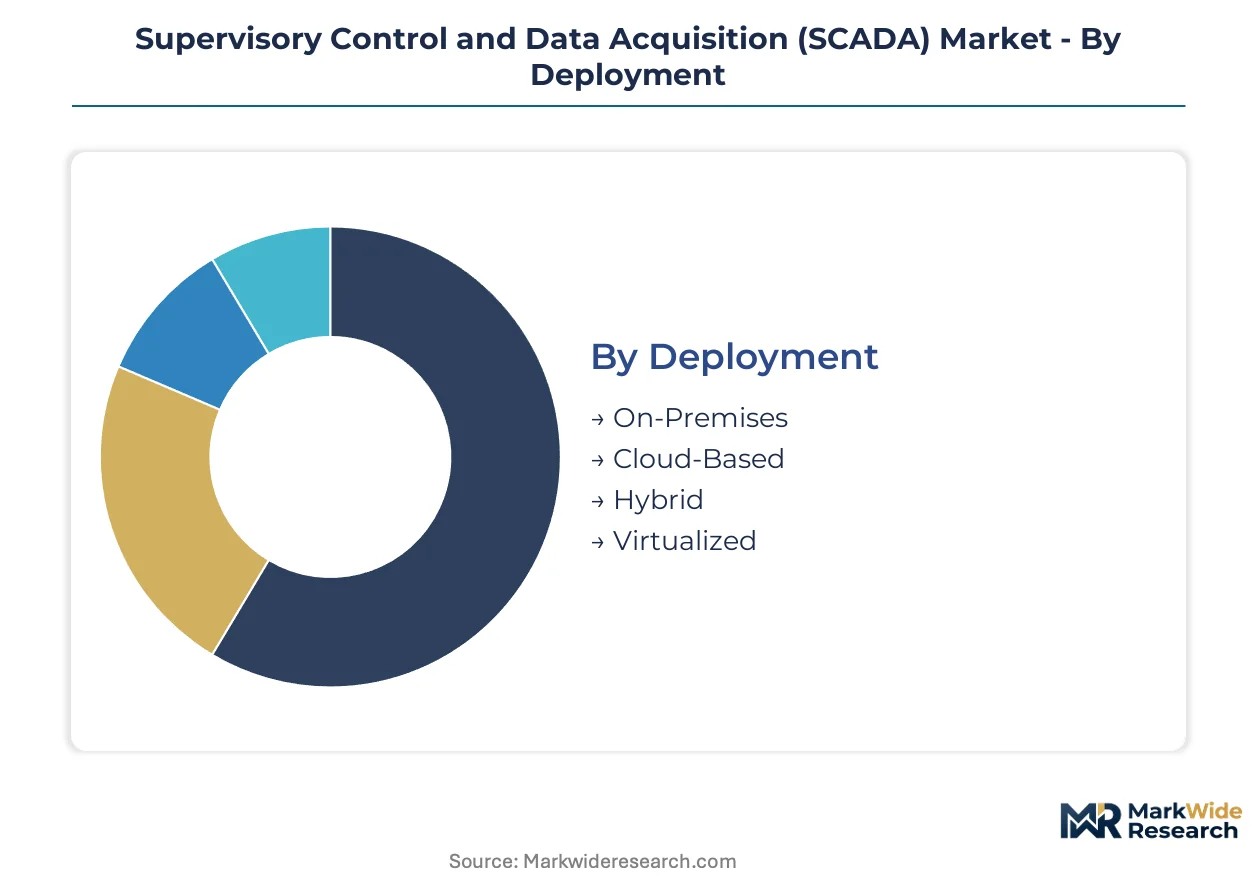
Understanding the SCADA market through detailed segmentation reveals the interplay of technological evolution and operational requirements. This analysis dissects the market into its core components, highlighting where investment flows and where innovation is most critical for industrial control systems.
Deployment:
The SCADA market's deployment models span a maturity spectrum, from established on-premises systems to rapidly emerging cloud-based architectures.
- On-Premises:These deployments involve SCADA hardware and software installed directly within the operator's physical infrastructure. On-premises systems remain dominant in sensitive critical infrastructure sectors due to stringent security and data sovereignty requirements, particularly in power generation.
- Cloud-Based:Cloud-based SCADA solutions host software and data on remote servers, offering scalability and reduced capital expenditure. This model gains traction among smaller operators and in sectors like water management, providing remote access and flexible resource allocation.
- Hybrid:Hybrid deployments combine local infrastructure with cloud-based services, balancing the security of on-premises control with the flexibility of the cloud. This approach supports phased modernization efforts for complex industrial environments.
- Virtualized:Virtualized SCADA systems run on virtual machines within an organization's data center, decoupling software from physical hardware. This deployment method enhances resource utilization and simplifies system management for large-scale enterprise operations.
On-Premises retains volume leadership; Cloud-Based holds the steepest expansion curve.
Solution Type:
The market's solution types reflect the diverse functional needs of industrial control, from core software to essential integration services.
- Software Platforms:These encompass the core SCADA human-machine interface, historical data archiving, and reporting functionalities for centralized process management. Demand for advanced software platforms is concentrating in sectors modernizing legacy systems, particularly in electric utilities.
- Integration Services:Integration services involve the design, implementation, and connection of SCADA systems with existing operational technology and enterprise IT infrastructure. The fragmentation of traditional integration models drives demand for specialized expertise in complex process industries.
- Hardware Components:This segment includes remote terminal units, programmable logic controllers, and master terminal units that collect and transmit data from field devices. High-reliability hardware components are critical for demanding applications in power generation.
- Communication Protocols:Communication protocols define the standards for data exchange between SCADA components and field devices, ensuring interoperability across diverse vendor ecosystems. Standardized protocols are vital for smart grid integration initiatives.
Demand for Software Platforms continues to evolve rapidly, while Integration Services are increasingly critical for complex deployments.
Application:
SCADA applications span various industrial sectors, with distinct requirements for reliability, data processing, and control capabilities.
- Water Management:SCADA systems in water management monitor and control water treatment plants, distribution networks, and wastewater facilities. This mature, high-value segment demands high-reliability hardware and robust data analytics for operational efficiency.
- Power Generation:This application involves SCADA for monitoring and controlling power plants, substations, and grid infrastructure. The sector is undergoing modernization driven by smart grid investments and stringent cybersecurity mandates like NERC CIP.
- Oil Refining:SCADA systems manage complex processes in oil and gas refineries, ensuring safety, optimizing production, and monitoring critical equipment. Predictive maintenance applications are gaining traction within this sector.
- Manufacturing Automation:In manufacturing, SCADA oversees production lines, robotic systems, and quality control processes to enhance efficiency and reduce downtime. Edge computing integration is increasingly important for faster decision-making.
- Transportation Control:SCADA supports railway signaling, traffic management, and airport operations, ensuring safety and optimizing logistical flows. Real-time data acquisition is paramount for critical infrastructure in transportation.
Power Generation remains a substantial application area, and Water Management demonstrates consistent demand for robust solutions.
End User:
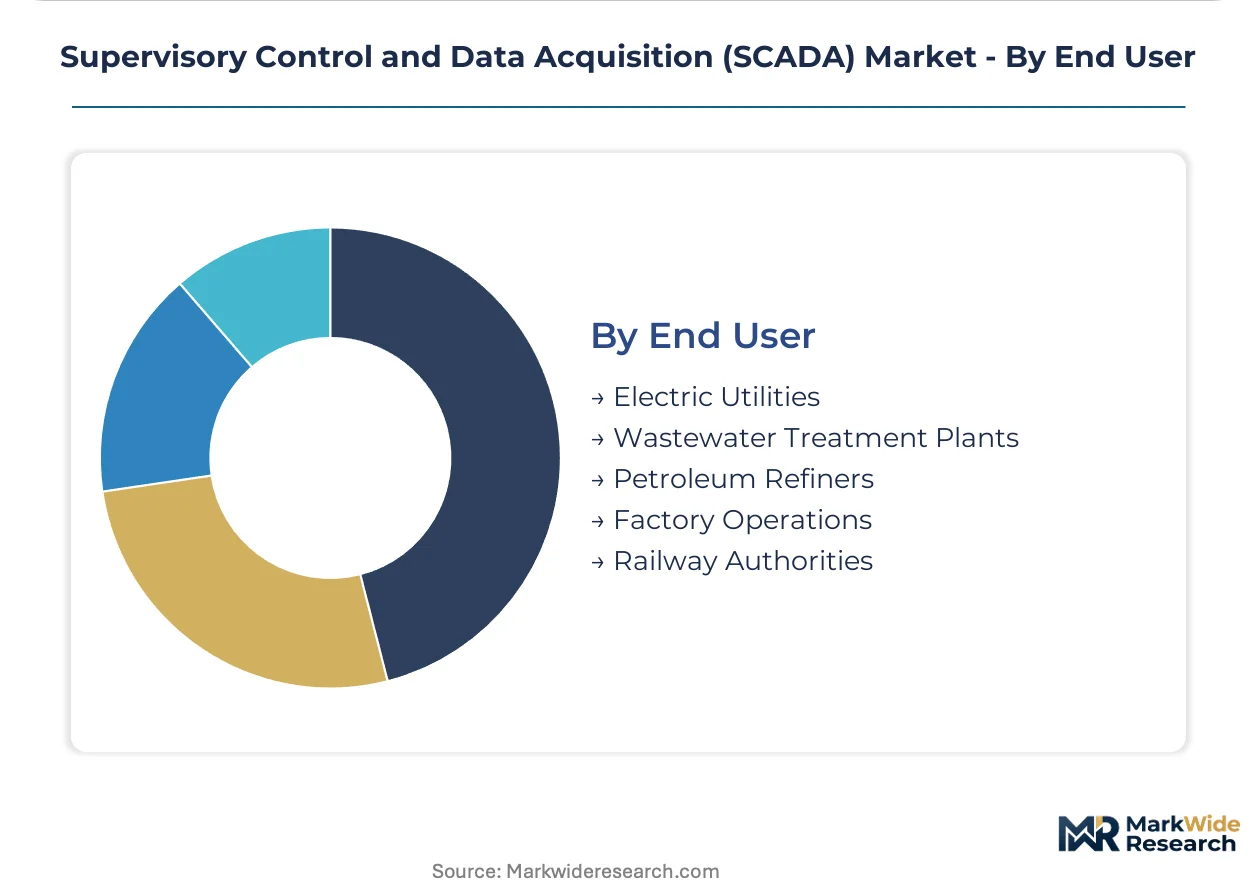
End-user segments highlight the specific organizational entities that deploy and operate SCADA systems, each with unique operational and regulatory landscapes.
- Electric Utilities:These entities manage the generation, transmission, and distribution of electricity, representing a primary driver for SCADA market growth. Modernization efforts and cybersecurity regulations like NERC CIP heavily influence their SCADA procurement.
- Wastewater Treatment Plants:These facilities utilize SCADA for monitoring and controlling water purification and wastewater processing, ensuring public health and environmental compliance. Budget flexibility in this sector promotes the adoption of cloud-based SCADA-as-a-Service models.
- Petroleum Refiners:Petroleum refining companies deploy SCADA to oversee complex chemical processes, pipeline operations, and safety systems. Their demand focuses on high-reliability process control and AI-powered predictive maintenance.
- Factory Operations:Manufacturing companies use SCADA to automate and supervise production lines, inventory management, and quality assurance. The push for Industry 4.0 initiatives drives investment in advanced SCADA functionalities.
- Railway Authorities:These organizations implement SCADA for railway signaling, track monitoring, and train control systems to enhance safety and operational efficiency. Integration with edge computing is vital for low-latency control in railway networks.
Electric Utilities are central to market activity, while Wastewater Treatment Plants show increasing interest in flexible deployment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SCADA technology and expertise from established industrial automation hubs frequently influence deployments in regions modernizing critical infrastructure.
United States
Grid modernization efforts and enhanced cybersecurity requirements drive SCADA demand across diverse industrial sectors in the United States. The Federal Energy Regulatory Commission (FERC) mandates NERC CIP standards for critical infrastructure operators, ensuring system resilience. Energy infrastructure in Texas heavily relies on advanced SCADA systems for reliable operational control and efficiency.
China
State-led smart grid investment and rapid industrial automation propel SCADA market expansion across China, particularly in energy and manufacturing. The Multi-Level Protection Scheme (MLPS 2.0) shapes stringent cybersecurity specifications for all critical infrastructure deployments. Manufacturing hubs in the Yangtze River Delta actively integrate advanced SCADA for production line control and data acquisition.
Germany
Industry 4.0 initiatives and substantial renewable energy integration efforts stimulate SCADA demand in Germany's advanced manufacturing and utility sectors. The EU's NIS Directive mandates stringent cybersecurity measures for critical infrastructure operators, influencing system design. Industrial technology clusters in Bavaria leverage SCADA for advanced manufacturing processes and efficient energy management.
India
Extensive infrastructure development and ongoing smart city projects fuel SCADA system deployment across India, especially in water and power utilities. The Central Electricity Authority (CEA) issues guidelines for grid modernization and operational technology security. Industrial zones in Maharashtra adopt SCADA for efficient water management, power distribution networks, and process control.
Japan
Modernization of aging infrastructure and advanced manufacturing initiatives drive SCADA adoption in Japan, focusing on reliability and precision. The Ministry of Economy, Trade and Industry (METI) promotes cybersecurity best practices for industrial control systems, ensuring system integrity. Manufacturing facilities in the Kanto region utilize SCADA for precise process control, automation, and data analytics.
Supervisory Control and Data Acquisition (SCADA) Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for SCADA solutions. The SCADA market exhibits fragmentation in specialized segments, contrasting with consolidation among broader industrial automation vendors. Large, established companies offer integrated solutions spanning hardware, software, and services across diverse industries. Niche providers often focus on specific application areas or advanced functionalities like cybersecurity and AI integration. Strategic partnerships and targeted acquisitions are common competitive moves to expand solution portfolios and geographic reach within this evolving landscape.
Within the integrated solutions archetype, Siemens, a German industrial automation giant, and Schneider Electric, a French energy management specialist, represent prominent players. These companies leverage extensive industrial portfolios to deliver comprehensive SCADA platforms for complex process industries and utility-scale deployments. Emerson Electric Co., a US-based technology and engineering company, exemplifies a focus on process control systems, particularly for the oil and gas sector, anchoring its position through specialized hardware and software offerings.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| Siemens |
| General Electric |
| AVEVA |
| Schneider Electric |
| Rockwell Automation |
| Yokogawa |
| ABB |
| Others |
Cost & Logistics Intelligence
Legacy system integration complexity acts as a significant regulatory chokepoint, determining both pricing tier spreads for SCADA solutions and the overall shape of the supply chain for specialized components and services.
Pricing Analysis
The widening technology-generation gap between legacy on-premises SCADA and cloud-native solutions drives distinct pricing models. Project-based pricing dominates large-scale critical infrastructure deployments, reflecting extensive customization and integration services. Price differentiation stems from NERC CIP compliance certification levels and the depth of after-sales support offered by vendors. Pricing softness reflects increased competition from cloud-native alternatives for smaller operators. Wastewater treatment plants demonstrate the highest price sensitivity, while power generation utilities prioritize reliability over cost.
Supply Chain Analysis
Upstream supply for SCADA systems relies heavily on specialized electronic components and industrial-grade hardware. Key manufacturing hubs in China, Germany, and the United States provide critical microprocessors, sensors, and secure communication modules. Geopolitical tensions affecting semiconductor supply represent a structural risk for hardware component availability. Distribution runs through a mix of direct sales for large enterprises and an extensive network of system integrators for complex, multi-vendor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as incumbents must navigate the threat posed by increasingly capable cloud-native industrial IoT platforms.
For Market Incumbents:Build integrated operational technology ecosystems that combine SCADA functionality with advanced analytics and robust cybersecurity. Deepen core cybersecurity features within existing platforms to meet evolving regulatory mandates like NERC CIP. Acquire niche specialists in AI integration or edge computing to rapidly expand solution capabilities. Invest heavily in R&D for predictive maintenance algorithms to create higher-value offerings for process industries, defending against general-purpose IT incursions.
For New Entrants and Emerging Players:Under-served small to mid-sized utilities in rapidly industrializing economies represent the most penetrable entry point. Target the water management sector in North America with flexible, cloud-based SCADA-as-a-Service models. Focus on developing interoperable solutions that simplify integration with diverse legacy hardware. A go-to-market strategy emphasizing lower total cost of ownership and rapid deployment can attract budget-conscious operators.
For Investors and Strategic Acquirers:The market sits at a modernization and consolidation phase that favors niche cybersecurity and AI integration specialists. Long-term viability remains strong, driven by persistent critical infrastructure upgrade cycles and escalating threat landscapes. Acquisition targets should possess strong intellectual property in secure communication protocols or advanced data analytics for industrial applications. Increased M&A activity in operational technology security solutions is the signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Development | Modernizes SCADA architecture, reducing capital expenditure for end-users and enhancing scalability. |
| Edge Computing Integration | Reduces latency for real-time control applications in manufacturing and energy sectors. |
| Cybersecurity Certification Investment | Ensures compliance with stringent regulations like NERC CIP, critical for electric utilities. |
| AI-Powered Analytics Partnership | Enables predictive maintenance and operational optimization for high-value industrial processes. |
| Regional Compliance Specialization | Addresses data sovereignty and specific regulatory requirements across diverse geographic markets. |
Research Approach
Operator-level perspectives from electric utility managers, water treatment plant engineers, industrial automation specialists, and cybersecurity officers anchored the qualitative base. This primary fieldwork was validated against extensive secondary research, including NERC CIP compliance reports, EU NIS Directive implementation documents, national smart grid investment plans, and vendor whitepapers, employing both bottom-up and top-down triangulation.
Scenario-bracketing across conservative, base, and aggressive growth trajectories informed the quantitative forecasting framework across the analysis window. Segmentation dimensions modeled included deployment, solution type, application, end-user, and regional cybersecurity compliance regimes. Compound annual growth rates were derived through a comprehensive analysis of historical trends and projected market drivers, incorporating smart grid investment levels and regulatory enforcement timelines as key inputs.
Practitioners should monitor geopolitical shifts, new cybersecurity mandates, or technological breakthroughs in industrial IoT for early signals of forecast revision. Forecasts reflect assumptions regarding market evolution and regulatory stability. Cross-checking against external market intelligence reports or government infrastructure spending forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Factory Automation Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Connected Worker Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Global Operational Technology Market