
 Industrial Artificial Intelligence [AI] Market | 2026-2036
Industrial Artificial Intelligence [AI] Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Artificial Intelligence [AI] Market Foresight
Multi-source procurement of AI training infrastructure is recalibrating how industrial firms balance cloud dependency against on-premise control. NVIDIA dominates GPU supply for model training, while Siemens anchors European factory-floor deployments with its edge-AI portfolio. IBM competes through hybrid cloud architectures that bridge IT and operational technology environments.
Industrial Artificial Intelligence [AI] encompasses machine learning algorithms, computer vision systems, and predictive analytics engines that process sensor data from manufacturing equipment, typically operating at latency thresholds below 50 milliseconds for real-time process control. Its primary purpose is to optimize throughput, prevent unplanned downtime, and automate quality inspection in heavy industry. Machine learning applications currently capture the largest revenue share due to their deployment across predictive maintenance and process optimization use cases. Edge computing is expanding fastest as manufacturers seek to reduce data transmission costs and latency for time-critical decisions.
The EU AI Act imposes risk-classification requirements on industrial AI systems, pushing OEMs toward documented conformity assessments before deployment. In the United States, NIST AI Risk Management Framework shapes procurement standards for federal manufacturing contractors, while OSHA guidelines influence how autonomous systems integrate with human workforce safety protocols. Stakeholders must monitor divergence between European conformity mandates and American sectoral guidance when architecting cross-border deployment strategies.
Market Dynamics
The convergence of edge computing architectures with EU AI Act compliance mandates is restructuring how industrial firms allocate capital between cloud infrastructure and on-premise inference hardware.
Growth Catalysts
- Predictive maintenance deployment:Automotive OEMs in Germany are embedding sensor-fusion algorithms into stamping presses and welding robots to eliminate unplanned downtime.
- EU AI Act risk classification:The regulation's documented conformity assessment requirements for high-risk systems are accelerating procurement of certified edge-AI hardware.
- Computer vision quality inspection:Machinery builders across Bavaria and Baden-Württemberg are retrofitting production lines with sub-50-millisecond latency vision systems.
Market Restraints
- GPU supply concentration:Training infrastructure procurement depends heavily on NVIDIA's foundry allocation, creating vulnerability to semiconductor fabrication bottlenecks.
- Edge hardware capex requirements:On-premise inference accelerators from Siemens and specialist vendors demand upfront investment that compresses near-term margins.
- Cross-border regulatory divergence:NIST AI Risk Management Framework requirements for US federal contractors create friction with EU conformity pathways.
Strategic Opportunities
- Process optimization in chemicals:German chemical producers remain underpenetrated for real-time reaction control using reinforcement learning.
- 5G-private network convergence:Time-sensitive networking over localized 5G infrastructure enables new ultra-low-latency control applications.
- CSRD disclosure mandates:The EU Corporate Sustainability Reporting Directive creates demand for AI-driven energy consumption monitoring in heavy industry.
Industry Challenges
- OT-IT integration complexity:Manufacturing engineers lack expertise in Kubernetes orchestration and MLOps pipelines required for hybrid deployments.
- Conformity assessment timelines:EU AI Act notified body capacity constraints delay high-risk system deployment authorizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Artificial Intelligence [AI] Market |
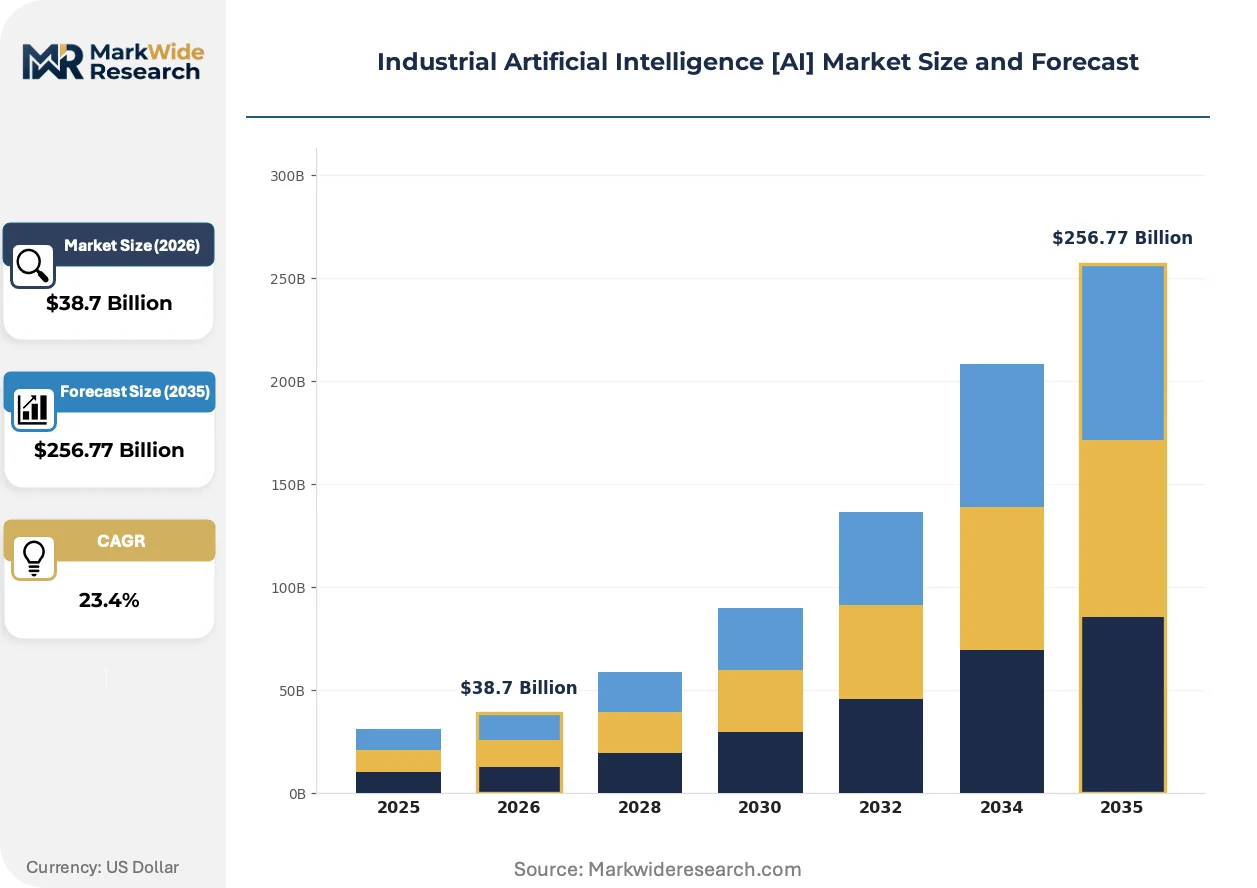
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $256.77 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machine Learning, Computer Vision, Natural Language Processing, Predictive Analytics Application: Manufacturing, Quality Control, Supply Chain Optimization, Asset Management End User: OEMs, Energy Sector, Manufacturing Plants, Logistics Technology: Cloud-Based Solutions, Edge Computing, Big Data Analytics, IoT Integration |
| Companies Covered | IBM, Siemens, Microsoft, Intel, NVIDIA, ABB, General Electric, Rockwell Automation, Alphabet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Artificial Intelligence [AI] Market Shifts & Advancements
Industrial AI deployment is fragmenting from centralized cloud training toward distributed edge inference, with regulatory pressure and latency requirements jointly determining architecture choices.
Containerized machine learning inference engines is modularizing across German automotive plants, allowing quality inspection models to deploy as swappable microservices on factory-floor edge nodes. Tier-1 suppliers are adopting this pattern fastest, compressing model update cycles from quarterly to weekly without production line reconfiguration.
The EU AI Act's risk-classification framework is forcing OEMs to restructure development workflows around documented conformity assessments before deployment. High-risk categorization for autonomous material handling systems now requires human oversight protocols and bias testing, with machinery builders in Stuttgart and Munich restructuring R&D teams to embed compliance engineers.
Buyers are unbundling predictive maintenance software from capital equipment procurement, shifting toward subscription-based algorithm licenses that transfer model performance risk to vendors. German automotive OEMs pioneered this structure, and it is now spreading to packaging machinery and metal fabrication equipment procurement across Central European manufacturing clusters.
Industrial Artificial Intelligence [AI] Market Segmentation
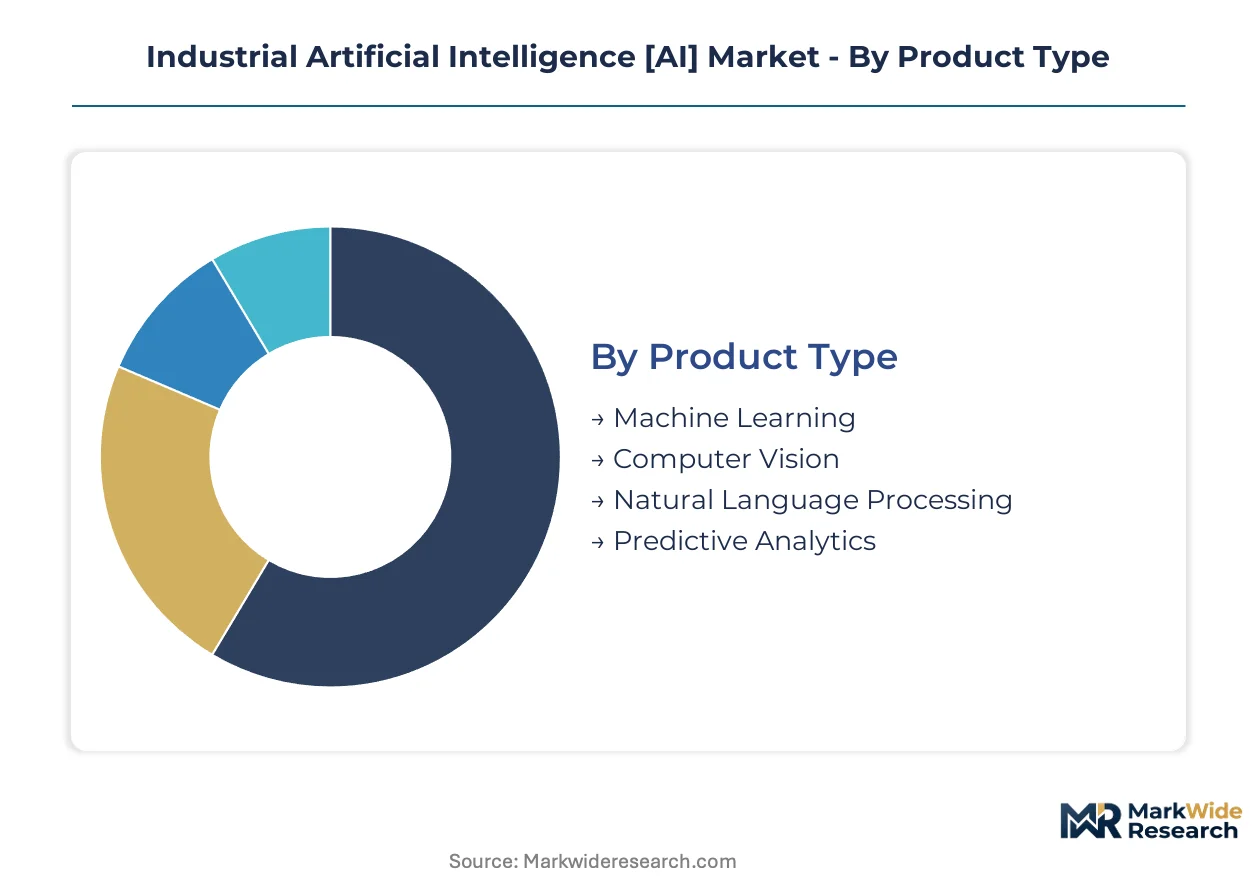
Industrial AI segmentation reveals how regulatory burden, latency requirements, and capex thresholds reshape procurement patterns across product types and deployment architectures. Buyers prioritize segments offering documented conformity pathways under the EU AI Act while balancing edge versus cloud trade-offs.
Product Type:
Certification requirements vary sharply across product types, with computer vision systems facing the strictest conformity assessments under EU AI Act high-risk classifications while predictive analytics engines navigate lighter documentation burdens.
- Machine Learning:Algorithms process sensor-fusion data from stamping presses and welding robots to forecast equipment failures. German automotive OEMs in Stuttgart and Munich embed these systems into predictive maintenance contracts, transferring model performance risk to vendors through subscription licensing.
- Computer Vision:Sub-50-millisecond latency inspection systems detect surface defects on production lines. Bavarian machinery builders retrofit these into existing workflows, driven by EU AI Act mandates for documented bias testing and human oversight protocols in autonomous quality control.
- Natural Language Processing:Interfaces parse maintenance logs and operator instructions for knowledge extraction. Demand concentrates in technical documentation automation for complex equipment.
- Predictive Analytics:Statistical engines forecast demand patterns and inventory requirements. Chemical producers deploy these for supply chain optimization with lighter regulatory overhead.
Machine Learning sits at the top of the volume ranking, with Computer Vision climbing the fastest.
Application:
Cost tier differentiation separates high-capex autonomous systems from software-only deployments that minimize upfront factory-floor hardware investment.
- Manufacturing:Real-time process control systems adjust reaction parameters in chemical plants and machining centers. Edge computing architectures dominate here due to latency thresholds below 50 milliseconds for safety-critical adjustments.
- Quality Control:Automated inspection replaces manual sampling with continuous monitoring. Baden-Württemberg automotive suppliers lead adoption, compressing model update cycles through containerized microservices deployment.
- Supply Chain Optimization:Demand forecasting and logistics routing algorithms reduce inventory carrying costs. Cloud-based deployment prevails given tolerance for higher latency.
- Asset Management:Lifecycle tracking and predictive replacement scheduling extend equipment utilization. Energy sector buyers prioritize this segment for grid infrastructure.
Manufacturing commands the largest deployment base, while Quality Control gains share fastest.
End User:
Customer type determines procurement sophistication, with OEMs demanding outcome-based pricing and energy sector buyers prioritizing cybersecurity certification.
- OEMs:Automotive and machinery builders embed AI into capital equipment offerings. These buyers pioneered subscription-based algorithm licenses that transfer model performance risk to software vendors.
- Energy Sector:Grid operators and renewable asset managers deploy predictive maintenance for turbines and transformers. NERC CIP cybersecurity standards shape vendor selection alongside EU AI Act conformity.
- Manufacturing Plants:Discrete and process manufacturers implement sensor-fusion systems for unplanned downtime elimination. Edge hardware capex requirements compress near-term margins.
- Logistics:Warehouse operators and freight networks optimize routing and inventory positioning. Cloud-based solutions dominate given distributed facility footprints.
Manufacturing Plants anchor current volume, with OEMs expanding fastest through embedded AI offerings.
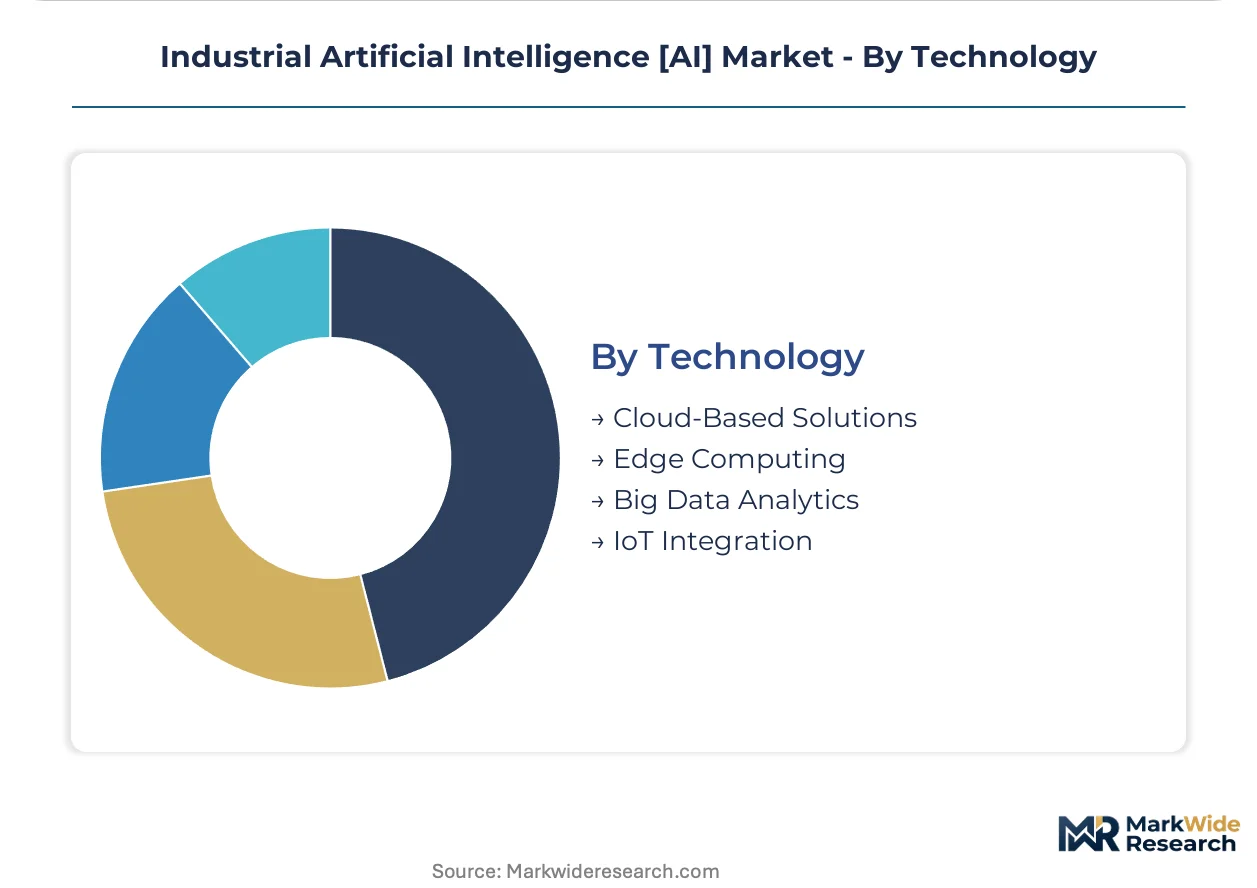
Technology:
Supply concentration in GPU foundry allocation creates vulnerability for cloud-dependent segments while edge computing demands upfront investment in Siemens and specialist vendor hardware.
- Cloud-Based Solutions:Centralized training and inference leverage hyperscaler infrastructure. NIST AI Risk Management Framework shapes procurement for US federal contractors, creating friction with EU conformity pathways.
- Edge Computing:On-premise inference accelerators process data locally for sub-50-millisecond latency. German machinery builders in Stuttgart and Munich favor this architecture to satisfy EU AI Act high-risk system requirements.
- Big Data Analytics:Historical pattern recognition across enterprise data lakes supports strategic decision-making. Chemical producers underpenetrate this segment for real-time reaction control.
- IoT Integration:Sensor networks feed continuous data streams into AI pipelines. 5G-private network convergence enables new ultra-low-latency control applications in heavy industry.
Cloud-Based Solutions hold the volume lead, with Edge Computing expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and machinery clusters in Stuttgart, Munich, and Wolfsburg concentrate the heaviest industrial AI deployment density in Europe, with predictive maintenance and computer vision systems penetrating production lines faster than regulatory frameworks can standardize.
United States
Automotive OEMs in Detroit and aerospace manufacturers in Seattle embed sensor-fusion algorithms into capital equipment for unplanned downtime elimination. NIST AI Risk Management Framework shapes procurement standards for federal manufacturing contractors. The Department of Defense accelerates adoption through defense industrial base cybersecurity mandates.
China
MIIT's intelligent manufacturing initiatives drive edge-AI deployment across Yangtze River Delta electronics clusters and Pearl River Delta automotive plants. GB standards for industrial internet platforms create conformity pathways for computer vision quality inspection systems. Shenzhen-based machinery builders compress model update cycles through containerized microservices.
Japan
METI's Society 5.0 roadmap prioritizes predictive maintenance for aging infrastructure in Kansai manufacturing corridors. JIS standards for industrial IoT interoperability reduce integration friction for hybrid cloud deployments. Nagoya-area automotive suppliers pioneer subscription-based algorithm licensing for stamping press optimization.
South Korea
Seoul Capital Area semiconductor fabricators deploy sub-50-millisecond latency vision systems for wafer defect detection. MFDS medical device regulations create spillover compliance expertise for industrial AI risk classification. Busan-Ulsan shipbuilders integrate reinforcement learning for real-time welding parameter control.
India
PLI scheme incentives attract automotive OEMs to Tamil Nadu and Gujarat manufacturing corridors, accelerating predictive maintenance adoption. BIS standards for industrial automation create domestic conformity pathways. Pune and Chennai industrial clusters show fastest uptake of cloud-based supply chain optimization algorithms.
Industrial Artificial Intelligence [AI] Market Competitive Landscape
Global majors compete with regional champions across cloud-to-edge deployment architectures, creating a tiered structure where hyperscalers anchor training infrastructure while industrial automation specialists capture factory-floor inference. The vendor base separates into three archetypes: GPU-centric training hardware suppliers, hybrid cloud orchestration platforms, and edge-AI hardware integrators. Dominant competitive moves include strategic partnerships bridging IT-OT environments and portfolio diversification into subscription-based algorithm licensing.
Within the industrial automation tier, Siemens anchors European factory-floor deployments with edge-AI hardware portfolios, while NVIDIA exemplifies training infrastructure concentration through GPU supply dominance. IBM occupies a position bridging both domains through hybrid cloud architectures. These three represent distinct strategic postures: captive hardware integration, upstream semiconductor control, and middleware orchestration.
| Leading Market Players |
|---|
| IBM |
| Siemens |
| Microsoft |
| Intel |
| NVIDIA |
| ABB |
| General Electric |
| Rockwell Automation |
| Alphabet Inc. |
| Others |
Supply & Pricing Matrix
EU AI Act conformity assessment mandates are forcing procurement teams toward certified edge-AI hardware, compressing margins for suppliers unable to document bias testing and human oversight protocols while rewarding vendors with pre-certified inference accelerators.
Pricing Analysis
GPU foundry allocation costs from NVIDIA pass through directly to training infrastructure pricing, with automotive OEMs in Stuttgart absorbing premium tier increases for certified edge nodes. Price differentiation separates EU AI Act-compliant systems with documented conformity pathways from uncertified alternatives. Cost compression in cloud-based inference is intensifying because hyperscalers are consolidating procurement volume. Manufacturing plants show highest price sensitivity due to upfront capex requirements, while energy sector buyers prioritize cybersecurity certification over unit cost.
Supply Chain Analysis
AI training hardware supply rests on Taiwanese semiconductor fabrication, South Korean memory production, and American GPU design. Edge inference accelerators draw from German industrial automation specialists and Chinese component suppliers. Single-source vulnerability concentrates in NVIDIA's foundry allocation for training chips. Distribution runs through direct OEM relationships for factory-floor deployments and hyperscaler marketplaces for cloud-based solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial AI has shifted to a late-cycle quality story as buyers demand EU AI Act-certified systems with documented conformity assessments rather than lowest-cost alternatives.
For Market Incumbents: Lock in captive supply of certified edge-AI hardware through exclusive partnerships with Siemens and specialist vendors. Deepen backward integration into sensor-fusion algorithm development to transfer model performance risk away from manufacturing plant buyers. Defend against subscription-based licensing entrants by embedding AI into capital equipment with outcome-based pricing guarantees. For New Entrants and Emerging Players: Launch via containerized microservices deployment models that compress model update cycles for Tier-1 automotive suppliers. Target underpenetrated German chemical producers for real-time reaction control using reinforcement learning. White-space exists in 5G-private network convergence for ultra-low-latency applications where incumbent edge hardware lacks integration expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with edge-AI hardware integrators possessing EU AI Act notified body relationships and pre-certified product portfolios. Five-to-ten year viability favors vendors bridging IT-OT integration complexity for manufacturing engineers lacking Kubernetes expertise. Watch notified body capacity expansion as the inflection signal for high-risk system deployment authorization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Documented assessment capabilities unlock high-risk system deployments for autonomous material handling. |
| Edge-AI Hardware Certification | Pre-certified inference accelerators command pricing premiums from German automotive OEM procurement teams. |
| Subscription Algorithm Licensing | Outcome-based pricing transfers model performance risk from manufacturing plants to software vendors. |
| 5G-Private Network Integration | Time-sensitive networking enables sub-50-millisecond control applications in heavy industry. |
| OT-IT Integration Partnerships | Kubernetes orchestration expertise bridges manufacturing engineering gaps in hybrid deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and edge-AI hardware specialists with secondary validation through SEC filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and industrial automation trade data. Bottom-up deployment estimates triangulated against top-down market sizing.
Historical reference periods anchored the projection horizon to observed adoption curves in German automotive clusters and Bavarian machinery corridors. Segmentation dimensions modeled include product type, deployment architecture, end-user sophistication, and regional regulatory framework. CAGRs derived from fitted growth curves adjusted for conformity assessment timeline constraints. Forecast inputs incorporated GPU supply allocation schedules and notified body capacity expansion plans.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement intensity shifts and semiconductor fabrication bottleneck persistence. Forecasts reflect assumptions on edge hardware cost trajectories and cross-border regulatory alignment. A small set of triggers warrants ongoing watch: notified body authorization backlogs, NVIDIA foundry allocation shocks, and NIST-EU conformity pathway divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Global Conversational Computing Platform Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market